Author:Chao Xu
The latest analysis from research firm SemiAnalysis reveals that Anthropic is reshaping the AI commercialization landscape with profitability and growth rates far exceeding its competitors. With its high-margin, API-centric business model, Anthropic has become the leader in the B2B AI market.
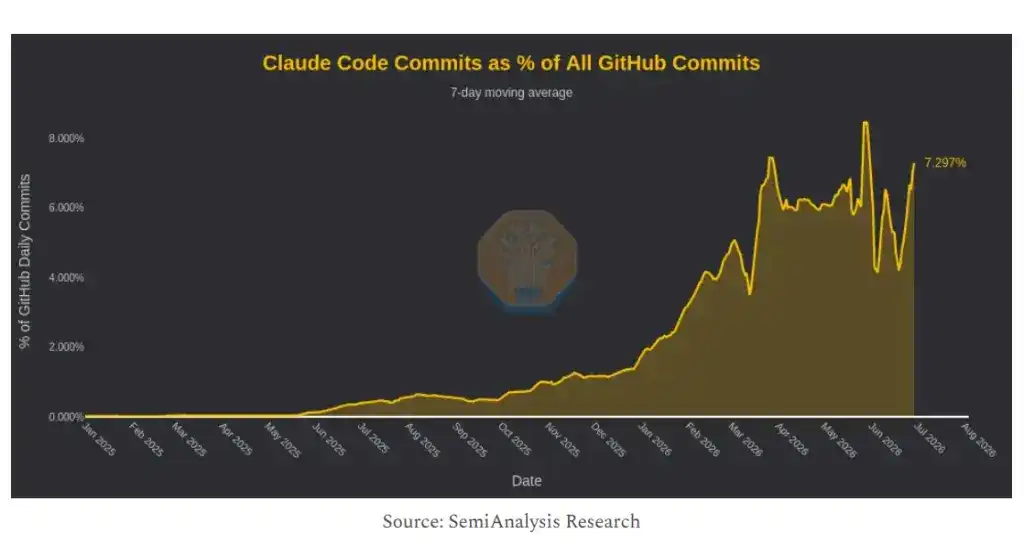
According to a deep-dive report released by SemiAnalysis, Anthropic is projected to achieve $1 billion in GAAP EBIT (Earnings Before Interest and Taxes) in the third quarter of 2026, corresponding to an approximately 6% profit margin. Meanwhile, its Annual Recurring Revenue (ARR) has skyrocketed from $9 billion at the end of 2025 to over $60 billion currently. The agency forecasts that if Anthropic maintains a pace of about $15 billion in net new ARR (NNARR) per month, its ARR by the end of 2027 could reach $300 billion, corresponding to a $6 trillion enterprise value, making it the world's highest-valued company.
Anthropic confidentially filed for an IPO on June 1st. SemiAnalysis believes that going public at this time carries strategic urgency — Alphabet has already completed an $84.75 billion equity financing round, and Meta is rumored to have a multi-hundred-billion-dollar financing plan; the capital market window is narrowing. The report points out that Anthropic's superior financial performance and business model suggest it should go public before OpenAI to seize the initiative in capital competition.
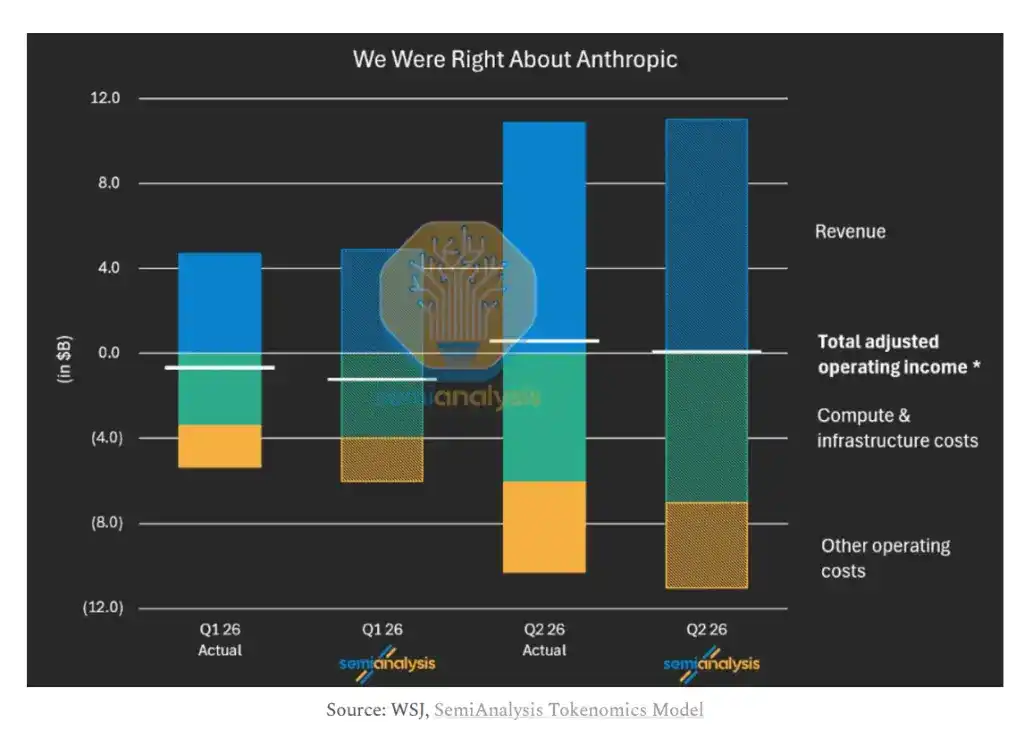
Anthropic's inflection point in performance stems from the explosive adoption of Claude Code. SemiAnalysis data shows that Claude Code currently accounts for over 7% of all code commits on GitHub, directly driving the company's monthly net new ARR to surge from $3 billion in January to $11 billion in March during the first quarter.
In terms of revenue structure, Anthropic and OpenAI show significant divergence. Approximately 75% to 85% of Anthropic's ARR comes from usage-based billing via its API business, with consumer subscriptions accounting for only about 5% of total ARR. In contrast, over 65% of OpenAI's revenue in Q1 2026 still came from subscription models, with consumer ARR representing about 40%.
SemiAnalysis notes that the core advantage of the API model is the lack of a per-user revenue cap — as the same customer adopts more agentic workflows, their token consumption and corresponding revenue will continue to grow, enabling expansion without acquiring new customers. Krishna Rao, Anthropic's Chief Financial Officer, disclosed in a podcast this May that the company's Net Revenue Retention Rate (NRR) is as high as 500%, meaning that among customers who contributed $30 billion ARR in Q1, these same customers contributed only $2 billion a year ago.
Differences in business models are directly reflected in gross margins. SemiAnalysis estimates that Anthropic's current consolidated gross margin has risen to the mid-60% range, whereas this figure was negative 94% in 2024. Within this, the API business gross margin exceeds 80%.
The core driver of the significant improvement in gross margin is enhanced inference efficiency. Measured by ARR per megawatt of compute power, Anthropic's metric will reach $60 million later this year, compared to just $16 million nine months ago. Since inference compute costs are largely fixed, marginal profit approaches 100% when the volume of tokens processed per unit of compute or the token pricing increases.
The report calculates that if both Anthropic and OpenAI reach $100 billion ARR, OpenAI's gross profit would be approximately $25 billion less than Anthropic's due to the need to support over 900 million free users (SemiAnalysis estimates monthly service costs at about $0.70 per person). This gap will directly impact both companies' ability to reinvest in training next-generation models.
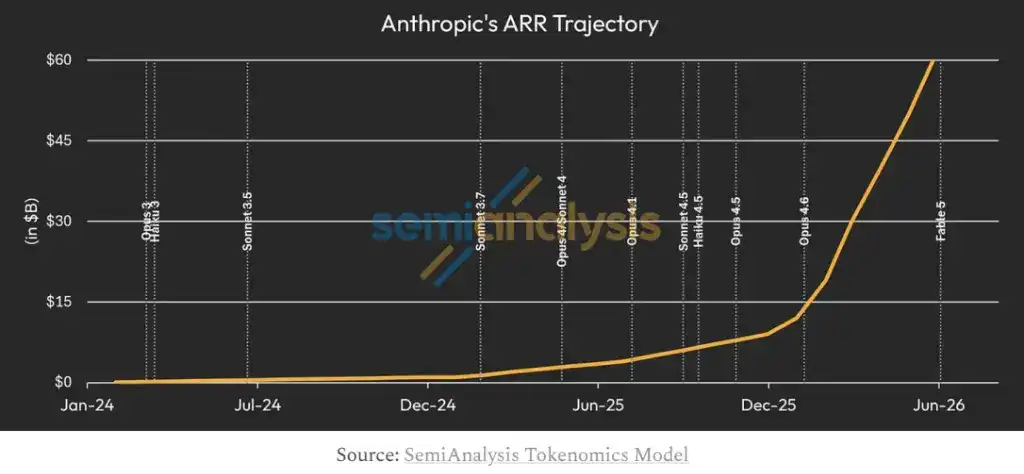
SemiAnalysis introduces "Earnings Before Training, Interest, and Taxes" (EBTIT) as a core metric to measure a lab's reinvestment capacity. Anthropic's EBTIT margin reached 36% in Q2 2026. The report predicts that Anthropic's cumulative EBTIT before 2028 will be $250 billion higher than OpenAI's.
SemiAnalysis estimates that currently over 65% of the lab's ARR comes from programming-related use cases. Programming tool startups like Cursor, Cognition, Loveable, and Replit collectively contribute approximately $6 billion in ARR. Meta is Anthropic's largest single customer, but its share remains between 3% and 5%.
The report believes that cybersecurity will be the next explosive vertical after programming, and it expects the release of the Fable new model will further elevate token pricing and expand application scenarios, driving monthly NNARR in the second half of 2026 to surpass the current level of $10 billion per month. Vertical fields such as healthcare, finance, and biotech are also listed as potential major areas for Total Addressable Market (TAM) expansion.
Regarding distribution channels, the "Tokens as a Service" (TaaS) model sold indirectly through hyperscale cloud platforms like AWS Bedrock and Azure Foundry is experiencing rapid growth. It currently accounts for 15% to 20% of Anthropic's ARR, up from just 5% to 10% a quarter ago. SemiAnalysis argues that paying 20% to 30% revenue share to hyperscale cloud platforms remains economically justifiable from the perspective of enterprise customer reach efficiency and compliance convenience.
The core constraint facing Anthropic's growth prospects stems from compute supply.
SemiAnalysis predicts that by 2030, the combined unconstrained compute demand of Anthropic and OpenAI will exceed 100 gigawatts (GW). However, the net new compute added in 2025 and 2026 was only 2.5GW and 5GW respectively, and the combined currently available compute for both companies is just over 6GW.
It is precisely this supply-demand gap that gives the IPO clear strategic significance. The report states that funds raised from the public offering will primarily be used to bridge the widening gap between inference operations and the compute demands of new model training, allowing for securing compute resources in advance at more favorable financing costs. The report also mentions that Meta is considering leasing compute to external parties (based on market rumors dated July 1, 2026) and expects Anthropic to purchase incremental compute from such trusted suppliers.
SemiAnalysis also lists key risk factors, including: rumored price reduction plans from OpenAI; competitive pressure from Google DeepMind and Meta in programming models; potential regulatory restrictions by governments on frontier model releases; and the dilutive effect on consolidated gross margin from the rising proportion of TaaS revenue. The report clearly states that if regulatory regimes hinder model releases and narrow the capability gap between open-source models and frontier proprietary models, it will fundamentally undermine Anthropic's commercial moat.