Author: Wall Street News
The most active during the Asian session are not tech stocks, but US market ETFs.
On December 6, 2026, Nasdaq plans to launch 23-hour, five-day-a-week stock trading. The SEC has approved Nasdaq's rule changes for 23/5 trading, but official launch still depends on the readiness of SIP and other market data infrastructure and the implementation of supporting rules.
The new night session starts at 9:00 PM ET and ends at 4:00 AM ET the next day. During December, which is on winter time, this corresponds to 10:00 AM to 5:00 PM Beijing Time. Asian investors can trade US stocks directly during their daytime.
On the surface, this reform seems to be just an extension of trading hours. Behind it lies a battle for order flow. Nasdaq aims to reclaim executions from night trading platforms, brokers' internal crossing systems, and other exchanges. It also wants global investors, after major events occur in any time zone, to first use the US market to complete their trades.
In the short term, Nasdaq is competing for orders from ATS night platforms, brokers' internal execution systems, and other exchanges; in the medium term, it's competing for the nighttime price discovery of ETFs and large-cap tech stocks; in the long term, it's competing for the entry point for global asset pricing during Asian daytime.
The Nasdaq is extending trading hours not to make American investors stay up late trading stocks. It wants to turn the daytime of Asian investors into the trading hours for US stocks.
Asian Daytime Becomes the US Night Session
The core US stock trading session is only 6.5 hours. Pre-market and after-hours trading already exist. Nasdaq's new arrangement fills the gap from 9:00 PM to 4:00 AM ET. Only one hour is left for maintenance daily.
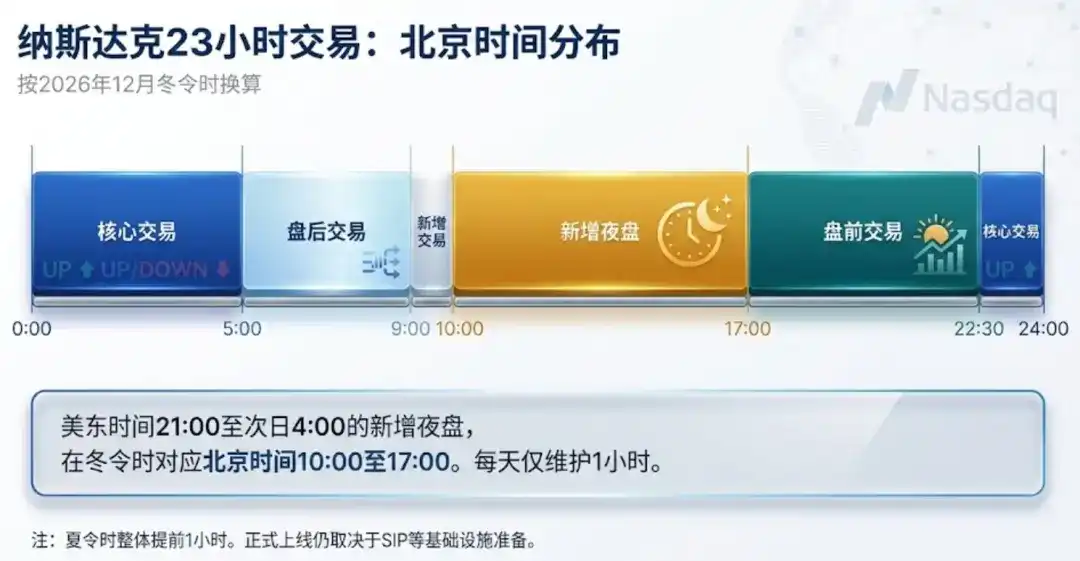
Note: Beijing Time cross-day distribution of Nasdaq's 23-hour trading
This new time slot precisely covers the daytime of major Asian markets. Investors in China, Japan, and South Korea no longer need to wait until late at night. After events like Fed policy announcements, geopolitical conflicts, or corporate news, Asian capital also doesn't need to wait for the New York open.
What Exactly Are Investors Buying During the Asian Session?
Nasdaq has published a set of US overnight trading data. The statistical period is from January to June 2025. These trades mainly occur during the Asian session. The data cannot identify investor nationality, nor can all trades be attributed to Asian capital. It is more suitable for observing trading preferences and instrument choices during the Asian session.
There are about 11,300 trading symbols in the US market. Only 1,403 of them recorded trades overnight. Only 644 had average daily trading volume exceeding $10,000. The top 15 symbols accounted for about 53% of total overnight volume (Nasdaq summarized it as close to 55%). Among them, 12 were ETFs, and only 3 were individual stocks. This indicates that night trading is not a migration of liquidity across the entire market, but rather concentrated trading in a few macro risk tools and ultra-large-cap assets.
SPY, IVV, and VOO are all S&P 500 ETFs, collectively accounting for 25.6% of overnight volume. QQQ accounted for 4.5%. TQQQ (triple leveraged long on QQQ) and SQQQ (triple leveraged short on QQQ) together accounted for 2.9%.
The three most active individual stocks were Tesla, Nvidia, and Alibaba, collectively accounting for 12.7%. Other active products included gold, Indian equity, international equity, and corporate bond ETFs.
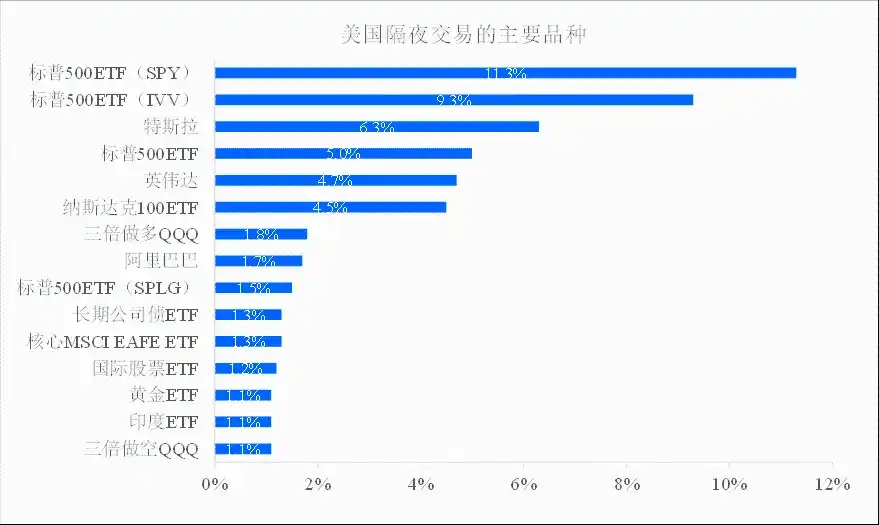
Investors during the Asian session first trade the US market, and only then US companies. The main character in the night session is not company research, but risk management.
Nasdaq's First Target Is Order Flow
SPY, IVV, VOO, and Alibaba are not listed on Nasdaq. They can still be traded on Nasdaq. This fact illustrates that 23-hour trading is first and foremost not about competing for listed companies, but about competing for trading orders.
After US exchanges close, order flow does not disappear. It flows to overnight platforms like Blue Ocean, brokers' internal systems, and other trading venues. The New York Stock Exchange and Cboe are also advancing longer trading. The London Stock Exchange is preparing to build a new extended-hours trading platform starting with ETFs. The supporters' rationale is that pulling these orders back to regulated exchanges can improve execution transparency, quote visibility, and market surveillance capabilities.
Exchange revenue doesn't just come from fees. Order flow brings data revenue, attracts market makers, and also forms market reference prices. Whoever gets the orders first gets to write the information into the price earlier.
Longer trading hours will also enhance the attractiveness of the US market to overseas companies. This effect ranks after the competition for orders. Companies choosing a listing venue still need to compare valuation, liquidity, investor base, and regulatory costs.
Nasdaq competes for orders first, then for price. Only after mastering price can it potentially attract more companies.
Who Pays for 23-Hour Trading?
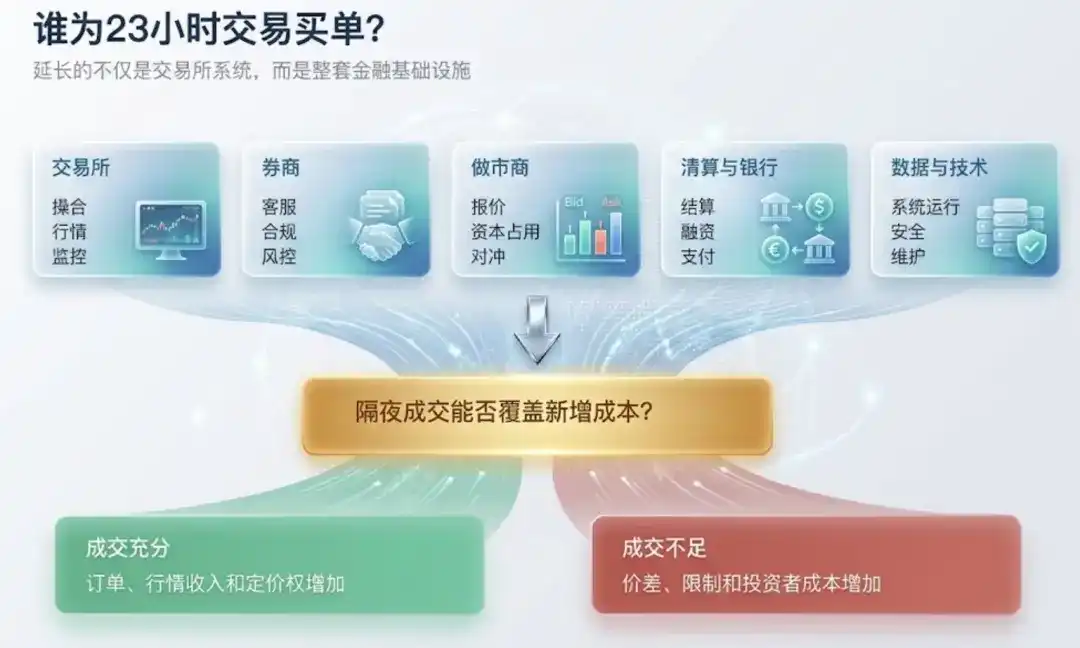
The exchange is extending more than just its matching system. The entire financial infrastructure needs to operate for longer hours.
Exchanges need to continuously provide data and monitor trading. Brokers need to arrange customer service, compliance, and risk control. Market makers need to extend their quotes, tying up more capital. Clearinghouses, banks, data vendors, and technology service providers also need to work synchronously. System maintenance time is compressed, and cybersecurity risks increase accordingly.
Existing pre-market and after-hours trading already bears part of the cost. Adding a night session will still increase personnel, system, capital, and compliance expenses. The problem is that overnight trading volume for most stocks is very thin. A large number of institutions will need to maintain a full set of services for a handful of ETFs and large-cap tech stocks.
The cost will ultimately fall back on investors. It may not manifest as a specific night session commission. Bid-ask spreads may widen. Financing costs may increase. Brokers may limit market orders and tradable products. Market makers will also factor capital commitment and hedging risks into their quotes.
The exchange extends time; investors bear the spread. Trading hours are not a free public service; they are a financial product that requires trading volume to pay the costs.
Prices Appear Faster, But That Doesn't Mean They're More Accurate
23-hour trading increases market reaction speed. It does not automatically create liquidity.
Overnight participants are fewer, and market depth is insufficient. Trading hours for stocks, futures, and options are also not fully synchronized. After selling a stock, a market maker may not be able to immediately use other instruments to hedge. Quotes will be more conservative, and spreads will be wider.
After a major news event, a price will quickly form in the night session. This price may reflect new information, or it may just be the result of a small number of orders pushing it. When the main trading session opens and more institutions enter, the night session price often needs to be retested.
Investors gain the freedom to trade at any time, and also the freedom to make mistakes at any time. The night session is more suitable for reducing sudden risks than for chasing short-term price movements. Limit orders are more important than market orders. Sometimes, waiting for liquidity to recover is cheaper than acting immediately.
23-hour trading solves the problem of "can I sell?" but not the problem of "at what price should I sell?"
The US Exports Not Just Capital, But Also Price
The fact that ETFs dominate overnight volume reveals a deeper change. Global investors can trade not only US stocks but also gold, Indian equities, global bonds, and other countries' market risks in the US market. These assets may not belong to the US, but trading and pricing are increasingly concentrated in the US. After major events, global capital first adjusts positions through US ETFs. Before local markets open, the US market has already formed a reference price.
This leaves a question for Asian markets. When Indian stocks trade through US ETFs, who determines the international price for Indian assets? When Chinese tech stocks trade simultaneously in Hong Kong and the US, which market reflects global expectations earlier? When Asian markets open, do they price independently, or do they correct the answers already given by the US market?
The US exports not just capital, but also price.
Does HKEX Need to Replicate Nasdaq?
HKEX has already studied extending trading hours. The cash market has discussed opening at 9:00 AM and eliminating the lunch break. The current focus remains on extending night trading for derivatives. In the short term, the Hong Kong stock market is better suited for limited extensions and product pilots rather than directly copying 23-hour cash trading.
The biggest constraint is the Southbound Stock Connect. Southbound capital accounts for a significant portion of Hong Kong stock turnover. If HKEX unilaterally opens a night session, mainland capital cannot participate simultaneously. Trading could be split into two markets. Operational costs for financial institutions would definitely increase, while there is no guarantee of new order flow. A more realistic path is to first create incremental changes around derivatives night trading, ETFs, a few large dual-listed stocks, and RMB trading and settlement conveniences.
Hong Kong's real advantage is also not business hours. Hong Kong possesses a group of Chinese internet, consumer, healthcare, and AI companies that global investors cannot directly access in other markets. A more important task for HKEX is to increase the supply of quality assets, expand Connect schemes, and improve RMB trading and settlement.
Nasdaq brings global order flow to the US market. HKEX brings Chinese assets to global investors. While both are competing for pricing power, their paths are different.
Conclusion: It's Not About Staying Open Longer
On the surface, 23-hour trading is a change in trading rules. Behind it is a battle among trading platforms, financial intermediaries, and major capital markets for global order flow.
Trading hours are just an amplifier. With global demand, extending hours can increase turnover and expand pricing power. Without sufficient demand, extending hours only increases costs and fragments liquidity.
Without assets worth sustained trading by global investors, extending business hours will only extend thin trading. What exchanges are truly competing for is not who stays open longer, but who defines the next global price.