From Speculation to Risk Management: Predictive Markets Are Filling the Gap in Commercial Insurance

marsbitPublished on 2026-08-17Last updated on 2026-08-17

Abstract

From Speculation to Risk Management: Predictive Markets Filling the Commercial Insurance Gap The emergence of AI risk management tools like Blanket is exploring the potential of predictive markets as a genuine insurance tool for businesses. These markets, with their simple contract structure—paying $1 if an event occurs, $0 if not—allow the real-time market price to reflect collective probability assessments. Businesses can use them to hedge against operational risks (e.g., abnormal weather, energy price fluctuations) that are often not covered by traditional business interruption insurance, which typically requires physical damage. A key question is whether these markets are genuinely used for hedging or remain primarily speculative. Analysis of Kalshi markets from August 2025 to August 2026 compared weather contracts (a potential hedge instrument) against sports contracts (largely speculative) and traditional CME grain futures. Three behavioral metrics were examined: 1. **Daily Turnover Rate:** Weather contracts showed the lowest rate (0.210), lower than corn futures (0.266) and significantly lower than sports contracts (0.315), suggesting longer holding periods. 2. **Hold-to-Expiry Ratio:** Weather contracts had a much higher ratio (over 0.5) compared to near-zero ratios for sports contracts, indicating a stronger tendency to hold positions until settlement, consistent with hedging behavior. 3. **Position Buildup Timing:** Weather market positions reached 50% of their...

Written by: G_Gyeomm

Compiled by: AIdidiaoJP, Foresight News

I. A New Type of Insurance Directly Priced by the Market

The recently launched AI risk management tool Blanket is attempting to turn predictive markets into a genuine insurance tool usable by businesses. The logic is straightforward: a business inputs its operational information, the system automatically diagnoses its main risk exposures, and then recommends corresponding Kalshi event contracts to help the business hedge against these risks.

The hedging mechanism itself is not complex. The contract structure of a predictive market is extremely clear — it pays $1 if an event occurs and $0 if it doesn't. The contract's real-time price represents the market's collective judgment on the probability of that event occurring.

It is precisely this simple structure that gives predictive markets the potential to become real hedging tools. Businesses can preemptively purchase contracts for events that could impact their operations, such as abnormal weather, energy price volatility, or tariff policy changes. If these risks materialize, the contract payouts can partially or fully offset the operational losses.

A specific example: an ice cream shop that would lose about $20,000 in revenue if the summer is unusually cool.

The hedging operation is as follows: buy 20,000 temperature contracts at $0.30 each. If the average summer temperature falls below a preset threshold, each contract pays out $1. The total cost is $6,000.

There are only two possible outcomes:

  • Cool Summer: The temperature is below the threshold, revenue is down $20,000, but the contracts pay out $20,000 in total. The net loss is locked at $6,000 — exactly the initial cost of buying the contracts.
  • Hot Summer: The temperature is above the threshold, revenue is unaffected, but the contracts expire worthless, and the $6,000 cost is completely lost.

Regardless of the outcome, the final loss is firmly locked at $6,000. This $6,000 is essentially the insurance premium. And the rate for this premium is not set by an insurance company's actuary or any traditional underwriting institution, but by the market itself — the price quoted in real-time by countless buyers and sellers with real money.

II. Is the Hedging Market Really Functioning?

Predictive markets have already accumulated enough speculative demand. They first gained fame through election predictions, then smoothly expanded into the sports arena, largely solving the volume problem. The industry generally believes the next growth space lies in expanding more practical use cases, with hedging needs repeatedly mentioned as one of the most promising directions.

In principle, its value is indeed significant. The gaps not covered by existing hedging tools are quite broad. Traditional business interruption insurance in commercial insurance typically requires physical damage as a precondition. A ski shop losing revenue because there was hardly any snow all winter — this kind of pure "operational risk" — is almost impossible to find suitable insurance products to cover on the market.

There are mature hedging tools in the futures market, but the barriers are high: requiring an ISDA agreement, opening a specialized futures account, posting margin, and minimum contract size limits. These are not issues for large institutions, but are almost unattainable for ordinary small and medium-sized enterprises. Goldman Sachs can maintain a professional derivatives trading team, but the cafe on the corner obviously cannot.

The problem is, there has always been a clear chasm between theoretical rationality and actual use. Predictive markets have long carried the label of "gambling," and whether they can truly operate as an independent hedging market — rather than just a speculative tool — has never been systematically verified.

The real question that needs answering is: Are predictive markets actually being used for hedging? Does real hedging demand exist? Trading behavior itself can provide clues. We selected three sets of data for comparison.

The first set is CME grain futures — a typical traditional hedging market, primarily used to mitigate losses from price fluctuations in agricultural and livestock products.

The second set is the Kalshi sports market — where hedging demand is extremely limited, and trading is almost entirely driven by speculation.

The third set is the Kalshi weather market — it handles weather risk in a manner similar to CME weather futures, while sharing the exact same event contract structure and trading environment with the Kalshi sports market. This makes it an excellent test sample — to see which side its trading behavior is closer to.

Hedging and speculation typically exhibit different trading characteristics. Hedgers tend to establish positions well before the actual risk window arrives and hold them until expiration; speculators move in and out more frequently, chasing prices, with noticeably higher turnover rates.

If the Kalshi weather market's turnover rate and holding behavior are closer to traditional hedging markets than to the sports market, then hedging demand is real.

Conversely, if it's not much different from the sports market, then actual usage is closer to pure speculation. In that case, tools like Blanket might be responding to a nice industry hypothesis, not a real demand confirmed by data.

The dataset for this analysis covers 1,265 Kalshi markets settled between August 2025 and August 2026. The screening criteria were: cumulative trading volume of at least 500 contracts, and trading lasting at least three days.

III. Data Point 1: Average Daily Turnover Rate

First, look at how frequently positions are traded in each market. Turnover rate is defined as daily trading volume divided by open interest (OI) for that day. We calculated the daily turnover rate for each contract in each market and then took the median for the entire trading cycle.

The results are clear: Kalshi weather contracts have the lowest turnover rate, only 0.210. The traditional hedging product corn futures is 0.266, and Kalshi sports contracts are the highest at 0.315.
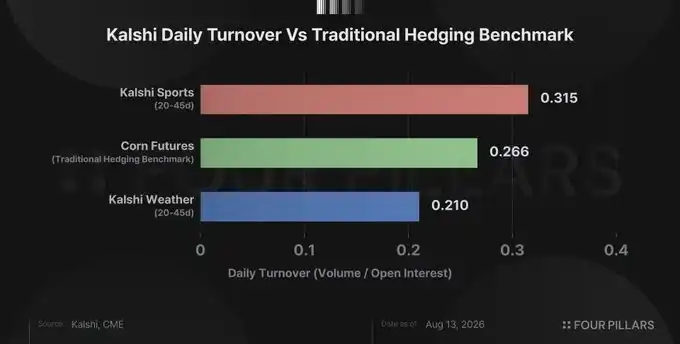
Sports contracts turn over about 1.5 times faster than weather contracts. This indicates a relatively longer holding tendency for weather contracts, initially suggesting the possible existence of real hedging demand.

However, a caveat: Corn futures' turnover rate sits in the middle, and the differences among the three data sets are not particularly stark. Based on turnover rate alone, we cannot fully confirm the existence of hedging demand in the weather market. What this data can definitively tell us so far is only that weather contract turnover is significantly lower than sports contract turnover.

IV. Data Point 2: Hold-to-Expiration Ratio

The second key metric is the hold-to-expiration ratio — measuring how many positions remain untouched in the market at settlement. It is calculated as the final open interest for each contract divided by the cumulative trading volume. A higher value indicates more positions were firmly held until the expiration date.
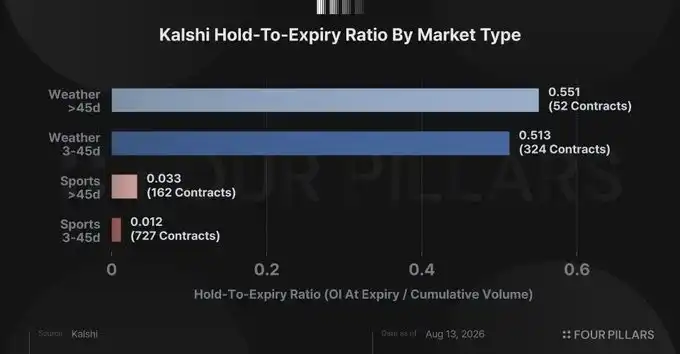
The difference in results is very striking: regardless of trading duration, the hold-to-expiration ratio for weather contracts exceeds 0.5. In contrast, sports contracts are only 0.012 and 0.033 respectively. In the 3 to 45-day trading interval, weather is 42.8 times that of sports; in the over 45-day interval, the gap is still 16.7 times.

This clearly shows: Weather contracts are far more inclined to "buy and hold" than sports contracts. Hedgers hold contracts to receive payouts if the risk materializes, not to chase price differences. Therefore, a high hold-to-expiration ratio strongly supports the judgment that there is real hedging demand in the weather market.

Of course, this cannot be directly interpreted as the entire weather market being used for hedging. This data does not track the identities of individual position buyers and sellers, so it cannot be simply equated with the proportion of original buyers holding to expiration. What can be confirmed at present is that the holding behavior of weather contracts is distinctly different from that of sports contracts.

V. Data Point 3: When Were Positions Established?

The final question is: When were these positions established? We divided the daily open interest for each contract by that contract's peak open interest, converted the time from launch to expiration into a progress bar from 0% to 100%, and then plotted the median curve.

The criterion for judgment is the point at which half of the peak open interest is reached. If half is reached when there is still more time until expiration, it means positions were built earlier — which is more in line with the behavior pattern of hedgers.
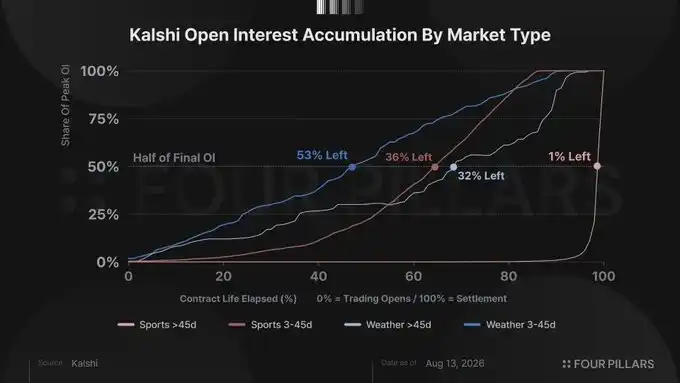
For weather contracts trading for 3 to 45 days, they had already reached half their peak open interest when their lifecycle was at 47%, leaving 53% of the time until expiration. Sports contracts in the same interval didn't reach half until 65%, with only 36% of the time remaining.

For contracts over 45 days, the difference is even more astonishing. Weather contracts reached half when there was still 32% until expiration, while sports contracts had only 1.3% left. Regardless of the interval, weather positions were established much earlier than sports positions.
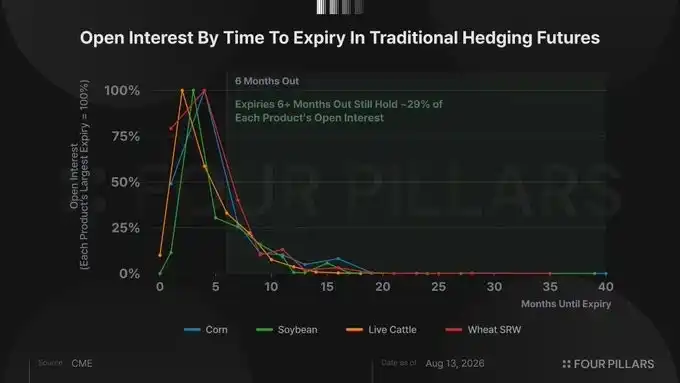
This behavior of "early positioning" is precisely a typical characteristic of traditional hedging markets. As of August 11, 2026, CME grain and livestock futures contracts expiring in six months had already accumulated massive open interest. Corn futures even held 65,127 positions on contracts expiring 16 months later.

This reflects the tendency to act well before the risk actually materializes. And the behavioral pattern of Kalshi weather contracts is clearly closer to traditional hedging markets than to sports markets.

VI. Hedging Relies on Liquidity Built by Speculation

Conclusion first: The Kalshi weather market is neither a purely hedging market nor a purely speculative one like sports. Speculative demand still contributes a significant portion of the liquidity, but on top of that, hedging demand has also emerged relatively clearly.

The three indicators point in the same direction: weather contracts trade less frequently, retain more positions at settlement, and positions are established earlier. No single indicator can confirm trading intent with 100% certainty, but the high consistency of these behaviors collectively supports a judgment — there indeed exists a holding demand in the Kalshi weather market distinct from sports, and a considerable part of it is likely real hedging demand.

More importantly, speculative demand is not so much a weakness of predictive markets as it is a prerequisite for the hedging function to exist. A market with only hedgers and no speculators would struggle to find sufficient counterparties and continuous liquidity.

In predictive markets, speculators are responsible for pricing and providing liquidity, while hedgers transfer the risks they do not wish to bear on this foundation. The risk is no longer directly underwritten by an insurance company but is naturally dispersed among market participants through trading.

Therefore, the next phase of growth for predictive markets is not about "squeezing out" speculation and shifting entirely to hedging. What truly matters is: How much real corporate hedging demand can be layered on top of the liquidity base already built by speculation? This is the core variable that determines whether it can upgrade from an "interesting speculative tool" to a "usable risk management infrastructure."

Trending Cryptos

Related Questions

QWhat is the main difference between using a prediction market and traditional insurance for business risk management?

AThe main difference is that in prediction markets, the insurance premium (price of the contract) is determined collectively by market participants based on their assessment of the event's probability, whereas in traditional insurance, the premium is calculated by the insurer's actuaries.

QWhat are the three data points used to analyze whether the Kalshi weather market is used for hedging?

AThe three data points are: 1) Average daily turnover rate, 2) Hold-to-expiration ratio, and 3) The timing of when positions are established (measured by the time it takes to reach 50% of peak open interest).

QAccording to the analysis, how does the trading behavior of Kalshi weather contracts compare to its sports contracts?

AThe analysis shows that Kalshi weather contracts have a lower turnover rate, a significantly higher hold-to-expiration ratio, and positions are established much earlier compared to Kalshi sports contracts. This suggests behavior more consistent with hedging.

QWhat is the primary role of speculators in a prediction market that aims to serve hedging purposes?

ASpeculators provide the necessary liquidity and price discovery in the prediction market, which creates a functional trading environment that allows hedgers to enter and exit positions to transfer their risks.

QWhat example is given to illustrate how a business could use a prediction market contract to hedge against operational risk?

AThe example given is an ice cream shop that could hedge against a cool summer. It could buy 20,000 temperature contracts at $0.30 each (total cost $6,000). If the summer is cool and average temperature falls below a threshold, each contract pays $1, offsetting the estimated $20,000 revenue loss, thereby locking the net loss at the initial $6,000 cost. If the summer is hot, the contracts expire worthless, and the shop loses the $6,000 premium but enjoys full revenue.

Related Reads

Trade.xyz Enters the Prediction Market: Who Has Cheaper Fees Compared to Polymarket?

Trade.xyz has launched its prediction market product, "Events," on the Hyperliquid mainnet. Its initial week saw modest activity: $180k in volume and 263 users. The platform aims to integrate prediction markets into a "universal exchange" vision alongside its existing perpetual contracts. A key focus is its fee structure compared to incumbent Polymarket. Trade.xyz uses Hyperliquid's spot trading fees: a fixed 0.07% for Takers and 0.04% for Makers, with volume-based discounts and additional reductions for HYPE token stakers. Fees are charged upon position closure or settlement. Polymarket employs a dynamic model: Makers pay no fees and receive rebates, while Taker fees vary by market category and are calculated as `C × feeRate × p × (1-p)`, where `p` is the outcome probability. This makes fees highest near 50/50 odds and lower as probability approaches 0% or 100%. In a 50% probability scenario for a $100 Taker trade, Polymarket fees (0.04%-0.07% parameter) range from $1 to $1.75, significantly higher than Trade.xyz's ~$0.07. However, for highly probable outcomes (e.g., 99%) or for Maker orders, Polymarket can be cheaper or even free (e.g., Geopolitics markets). While Trade.xyz currently lags far behind Polymarket in scale, it leverages Hyperliquid's existing liquidity and user base. Its potential lies in combining prediction markets with its proven perpetuals infrastructure, positioning it as a possible challenger in the evolving prediction market space.

marsbit1h ago

Trade.xyz Enters the Prediction Market: Who Has Cheaper Fees Compared to Polymarket?

marsbit1h ago

Bankless Swap Strategy Success Methodology: How to Screen Undervalued Tokens from VVV to Hyperliquid?

Title: Bankless on Identifying Undervalued Tokens: From VVV to Hyperliquid Summary: In a shifting crypto market, the investment focus is moving from infrastructure narratives to applications with verifiable business models and revenue. This Bankless podcast discussion with Austin Barack of Relayer Capital analyzes how tokens like Venice (VVV), Hyperliquid (HYPE), Pump.fun (PUMP), and ether.fi (ETHFI) can be evaluated based on their fundamentals. Key points include: 1) The market is shifting from chasing growth narratives to finding the intersection of growth and reasonable valuation. 2) Token value is increasingly linked to observable value flow through mechanisms like protocol revenue used for buybacks/burns (e.g., Venice, Hyperliquid). However, this is not a direct equivalent to stock dividends, as token rights are less formalized. 3) Revenue quality and sustainability matter more than just the amount. For instance, Pump.fun's low valuation reflects market skepticism about meme coin trading longevity, despite its resilient revenue over two years. 4) Market categorizations can lag behind business evolution. ether.fi is now primarily a neo-bank/payments platform, not just a restaking protocol, which may create a pricing disconnect. 5) While real revenue can provide a valuation floor and reduce correlation with crypto cycles, these tokens are not fully decoupled from broader market trends. The core argument is that the next phase of crypto valuation will be driven by applications that convert real usage into sustainable revenue and credibly share a portion of that value with token holders, moving towards an application-based economy.

marsbit1h ago

Bankless Swap Strategy Success Methodology: How to Screen Undervalued Tokens from VVV to Hyperliquid?

marsbit1h ago

Trading

Spot

Hot Articles

What is G$

Understanding GoodDollar ($G$): A Blueprint for Decentralized Universal Basic Income Introduction In the ever-evolving landscape of cryptocurrency and blockchain technology, initiatives that seek to address pressing social issues have garnered increased attention. One such project is GoodDollar ($G$), a Web3-based universal basic income (UBI) solution. GoodDollar endeavors to tackle inequality and bridge the wealth gap by creating and distributing accessible economic resources to those most in need. Through its innovative use of decentralized finance (DeFi), GoodDollar presents a unique model that could potentially reshape the way financial assistance is perceived and delivered globally. What is GoodDollar ($G$)? GoodDollar is a cryptocurrency protocol that facilitates the issuance and distribution of digital tokens, referred to as $G$, to its registered users on a daily basis. These tokens function as a form of universal basic income, promoting financial empowerment for individuals from various backgrounds, especially those traditionally excluded from the financial system. Operating on the blockchain, GoodDollar utilizes multiple chains, including Ethereum, Celo, and Fuse, ensuring broad access and usability. The fundamental goal of GoodDollar is to make cryptocurrency accessible and beneficial to everyone, irrespective of their economic starting point. The Creator of GoodDollar ($G$) Details concerning the creator of GoodDollar remain somewhat obscure. However, it is notably highlighted that the project has strong backing from eToro, a widely recognized investment platform that provided the initial funding and foundational support for GoodDollar's development. The vision behind the project is not solely profit-driven but leans heavily towards social entrepreneurship, aiming for a systemic change in economic accessibility. Investors of GoodDollar ($G$) GoodDollar enjoys the financial backing and operational support of eToro. This partnership has played a significant role in launching the protocol and its subsequent developments. While eToro was instrumental in establishing the foundation of the project, GoodDollar envisions transitioning towards a model funded by its community in the long run. This shift to community funding is in line with GoodDollar's commitment to decentralization, allowing its users to have a direct stake in the project's future. How Does GoodDollar ($G$) Work? GoodDollar's operational framework relies heavily on DeFi principles to generate interest from staked cryptocurrencies. This mechanism allows the project to mint and distribute $G$ tokens as a digital basic income for users worldwide. Several key features contribute to GoodDollar's uniqueness and innovation: Universal Basic Income (UBI): Every day, registered users receive free tokens, establishing an automatic income stream intended to alleviate financial pressures. Sustainable Economic Model: The project’s tokenomics aim to balance supply and demand for $G$ tokens, ensuring that the value remains stable over time. Reserve-Backed Tokens: Each $G$ token is backed by a reserve of cryptocurrencies, providing it with inherent value and reliability, a crucial aspect for maintaining user trust. Decentralized Governance: GoodDollar incorporates a democratic approach to decision-making through token-powered decentralized governance. This allows community members to actively participate in the shaping of the project's trajectory, making it truly community-driven. Global Accessibility: GoodDollar has established a considerable community footprint, boasting over 640,000 members spanning 181 countries. Such widespread reach is instrumental in facilitating UBI on a global scale. Timeline of GoodDollar ($G$) The evolution of GoodDollar is marked by several significant milestones throughout its history: 2019: The launch of the GoodDollar wallet marked the first step in operationalizing its vision of delivering UBI through cryptocurrency. 2020: Following the successful wallet rollout, the GoodDollar protocol officially debuted. This marked a crucial phase in its mission to provide daily distributed income. 2021: The project advanced further with the introduction of its Decentralized Autonomous Organization (DAO), fostering a greater level of community involvement and governance. 2022: GoodDollar unveiled its DeFi-friendly version 2 (V2), striving for enhanced user engagement and operational efficiency. The same year also saw the transition to a decentralized governance structure via GoodDAO. 2022: A new roadmap was conceptualized, focusing on initiatives like a grant program designed to promote $G$-related entrepreneurial ventures and an upgraded GoodDollar Marketplace. Key Features of GoodDollar ($G$) The GoodDollar project introduces numerous critical features aimed at redefining the landscape of basic income: Universal Basic Income: Delivering daily free tokens to its users fundamentally underscores its mission to eliminate economic precarity. Multi-Chain Operation: Leveraging multiple blockchain networks enhances accessibility and scalability, ensuring broader participation. Engagement with Decentralized Finance: The use of DeFi allows for sustainable funding of the UBI model, reinforcing its viability as an economic solution. Community Engagement and Governance: GoodDollar envisions a model where the community influences operations through democratic participation, fostering transparency and accountability. Global Community: Boasting a diverse global community enables the project to implement UBI solutions tailored to various cultural and economic contexts. Conclusion GoodDollar represents a transformative leap towards incorporating the principles of universal basic income through the innovative lens of blockchain technology. By harnessing decentralized finance, the project not only provides a solution to financial inequality but also actively engages users in its governance and operations. With a growing community and evolving roadmap, GoodDollar stands as a significant player in the intersection of cryptocurrency and social good, paving the way for a more equitable financial future. As it continues to evolve, GoodDollar’s journey may ultimately inspire other initiatives to consider similar models, furthering the cause of economic empowerment for all.

1.6k Total ViewsPublished 2024.04.01Updated 2024.12.03

What is G$

How to Buy G

Welcome to HTX.com! We've made purchasing Gravity (G) simple and convenient. Follow our step-by-step guide to embark on your crypto journey.Step 1: Create Your HTX AccountUse your email or phone number to sign up for a free account on HTX. Experience a hassle-free registration journey and unlock all features.Get My AccountStep 2: Go to Buy Crypto and Choose Your Payment MethodCredit/Debit Card: Use your Visa or Mastercard to buy Gravity (G) instantly.Balance: Use funds from your HTX account balance to trade seamlessly.Third Parties: We've added popular payment methods such as Google Pay and Apple Pay to enhance convenience.P2P: Trade directly with other users on HTX.Over-the-Counter (OTC): We offer tailor-made services and competitive exchange rates for traders.Step 3: Store Your Gravity (G)After purchasing your Gravity (G), store it in your HTX account. Alternatively, you can send it elsewhere via blockchain transfer or use it to trade other cryptocurrencies.Step 4: Trade Gravity (G)Easily trade Gravity (G) on HTX's spot market. Simply access your account, select your trading pair, execute your trades, and monitor in real-time. We offer a user-friendly experience for both beginners and seasoned traders.

7.1k Total ViewsPublished 2024.07.18Updated 2026.08.28

How to Buy G

What is @G

Graphite Network, $@G: Bridging TradFi and Web3 Introduction to Graphite Network, $@G In the vibrant world of cryptocurrencies and web3 projects, Graphite Network emerges as a beacon of innovation. With its native token, $@G, this Layer-1, Proof-of-Authority (PoA) blockchain is tailored to bridge the gap between traditional finance (TradFi) and the rapidly evolving Web3 ecosystem. As digital currencies gain traction, Graphite Network strives to offer a blockchain platform that prioritizes security, compliance, and speed, presenting itself as a facilitator of trust and accountability. What is Graphite Network, $@G? Graphite Network is not merely another blockchain project; it aims to redefine how decentralization, security, and user accountability are perceived in the digital finance realm. The project boasts a series of distinctive features: Reputation-Based Blockchain: At its core, Graphite Network implements a one-user, one-account policy, fortified with integrated Know Your Customer (KYC) verification and scoring mechanisms. This design ensures a balance between user privacy and transparency—a critical aspect of financial operations in today’s digital world. Entry-Point Node Income: The network incentivizes users to set up entry-point nodes, allowing operators to earn rewards from network transactions. This income generation model not only boosts user engagement but also reinforces network health and decentralization. EVM Compatibility: With an Ethereum-compatible virtual machine (VM), Graphite Network enables seamless integration of existing Solidity decentralized applications (dApps) and smart contracts, thereby inviting developers to leverage its capabilities without extensive modifications. KYC Integration: In an era where compliance is paramount, the integrated KYC framework with multiple verification tiers enhances the control over financial operations without mandatory participation, setting a precedent for user autonomy. Who is the Creator of Graphite Network, $@G? The Graphite Network is borne out of the endeavors of the Graphite Foundation, a non-profit organization dedicated to the development, maintenance, and evolution of the Graphite Network. The foundation’s commitment underscores the project’s vision to create a secure and sustainable blockchain environment focused on genuine user engagement and compliance. Who are the Investors of Graphite Network, $@G? Currently, there is limited information available on the specific investors backing the Graphite Network initiative. The founding organization, the Graphite Foundation, functions independently in fostering the project’s growth while seeking partnerships that resonate with its vision of a compliant and accessible blockchain platform. How Does Graphite Network, $@G Work? Graphite Network’s operation is grounded in its unique Proof-of-Authority consensus mechanism, which strikes an impressive balance between high throughput and decentralization. Let's delve into the various components that define its operation: Transport Nodes: Serving as the entry-point nodes, these are critical to the ecosystem. Operators can earn revenue from transactions that traverse the network, which not only empowers individual users but also bolsters network decentralization. Authorized Nodes: At the heart of the Graphite Network are core validators who undergo rigorous compliance tests, encompassing robust KYC verification along with technical assessments. This layer of trust is essential for ensuring that transactions within the network maintain a high level of integrity. Ticker System: Graphite Network employs a distinctive ticker system for its wrapped tokens, denoted as @G. This feature enhances clarity in asset integration, making user transactions comprehensible and straightforward. Graphite Network’s innovative approach reflects a significant step in addressing the crucial issues of digital finance, positioning itself favorably for the future as more users transition from traditional forms of finance into the world of decentralized applications. Timeline of Graphite Network, $@G To understand the progression and milestones of Graphite Network, it is beneficial to overview key events in its timeline: 2021: The inception of Graphite Network by the Graphite Foundation marks the commencement of a new chapter in blockchain development, focusing on compliance and user empowerment. Key Developments: Following its launch, the introduction of entry-point node income, the establishment of a reputation-based model, integrated KYC verification, and the provision of EVM compatibility represent significant advancements in the project. Recent Activities: The continuous development and nurturing efforts of the Graphite Foundation have focused on augmenting network features while fostering the ecosystem's growth, demonstrating a long-term commitment to sustainability and innovation. Additional Key Points Beyond its foundational components, Graphite Network encompasses several tools and features that bolster its usability: Graphite Wallet: A user-friendly Chrome extension that facilitates access to various network features and applications across Ethereum-compatible chains, enhancing user convenience. Graphite Bridge: This utility allows seamless transfers of Graphite assets across different networks, fostering an integrated and interoperable ecosystem. Graphite Explorer: Serving as an essential tool within the ecosystem, this feature enables users to view and verify smart contract source code, track transactions, and explore other vital information in real-time. Graphite Testnet: The project provides a robust testing environment for developers, allowing them to ensure stability and scalability prior to mainnet deployment. This initiative not only empowers developers but also enhances the reliability of the entire network. Conclusion Graphite Network, with its native token $@G, represents a significant stride toward bridging traditional finance and cutting-edge blockchain technology. By focusing on security, compliance, and decentralization, this innovative platform is set to lead the transition into the Web3 era. As user engagement grows and more projects leverage its capabilities, Graphite Network is poised to make lasting contributions to the rapidly evolving digital landscape. In conclusion, Graphite Network stands as a testament to what can be achieved when innovative thinking meets the growing demands of modern finance and technology. As the world explores the potential of decentralized finance, Graphite Network will undoubtedly remain a noteworthy player in this arena.

1.1k Total ViewsPublished 2025.01.06Updated 2025.01.06

What is @G

Discussions

Welcome to the HTX Community. Here, you can stay informed about the latest platform developments and gain access to professional market insights. Users' opinions on the price of G (G) are presented below.

活动图片