Original text byRyan Berckmans
Compiled / Odaily Planet Daily Golem(@web 3_golem)
The last era of the crypto industry dumped tokens through infrastructure, while its next era will choose Ethereum L1+L2 to build real businesses.
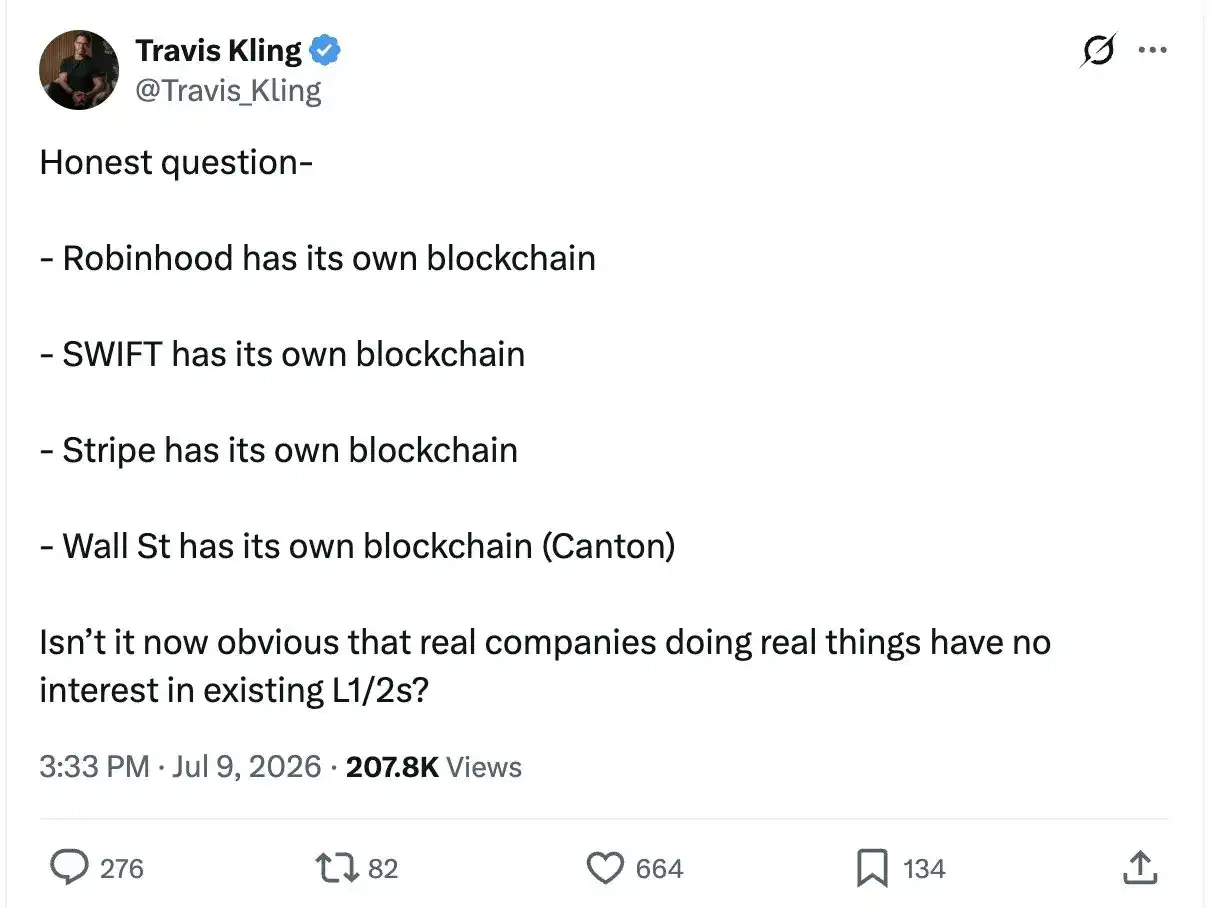
Travis Kling raised a question this week: 'Is it now obvious that companies doing real work are not interested in L1/L2?' Robinhood was his first example. But on the contrary, Robinhood is almost a perfect counterexample: when real-world companies make business decisions, they almost invariably choose the Ethereum L1+L2 model.
Robinhood chose an existing L1—Ethereum, and then built its own Ethereum L2 using Arbitrum technology. Robinhood Chain uses Ethereum blobs for data availability, uses ETH as its native gas token, and its security is provided by Ethereum.
Therefore, Robinhood did not reject the Ethereum L1+L2 model. On the contrary, the model is working as intended on Robinhood.
The 'buyers' choosing Ethereum have changed. In the past, crypto projects chose public chains and technologies to sell their own tokens, while the emerging real-world on-chain economy is adopting the Ethereum L1+L2 model as the foundation for cash businesses.
As the composition of buyers changes, I believe Ethereum's advantages will become even more pronounced.
The Old Crypto Economy Was Token-Centric
What I mean by 'real businesses serving real users' refers to a traditional company model: building products that customers need, earning profits by serving customers, and increasing the equity value of those profits.
The 'real users' here refer to consumer demand stemming from ordinary economic needs, not primarily speculative demand generated by new token issuance. Crypto-native users are obviously real users. This is not a moral judgment on a protocol's usefulness or the sincerity of its developers, merely a distinction based on the goal of operating a real-world economy.
A token's value can only come from three aspects:
- Cash: A reliable claim on future cash flows, similar to on-chain equity or bonds;
- Utility: Access, control, governance, or other privileged participation in a valuable system. Even without cash flow, a token that controls something important clearly has value;
- Monetary Premium: People hold the asset because they expect others to accept and recognize its value in the future. This asset is no longer merely a claim that must ultimately be exchanged for something else, but becomes a store of wealth—a terminal value asset.
Monetary premium is real but extremely difficult to sustain. It requires deep network effects built on trust, liquidity, distribution, integration, and utility. Gold, the US dollar, Bitcoin, and Ethereum have all built different versions of this effect, and few other assets have managed to do so.
Looking back, since programmable cryptocurrencies became popular, the vast majority of industry participants were not ordinary cash flow businesses. Their economic goal was often to sell a token whose value was primarily based on utility, anticipated monetary premium, or distant promises of future cash.
Sometimes, their plan was straightforward—launch a protocol and sell its token. Sometimes, it was more indirect—receive funding from a token-funded ecosystem and then cash out the received tokens. Sometimes, a project genuinely expected future profitability, but because the token's valuation was disconnected from any possible future cash, the actual business model remained confidence in the token itself.
This became the norm because almost every project was doing something similar, though there were some exceptions.
Centralized exchanges are essentially cash trading business platforms and are naturally multi-chain, connecting to another chain is like adding another deposit/withdrawal channel. Some stablecoin issuers are also cash trading businesses; they initially served clients in the crypto space and are now rapidly expanding into the broader economy.
But these exceptions precisely prove the point: businesses aiming for ordinary cash trading will choose infrastructure that maximizes their business, not their token's value.
Different Business Goals Will Build Different Projects
A company's ultimate goal determines its technology choices.
If the goal is a cash trading business, then the blockchain is infrastructure. The selection criteria are to reduce risk, improve the product, reach customers, and secure profits. If the goal is token monetization, then there is greater freedom in blockchain choice. After receiving funding from a public chain, a company can choose to build on the chain that funded it.
For example, if a protocol succeeds on Chain A, you can launch a similar protocol on Chain B, allowing investors to price your token by comparison. Want to create hype for a new token? A new L1, L2, app-chain, gas token, governance system, or certain special tech stack could all become selling points.
The issue is not the diversity of technology itself. The crypto industry will continue to see an explosion of applications, protocols, L2 architectures, and dedicated execution environments. The issue is the tendency to turn every new idea into a sovereign, independent ecosystem (with its own L1 architecture, security validation, liquidity base, and monetary asset), regardless of whether the underlying product warrants it.
As the crypto industry now shifts towards cash businesses, experiments continue, but these experiments will increasingly be built on shared infrastructure. Businesses will specialize at the application layer or on L2s while relying on the Ethereum L1 layer for settlement, security, liquidity, and monetary asset management. The result is not less innovation, but a balance: more diversity at the edges, more consolidation at the base.
The traditional crypto economy of the past often chose architecture around the token it wanted to sell. The emerging on-chain economy will choose architecture around the product it wants customers to buy.
The Buyers Are Changing
The future of the crypto industry will be vastly different from the past because the 'buyers' have changed.
The previous US administration vigorously suppressed the development of on-chain transactions. This trend has now reversed. The GENIUS Act is now in effect, providing a legal framework for payment stablecoins, and Europe's MiCA regulatory system is fully applicable. Brokerages, payment companies, banks, asset managers, and governments worldwide are formulating strategies for stablecoins, tokenization, and on-chain transactions.
This doesn't mean all regulatory issues are resolved, but it at least proves that large institutions can attempt more blockchain business.
We are approaching the beginning of the S-curve for true crypto industry mass adoption.
When we emerge from this phase, the crypto industry and traditional finance will no longer be two distinct categories. Property, money, transactions, finance, identity, and trust will all be coordinated through networks of on-chain and off-chain systems. Eventually, 'Web3' will fade away just like 'Web2', and everything will simply return to being the internet itself.
As this process advances, a larger proportion of crypto market participants will be real-world businesses serving ordinary consumers in the broader economy. This proportion will be reflected not just in the number of companies, but also in capital scale, user numbers, asset size, and institutional influence.
These companies are no longer crypto projects looking for a business model to prop up a token; they are businesses using crypto technology to optimize existing or emerging cash businesses. This determines their technology choices. Infrastructure choices made for token economics do not serve as a good guide for infrastructure choices made for cash economics.
Real-World Businesses Won't Build Infrastructure from 0 to 1
Typically, real-world businesses have limited budgets for risky infrastructure development. They do not want consensus mechanisms, cross-chain bridges, validator economics, gas, governance tokens, and liquidity bootstrapping to become six separate side businesses. Each additional link must create customer value, or it becomes a burden.
The chain should serve the business, not the business serve the chain.
Some businesses are inherently multi-chain. Exchanges, wallets, stablecoin issuers, and certain asset issuers may need broad distribution. Even then, 'multi-chain' rarely means every chain is equally important. Different chains usually have their own exclusive domains in terms of liquidity, issuance, settlement, product status, or deeper integration.
Most on-chain businesses need to make a special commitment to one chain or a few chains. Their choice typically takes three forms:
- When an on-chain business needs maximum decentralization, credible neutrality, risk minimization, or liquidity, they use Ethereum L1 services. L1 execution is more costly because it bears the burden of the most robust shared environment;
- When a business needs control, customization, compliance, predictable unit economics, low latency, or high throughput, they build their own Ethereum L2. Because they can get a dedicated chain as they wish while maintaining a direct connection to Ethereum;
- When a business does not need L1 and building its own L2 is unnecessary, they typically use one or more mature, shared L2s. Base, Arbitrum One, Robinhood, and other mature Ethereum L2s have become common deployment platforms.
These on-chain businesses will still bridge assets, 'export' products, and connect to other networks. Having a primary chain does not mean isolation. Importing, exporting, and interoperability are also core parts of an on-chain business. But the primary chain remains crucial. It determines the system's security, canonical state, liquidity relationships, operational model, and long-term dependencies.
Why Is Ethereum's L1+L2 Model Still Useful?
Ethereum separates the two major elements that large enterprises need.
The L1 provides a highly decentralized, credibly neutral, and highly liquid global hub. L2s provide a market of fast, low-cost, specialized, controllable, and customizable execution environments.
The L1 remains neutral, while the L2s at the edge can adapt to different operators, jurisdictions, products, and users. L2s extend Ethereum not only technically but also politically: organizations can operate in their own way without asking the global center (L1) to become their private chain.
An independent L1 can offer control and performance advantages. In some cases, complete sovereignty over consensus and data availability is worth it for a project, but acquiring it isn't cheap.
A new L1 must create and maintain its own security system, validator or operator set, bridges, liquidity, tools, integrations, and reputation. It creates a new security and liquidity silo, increasing the cost and friction of interoperability with Ethereum L1 and the broader L2 economy (i.e., the dominant on-chain economic network).
For the vast majority of businesses, the value created by an independent L1 does not offset these costs.
A customized Ethereum L2 can obtain most of the business advantages a company would want from adopting an independent L1: high TPS, control over execution, upgrades, fees, sequencing, latency, access rules, and product-specific features.
Furthermore, L2s provide advantages that independent L1s do not inherently have: Ethereum for settlement and data availability, standard L1 bridges, proximity to assets and capital on Ethereum, and a framework for achieving increasingly trust-minimized interoperability.
L2 design is still crucial. Admin keys, upgrade keys, proof systems, and withdrawal guarantees determine how much security a user has at any given moment. But even an L2 with control held by a few operators provides users with a solid settlement foundation on Ethereum L1. A company does not need to run and maintain its own L1 layer to operate its business.
An Ethereum L2 is both an independent blockchain and part of the Ethereum economic system. It can own and customize its execution environment while leveraging Ethereum for settlement, data availability, and interoperability management.
L2s often deeply integrate ETH into their application economy, for example, as the native Gas token. Canonical bridging patterns provide a trust-minimized path for capital and assets on L1 to enter the 'local economy' of the L2. Each new L2 has a unique product interface, and Ethereum's network effects continue to strengthen.
Robinhood Made This Business Decision
Robinhood's development path is highly instructive.
It first launched stock tokens on the mature L2 Arbitrum One. After validating the product and understanding its own needs, Robinhood launched its proprietary chain built on the Arbitrum platform.
This will likely become a standard strategy for real-world businesses: first build a business on an existing blockchain, then upgrade to a dedicated L2 once scale, product needs, and unit economics reach a certain level.
Robinhood Chain is customized for the financial services industry. It uses Arbitrum technology, offers 100ms latency, predictable transaction pricing, high throughput, and infrastructure tailored to Robinhood's performance, security, and regulatory requirements.
At the same time, Robinhood Chain is still an Ethereum L2. It uses Ethereum blobs for data availability and uses ETH as its native gas. Its official bridge to Ethereum does not require a third-party validator set. This is what it looks like when a real-world business builds a genuine on-chain product.
Robinhood does not need to launch a Robinhood gas token or convince the public it deserves a lasting monetary premium. Robinhood itself has stock; its economic gains come from customers, products, assets, transactions, and cash flow. The blockchain is merely its infrastructure.
Using ETH for gas is a simple business decision. L2 services already pay for L1 services using ETH. ETH is liquid, widely used, and the system's native token. If Robinhood used a proprietary Gas token, it would add issues with distribution, liquidity, pricing, and legality, and launching a token would not improve Robinhood's core product.
Robinhood's success will depend on its application layer and the off-chain business it supports, not on its efficiency in creating a new monetary asset. Therefore, it is inaccurate to say that Robinhood built its own blockchain and rejected existing L1 and L2 services.
Robinhood merely rejected sharing its dedicated execution environment with other projects, not Ethereum. On the contrary, it chose Ethereum as the mother chain for its proprietary blockchain.
Previously, Coinbase made a similar decision by launching Base. Coinbase is not an Ethereum advocate, and it's well known that Brian Armstrong has publicly stated his enthusiasm for Bitcoin far exceeds that for Ethereum. Yet, when Coinbase chose infrastructure for its on-chain business, it still chose to become an Ethereum L2.
Base is the strongest evidence that Ethereum's L1+L2 model is not just theoretical. Coinbase's decision was based on business considerations, not ideology.
When companies build cash businesses rather than conducting token sales, they make business decisions, which leads them to choose infrastructure based on the Ethereum L1+L2 model.
What Does This Mean for Ethereum and ETH?
This change in participant composition is extremely favorable for Ethereum.
Historically, the blockchain competitive landscape was dominated by teams whose incentives were focused on token creation, ecosystem funding, and token valuation. Looking ahead, the blockchain competitive landscape will increasingly be dominated by companies optimizing for security, customers, control, distribution, liquidity, and interoperability—all to serve cash businesses.
This shifts demand towards Ethereum's 'barbell' structure: L1 for maximum risk reduction and liquidity; L2 for scaling, customization, and operator control.
Ethereum has evolved into a globally universal platform not by forcing all companies into a single shared execution environment, but by becoming the underlying common settlement, security, liquidity, and asset layer for numerous environments.
This is also good news for ETH. ETH's success lies in building a monetary network and global trust. ETH is an excellent equity claim and the native asset of Ethereum's global settlement layer. Throughout the ecosystem, it serves as collateral, a liquid asset, a treasury asset, a productive asset, and is becoming a terminal asset.
As more real-world businesses build on Ethereum, they will distribute ETH to more users, integrate it into more products, and make it useful in more contexts. This enhances ETH's liquidity and investor confidence, thereby strengthening its monetary premium, which ultimately evolves into a larger network effect.
Robinhood is not an exception, but a beacon.
Real businesses use Ethereum L1 when they need the world's most neutral, lowest-risk, and most liquid shared environment. When they need control, customization, and high performance, they build their own Ethereum L2. And when their business isn't yet ready to support building an independent blockchain, they deploy to mature blockchains, typically Ethereum L2s.
This is not because they are fans of Ethereum, but because they made rational business decisions.