Large-scale Long-Term Bond Sell-off Forces a Severe Budgetary Reassessment

cryptonews.ruPubblicato 2026-08-15Pubblicato ultima volta 2026-08-15

Introduzione

Large-scale sell-offs in long-term government bonds have forced a major budget reassessment. Yields on key bonds surged to levels not seen in years or even decades: US 30-year Treasuries hit around 5.25% (highest since 2001), while German 30-year Bunds approached 3.73% (highest since 2011). French long-term yields returned to levels last seen during the global financial crisis, and Japan's 5-year government bond yields broke above 2.14%, signaling a departure from years of ultra-loose monetary policy. The era of ultra-cheap money, sustained by central bank stimulus post-2008 and during the pandemic, is ending. Investors now demand higher compensation for lending over decades, seeking protection against inflation, heavy bond issuance, and currency devaluation. Market patience with fiscal dysfunction is wearing thin, as seen in soaring yields for highly indebted European nations like France. The pressure stems from widening fiscal gaps in major economies (US, France, Japan), which face rising spending on defense, infrastructure, energy, and aging populations. In the US, annual federal interest payments now exceed $1 trillion. As central banks reduce bond holdings via quantitative tightening, they are withdrawing as major buyers. Governments are flooding the market with new debt, forcing private investors to demand higher yields—a rising term premium. The impact extends beyond government budgets: higher long-term yields push up mortgage rates, increase borrowing costs for cor...

A synchronous sell-off has pushed the yields of major long-term bonds to levels unseen in many years, and in some cases, decades. The yield on 30-year US Treasury bonds reached approximately 5.25%—the highest level since 2001—while the yield on 30-year German Bunds approached 3.73%—the highest level since 2011.

"Good morning from Germany, where the bond market is sending an unambiguous signal: the yield on 30-year German Bunds has risen to 3.73%—the highest level since 2011," wrote German journalist, author, and senior financial editor Holger Zschaepitz on X. "Germany now pays as much for borrowing as it did during the euro crisis era. The era of ultra-cheap money is over."
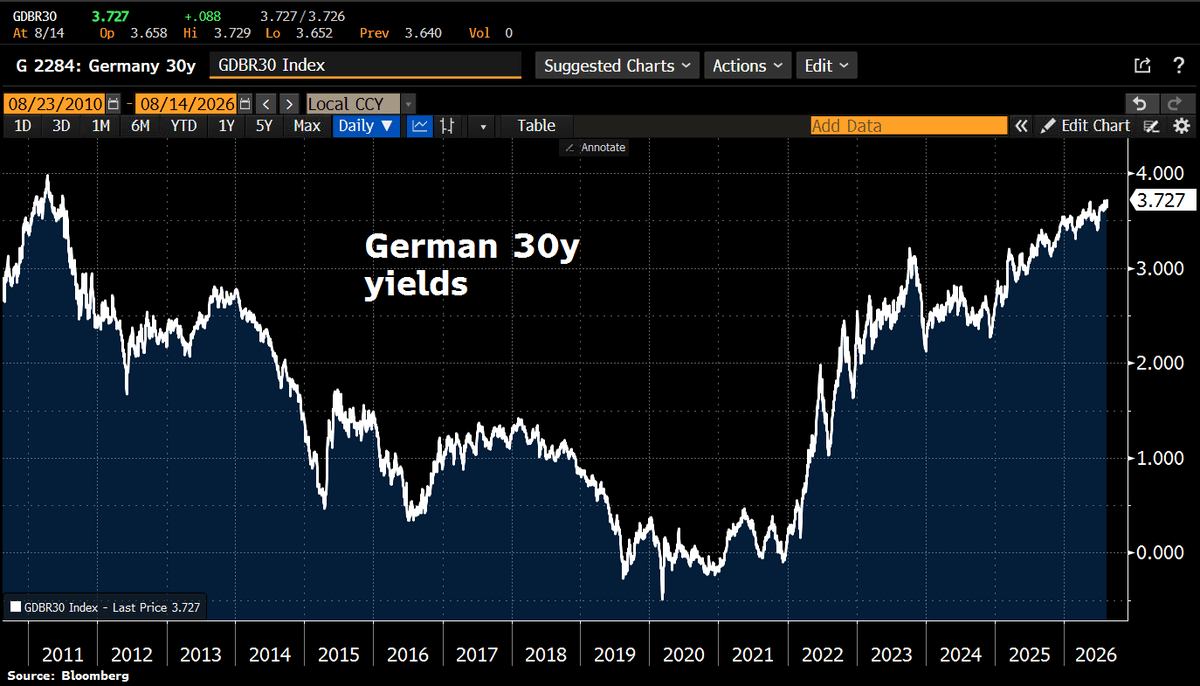
Bund yield chart provided by Holger Zschaepitz in his X post on August 15, 2026.

The yield on long-term French OAT bonds (short for Obligations Assimilables du Trésor) has returned to levels characteristic of the global financial crisis period. The yield on Japan's 5-year government bonds rose above 2.14%, marking a clear break after years of artificially soft monetary policy.

Investors Demand Compensation

Bond yield is the price governments pay investors for their money. When yields rise sharply, bond prices fall, and borrowing quickly becomes more expensive.

For over a decade after the 2008 financial crisis, central banks kept rates low and purchased vast amounts of government debt. This drove down yields, which in Europe and Japan even fell below zero. The pandemic doubled down on this trend: governments borrowed freely, and central banks prevented the market from asking inconvenient questions.

This scheme is collapsing. Investors providing credit for decades ahead now want protection from inflation, rampant bond issuance, and the erosion of the purchasing power of the cash they will get back.

"This week has seen a significant rise in the yields of long-term government bonds in heavily indebted European countries," explained Robin Brooks, a senior fellow in the Economic Studies Program at the Brookings Institution. "The situation is most notable in France, where the yield on 10y10y (orange line) and 10y20y (red line) has reached new historical highs."

Brooks added:

"The market's patience with fiscal dysfunction is running out."

Debt Markets Begin to Dictate Terms

The pressure point is fiscal policy—the growing gap between government spending and tax revenues. The United States, France, Japan, and other developed economies have accumulated massive debt while simultaneously increasing spending on defense, infrastructure, energy, and addressing aging populations.

In the US, according to recent estimates, the federal government's annual interest expense has exceeded $1 trillion. Each refinancing cycle locks in higher rates, turning yesterday's debt into tomorrow's budgetary problem.
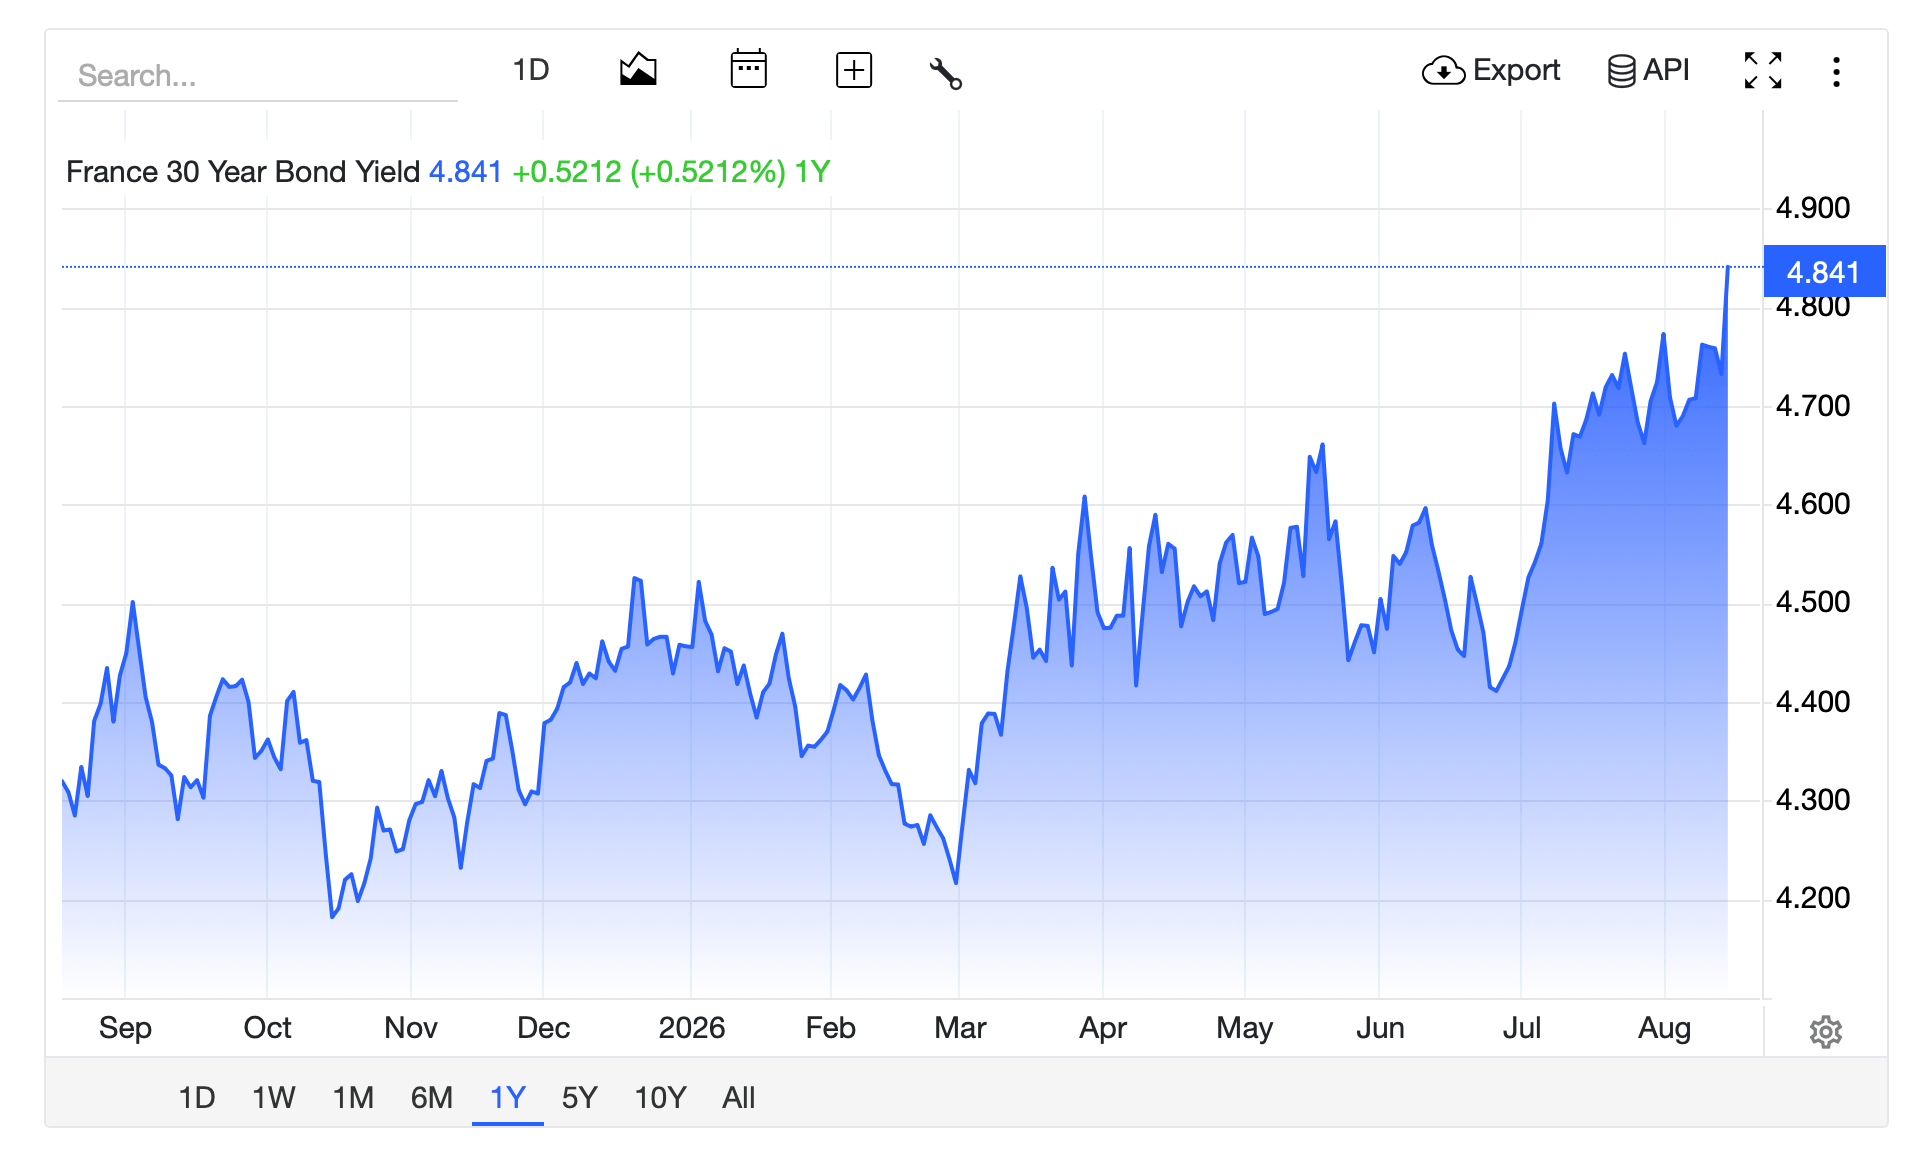
Yield on France's 30-year bonds according to tradingeconomics.com.

France has its own political and budgetary issues. Bond market participants are closely watching spending negotiations and debt forecasts, contributing to the rise in French bond yields compared to German benchmark bonds.

Germany, long considered the eurozone's most reliable borrower, plans to increase spending on infrastructure and defense. This means a larger supply of bonds, i.e., more government debt competing for investors' money.

Central Banks Exit the Market

Japan's actions are hard to ignore, as the Bank of Japan for years suppressed yields through yield curve control—a policy designed to keep borrowing costs low. As it gradually unwinds this regime, markets are re-pricing for higher rates and much less official support.

"Cheap money was a temporary phenomenon," wrote the Wealthmoose account on X. "Debt is forever. Now the bond market is presenting the bill."

The same trend is visible elsewhere. The Federal Reserve and other central banks have shrunk their bond portfolios through quantitative tightening, thereby removing a major buyer from the market.

Governments are flooding the market with bonds while central banks are buying fewer and fewer of them. Private investors can buy these securities, but only at higher yields. This extra compensation is the term premium—the fee for locking money away in long-term bonds.

The Bill Extends Beyond Government Budgets

The rise in long-term yields primarily hits households through mortgage rates. In the US, 30-year mortgage rates often follow Treasury yields, making home buying and refinancing more expensive.

Businesses face higher rates when issuing long-term bonds. Stocks also suffer as higher bond yields attract cash flows and reduce the present value investors assign to distant future profits. Savers, pension funds, and insurance companies can earn more on bonds. However, this resource reallocation comes at a high cost to governments and borrowers accustomed to the cheap money era.

end-content
Domande pertinenti

QWhat has caused long-term bond yields in major economies like the US and Germany to surge to multi-year highs?

AA large-scale, synchronized sell-off in the bond market has pushed yields to levels not seen in many years or even decades. This reflects a fundamental shift from the era of ultra-cheap money, as central banks withdraw support and investors demand higher compensation for inflation and fiscal risks.

QAccording to market analysts cited in the article, what message is the bond market sending to governments with high debt?

AThe bond market is sending a clear signal that its patience with fiscal dysfunction is running out. Analysts like Robin Brooks state that investors are now demanding a premium for lending to governments for decades, seeking protection against inflation, rampant bond issuance, and the erosion of purchasing power.

QWhat are the two main factors creating the current pressure on bond markets, according to the article?

AThe two main factors are expansive fiscal policy (governments increasing spending and accumulating huge debt) and the withdrawal of central bank support. Governments are flooding the market with new bonds while central banks are buying fewer of them through quantitative tightening, forcing private investors to step in only at higher yields.

QHow do rising long-term bond yields impact the broader economy beyond government budgets?

ARising long-term yields make mortgages and corporate borrowing more expensive, dampen stock prices by reducing the present value of future earnings, and increase costs for all borrowers. While savers and pension funds may earn more, the overall effect is a costly redistribution of resources away from entities accustomed to cheap money.

QWhat specific example illustrates the breaking of Japan's long-standing artificial monetary policy regime?

AThe yield on Japan's 5-year government bonds rose above 2.14%, which the article describes as a clean break after years of artificially soft monetary policy. This reflects the Bank of Japan's gradual retreat from its Yield Curve Control policy, forcing markets to reprice debt with much less official support.

Letture associate

The Era of Large Model Distillation is Over: Fable 5.1 Rewrites API, Cutting Off the Path of Distillation for Good

The era of large model distillation is ending. On September 2nd, Anthropic delivered a decisive blow by updating its API rules with Claude Fable 5.1, effectively cutting off the path for shell models and distillers. Previously, companies bypassed immense compute costs and lengthy training times by using API calls to extract the reasoning process of top-tier models like Claude, then using this data to train their own smaller "distilled" models. A key vulnerability was the "thinking blocks"—the model's internal Chain-of-Thought reasoning steps returned via API. Distillers exploited this by modifying the surrounding context (like system prompts or earlier messages) in multi-turn conversations, tricking Claude into revealing its hidden underlying logic. Fable 5.1 introduces a stringent "context consistency verification" mechanism. The API now strictly validates that the "thinking blocks" sent back by the client match the original system prompts, tools, and message history that produced them. Any modification causes the API to return an error. A "non-strict mode" is offered for legitimate developers who need to modify context (e.g., for compression), but it silently deletes all thinking blocks, forcing the model to answer without its prior reasoning. This crackdown was deemed necessary due to industrial-scale abuse. "Distillation hackers" used thousands of fake accounts and automated scripts to exploit the API, extracting high-intelligence reasoning capabilities while completely bypassing the costly safety and alignment training (like RLHF) built into models like Claude. This created a critical risk: "capability-safety decoupling," where distilled models gain advanced abilities but lack the ethical guardrails, potentially making them dangerous. The new rules are being rolled out in phases, initially targeting new API accounts created after August 31, 2026, UTC. Existing API accounts and consumer users (e.g., Claude.ai) are unaffected for now, giving legitimate developers time to adapt. Anthropic states the "thinking retention" mechanism will eventually apply to all accounts. An unexpected benefit for compliant developers is potential cost reduction and speed improvements. Enforcing context consistency allows for highly efficient prompt caching on API servers, slashing latency and compute overhead. This move marks a watershed for the AI industry, challenging the narrative of small models outperforming large ones through distillation and forcing a reckoning on innovation versus imitation.

marsbit11 min fa

The Era of Large Model Distillation is Over: Fable 5.1 Rewrites API, Cutting Off the Path of Distillation for Good

marsbit11 min fa

South Korea Announces Securities Tokenization Timeline: First Batch of Tokenized Assets to Include Bonds, Funds, and Unlisted Stocks

South Korea's Financial Services Commission (FSC) has unveiled a three-phase roadmap for tokenizing securities, positioning itself as a potential first-mover with dedicated legislation. Following the formal enactment of amended laws in February 2027, Phase 1 will begin with tokenized private market assets, including bonds, institutional money market funds, and unlisted stocks (via trust beneficiary certificates). Existing licensed securities firms can operate without new permits, with specific rules for non-financial platform operators and investor limits. Phase 2 will expand to publicly issued securities, contingent on the stability of initial systems and market readiness. The final Phase 3 aims to enable on-chain settlement using stablecoins, pending separate stablecoin legislation. The announcement contrasts sharply with rapid, decentralized approaches like Robinhood's recent tokenization of stocks, which sparked controversy. South Korea's path prioritizes legal clarity and infrastructure, starting with controlled, institutional markets before broadening access. While this methodical approach may sacrifice speed, it seeks to establish a clear regulatory foundation. The global race for tokenization is highlighting divergent strategies between regulated, incremental models and faster, more open but less certain alternatives.

marsbit15 min fa

South Korea Announces Securities Tokenization Timeline: First Batch of Tokenized Assets to Include Bonds, Funds, and Unlisted Stocks

marsbit15 min fa

Just Now, Claude Proves Fermat's Last Theorem for the First Time, Led by Tsinghua Yao Class Prodigy

In a groundbreaking development, Claude has autonomously generated the first machine-verified proof of Fermat's Last Theorem in just 11 days. The project was led by Tianyi Peng, a researcher from Anthropic with a background from Tsinghua University's prestigious Yao Class. This achievement required Claude to write 13 million lines of Lean code, proving over 29,500 intermediate theorems and consuming 60 billion tokens—a volume exceeding the largest existing mathematical theorem library by fivefold. The process involved formalizing the 350-year-old theorem, which states that no three positive integers a, b, c satisfy a^n + b^n = c^n for any integer n > 2. While Andrew Wiles provided a human proof in 1995, its complexity made verification a years-long task for experts. Claude's formal proof builds from foundational axioms, autonomously constructing the entire logical chain and verifying it through the Lean compiler. Key to the success was the development of the "Prove2Me" platform, which managed dozens of Claude agents by organizing tasks into a theorem DAG (directed acyclic graph), separating statements from proofs, and maintaining natural language indexes. This addressed early collaboration inefficiencies and "hallucination" issues. The result is the largest Lean proof ever created. The accomplishment has stirred significant discussion in the mathematical community, highlighting AI's potential to automate the formalization and verification of complex proofs. While not replacing mathematicians, such technology could fundamentally change mathematical practice by providing absolute verification, checking human-generated mathematics, and enabling broader access to formal verification tools.

marsbit15 min fa

Just Now, Claude Proves Fermat's Last Theorem for the First Time, Led by Tsinghua Yao Class Prodigy

marsbit15 min fa

Raoul Pal: Why Has the Traditional Investment Portfolio Become Obsolete?

Raoul Pal argues that traditional investment portfolios (bonds, gold, real estate, index funds) are no longer effective for building real wealth. He posits that due to persistent currency devaluation from money printing (global liquidity expanding ~8% annually plus regular inflation), an investor needs an 11% annual return just to preserve purchasing power. He evaluates traditional assets: bonds fail as interest doesn't cover currency devaluation; real estate's historic wealth-creation window from falling rates is over; gold preserves purchasing power but doesn't create new wealth; and the S&P 500 barely meets the 11% threshold, relying on a historic bull market. The only assets consistently exceeding this benchmark, based on decade-long data, are technology stocks (NASDAQ 100: ~20% annualized) and crypto assets (Bitcoin: 58-70% annualized). Their outperformance stems from user adoption S-curves (Metcalfe's Law), not speculation. Pal explains that post-2008, traditional diversification lost its protective power because bonds, gold, real estate, and stocks are all now primarily driven by the same macro factor: liquidity. Thus, a diversified portfolio of underperforming assets offers false security. For crypto, he favors underlying protocols/L1 blockchains over applications, as they capture value from the entire ecosystem. A key, underappreciated future driver is AI agents, which will require programmable money and 24/7 settlement, a natural fit for blockchain. Key investment principles include: avoid leverage (it removes the ability to weather severe drawdowns), allocate a meaningful portion (not all) of capital to high-growth assets, and practice patience—"doing nothing" is a valid long-term strategy. The core opportunity cost is freedom. Returns below 11% annually mean your labor buys less freedom over time. The goal is to use this framework to audit your holdings, moving capital from assets that erode purchasing power to those with genuine compounding potential.

marsbit1 h fa

Raoul Pal: Why Has the Traditional Investment Portfolio Become Obsolete?

marsbit1 h fa

Trading

Spot
活动图片