Morgan Stanley Report Analysis: PE Giants Eye Workday, Software Stocks' Valuations Already Cheap Enough to Tempt Buyers

marsbitPublicado a 2026-08-18Actualizado a 2026-08-18

Resumen

In a report titled "MStanley Software QuickTake: A Signal to Watch" dated August 16, analysts at Morgan Stanley discuss potential shifts in the software sector, highlighted by rumors of Silver Lake's interest in acquiring Workday. A deal of this scale, valuing Workday at approximately $50 billion, could signal a turning point for private equity (PE) interest. The analysts note that even with a 30-40% premium, the acquisition multiple (around 5x 2027 P/S and 16x 2027 FCF) would be below historical averages, suggesting software valuations may have become attractive enough for PE to re-engage. The report explores two key areas. First, the dynamic of open-source large language models is creating price stratification, putting pressure on token prices but not necessarily destroying the return on invested capital for major cloud providers, which could remain between 20-60%. Second, a survey of over 150 investors shows a divided but cautiously optimistic short-term view on software stocks, with expectations for greater price dispersion within the sector. The analysis also touches on specific companies: Netcompany, despite strong revenue growth, faces free cash flow challenges, while the potential acquisition of Cursor by SpaceX is seen as strategically valuable due to its position in the AI-assisted development workflow layer. Overall, the combination of potential PE activity, AI pricing dynamics, and a gradual recovery in investor sentiment points to software sector valuations pot...

By: Rita

Reuters reports that PE giant Silver Lake is in talks to acquire Workday, and the software sector surged collectively on the last trading day of last week.

In a software snapshot released on August 16, Morgan Stanley viewed this rumor as a significant signal for software sector valuations. Workday, with a market cap of around $50 billion, is a global giant in human capital management and financial management software. If the deal goes through, it would be one of the largest software privatization deals in recent years. Morgan Stanley's U.S. software analyst Adam Wood pointed out that even calculated with a 30% to 40% premium, the acquisition valuation is only about 5 times the 2027 price-to-sales ratio and about 16 times the 2027 free cash flow, both below historical averages. Software stocks may already be cheap enough for PE to consider re-entering the market.

PE Returns to Software Acquisitions

There have been very few privatization deals in the software industry over the past year.

Morgan Stanley believes that tight credit conditions and ongoing debates around AI have dampened deal confidence. The only noteworthy recent case in the European market was the expression of interest by Ridgeview Partners in acquiring UK's Pinewood Technologies for around £500 million at the end of July. A Workday deal would be on a completely different scale.

Morgan Stanley's analysis unfolds on two levels: In an optimistic scenario, this deal could reignite PE confidence in software investments, triggering short covering and driving a valuation recovery for software stocks. Silver Lake has already indicated with action that the current price level is attractive. Conversely, even at a premium, the multiples remain below historical averages, also indicating that software stock valuations have compressed to levels worth attention.

Morgan Stanley expects that if the deal is officially announced, the software sector will experience a round of valuation re-rating. Short covering and the market's correction in recognizing "these businesses are already too cheap" could drive the overall software sector higher.

Open Source Models Depress Token Prices, But Don't Destroy ROIC

Another variable worth noting comes from the pricing dynamics of open-source weight models.

Morgan Stanley's Head of Thematic and Sustainability Research, Stephen Byrd, noted that open-source weight models are delivering tangible returns on investment and cost savings for users. Chinese model prices are rising as suppliers start to focus more on commercialization; U.S. suppliers are still cutting prices, especially for mid- to low-tier models. A price stratification is forming: cheap models support high-volume or simple tasks, while high-end models continue to serve complex enterprise workflows.

The impact of this stratification on hyperscalers: Open-source models will put pressure on token prices, but analysis by Morgan Stanley's internet research head, Brian Nowak, shows that even under price-cut assumptions, hyperscalers can still maintain a return on invested capital of about 20% to 60% on their own computing power. A price war does not necessarily destroy the profitability of AI for cloud giants.

Investor Divergence on Software Stocks Widens, But Bulls Outnumber Bears

Morgan Stanley surveyed over 150 investors during this week's webinar on "Buying the AI Dip."

When asked "Is the recent rally in previously 'disrupted' sectors like software and business services sustainable," 52% of respondents believed greater price differentiation would emerge within the sector. Approximately 28% of investors considered the rally sustainable, while about 15% deemed it unsustainable. Bulls outnumbered bears by nearly two to one.

The survey shows the market is not uniformly bullish, but the short-term bias for software stocks is overall positive. Divergent expectations mean stock-picking ability will be more important than beta.

Netcompany and Cursor Send Different Signals

Danish IT services company Netcompany reported Q2 revenue exceeding expectations, with organic growth of around 17%, significantly outperforming the industry. However, Morgan Stanley focused more on earnings quality. Free cash flow was cumulatively negative DKK 192 million over the past six quarters, compared to adjusted net profit of DKK 935 million for the same period. While this is mainly attributed to phasing impacts of certain EU and Greek projects, the key is whether FCF can turn positive in the second half of the year. Based on Thursday's closing price, Netcompany trades at about 49 times its 2026 free cash flow multiple and about 19 times its 2027 multiple. Morgan Stanley maintains an Underweight rating.

Regarding Cursor, Morgan Stanley's global Embodied AI & Robotics strategist, Adam Jonas, provided an in-depth analysis of SpaceX's all-stock acquisition of Cursor for $60 billion. Cursor, as an AI-assisted software development "workflow layer," routes coding tasks between third-party frontier large language models and its own Composer model. It is already used by over 50,000 enterprises, covering more than 64% of the Fortune 500. Morgan Stanley expects Cursor's annualized recurring revenue to reach $8 billion by year-end and $33 billion by 2030. Within the SpaceX ecosystem, Cursor holds a core position at the "Data & Deployment" layer. As code generation becomes commoditized, value will accumulate in this layer. Morgan Stanley's $33 billion revenue forecast for 2030 does not yet factor in any synergies.

The return of PE to software acquisitions, the cost stratification from open-source models, and the mild repair of investor confidence—three signals point in the same direction: software sector valuations have compressed to a critical point. Morgan Stanley believes the true significance of the Workday deal lies not in Workday itself, but in the fact that it may mark a turning point in PE's attitude towards software assets.
Disclaimer: This article is an adaptation and interpretation of a third-party brokerage research report (Morgan Stanley, August 16, 2026) by Chaoxiang Research, combined with the compilation of public market information. The ratings, target prices, earnings forecasts, and related judgments cited are the views of the analyst from that brokerage firm, representing only the stance of their institution. They do not represent the views of Chaoxiang Research and do not constitute any investment advice. The market carries risks; decisions must be independent. This article should not be used as a basis for trading any securities.

Preguntas relacionadas

QWhat is the main reason Morgan Stanley believes the reported talks about Silver Lake acquiring Workday are a significant signal for the software industry?

AMorgan Stanley views the talks as a significant signal because even with a 30-40% acquisition premium, the implied valuation would be below historical averages (approximately 5x 2027 P/S and 16x 2027 FCF), suggesting software stock valuations have compressed to a level attractive enough for private equity to re-engage.

QAccording to Morgan Stanley's analysis, how do open-source weight models affect AI token pricing and the return on invested capital (ROIC) for hyperscalers?

AOpen-source weight models are putting downward pressure on AI token prices. However, Morgan Stanley's analysis indicates that even under price decline assumptions, hyperscalers running models on their own infrastructure can still maintain an ROIC ranging from approximately 20% to 60%, meaning a price war does not necessarily destroy their AI profitability.

QWhat was the key takeaway from Morgan Stanley's survey of over 150 investors regarding the sustainability of the rebound in software stocks?

AThe key takeaway is a divergence in views but a generally positive bias. While 52% of respondents believed greater price dispersion within the sector would occur, 28% thought the rebound was sustainable versus only 15% who thought it was not, making bullish investors nearly twice as numerous as bearish ones.

QWhy did Morgan Stanley maintain a 'Reduce' rating on Danish IT services company Netcompany despite its better-than-expected Q2 revenue?

AMorgan Stanley maintained a 'Reduce' rating due to concerns over profit quality. Netcompany's free cash flow has been negative for six consecutive quarters (cumulatively -192m DKK), significantly diverging from its adjusted net profit of 935m DKK over the same period, even though this is attributed to specific project timing.

QWhat role does Morgan Stanley assign to Cursor within SpaceX's ecosystem following its acquisition, and what is the firm's 2030 revenue forecast for Cursor?

AWithin SpaceX's ecosystem, Morgan Stanley positions Cursor at the core of the 'Data & Deployment' layer. The firm expects value to accrue to this layer as code generation becomes commoditized. Morgan Stanley forecasts Cursor's annual recurring revenue to reach $33 billion by 2030, a figure that does not yet include any potential synergies from the acquisition.

Lecturas Relacionadas

Japan is dragging the world down with it

Japan's 10-year government bond yield surpassed 3% for the first time since 1996. According to a Nomura Research Institute report, the primary driver of this global rise in long-term interest rates is Japan's domestic factors, not external influences. A key contributor is the heightened risk premium due to concerns over Japan's deteriorating fiscal situation, which outweighs the impact of inflation expectations and monetary policy shifts. The report identifies three main factors behind the yield surge: expectations of Federal Reserve rate hikes, anticipation of a Bank of Japan policy rate increase, and significant risks from Japan's expanding fiscal budget. Notably, fiscal risk premiums are the largest single factor pushing yields higher. The Trump administration has unusually intervened in Japan's economic policy, urging both monetary tightening and fiscal consolidation. This move aims to mitigate potential global negative spillovers from a weak yen and rising Japanese bond yields. Nomura warns that this Japan-originated rise in global long-term rates poses systemic risks. It could increase government debt servicing costs, destabilize financial institutions' balance sheets, and depress risk asset prices, particularly in real estate and equities. Tech and AI-related stocks, being highly sensitive to interest rates, could see a significant cooling-off in investment enthusiasm. This scenario might trigger not just a gradual economic slowdown but a sudden deceleration, explaining the U.S. administration's direct intervention.

marsbitHace 4 min(s)

Japan is dragging the world down with it

marsbitHace 4 min(s)

Meme Launch Platform Battlefield: Pons Overtakes Pump.fun in Two Months, Who's Next?

The meme token launch platform war is intensifying. While Pump.fun has long dominated Solana, a new challenger, Pons, has rapidly emerged on the recently launched Robinhood Chain (an Arbitrum Orbit L2). Within two months, Pons achieved a daily protocol fee of over $6.33 million, briefly surpassing Pump.fun. Robinhood Chain's low gas fees and incentives fueled this growth, also enabling platforms like LONG, which pairs meme tokens with tokenized stocks. The competition for the "right to launch tokens" is heating up across all chains. On Solana, LetsBONK.fun and Raydium's LaunchLab challenge Pump.fun. On Base, Zora enables creator-specific tokens, while platforms like Believe experiment with social token minting. On Robinhood Chain itself, Uniswap's zero-fee Pools.trade directly competes with Pons, demonstrating a trend towards making token launches a free, commoditized service. Nearly all these platforms have issued their own governance or fee-sharing tokens, often using "buyback and burn" mechanisms to support prices. However, their value is tied to sustained platform fees, and regulatory risks loom. The new U.S. SEC "crypto asset regulations" pose questions about whether these centralized platforms can achieve a "safe harbor" by proving decentralization. The real test for these platforms, beyond explosive growth, is which will survive the eventual market downturn. As the article concludes, "When the right to launch becomes free, survival is what you charge for."

marsbitHace 17 min(s)

Meme Launch Platform Battlefield: Pons Overtakes Pump.fun in Two Months, Who's Next?

marsbitHace 17 min(s)

Zhejiang University's Female Professor is About to Go Public in Hong Kong

A Zhejiang University professor is heading to the Hong Kong IPO market. Xiong Rong, a professor at Zhejiang University's College of Control Science and Engineering, is the founder and driving force behind GIAZ Intelligent Technology Co., Ltd., which recently filed for a listing on the Hong Kong Stock Exchange's main board under Chapter 18C. Xiong's journey began in 2001 when she and her students built Zhejiang University's first soccer robot. Over the next decades, she led teams to multiple world championships. In March 2026, she was recognized by the International Federation of Robotics as one of 11 women shaping the future of robotics, the only Chinese individual on the list. In 2016, leveraging years of academic research, Xiong co-founded GIAZ Intelligent Technology in Hangzhou with several students. The company initially explored various robotics applications before focusing on Autonomous Mobile Robots (AMRs) for industrial logistics, seeing greater value in manufacturing upgrades. GIAZ's first commercial AMR product launched in 2018. The company has since expanded its product line to include outdoor robots and heavy-duty models. The startup has attracted significant investment, including from ByteDance's Qiantiao Capital, Lenovo Capital, and Shenzhen Capital Group. Its post-money valuation reached 2.13 billion yuan in early 2026. Financially, GIAZ reported revenue of 169 million yuan for the first half of 2026, an increase of 25% year-on-year, with AMR solutions comprising 87.3% of total revenue. GIAZ joins a wave of robotics companies seeking IPOs in 2026. Over 50 robotics-related firms are reportedly queuing for listings in Hong Kong, marking a potential exit milestone for investors who backed the sector a decade ago. However, the public market presents new challenges, shifting focus from technological potential to profitability, supply chain management, and sustainable commercial scaling. The performance of recent robotics IPOs has been mixed, indicating that listing is not a guarantee of success in this capital-intensive and competitive field.

marsbitHace 19 min(s)

Zhejiang University's Female Professor is About to Go Public in Hong Kong

marsbitHace 19 min(s)

Goldman Sachs Research Report: Cryptocurrency Market Cap Rises 34% in Q3, Profit Forecasts and Price Targets for Brokers and Crypto Stocks Revised Upward

Goldman Sachs Research Report Update: Crypto Market Cap Surges 34% in Q3, Boosting Revenue Forecasts for Brokers & Crypto Stocks Goldman Sachs has raised revenue and price targets for covered brokers and crypto-related companies, citing a 34% increase in the total crypto market capitalization quarter-to-date (QTD) in Q3. The firm's updated analysis, published on September 8, led to a 10% average upward revision in Q3 revenue expectations for the coverage group. While overall trading volumes remain below Q2 levels (down 8% QTD), an August rebound of 16% showed marginal improvement. The market cap appreciation drives revenue through multiple channels beyond direct trading: higher custody and staking fees linked to asset values, and increased stablecoin revenue tied to stablecoin market capitalization. Consequently, Goldman raised its median 2026 EPS estimate by 1% and increased the median target price-to-earnings (P/E) multiple by 3.0x to 32.5x, resulting in a median total return expectation of +3% for the group. Key individual adjustments include raising Coinbase's (COIN) price target to $219 (Buy) from $196, reflecting a 7% increase in assumed platform assets and a 9% rise in expected Q3 trading volume. Similar target price increases of 12-14% were applied to other covered stocks like ETORO, Galaxy Digital (GLXY), BitGo (BTGO), and Circle (CRCL), with ratings largely maintained at Neutral. The report highlights that companies with diversified revenue streams from custody, staking, and stablecoins are better positioned to benefit from market cap growth, partially insulating them from ongoing trading volume softness, which remains a key variable for transaction fee-dependent platforms.

marsbitHace 20 min(s)

Goldman Sachs Research Report: Cryptocurrency Market Cap Rises 34% in Q3, Profit Forecasts and Price Targets for Brokers and Crypto Stocks Revised Upward

marsbitHace 20 min(s)

BiyaPay Market Observation|US Stocks Pull Back, Intel and AMD Surge Against the Trend, Has the AI Chip Rally Shifted Focus?

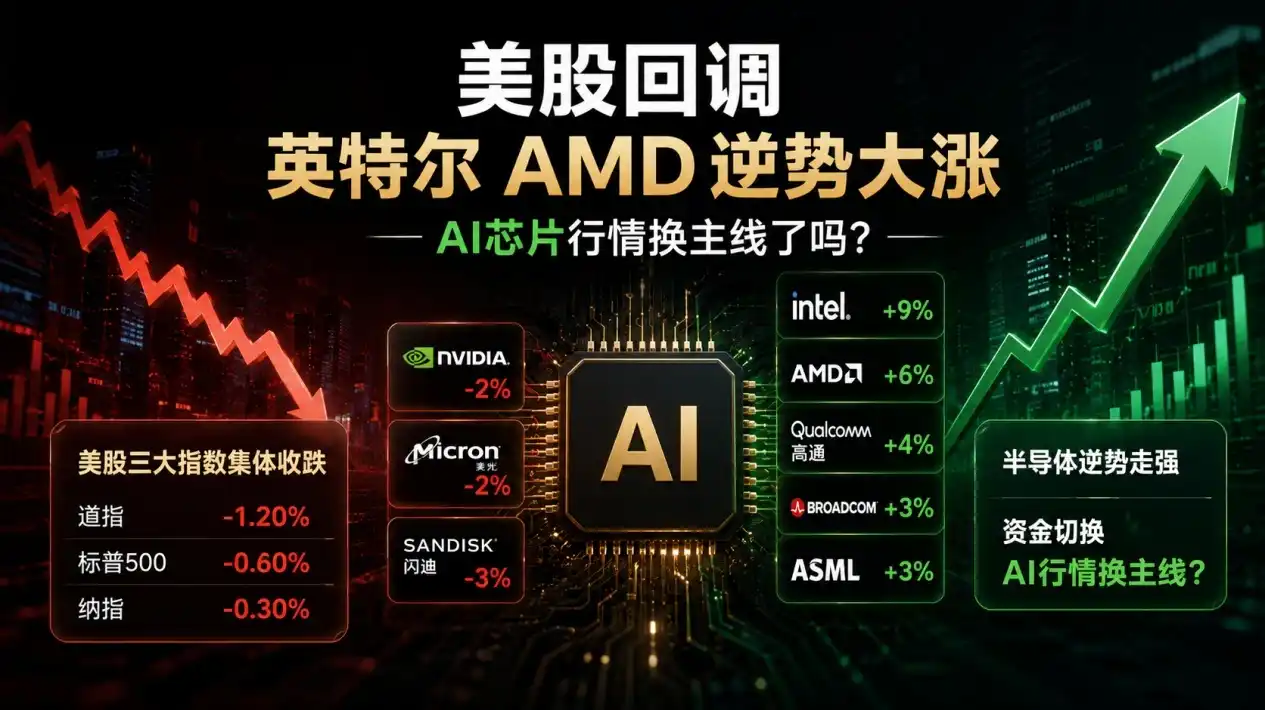
BiyaPay Market Observations: US stocks experienced a general pullback, with major indices closing lower on September 8th. However, a notable divergence emerged within the semiconductor sector: Intel surged around 9% and AMD rose nearly 6%, while NVIDIA declined about 2%. This suggests capital is not exiting the AI and chip theme but rotating within the sector. The rotation comes amid macro pressures from rising oil prices and Treasury yields, which increase inflation concerns and pressure equity valuations. In this environment, investors are becoming more selective, shifting focus from high-flying pure-play AI stocks towards companies with clearer near-term profit recovery or new growth narratives. Intel's rally was sparked by reports of potential CPU price hikes, signaling a reassessment of its pricing power and potential profitability recovery within the broader AI infrastructure build-out. Qualcomm gained after announcing a multi-generational collaboration with Amazon for AI data center chips, opening a potential new growth avenue beyond mobile. AMD's rise appears tied to the overall positive sentiment towards alternative AI chip plays. This movement indicates the AI investment theme is maturing. The narrative is evolving from a singular focus on market leaders to a more nuanced, multi-faceted evaluation of the entire supply chain. Key factors to watch include upcoming US CPI data, the Federal Reserve's policy meeting, and further validation of order momentum and financial execution from these semiconductor companies. The core question remains which firms can convincingly translate AI investments into sustained cash flow.

marsbitHace 23 min(s)

BiyaPay Market Observation|US Stocks Pull Back, Intel and AMD Surge Against the Trend, Has the AI Chip Rally Shifted Focus?

marsbitHace 23 min(s)

Trading

Spot
活动图片