US Stocks Are at an Extremely Fragile Moment as Earnings Season Kicks Off

marsbit发布于2026-07-11更新于2026-07-11

文章摘要

U.S. stocks are entering a high-stakes earnings season amidst what analysts describe as an "extremely fragile" market environment. While major indices show subdued volatility, underlying pressures from geopolitics, monetary policy expectations, and mixed credit market signals are building. UBS's proprietary "Turbu-lens" market fragility indicator has reached 0.9, its highest level since September 2025, historically a precursor to a sharp spike in the VIX volatility index. The risk is amplified by elevated earnings expectations. Analysts project robust profit growth for Q2—24% for the S&P 500 and 12% for the Stoxx 600—but recent upward revisions mean disappointment could trigger outsized market moves. Current low VIX levels are seen as misleading and temporary, with the earnings season likely to push volatility higher. Market internals reveal significant stress, with single-stock volatility exceeding index volatility by more than threefold. This divergence suggests a potential convergence that could drive a sharp rise in index-level volatility. Given likely continued sector rotation, UBS suggests single-stock options may offer better tactical hedging opportunities than broad index hedges. Further pressures stem from rising oil prices, which threaten to keep inflation and interest rate expectations elevated, and a cautious credit market where CDS spreads have not confirmed the equity rally's strength. For investors, UBS recommends focusing on pair-wise correlation trades to ...

By: Zhang Yaqi, Wall Street News

Volatility at the index level for US stocks appears calm on the surface, but internal pressures are building. Under the triple constraints of geopolitical tensions, monetary policy expectations, and signals from the credit market, market fragility has climbed to a multi-year high—and a high-expectation, high-risk earnings season is now kicking off.

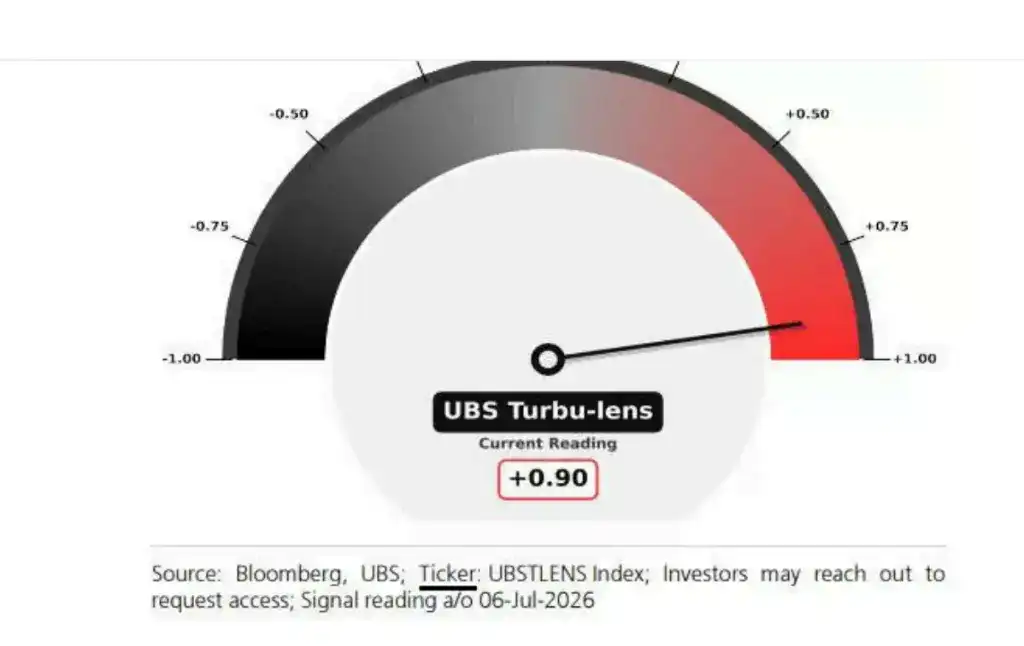
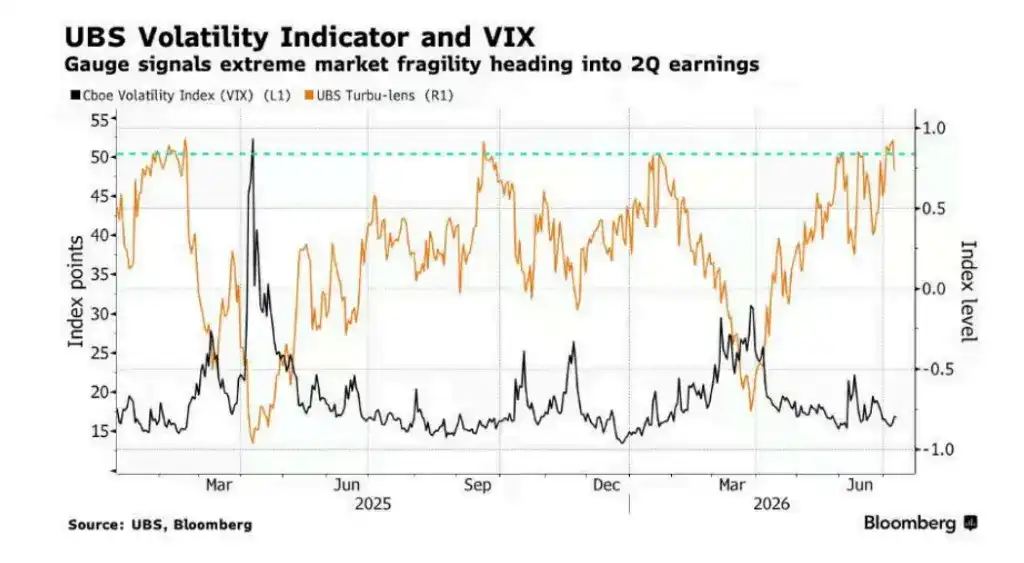
The "Turbu-lens" market fragility indicator from UBS's derivatives strategy team currently reads 0.9 (on a scale from -1 to 1), its highest level since mid-September 2025. Historically, such readings have often preceded a sharp, phased increase in the VIX. UBS derivatives strategist Maxwell Grinacoff's team warns that this indicator points to "extreme market fragility" just as earnings season begins. Meanwhile, the team also noted that if systematic strategies fully add leverage, the reading "could truly touch +1".
High market expectations are further amplifying risks. Analysts expect Q2 earnings growth for S&P 500 index components to be as high as 24%, and 12% for the Europe STOXX 600. Unlike previous earnings seasons, analysts have persistently raised forecasts ahead of the reporting period, a confidence so strong that it conversely implies greater room for adjustment if results disappoint the market.
The VIX is currently at low levels, but this calm is deceptive. Barclays strategist Anshul Gupta's team points out that the recent decline in the VIX coincided with a seasonal calendar window where price volatility typically narrows, representing a "short-lived sweet period" with limited persistence. The onset of earnings season could push the VIX higher again.

More noteworthy is that the subdued index volatility masks extreme divergence within the market—single-stock volatility has exceeded index volatility by more than threefold. Grinacoff noted that the probability of this gap narrowing during the summer is high, at which point either monetary policy repricing or geopolitical disruptions could trigger a sharp spike in index-level volatility.

Regarding hedging strategies, as dispersion trading and sector rotation may persist over the coming weeks of the earnings period, index-level hedging might be limited in its effectiveness. Grinacoff suggests, "Single-stock options perhaps offer better opportunities on a tactical level."
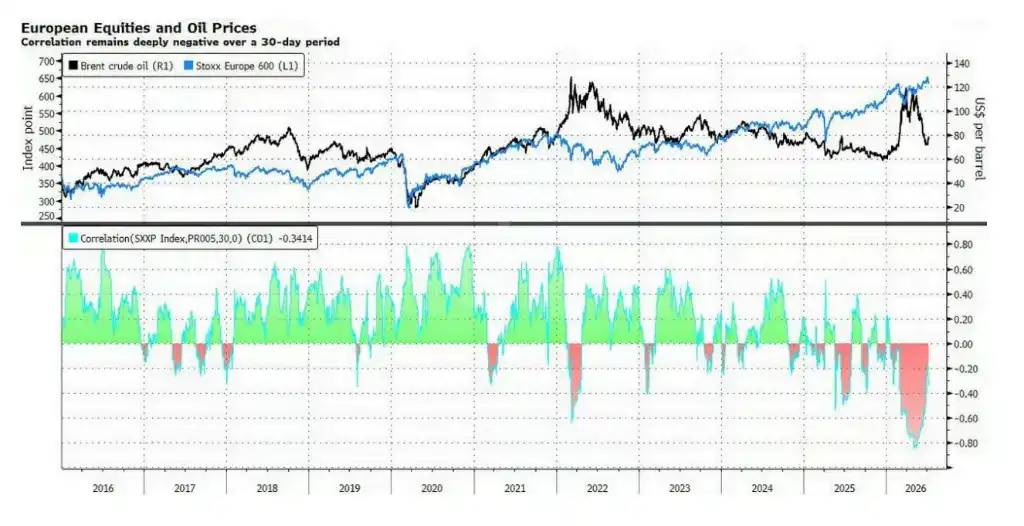
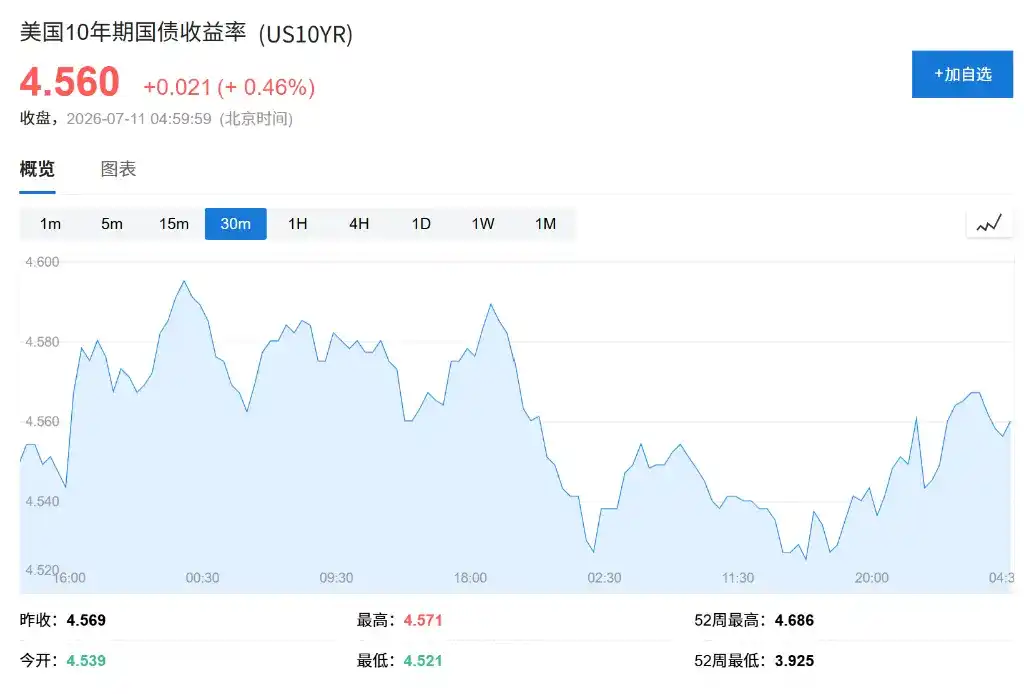
Oil price volatility driven by geopolitical tensions is creating persistent pressure on global equity markets. Brent crude has climbed to just below $80 per barrel, a move that could keep inflation expectations elevated and the Federal Reserve on the sidelines. While expectations for rate hikes saw limited change following the release of the Fed meeting minutes, the 10-year Treasury yield has quietly risen to around 4.6%. Rising bond market volatility is sending a negative signal to global equity markets, or at least capping further upside potential.
Strategists at Citi (including Alice Zheng) noted that current market positioning for higher oil prices is skewed, with Europe being particularly vulnerable—due to its high reliance on imported energy and lower exposure to AI-benefiting assets. "If the oil rally continues, the pullback in European equities could be quite significant, given the market had already largely priced in expectations for the conflict to end," the strategists wrote.

Performance in the credit market sounds a cautionary note for the current equity market upward momentum. Compared to the stock indices' previous surge to record highs, the narrowing of credit default swap (CDS) spreads has been quite limited; the credit market has not fully endorsed the equity rally. As equities have pulled back recently, the two have realigned, but analysts believe that to support a more robust equity market advance, clearer tightening signals from the credit market are needed.

Facing the above risks, UBS recommends investors capture stock-specific volatility opportunities through pair-wise correlation trades. In terms of sectors, UBS believes the Technology, Energy, and Financial sectors in the US market are most suitable for setting up pair-wise volatility trades, while in Europe, the Energy, Technology, and Consumer Discretionary sectors are recommended.

相关问答

QWhat does the UBS derivatives strategy team's 'Turbu-lens' market vulnerability indicator currently read, and what is its significance?

AThe 'Turbu-lens' market vulnerability indicator from the UBS derivatives strategy team currently reads 0.9 (on a scale of -1 to 1), its highest level since mid-September 2025. This reading points to 'extreme market vulnerability' and historically, such readings have often preceded a sharp, near-term spike in the VIX volatility index.

QWhat is notable about current analyst earnings growth expectations for the upcoming reporting season?

AAnalysts have high earnings growth expectations, with estimates at 24% for S&P 500 constituents and 12% for the European Stoxx 600. Notably, analysts have continued to raise their forecasts right up to the reporting period. This strong confidence means there is greater potential for market disappointment and sharper adjustments if the actual results fall short.

QWhy is the current low level of the VIX considered potentially misleading?

AThe current low VIX level is considered misleading because its recent decline coincided with a seasonal calendar window where price volatility typically narrows, creating a 'brief sweet spot' that is unlikely to last. Furthermore, the article notes that the start of earnings season could be a catalyst that pushes the VIX higher again.

QAccording to the article, what risk does rising oil price volatility pose, particularly to European stocks?

ARising oil price volatility, with Brent crude moving near $80 per barrel, could keep inflation expectations elevated and keep the Federal Reserve on hold. European stocks are seen as particularly vulnerable because Europe is highly dependent on imported energy and has lower exposure to AI-beneficiary assets. A sustained oil price rise could lead to a significant correction in European markets.

QWhat trading strategy does the article suggest might be more effective for hedging during this reporting season?

AThe article suggests that due to continued dispersion and sector rotation expected during the earnings period, index-level hedging may have limited effectiveness. Instead, UBS strategist Maxwell Grinacoff suggests that 'single-stock options might offer better opportunities at a tactical level.' The article also mentions 'pair-wise correlation trades' to capture volatility opportunities at the individual stock level.

你可能也喜欢

Ripple首席执行官布拉德·加林豪斯敦促参议院支持《清晰法案》,称谈判“非同小可”

Ripple首席执行官布拉德·加林豪斯在参议院即将对《CLARITY法案》进行投票前发声支持该加密市场监管框架,并强调为达成这一两党法案所做出的政策妥协“并非小事”。 加林豪斯支持美国财政部长斯科特·贝森特推动该法案的最新努力,敦促参议院在9月15日关键投票前推进此项加密市场结构法案。贝森特指出,最终草案强化了政府保持美国在数字技术领域竞争力同时保护社区银行的目标,并提及财政部长被赋予了新权力,以应对稳定币可能引发损害社区银行的存款外流情况。 加林豪斯引用贝森特的声明并补充说,最新的《CLARITY法案》不应被简单地视为妥协的产物,而是政策制定者为达成目标进行了实质性交易的结果。他呼吁参议员们不要仅仅将这项立法视为勉强接受的东西,而应作为一项值得支持的协议予以通过。 此次表态之际,参议院共和党人发布了经修订的《CLARITY法案》版本,其中包含了民主党人要求的126处重大修改。参议院计划于美国东部时间下午2:15就推进该法案的程序动议进行投票,这将决定法案能否进入辩论环节。修订文本包含了新的道德条款、州检察长的执法权力以及针对稳定币和金融稳定问题的措施。 与此同时,XRP价格近日有所上涨,交易价格接近1.42美元。

TheNewsCrypto3小时前

Ripple首席执行官布拉德·加林豪斯敦促参议院支持《清晰法案》,称谈判“非同小可”

TheNewsCrypto3小时前

交易

现货
活动图片