In the previous two articles, "From Supporting Role to Star: How AI Inference Gives NAND a 'Game-Changing' Makeover?" and "NAND's Inherently 'Prolific' Nature: How Does SanDisk Maintain 80% Gross Margin?", Dolphin Analyst noted: AI is not only lifting NAND demand to a new level but also has the potential to break its longstanding "silicon cycle" destiny.
Under the new logic dominated by inference workloads, NAND has shifted from a "peripheral data warehouse" to a "necessary component on the compute path." With the transition from training to inference and long-context scenarios, today's SSD has become a "Token battery" storing computing power.
This article follows this main thread to answer two questions:
1. How long can this wave of "super boom" price increases last?
2. Standing at the current valuation node, does the reborn SanDisk still have upward potential?
Detailed analysis is as follows:
1. How Long Can This Wave of Price Increase 'Super Boom' Last?
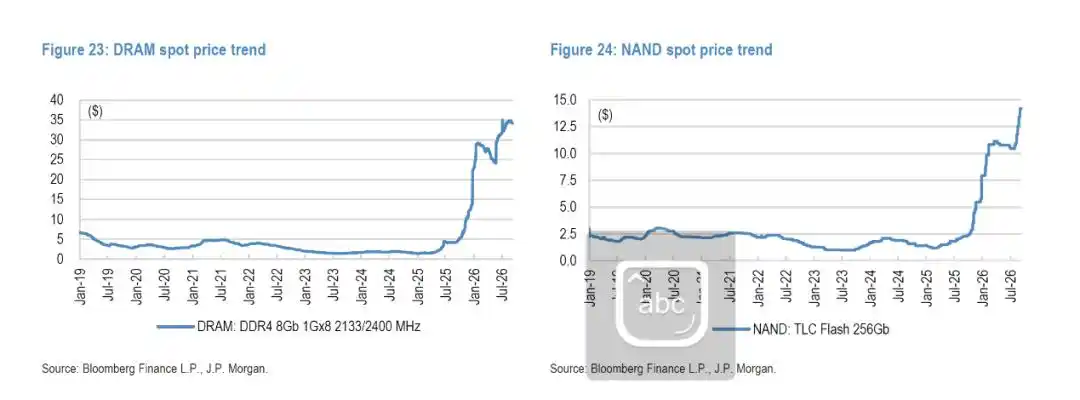
From an industry perspective, this round of price hikes is a "super boom" seen once in decades for the memory industry: Over more than a year since July 2025, the spot price of DDR4 8Gb has risen 7-8 times, from about $4.5 to about $35; NAND is similarly astonishing, with the 256Gb TLC spot price rising from about $2.5 to about $14, a 5~6 fold increase from the starting point.
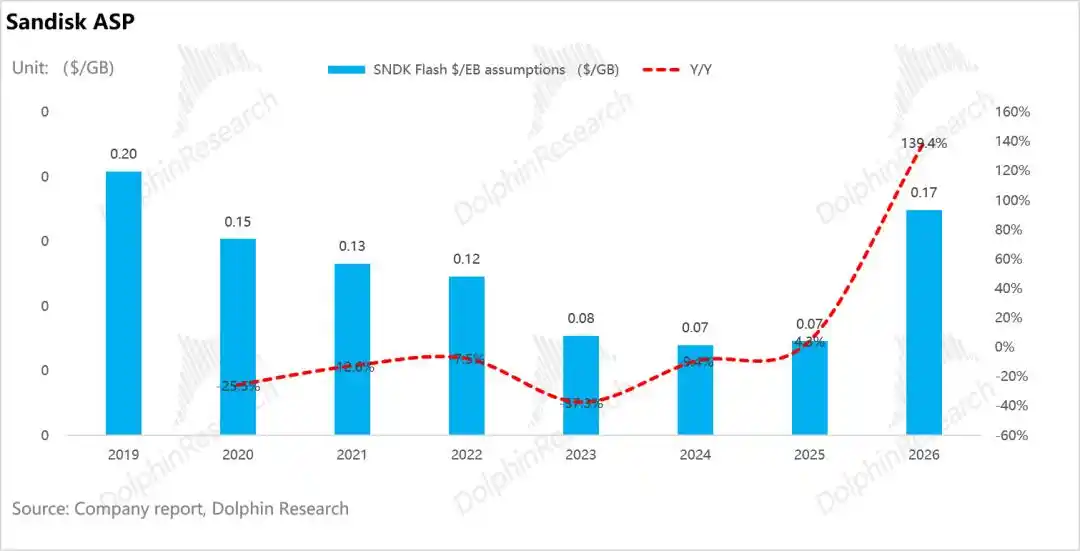
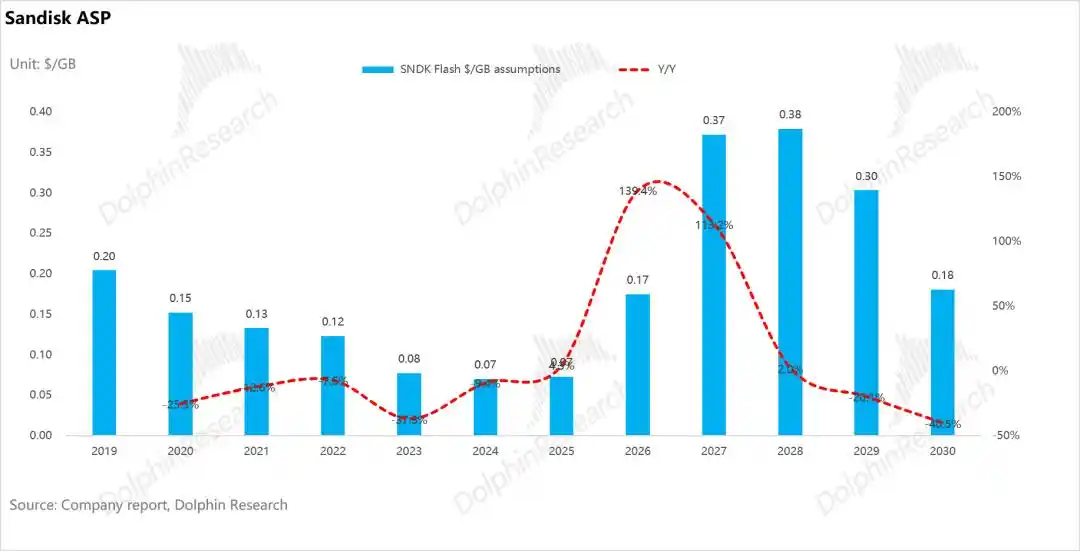
Calculations estimate SanDisk's FY26 (ending June 2026) blended ASP at about $0.17/GB, a year-over-year increase of about 139%, but significantly lower than the spot price increase. This is mainly due to limited price increases in the first half of the fiscal year, SanDisk's higher proportion of long-term agreements (LTAs), and the data center segment share rising to only 25% and 33% in FY26Q3 and Q4 respectively.
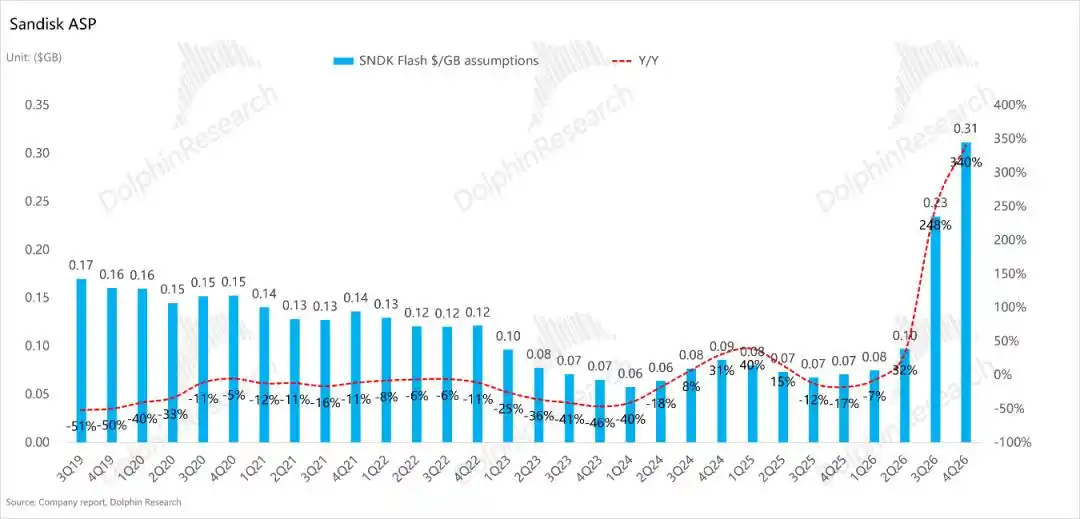
On a quarterly basis, FY26Q4 ASP was about $0.31/GB, a year-over-year increase of about 340%, basically catching up with the concurrent spot price (about $0.33~0.34/GB).
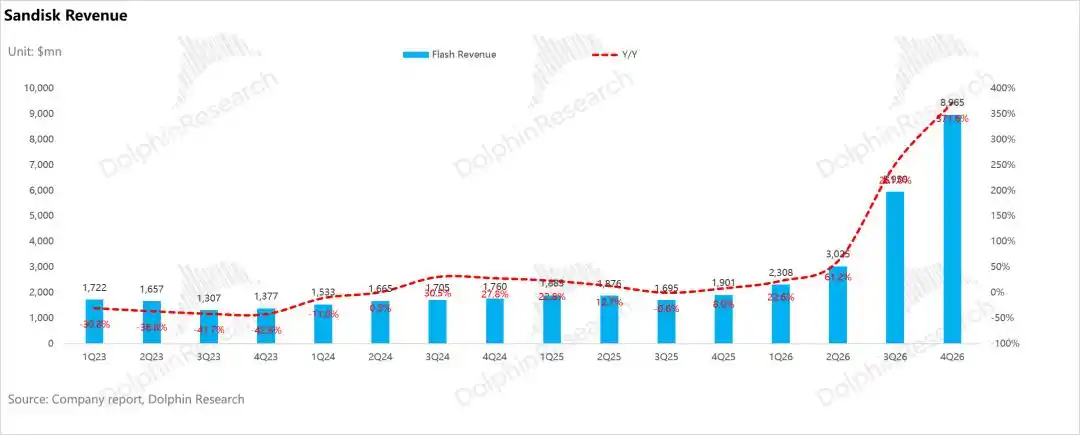
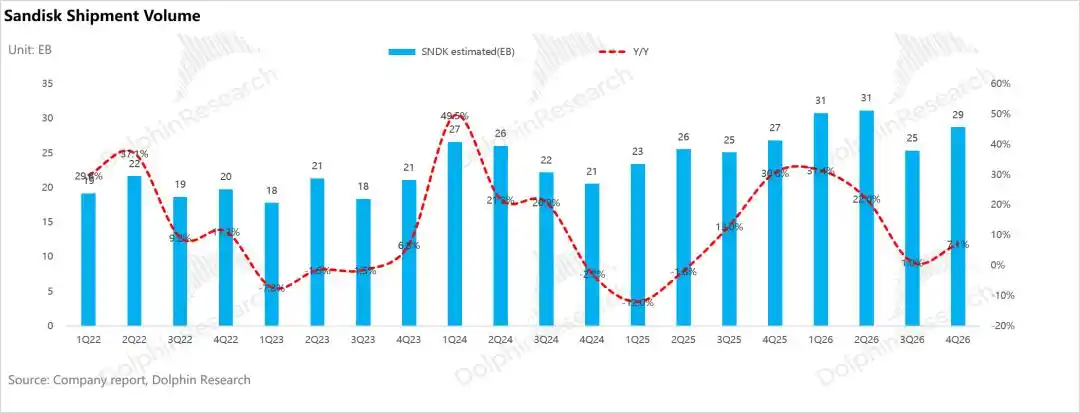
SanDisk's FY26Q4 revenue was about $9.0 billion, a year-over-year increase of 372%, almost entirely driven by price increases: bit shipment volume increased only about 7% year-over-year to 29EB.
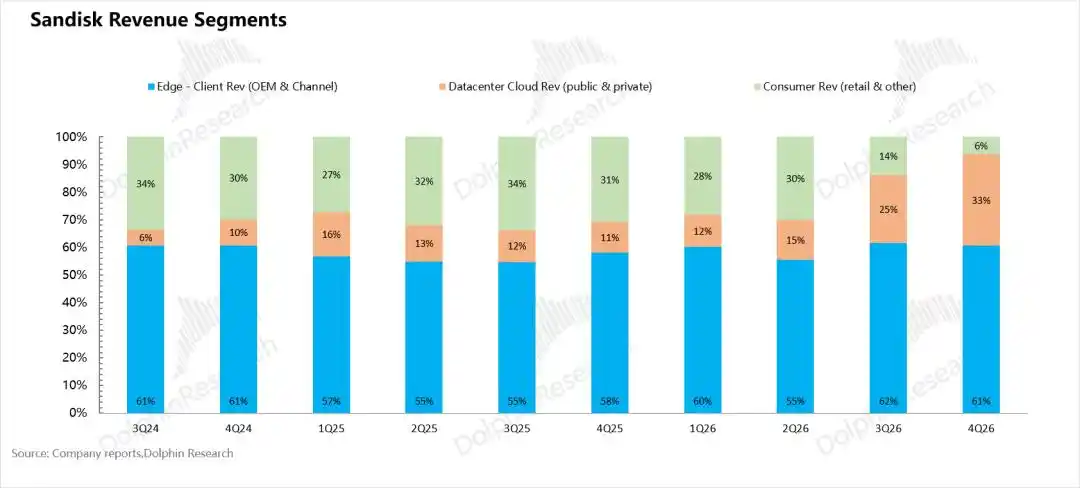
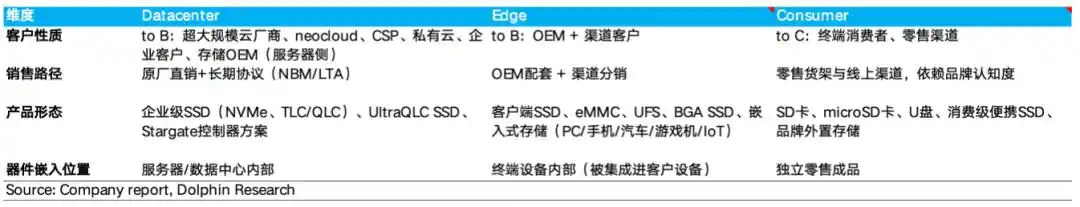
By business segment, data center grew the fastest: FY26Q4 revenue was about $3.0 billion, a year-over-year increase of about 13 times, with revenue share rising from 11% to 33%.
In AI scenarios, it's driven by performance-oriented TLC eSSD for AI inference use cases like KV caching and high-performance computing. Next is capacity-oriented UltraQLC high-capacity eSSD (starting at 128TB, currently under certification at multiple hyperscalers) which began shipments and recognized revenue in FY26Q4 (April-June 2026); the 256TB version is expected to launch in mid-to-late 2027.
Gross margin jumped from the low of 22.5% in FY25Q3 (Jan-Mar 2025) to 84.6% in FY26Q4, almost entirely driven by price increases:
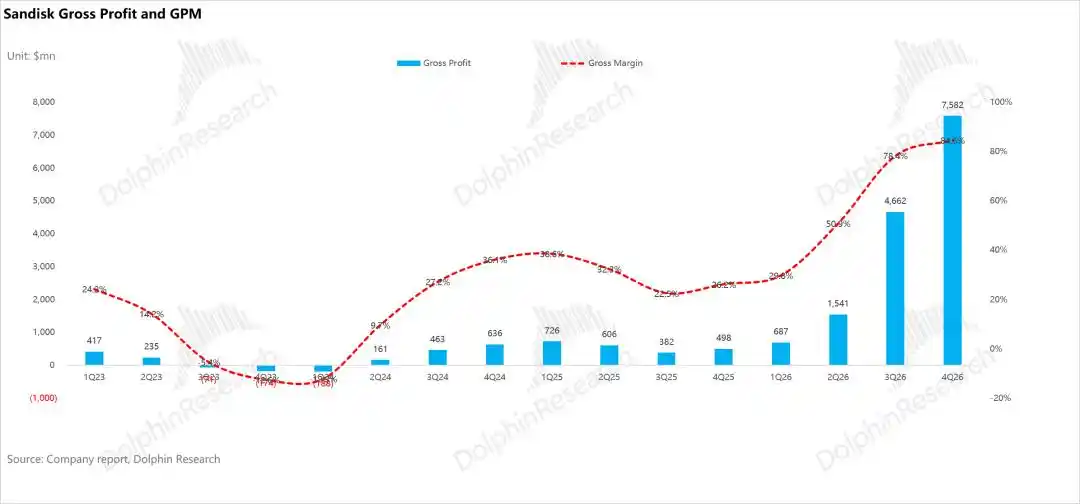
The question is: How long can this "super boom" last? And how long can SanDisk's ultra-high gross margin of 80%+ be maintained?
Dolphin Analyst will assess this from the perspective of overall NAND industry supply and demand:
1.1 Supply Side:
1 NAND Capacity Expansion: Not Relying on Capital Expenditure for New Production Lines
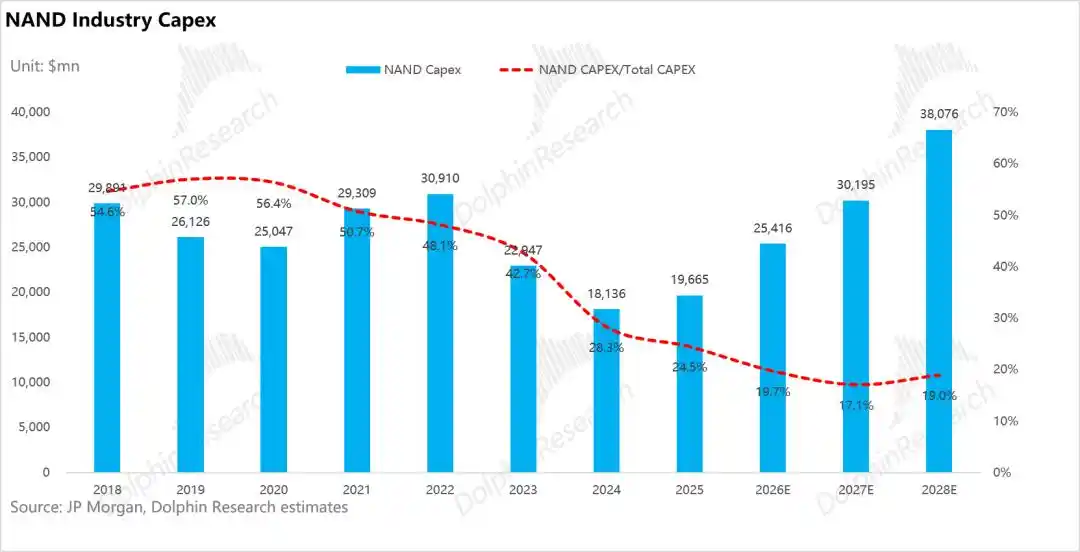
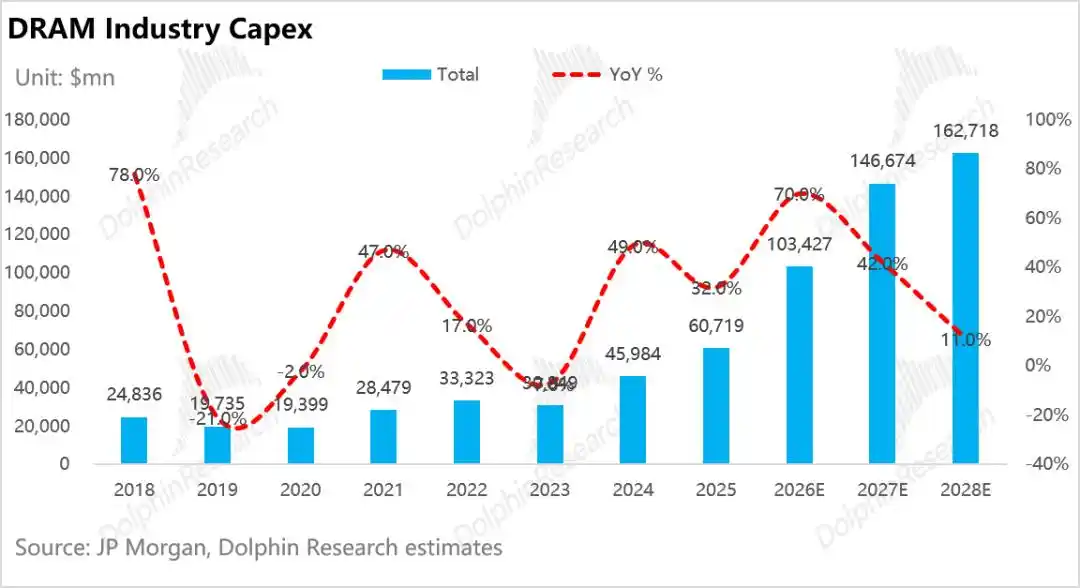
Despite the certain explosion in AI demand, the NAND industry, after a deep loss cycle, remains disciplined in capital expenditure. The contrast in the chart below is clear:
While memory manufacturers are increasing capital expenditure, it's primarily allocated to DRAM/HBM—estimated at $162.7 billion in 2028 (three-year CAGR of 39%); NAND investment was already low, growing to only $38.0 billion by 2028, with a three-year CAGR of just 25%. Its share of global memory capex actually declines from 25% in 2025 to 19%.
2 Shift in Capital Expenditure Focus: "Squeezing" Capacity via Technology Upgrades
Overseas original manufacturers' capacity expansion strategy has fundamentally shifted: Limited by cleanroom space in 2026-2027, they cannot build large-scale new capacity. Capex is mainly used to upgrade existing fabs—core focus is increasing 3D stacking layers (migration to 200+/300+ layers), supplemented by increasing cell bit storage (e.g., TLC/QLC) and optimizing architecture, to improve bits per wafer output.
New fabs will only start to be completed from 2028 onwards, and new capacity is still dominated by DRAM/HBM. Large-scale NAND capacity release is expected after 2029.
Compared to building new fabs, increasing wafer density requires less investment and yields faster results: large-scale equipment changeover typically takes 3–6 months (with a brief output dip), much faster than the 2–3 years for a new fab.
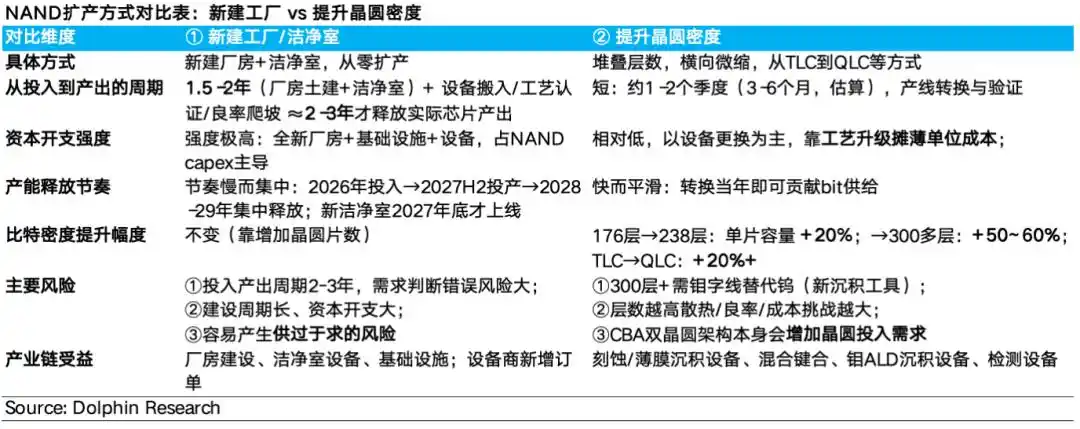
3 Capacity Release Timeline: China-led Expansion in 2026-2028, Global Players' New Lines Concentrated Post-2029
From a wafer start perspective, global NAND monthly capacity was about 1.26 million wafers in 2025, expected to increase to only 1.50 million by 2028, a three-year CAGR of just 6%. Of the 240k wafer increase, Yangtze Memory Technologies (YMTC) contributes about 150k, increasing its share from 12% to 20%; Samsung's physical capacity remains flat, with its share passively declining from 31% to 26%.
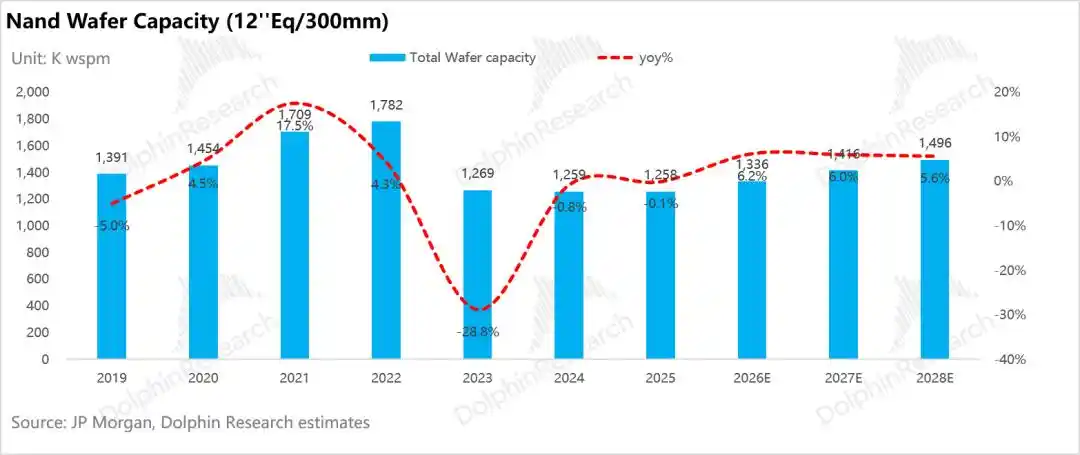
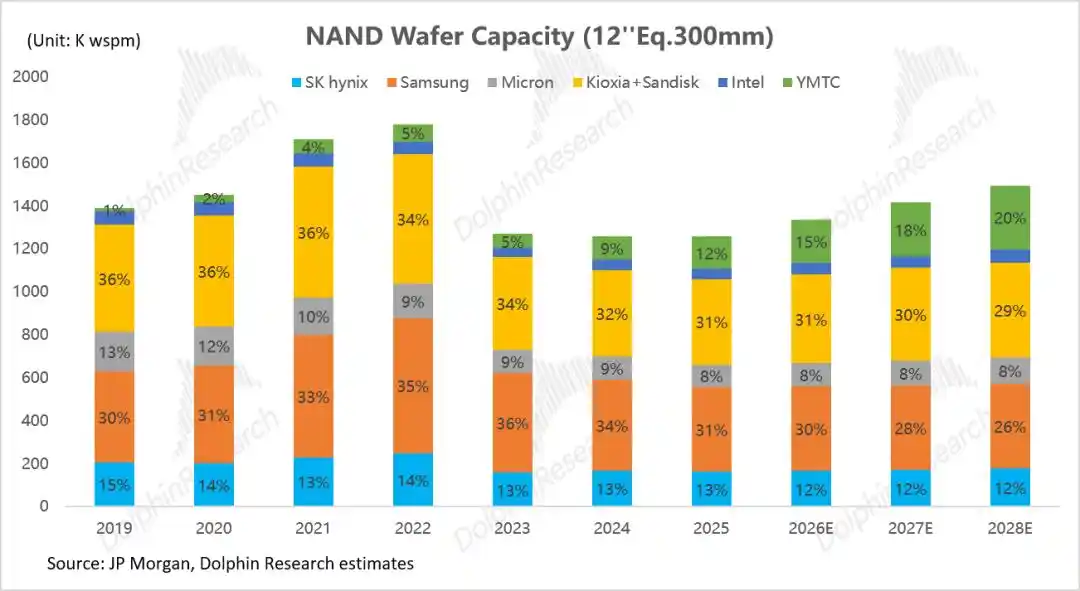
New fab additions are clearly staggered regionally and temporally: Supply is not massively released in 2027-2028, while 2029 poses a risk of a jump:
2026H2-2028 (led by China expansion): New fabs primarily come from YMTC (Fab 3) and SK Hynix (Dalian Fab 2). Overseas, almost no large new fabs will start production (only Micron's Singapore fab has minor output by late 2028). 2027-2028 is the period with the weakest supply elasticity for overseas vendors, and bit growth heavily relies on layer migration.
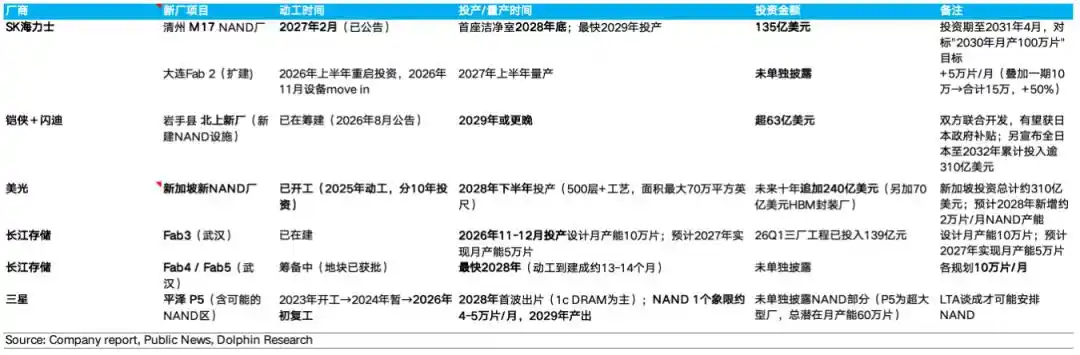
2029 and beyond (overseas new fabs concentrated): Large capacities from Samsung's P5, Kioxia/SanDisk's Kitakami new fab, and SK Hynix's M17 will be released, potentially significantly boosting supply growth. Project progress and LTA signings need monitoring.
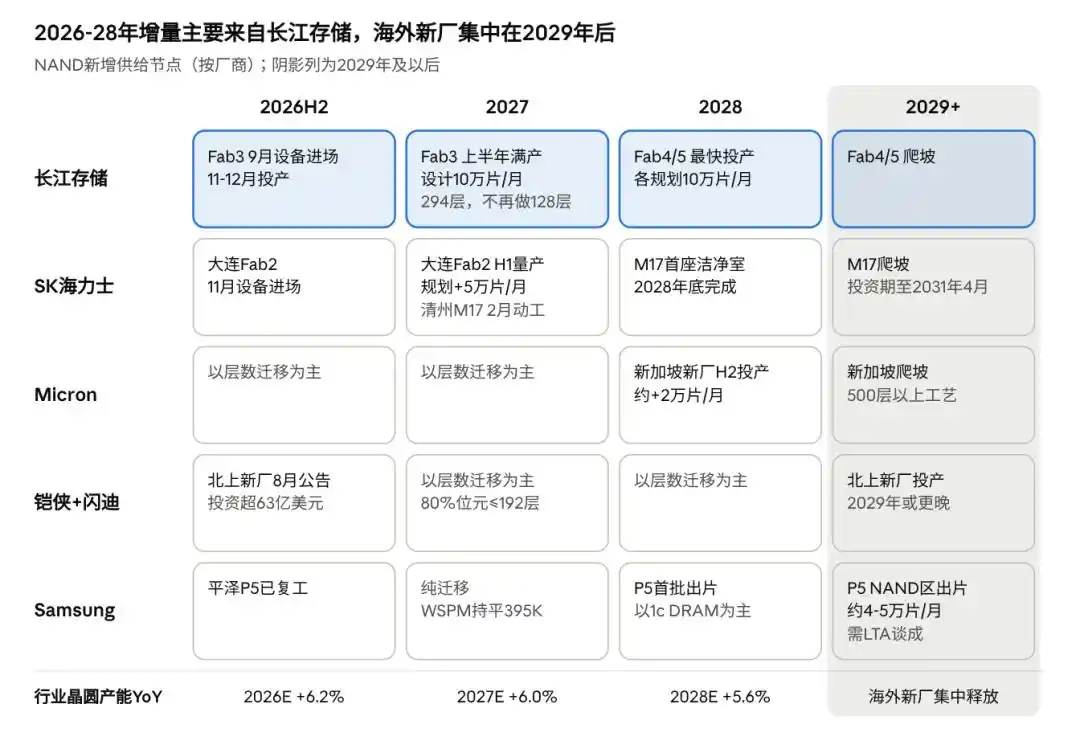
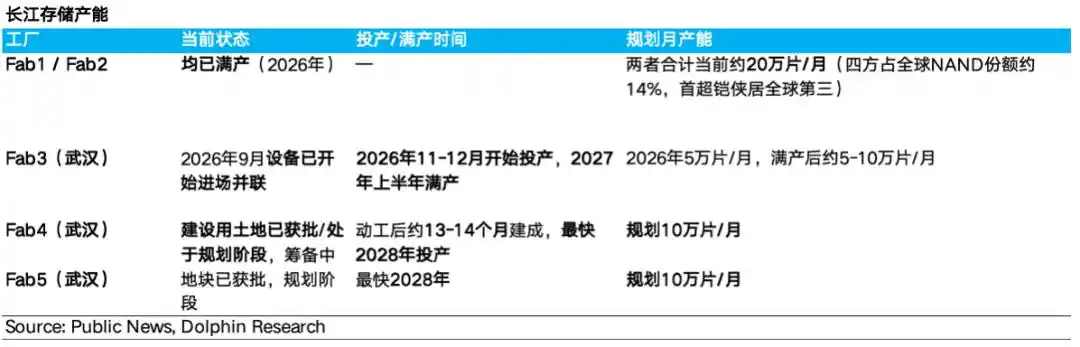
a. YMTC: Dual-Driver Expansion via Layer Stacking and New Lines Over Next Three Years
YMTC's capacity will expand from an estimated 200k wpm in 2026 to 300k wpm in 2028.
Currently, Fab1/Fab2 are at full capacity (approx. 200k wpm). The key increment is Fab 3 (designed for 100k wpm), expected to start production by end-2026, reaching 50k wpm capacity in 2027.
Its next-generation Xtacking 4.0 architecture can enable 1Tb TLC and 2Tb QLC products, covering enterprise and consumer needs.
Fab 3 will directly introduce 294-layer products, with the target of enterprise SSD share reaching 60%.
Fab 4/Fab 5 land has been approved (both designed for 100k wpm each). If construction starts early, 2028 supply could still be revised upwards.
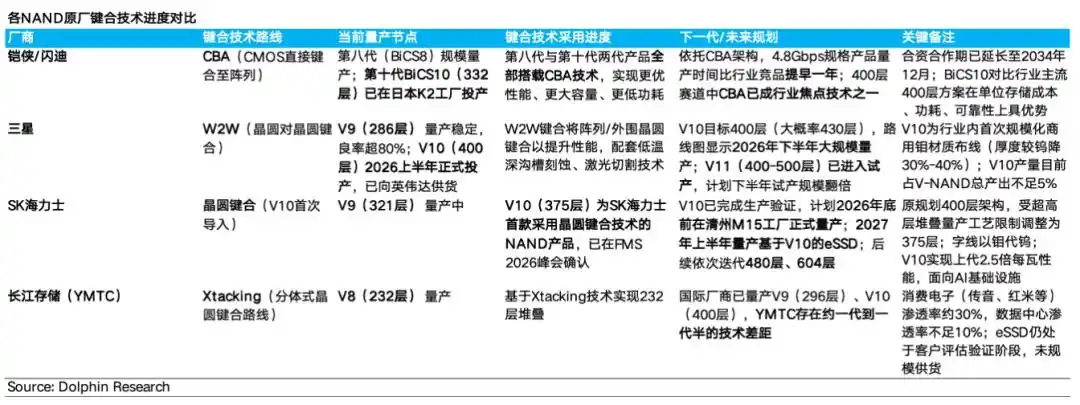
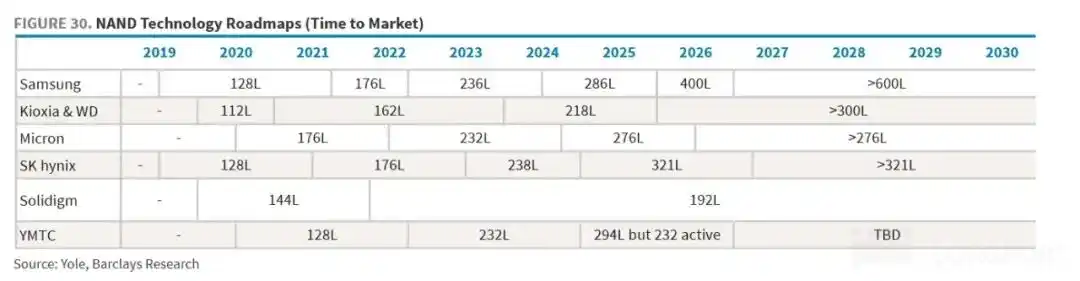
On expanding capacity via layer stacking: YMTC has mass-produced 232-layer; 294-layer (Xtacking 4.0) mass-produced in 2025; 300+ layer in R&D.
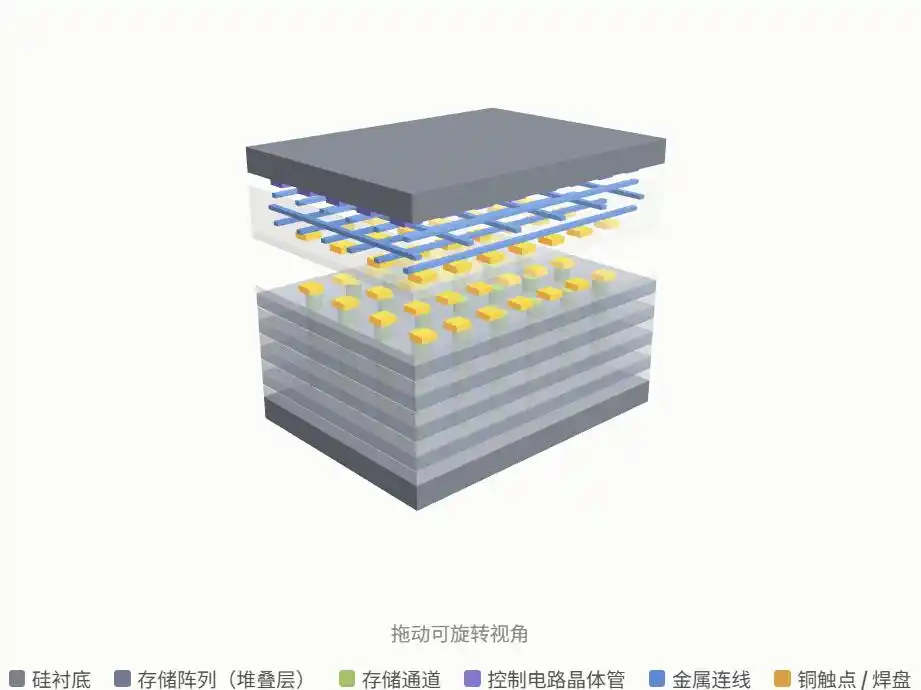
Beyond 400+ layers, wafer-to-wafer Copper-Copper Bonding (where the memory array and control circuit are manufactured on separate wafers and then bonded face-to-face via copper pillars) has become a common path for original manufacturers:
Samsung is advancing next-gen ~430-layer V-NAND with W2W bonding (V10 has mass-produced 400-layer); Kioxia/SanDisk's 8th and 10th gen products both use CBA; SK Hynix also confirmed V10 will adopt wafer bonding (planning mass production at Cheongju M15 by end-2026). As the pioneer of this path, YMTC possesses a first-mover advantage.
b. Samsung: Zero Capacity Growth, Purely Tech-Driven via "Layer Stacking"
Samsung allocates almost all NAND capex to technology migration, maintaining total monthly capacity around 395k wafers. By 2026, part of its output already reaches 286+ layers. After Pyeongtaek P5 resumed, priority is given to DRAM. Its NAND area will only have output by 2029 at the earliest, with pace adjustable based on LTA negotiations.
c. SK Hynix: Short-term Reliance on Dalian Expansion, Long-term Wait for M17 New Fab
Short-term increments come from Dalian Fab 2 expansion (adding 50k wpm, expected mass production 2027H1); Cheongju M17 new fab ($13.5 billion investment) plans to start construction in 2027, with no substantial output before end-2028.
d. Kioxia & SanDisk: Highest Migration Elasticity from Older Fabs, New Fab Post-2029
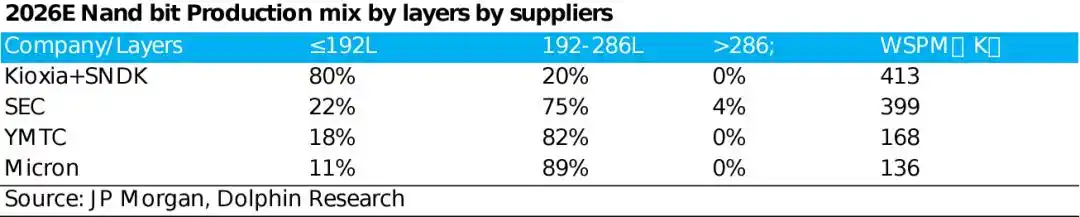
Combined capacity for the two will only increase from ~390k wpm to ~440k wpm over the next three years, but technology migration space is large: ~80% of 2026E output is still at 192-layer and below. The Kitakami new fab (investment over $6.3 billion) won't start production until after 2029.
e. Micron: Singapore New Fab as Sole Overseas Variable for 2028
Micron's total capacity expected to increase from 100k to 120k wpm. The Singapore new fab (500+ layer process) plans production start end-2028, contributing only ~20k wpm that year.
4 Total Supply: "Trading Technology for Capacity"
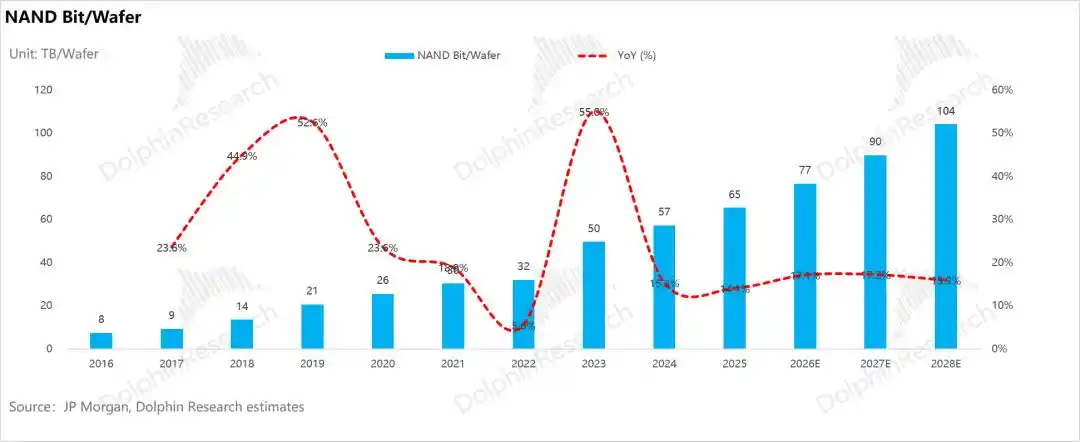
From capacity (i.e., how many raw wafers a memory fab can consume monthly) to output, it also depends on how much capacity each wafer yields: NAND bit supply = Wafer capacity (monthly capacity × 12) × Bits per wafer output. Dolphin Analyst estimates global average bits per wafer output was about 65TB in 2025.
As NAND moves beyond 300 layers (Kioxia/SanDisk BiCS10 is 332 layers, SK Hynix advancing 321-layer), average bits per wafer is expected to rise to about 104TB by 2028, a three-year CAGR of about 17%.
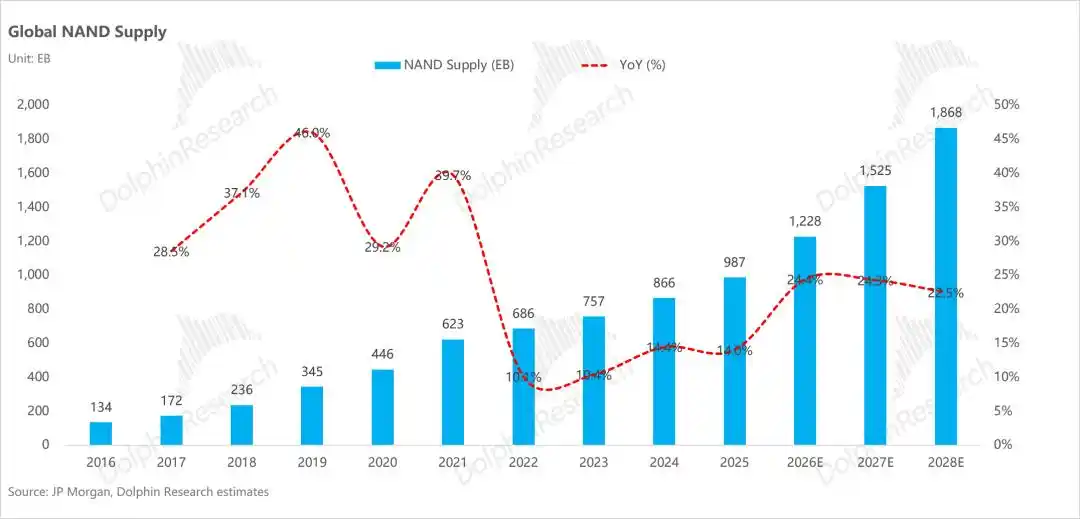
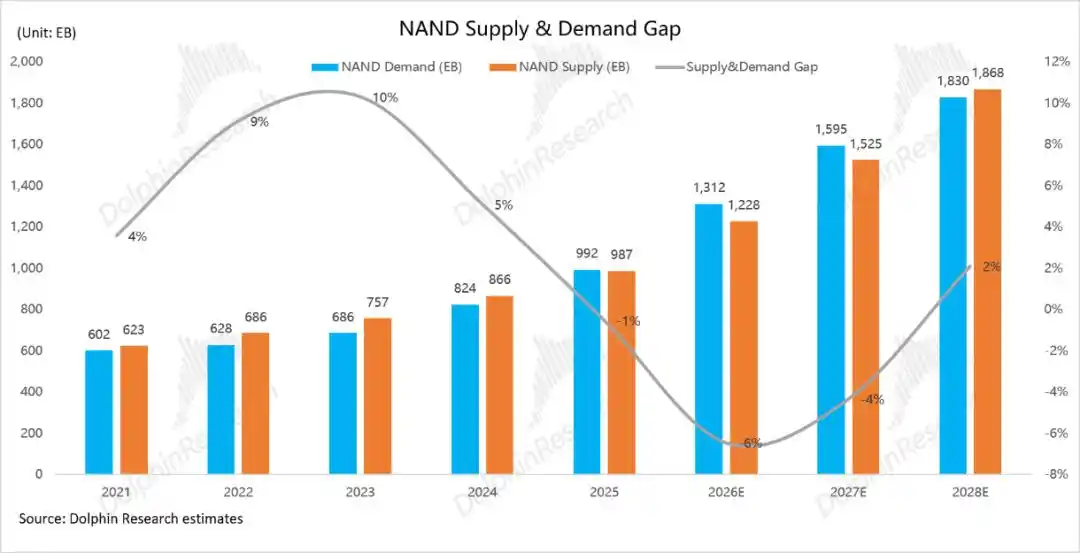
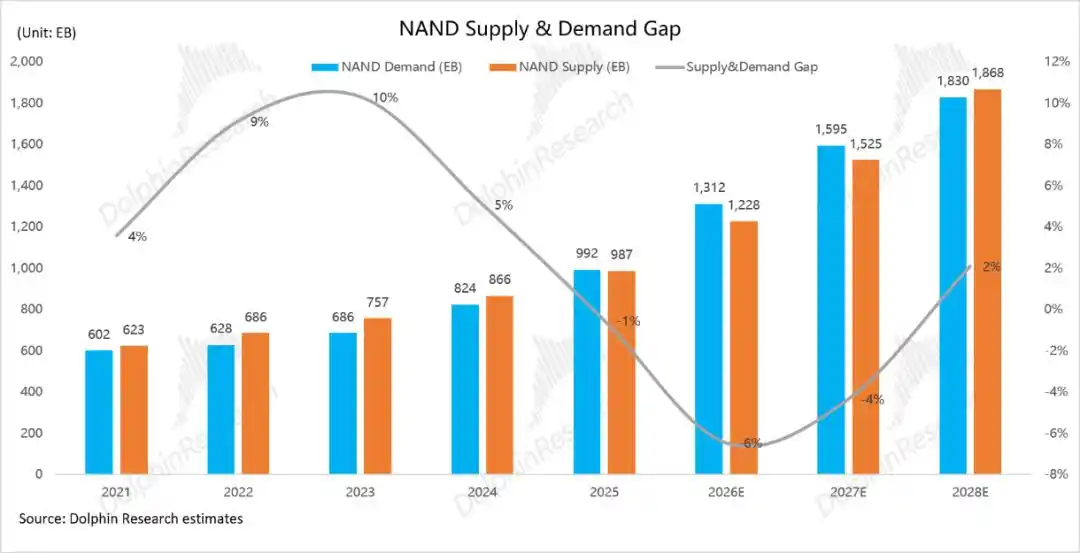
Based on this, global NAND supply for 2026/2027/2028 is estimated at about 1,228/1,525/1,868EB respectively, with a CAGR of about 24%. Of the new supply, about 73% comes from increased bits per wafer, only 27% from increased wafer capacity, i.e., "trading technology for capacity."
Migration potential varies significantly among vendors:
Kioxia+SanDisk are migrating from BiCS8 (218-layer) to BiCS10 (332-layer): BiCS10 was sampled in July 2026, expected mass production mid-to-late 2027, with bit density 59% higher than 8th gen, offering the highest migration elasticity.
Samsung leaps from 286-layer V9 to ~400-layer V10, expected to enter 600+ layers from 2027.
YMTC's Fab 3 introduces 294-layer (232 active layers) and phases out 128-layer; new capacity's bits per wafer are significantly higher than older lines.
Upside risks to supply include YMTC capacity releasing earlier, and Kioxia+SanDisk still having 80% of bits at 192-layer and below—once migration accelerates, bits per wafer directly increase.
Downside risks include: On the demand side, if pSLC (pseudo SLC)/SLC products for AI inference staging scenarios (temporary data storage before entering HBM) achieve mass production in 2027-2028, they consume three times the capacity of regular SSDs, significantly tightening industry supply.
1.2 NAND Demand: AI Takes Over as Dominant Force, Demand Structure Undergoes Fundamental Shift
Extreme supply-demand mismatch gives NAND storage the opportunity to smooth cyclical fluctuations via deposits, prepayments + LTAs, moving away from the past loose model of "short orders, volume locked but price not, low breach cost."
But Dolphin Analyst believes this round is more of a super cycle rather than a fundamental change in industry competition structure or barriers. Therefore, LTAs smooth the cycle but do not eliminate it.
Taking SanDisk's LTAs as an example, although NBM LTAs are signed, financial guarantees only cover about 18% of the guaranteed minimum revenue; the rest still heavily relies on customer credit. Once spot prices crash, LTAs also face renegotiation risks.
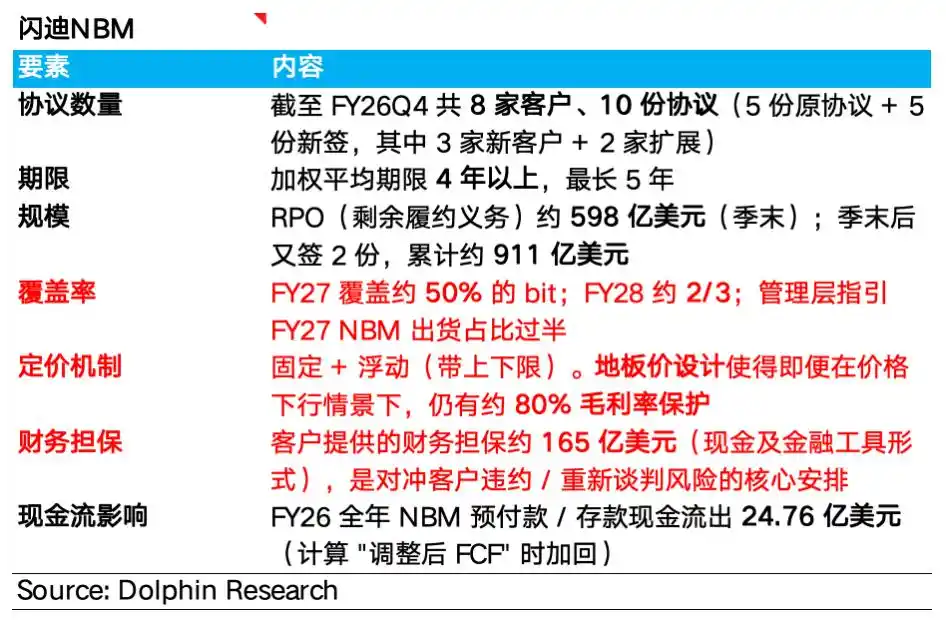
Since commercial barriers haven't fundamentally changed, the value judgment for SanDisk this round essentially depends on how long this supply-demand mismatch lasts. Supply-side growth is highly certain; the key next is demand elasticity.
1 AI Demand Structure: Data Lakes in 2026, NVIDIA Storage Cabinets in 2027
2026 is a structural inflection point: Data center demand is about 670EB, for the first time accounting for over half of total NAND demand, replacing smartphones and PCs as the largest downstream segment. Over the past decade, NAND demand was determined by smartphone and PC replacement cycles; in the future, it will be AI capital expenditure that dictates industry supply and demand.
Behind capital expenditure lies what Dolphin Analyst discussed in the previous article: the shift from "training" to "inference," and the three major scenarios within AI servers—high-frequency read/write Staging (temporary data storage), KV Cache for inference spilling over from HBM to NAND, and data lakes storing multimodal data.
Dolphin Analyst uses a bottom-up approach to estimate NAND demand from AI servers:
Total AI NAND Demand = (ASIC + GPU + CPU Racks + Chinese CSP + QLC Data Lakes) × (1 + CSP Inventory Buffer)
First, estimate shipments of various AI chips based on TSMC's CoWoS capacity, convert to rack numbers using 4 chips per compute tray, then multiply by NAND capacity per tray (eSSD).
Storage configurations vary greatly among players:
The key lies in chip architecture—how much built-in HBM/DRAM it has, and whether compute and storage are separated.
a. NVIDIA: "Disaggregated Compute and Storage," Storage Demand Shifts to Independent Cabinets
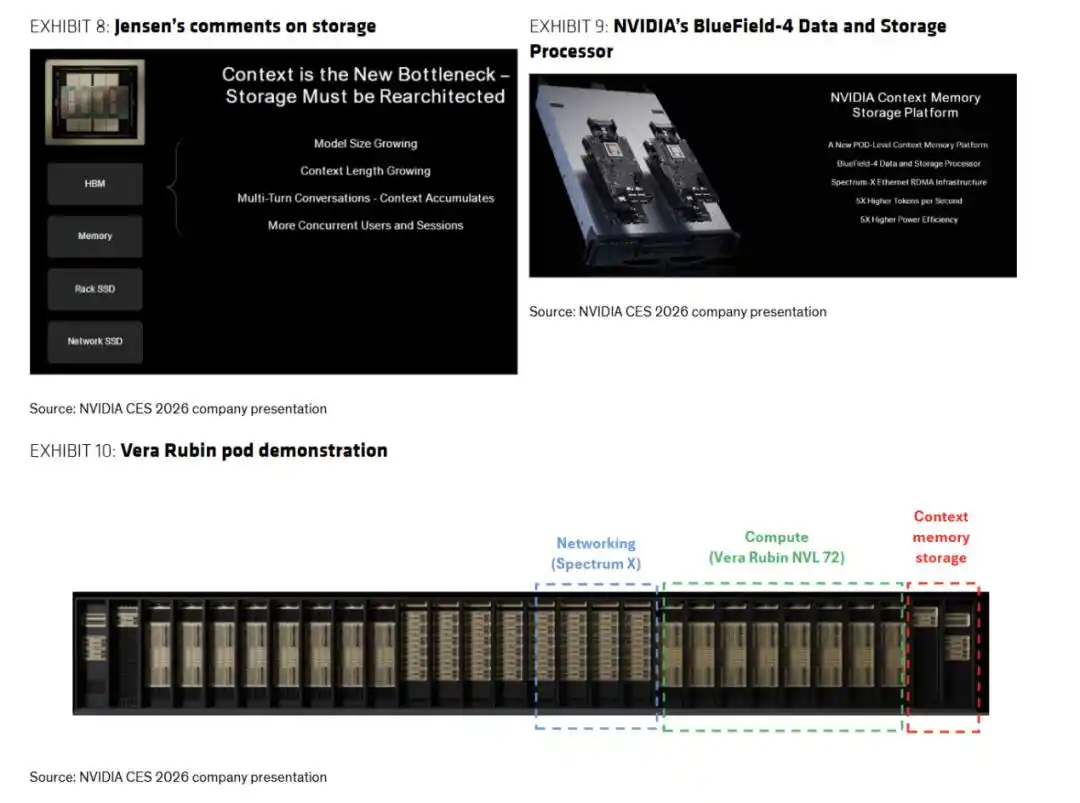
NVIDIA has the thickest memory hierarchy. Taking Vera Rubin NVL72 as an example, a single rack already has 20.7TB HBM (72 Rubin chips × 288GB) and 54TB LPDDR5X (36 Vera CPUs); most KV Cache pressure is digested within the memory layers.
Therefore, NVIDIA's approach is: Keep only basic SSDs in the compute tray, and offload massive storage to a separate storage layer (ICMS, Inference Context Memory Storage). Its NAND demand is divided into three layers:
First layer: Basic on-board configuration (18TB): Both Blackwell and Rubin standard configurations are 18TB per tray (4 GPUs), mainly used for loading data during training and saving checkpoints.
Second layer: Extra attachment for Blackwell (+46TB): 18TB is insufficient for needs like multi-tenant inference. Customers often attach an extra ~46TB, bringing a single tray to 64TB, but this is a transitional solution.
In the Rubin era, this demand will be taken over by the CMS storage cabinet. It will contract significantly when Rubin becomes mainstream in 2027.
Third layer: STX CMS Context Memory Storage in the Rubin era: This is the largest structural increment in 2027.
With the proliferation of Long-Context inference, HBM and DRAM can no longer hold the massive KV Cache. NVIDIA's solution is to introduce ICMS, a dedicated storage cabinet composed of numerous SSDs, shared by the entire compute cluster.
Every 4 NVL72 racks share 1 CMS storage cabinet, each cabinet has 8 trays, each tray 600TB, equating to about 16.7TB NAND per Rubin GPU, roughly 4 times the actual configuration for Blackwell. By 2027, this layer will contribute over 70% of NVIDIA's NAND demand.
Fourth layer: Independent Vera CPU racks: Mainly addressing Agent demand for CPU cores. These CPU racks are configured with 8TB NAND storage per Vera CPU.
b. In-house ASICs: Thinner Memory, Thicker SSD
SSD configurations for cloud vendors' in-house chips (ASIC) differ significantly:
Google TPU: Has built-in HBM (e.g., TPU v7 single chip 192GB), with only 16TB per tray. The lowest per-rack configuration, but large shipment volume accounts for over half of ASIC storage demand.
AWS Trainium: Has 144–288GB HBM (Trainium3 144GB, Trainium4 288GB), catering to both training and inference, with 32TB per tray, double that of Google.
Meta MTIA: Early models (MTIA v2) are the only "HBM-less" design, with only 128GB LPDDR5 per chip, about 512GB memory for the entire tray.
Due to its own memory scarcity, and recommendation systems needing to access TB-scale embedding tables, it must use SSD as an extension of memory. Thus, single-tray configuration is pulled up to 64TB, four times that of Google.
c. AMD and Others
AMD's compute trays across generations are uniformly calculated at 64TB.
Chinese Cloud Service Providers (CSPs): Estimated based on capital expenditure, demand for 2025/2026/2027 is 50/120/180EB respectively.
QLC Data Lakes: Referencing SanDisk's perspective, assumed to be 25% of total NAND demand.
Inventory Buffer: During price increase cycles, cloud vendors typically hold ~10% extra inventory, so from 2026 onwards, the total is multiplied by 1.1.
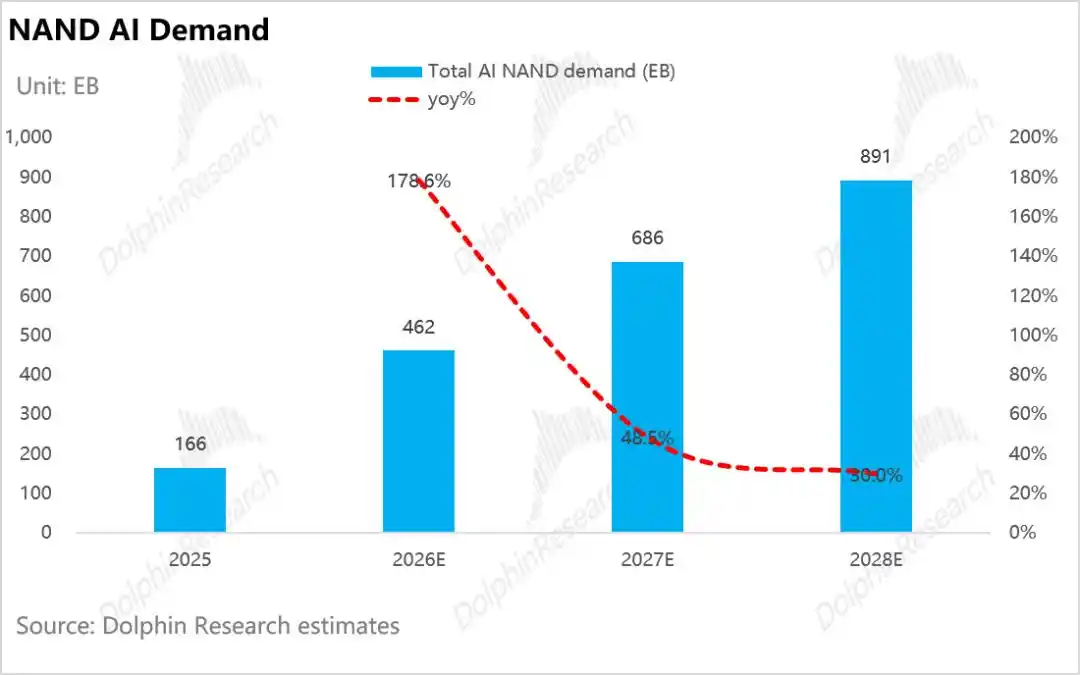
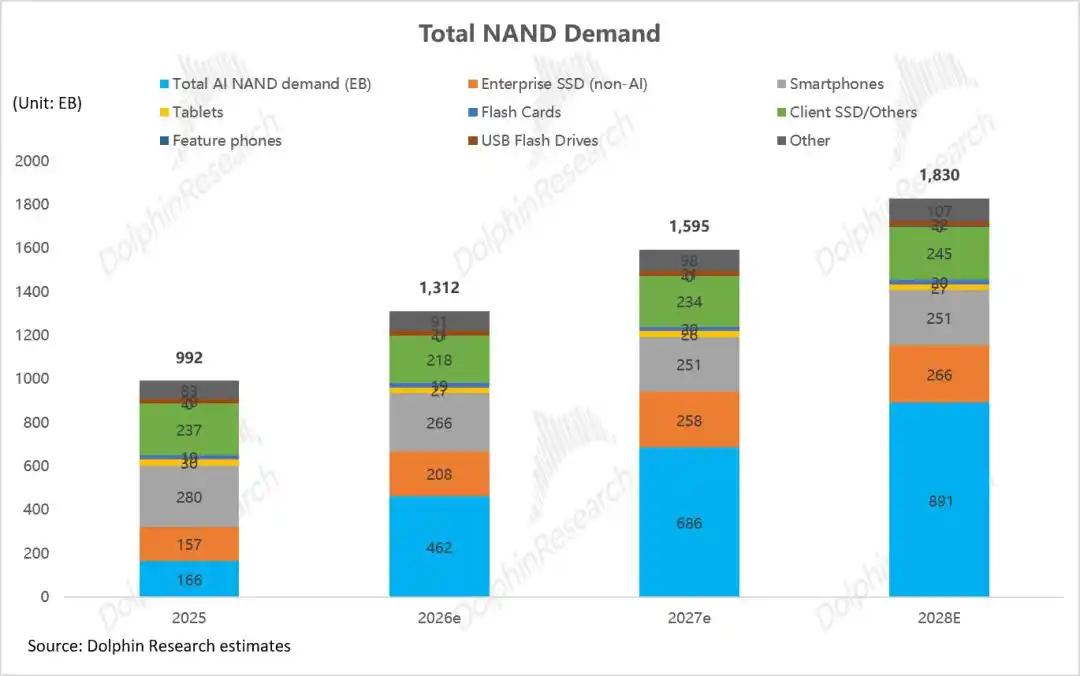
Aggregating demand from major players: Global AI NAND demand for 2026–2028 is estimated at about 462, 686, 891EB respectively, with a three-year CAGR of 75%.
The surge in 2026 mainly comes from QLC data lakes, Chinese CSP scaling and restocking, and growth in on-rack storage; the baton passes to NVIDIA in 2027—Rubin's STX CMS context storage cabinets will become the main engine for its NAND demand, alongside QLC data lakes as the two major sources of global demand increment.
2 Non-AI Demand: Enterprise Robust, Consumer Under Pressure
Non-AI enterprise SSDs benefit from general server refresh cycles. The rollout of AI inference applications by North American cloud vendors also drives volume and price for general servers. This demand is expected to grow 32.5% and 24.0% in 2026 and 2027 respectively, slowing to around 3% in 2028.
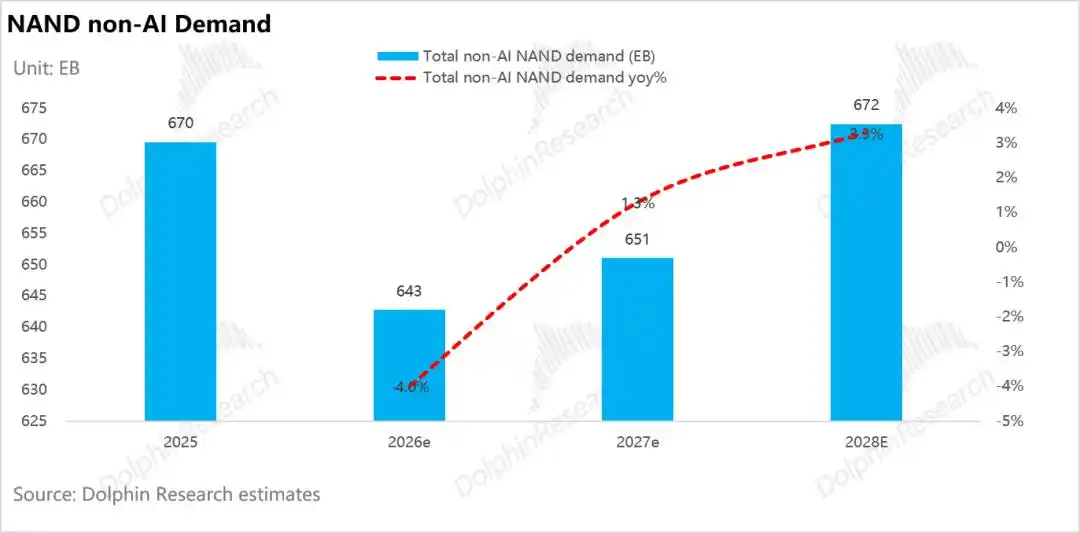
The consumer side faces severe squeeze. Dolphin Analyst expects consumer and other NAND demand to decline 4.0% in 2026. The PC segment is most directly impacted, with Client SSD demand falling about 8% in 2026, rebounding about 7% in 2027 from a low base. Smartphone NAND demand declines about 5%–6% year-over-year for both 2026 and 2027, stabilizing only in 2028. As one wanes and the other waxes, data center (AI + enterprise) share of total NAND demand will exceed half (51%) for the first time in 2026, rising to 63% by 2028.
This cycle will likely see differentiation: AI and enterprise products remain tight supported by LTAs, while consumer prices may peak earlier.
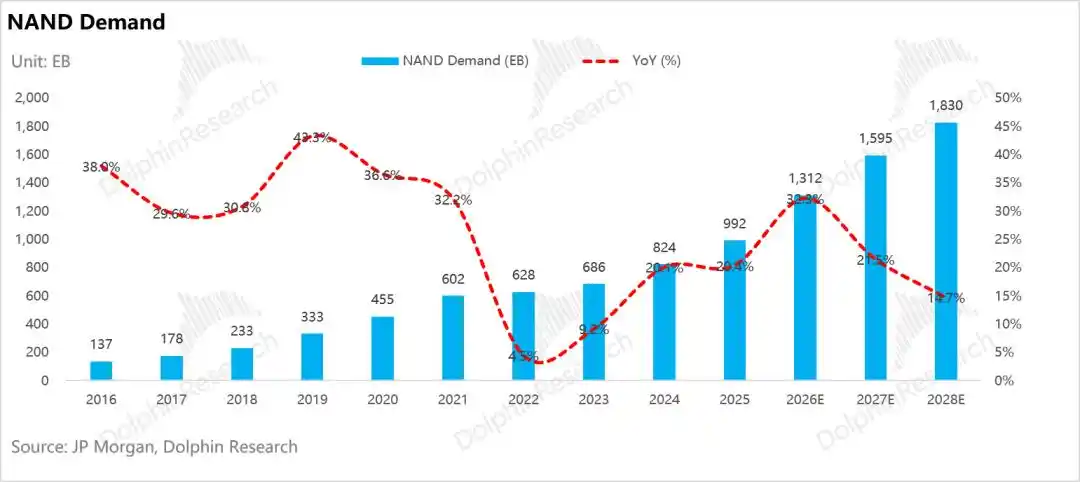
Overall demand-side estimate: Global NAND total demand will increase from 992EB in 2025 to 1,830EB in 2028, with a CAGR of about 23%, significantly higher than the ~13% CAGR from 2021–2025.
Growth almost entirely comes from AI: AI NAND demand increases from 166EB to 891EB, a three-year CAGR of 75%, contributing 87% of demand increment; non-AI demand CAGR is only 4%.
Structurally, data center demand's share exceeds 50% for the first time in 2026. By 2028, server (AI + traditional) demand share will rise to about 60%, with AI server share increasing from 17% in 2025 to 49%.
Summary: Will Supply-Demand Dynamics Reverse in 2028?
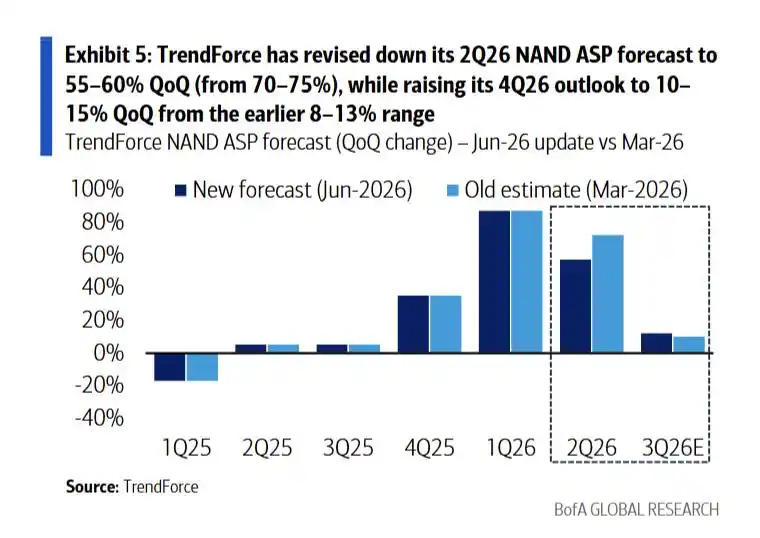
Aggregating NAND supply and demand estimates: The NAND bit deficit is about 6% in 2026; supply remains tight in 2027, with the deficit narrowing to about 4%.
2028 will be the watershed for supply-demand dynamics: Supply-side capacity release is highly certain (YMTC new fab starts ramping), while on the demand side, without new explosive drivers (e.g., continued high CSP capex growth, edge AI explosion, etc.), oversupply is likely, and the NAND price increase cycle will consequently end.
2. Standing at the Current Valuation Node, Does the Reborn SanDisk Still Have Upward Potential?
Based on this, Dolphin Analyst expects this "super boom" to likely extend until the end of 2027; supply-demand will turn looser from 2028, and prices will see significant correction after overseas new capacities are concentratedly released from 2029.
Forecasts for SanDisk are as follows (SanDisk fiscal year ends June each year; FY27 corresponds to July 2026 – June 2027, etc.):
1 ASP: Peaks in FY28, LTAs Provide a Floor
Management guidance indicates FY27 ASP will rise moderately quarter-over-quarter, with FY28–FY30 revenue maintaining 15%~19% growth, synchronized with bit shipment growth—this implies an extremely optimistic assumption of flat ASP over the next three years, with the cycle completely "ironed out" by LTAs.
Dolphin Analyst believes prices will peak in FY28 and see significant decline in FY29–FY30:
FY27 (Moderate Increase): ASP expected at $0.37/GB (year-over-year +113%). FY26Q4 average price was $0.31/GB, spot has risen to ~$0.44/GB. With still ~4% deficit in 2027, but price increase capped by LTA price ceilings, prices will rise moderately quarter-over-quarter.
FY28 (Peak and Turn): ASP expected at $0.38/GB (year-over-year +2%), peaking during FY28 (2027H2–2028H1); as YMTC Fab 3 ramps and supply-demand loosens, prices start declining from FY28 second half.
FY29–FY30 (Cyclical Decline): ASP expected to decline year-over-year 20% and 40% respectively, dropping to $0.18/GB, back to 2026 levels. Reason: industry shifts to oversupply, and new capacities like Samsung P5, Kioxia/SanDisk Kitakami, SK Hynix M17 start concentrated production from 2029.
Even so, FY30 ASP will still be about 2.5 times FY25 ($0.07/GB), supported by two factors:
a. NBM's price floor (full-cycle minimum contracted revenue of $93.9 billion, plus $16.5 billion in guarantees);
b. Data center share of NAND demand will rise to 63% by 2028; higher-value customer share increases, lifting the average price floor.
2 Shipment Volume: Driven by Process Migration
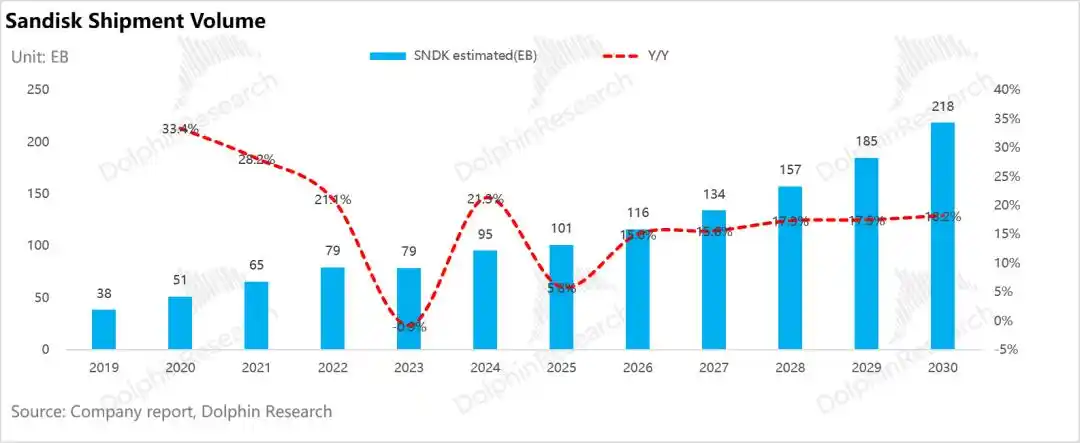
At the Investor Day, management revised FY27 salable bit growth from mid-to-high teens down to mid-teens (approx. 15%), due to the need to reserve inventory for NBM LTAs; bit growth still relies on process migration, not new wafer starts.
Dolphin Analyst expects SanDisk's bit shipments to increase from 116EB in FY26 to 218EB in FY30, a CAGR of about 17%, mainly driven by migration from BiCS8 to BiCS10 (BiCS10 mass production mid-to-late 2027, Kitakami new fab post-2029).
NBM LTAs are expected to cover about half of FY27 and two-thirds of FY28 shipments, providing high visibility on volume.
3 Gross Margin: High Margins Under Pressure Amid Oversupply Concerns
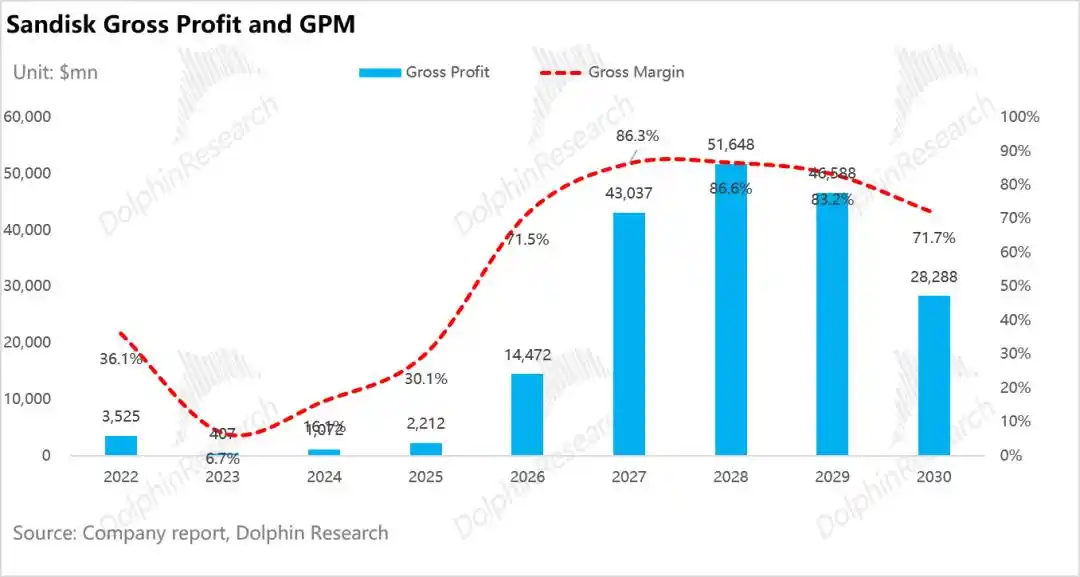
Management provided guidance for FY28–FY30 non-GAAP gross margin around 80%, premised on ASP holding basically steady; once prices turn down, margins could decline rapidly.
Historically, NAND has shifted from shortage to oversupply multiple times. Maintaining 80% gross margin throughout a full cycle is extremely rare. Although there is an NBM LTA floor, financial guarantees only cover about 18% of the guaranteed minimum revenue; the rest still heavily relies on customer credit. Once spot prices crash, LTAs also face renegotiation risks.
Therefore, Dolphin Analyst assumes unit cost remains around $0.051/GB for FY27–FY30 (excluding BiCS10 cost reduction), to cover new fab depreciation, yield ramp, and raw material price increases.
Corresponding gross margin peaks in FY28 (86.6%), then declines yearly with ASP, dropping to 72% in FY30.
4 Profit Divergence: Can the Cycle Be Fully "Ironed Out"?
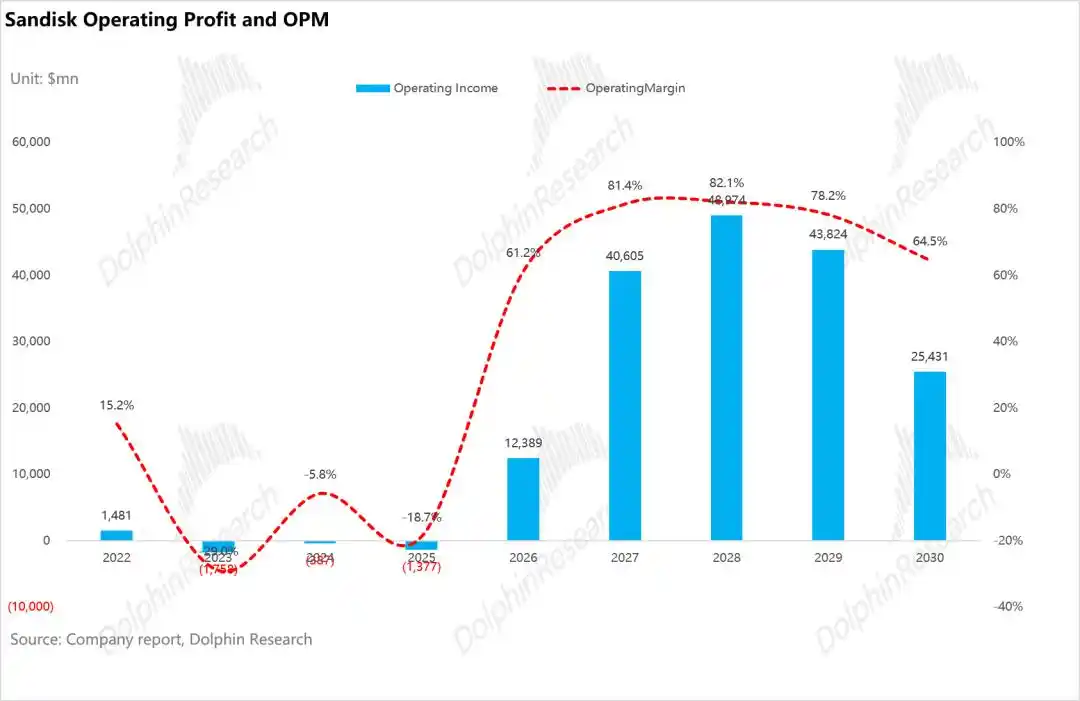
On the expense side, management guides FY28–FY30 OpEx at about 5% of revenue, non-GAAP operating margin around 75%. Dolphin Analyst expects operating margin to peak at 82% in FY28, declining to 65% in FY30 (three-year average still ~75%).
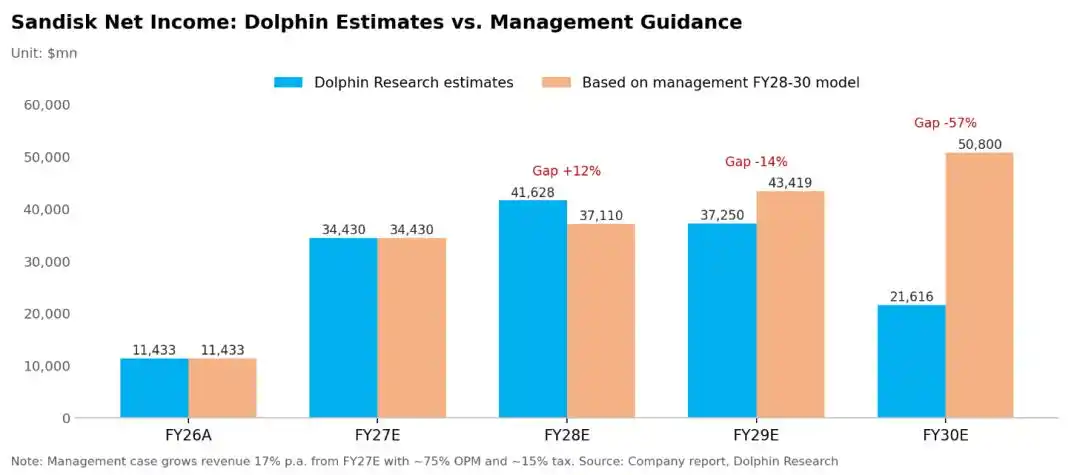
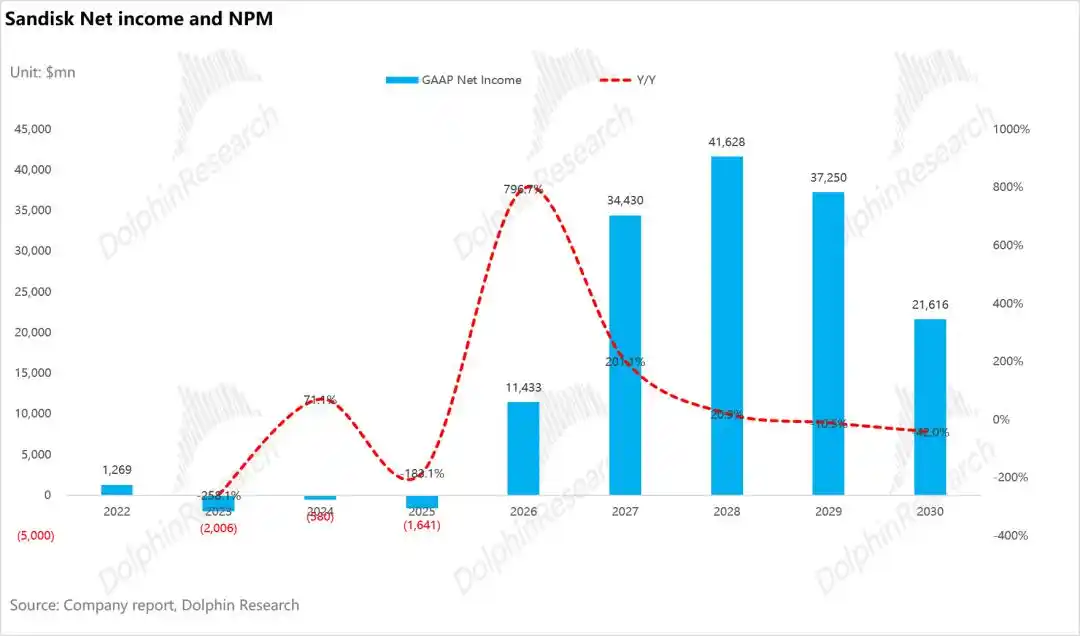
Applying an ~15% tax rate, Dolphin Analyst expects SanDisk's net profit to peak in FY28 (approx. $41.6 billion), declining to about $21.6 billion in FY30, only 43% of the value derived from management guidance (approx. $50.8 billion).
Derivation from management guidance: Starting from FY27E, revenue grows ~17% annually (ASP doesn't decline), operating margin ~75%, net profit would increase from ~$34.4 billion in FY27 to ~$50.8 billion in FY30.
This is essentially a cycle-ironing model: requiring LTAs to uphold prices for the contracted portion, and also requiring AI demand to absorb new supply post-2029, so that non-LTA prices also don't decline.
Value Analysis: Super or Still Cyclical
SanDisk is a typical cyclical growth stock with volatile earnings. Using traditional "peak EPS × low multiple" valuation is highly sensitive to the judgment of the peak year and ignores the significant earnings contraction during the downturn.
Therefore, Dolphin Analyst uses "through-cycle average net profit × mid-cycle multiple" as the core valuation method, cross-verified by discounted cash flow (DCF).
Through-cycle average net profit is taken as the nine-year average from FY22–FY30 (approx. $15.9 billion), covering the previous trough (FY23–FY25), the AI super cycle (FY26–FY28), and the price decline period (FY29–FY30).
More detailed value analysis is available in the article of the same name published by Dolphin Analyst in the "Dynamics - In-depth" section of the LongBridge App.
Overall, Dolphin Analyst believes SanDisk is currently in a reasonable range, largely reflecting neutral scenario expectations, with limited short-term safety margin. Whether it can continue to break upward depends on whether the market can believe and verify that "prices won't collapse post-2028."
- END -
This article is from the WeChat public account "Haitun Touyan" (ID: haituntouyan), author: Dolphin Analyst