Trump's Perplexing Fed Threat Might Be a Gift to Warsh

marsbitОпубліковано о 2026-09-08Востаннє оновлено о 2026-09-08

Анотація

Former President Donald Trump's puzzling call for Federal Reserve interest rate cuts and threats to halt trade with countries running U.S. deficits has drawn market confusion rather than movement. Reuters columnist Mike Dolan argues this rhetoric, lacking logical coherence, paradoxically presents new Fed Chair Kevin Warsh with an opportunity. By pushing for a rate hike at the upcoming September meeting, Warsh could credibly distance the central bank from White House pressure, reaffirm its commitment to the inflation target, and bolster his own credibility. With strong August jobs data, growth accelerating, and core inflation persistently above 2%, few economists see a case for cuts. A 25-basis-point hike, Dolan suggests, would be a strong public relations move to end speculation that Warsh is a White House "puppet" and could even help lower long-term borrowing rates by reinforcing the Fed's anti-inflation resolve. The article notes Trump's history of turning on his Fed appointees, implying Warsh faces a critical choice that may ultimately anger his patron.

Author: Mike Dolan

Compiled by: TechFlow

Deep Tide Digest: Last Friday, positive U.S. August employment data emerged, yet Trump suddenly pivoted to criticize the Federal Reserve, demanding "interest rate cuts, or else stop trading with countries with deficits." Reuters columnist Mike Dolan points out that this statement is logically incoherent and barely elicited a market reaction. However, it precisely presents an opportunity for Fed Chair Kevin Warsh, who took office this past May, to push for a rate hike this month. This move would reaffirm the Fed's commitment to its inflation target and demonstrate that he is not the White House's "puppet," thereby creating distance from the President and building his own credibility.

Trump's inexplicable linking of U.S. interest rate policy with trade relations with America's largest trading partners has generated more confusion than market volatility. But the President's outlandish statement has instead given Federal Reserve Chair Kevin Warsh an opportunity: to drive a Fed rate hike this month, convincingly creating distance from the White House and boosting his own credibility.

Last Friday should have been a reasonably good day economically for the President. After all, U.S. August job growth came in three times higher than expected, and a significant portion of the summer's weak job figures were revised upward. Diesel prices did hit a record high earlier that day, potentially adding upward pressure on inflation. However, the modest wage growth in the jobs report could also be interpreted as another reason for the Fed to stand pat ahead of this Friday's inflation data, coming just days before the Fed's next meeting.

Trump needed some good economic news. With only two months until the midterm Congressional elections, his overall approval rating remains at the low point of his two terms, and 71% of Americans (including four in ten Republicans) disapprove of his handling of the cost of living.

Yet, instead of focusing on the positive August jobs data, Trump quickly and somewhat inexplicably pivoted to attack the Fed, telling the central bank what it should do and threatening what he would do if it didn't comply.

"High interest rates put the U.S. at a very unfair disadvantage, I won't allow it!" Trump wrote on his Truth Social platform, while praising Warsh as "great." "We should have the lowest interest rates in the world... No rate cut, I'll stop trading with those countries where we have a deficit," Trump added.

The main problem with this argument is that it simply doesn't make sense. Even commentators typically supportive of the President either gave up trying to parse it or ignored it outright. Given the market's concerns over the past 18 months about the President's persistent political pressure on the central bank—including his willingness to force its hand through political appointments—this apparent disregard is noteworthy.

Trump has repeatedly called for significant rate cuts during his second term and has threatened multiple times to fire Warsh's predecessor, Jerome Powell, for not complying. He has also frequently questioned why America's economic strength shouldn't also grant it the world's lowest interest rates, even though most economists would struggle with the notion that a high-growth economy should have lower borrowing costs—considering the inflationary impact of overheating, the opposite is typically true.

More importantly, with core inflation running above the Fed's 2% target for 65 consecutive months, growth accelerating, financial conditions loose, and full employment effectively achieved, almost no one believes the Fed should be cutting rates now—not even those who think a September hike (currently priced by futures markets at over a 50% probability) might be slightly premature.
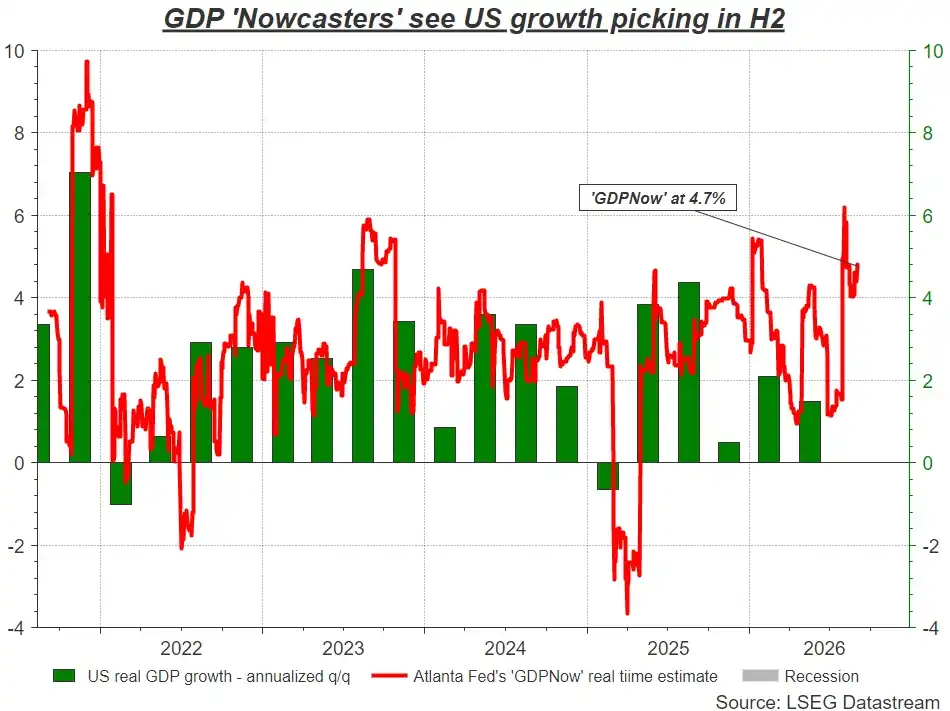
Even if one agreed with the call for rate cuts now, despite the cost-of-living issues, linking the Fed's hesitation to a threat to "stop trading with foreign countries" has left most commentators and investors questioning the President's grasp of basic economics.

"Clueless" or "Puppet"?

Perhaps Friday's post was just a hasty attempt to re-energize his latest offensive in the trade tariff war. But even then, deliberately weakening foreign economies by cutting off imports via tariffs or executive order could prompt those countries to cut rates while also potentially raising import prices at home. That wouldn't give the U.S. the world's lowest interest rates.

The market's lack of reaction to Trump's latest Fed comments might indicate investors are growing more skeptical and cautious about the President's increasingly outlandish posts. For example, Trump recently claimed to have "blown to pieces" Iran's Kharg Island oil hub, which turned out to be completely false.

So where does this leave Kevin Warsh? The Trump-appointed chair has struggled to establish his own credibility since taking office in May, with concerns about White House political pressure constantly looming over him.

However, Warsh seemed to lean noticeably hawkish in his recent keynote speech at Jackson Hole.

A rate hike now would not only highlight the Fed's commitment to its inflation target (regardless of how little consumer price inflation trends fluctuate this week) but also affirm Warsh's control over the central bank and help him create distance from the President.

"A 25bp hike is good PR. It ends the credibility narrative and months of speculation over whether Warsh is a puppet," wrote TS Lombard economist Dario Perkins. He noted that in the last 50 years, only Janet Yellen didn't raise rates within two months of becoming Fed chair.
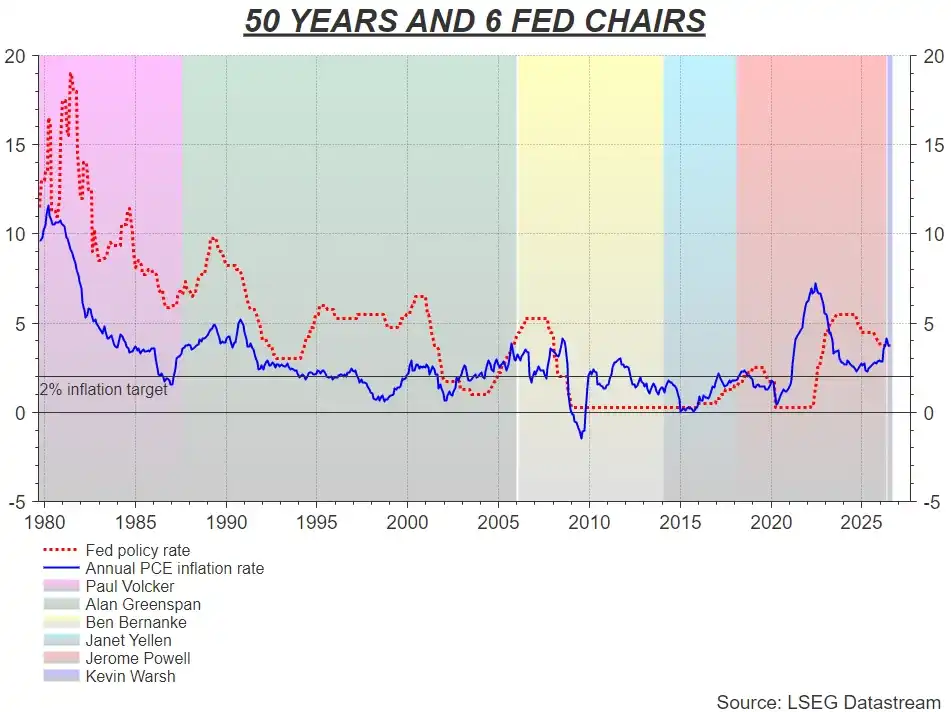
The perceived cost of the Fed and its current head being seen as cowed by a White House whose views are "hard to explain" outweighs any negative impact from a quarter-point hike. In fact, hiking now might even help lower long-term bond borrowing rates by reaffirming the Fed's inflation-fighting credibility, taking some pressure off Treasury Secretary Scott Bessent; and long-term rates arguably have a bigger impact on the economy than the policy rate.

"Warsh only gets credibility when Trump starts calling him an idiot!" Perkins added.

For now, Warsh still seems "great" in the President's eyes. But it took Trump only a year to go from praising Powell as "brilliant" to labeling him "clueless" as rates kept rising. Warsh faces significant choices, even if they risk angering the person who appointed him.

(These views are those of the author, Mike Dolan, a Reuters columnist.)

Пов'язані питання

QWhat is the main point made by the author regarding President Trump's recent criticism of the Federal Reserve?

AThe author argues that President Trump's illogical criticism of the Federal Reserve and his demand for rate cuts paradoxically provides an opportunity for Fed Chairman Kevin Warsh to raise rates, which would help him establish credibility and distance himself from the White House.

QAccording to the article, why is President Trump's argument for lower interest rates considered illogical?

ATrump's argument is considered illogical because it suggests a high-growth economy like the U.S. should have the world's lowest interest rates, while most economists believe the opposite is typically true due to inflationary pressures from an overheating economy. Furthermore, his threat to stop trade with countries running a deficit with the U.S. has no logical connection to Fed rate policy.

QWhat opportunity does Trump's critique create for Fed Chairman Kevin Warsh, according to the analysis?

ATrump's critique creates an opportunity for Warsh to lead the Fed in raising interest rates. This move could demonstrate the Fed's commitment to its inflation target, confirm Warsh's control over the central bank, and help him build personal credibility by distancing himself from political pressure from the White House.

QHow did the market react to President Trump's latest comments on the Federal Reserve, and what does this reaction suggest?

AThe market showed little reaction to Trump's latest comments. This lack of reaction suggests investors are becoming increasingly skeptical and cautious towards the president's more outlandish posts, as seen with his earlier false claim about bombing an Iranian oil hub.

QWhat is the significance of a potential rate hike for Fed Chairman Kevin Warsh's reputation, as highlighted in the article?

AA potential rate hike is significant for Warsh's reputation because it would serve as a strong public relations move. It could end the narrative questioning his credibility and speculation that he is a 'puppet' of the White House, ultimately helping him establish his independence and authority as Fed Chair.

Пов'язані матеріали

PhotonPay Obtains UK EMI License, Advancing Global Payment Operating System Layout

PhotonPay has obtained an Electronic Money Institution (EMI) license from the UK Financial Conduct Authority (FCA), marking a significant milestone in its global compliance strategy. With this license, PhotonPay can issue electronic money and provide payment services within the UK regulatory framework, strengthening its local financial capabilities and supporting global businesses with broader fund-flow solutions. The UK is a key financial hub connecting Europe and global markets, and as enterprises expand internationally, their financial needs are shifting from single cross-border transactions to integrated management of accounts, payments, foreign exchange, cards, and treasury. The EMI license reinforces PhotonPay's UK localization, enabling connections with local banks, payment networks, and financial partners. PhotonPay's Global Chief Compliance Officer JP noted that this license is a key step in building a global payment operating system backed by solid local regulatory foundations. PhotonPay is developing a next-generation payment operating system that unifies fragmented financial infrastructure across markets, allowing businesses to manage global accounts, collections, payments, FX, cards, and embedded finance more efficiently. Built on real business fund flows, PhotonPay continues to expand regulatory qualifications, banking partnerships, payment networks, and technology. To date, PhotonPay has secured nearly 30 payment licenses and regulatory qualifications worldwide, covering global accounts, payments, FX, cards, and embedded finance. The UK EMI license further strengthens its global compliance network as it continues building a next-generation global payment operating system.

marsbit39 хв тому

PhotonPay Obtains UK EMI License, Advancing Global Payment Operating System Layout

marsbit39 хв тому

US Treasury Survey Fails to Signal Debt Issuance Cuts, Treasury Yields Rise, 10-Year Back Above 5.12%

The U.S. Treasury's latest primary dealer survey did not signal an imminent reduction in long-term bond auction sizes, disappointing investors who bet the government would act to push down long-term rates. Treasury yields rose broadly, with the 10-year benchmark yield重回 above 5.12%, up 6.5 basis points intraday, while 20-year and 30-year yields also climbed. The survey was part of preparations for the quarterly refunding announcement on November 4. Markets had hoped for clues that Treasury Secretary Bessent might adjust long-term issuance, particularly the possibility of cutting or halting 20-year bond sales. Instead, Treasury only asked broadly what auction size adjustments should be considered, without clearly hinting at reduced long-term supply. Dealers were also asked about the long-term buyback program, improving buyback efficiency, timing of T-bill and floating-rate note issuance around FOMC meetings, and economic and financing outlooks. Analysts including RBC's Blake Gwinn and TD Securities' Molly Brooks said the questions were too broad and sent no substantive signal, with long-term auction changes unlikely before February 2027. Citi, however, maintained its forecast that Treasury would cut 20-year and 30-year auction sizes by $3 billion each in November. Rising oil prices also added upward pressure on yields. The market reaction was concentrated in long-dated Treasuries, which are especially sensitive to supply expectations. The November 4 refunding announcement is the next key focal point.

marsbit1 год тому

US Treasury Survey Fails to Signal Debt Issuance Cuts, Treasury Yields Rise, 10-Year Back Above 5.12%

marsbit1 год тому

Chainalysis Report: The $3 Trillion North American Crypto Landscape, AI and Stablecoins Reshaping Global Finance

Chainalysis’s 2026 North America report shows the region remains the world’s dominant crypto market, with $3.02 trillion in on-chain economic value over the year ending July 1, 2026. The U.S. accounts for $2.78 trillion, down 2.2% in a cyclical adjustment, while Canada grew 2.3% to over $247.7 billion. Three shifts stand out: AI agent commerce, dollar stablecoin exports, and tokenized real-world assets. The U.S. leads AI agent payments, with Base’s x402 protocol surpassing 138 million transactions and 88.1% of model-inference share. Micro-payments between machines are becoming viable, with most x402 transactions between $0.01 and $0.10. Wallet behavior shows rising stickiness: 89.3% of new wallets received a second funding within 30 days in Q2 2026, and the median time from funding to first payment fell from 73 days to 18 minutes. China-linked wallets dominate security and code analysis at 90%, while the U.S. leads inference and agent frameworks. Capital flows show the U.S. importing bitcoin and exporting digital dollars: large institutional bitcoin inflows totaled 53,200 BTC, while USDC circulation reached $73.3 billion and quarterly on-chain settlement hit $14.8 trillion. Tokenized U.S. Treasuries dominate RWA at $15.42 billion, 42.8% of the total, with overseas retail buyers prominent. Canada emerges as the G7’s top P2P market, driven by immigrants; stablecoin remittances to India, China, and the Philippines reached $2.36 billion, up 141%. Overall, the U.S. builds infrastructure while the world adopts it.

marsbit2 год тому

Chainalysis Report: The $3 Trillion North American Crypto Landscape, AI and Stablecoins Reshaping Global Finance

marsbit2 год тому

Торгівля

Спот
活动图片