Author:Castle Labs
Compiled by: TechFlow
TechFlow Insight: The trading volume of RWA perpetual contracts has surged 120 times within a year, but the unpredictability of funding rates and the cold start of liquidity have been persistent pain points. The recently launched swap product by Variational directly connects to traditional financial market makers, turning unpredictable funding rates into annualized holding costs. This could be a watershed event for institutions and market makers seeking compliant entry into on-chain RWA trading.
Perpetual contracts have become one of the most powerful tools in digital asset trading. They are capital efficient, allowing users to gain price exposure without holding the underlying asset.
Initially, perpetual contracts competed within the same arena, focusing on crypto assets and liquidity.
As perpetual contracts expanded to more assets, especially real-world assets (RWAs), the competitive landscape broadened, giving rise to different strategies for evolving markets.
This category has already extended to stocks, commodities, indices, forex, Pre-IPO markets, and other assets not naturally suited for crypto-native exchange models.
In fact, there are significant differences between RWAs and crypto-native assets when it comes to listing them as perpetual contracts. Launching these markets through ordinary order books requires a cold start of liquidity for each venue, typically achieved through subsidies, incentives, and external market maker relationships.
Essentially, platforms wanting to launch RWA perpetuals must find solutions for 7x24 trading outside traditional trading hours, ensuring sufficient liquidity for newly launched markets.
Moreover, perpetual contracts are not ideal instruments for RWA trading. The unpredictability of funding rates is a major pain point for RWA perpetuals.
Among the teams trying to solve these problems, Variational has just launched its Swap product, their solution to support a growing list of markets without having to rebuild each market and its liquidity from scratch, while providing traders with predictable costs.
Contrary to what the name might suggest, this is not about AMM swaps. Swaps have long existed in traditional finance. For Variational users, a Swap is a new way to trade RWAs with predictable costs, and liquidity sourced directly from traditional finance.
This report first highlights the growth of RWA perpetuals and their rising market share, then delves into Swaps, comparing them with perpetuals and explaining what makes them unique.
Next, by comparing order execution across different perpetual platforms, we translate this implementation into tangible advantages users can actually experience.
RWA Perpetuals: From Niche Category to One-Eighth of On-Chain Perpetual Trading Volume
RWA perpetuals have grown from a niche category to a structurally significant portion of crypto trading in less than a year. In October 2025, this category had less than $1 billion in trading volume, but by August, the volume exceeded $120 billion, a 120x increase within a few quarters.
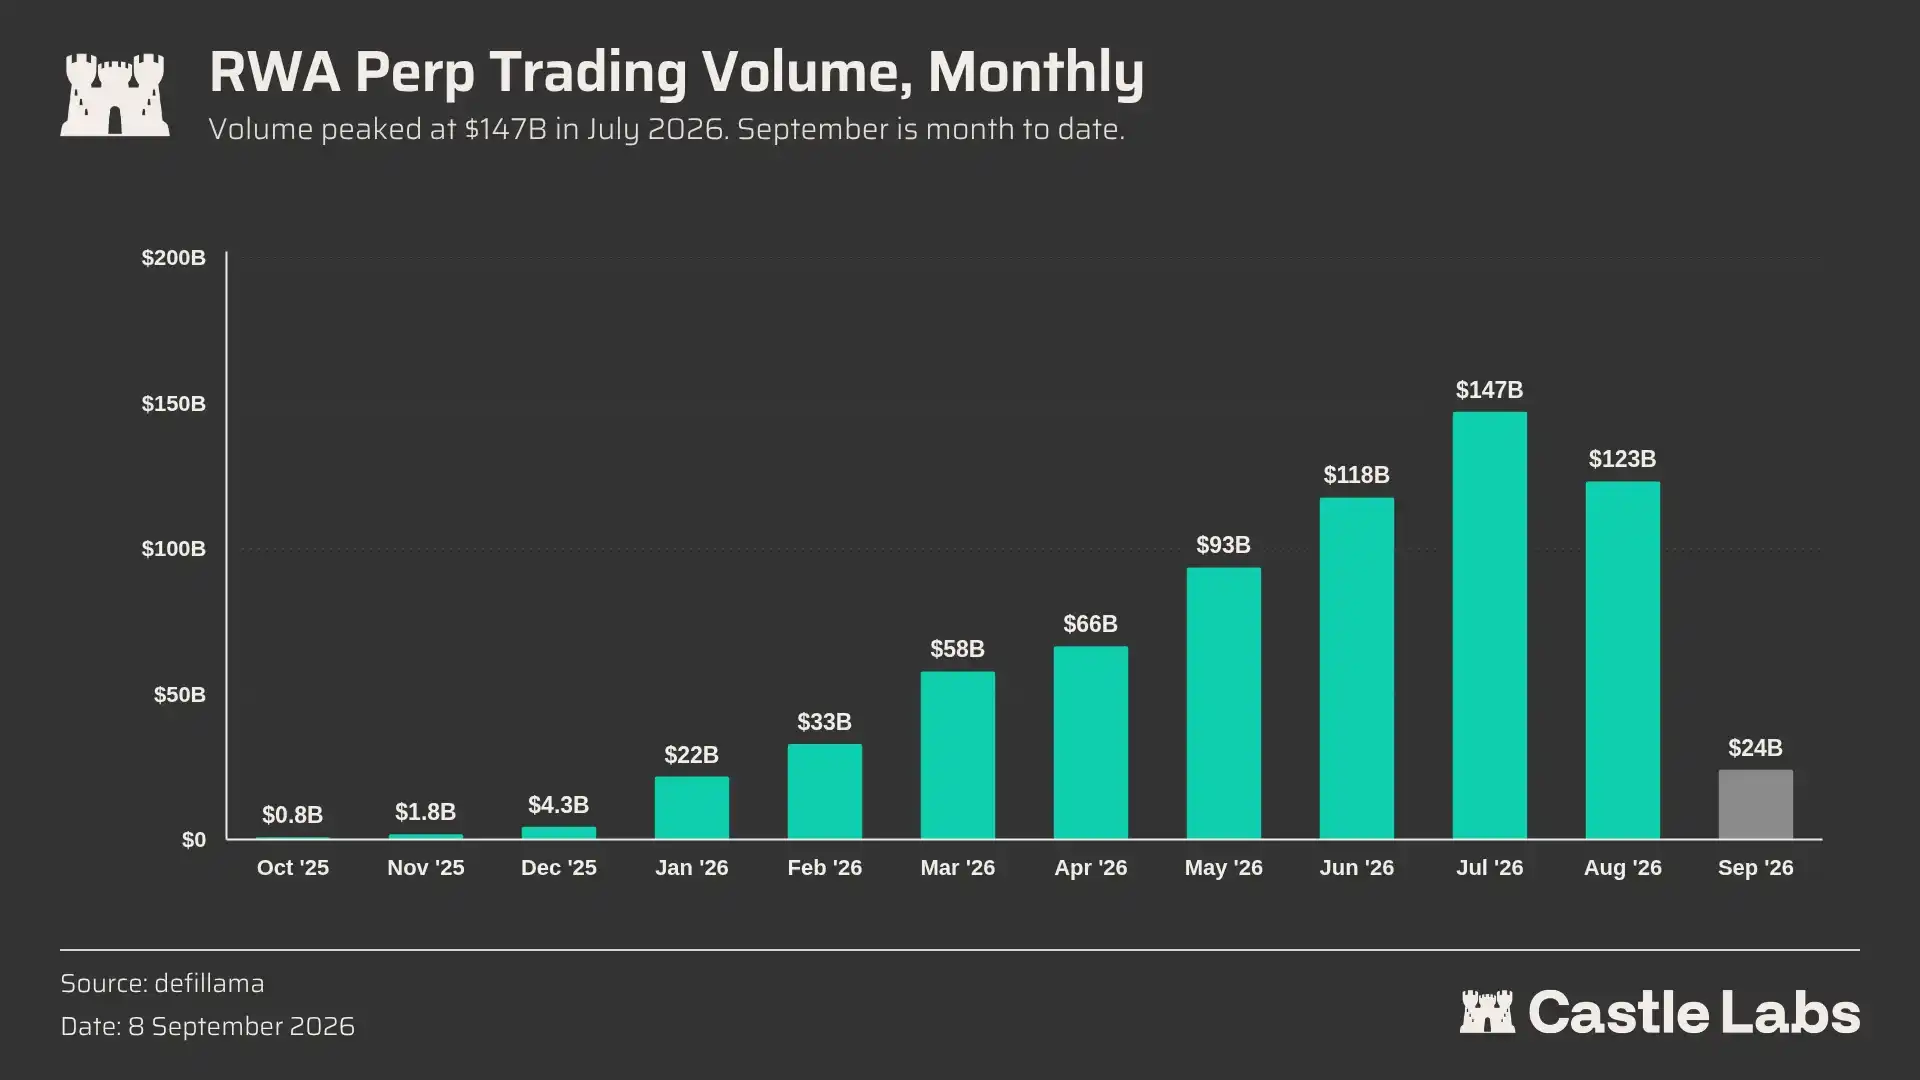
Chart: Monthly trading volume of RWA perpetual contracts (Oct 2025 – Sep 2026), peaking at $147 billion in July 2026. Source: DefiLlama; Date: Sep 8, 2026.
This category saw its first inflection point last October when TradeXYZ launched as a HIP-3 deployer on Hyperliquid. Since then, growth has been continuous, reaching a peak of 20% of on-chain perpetual trading volume in July, averaging around 12%-13% in most months. This means that for every $8 traded in on-chain perpetuals, nearly $1 comes from RWAs. Additionally, over the past few months, it has established a base trading volume level of $100 billion since June.
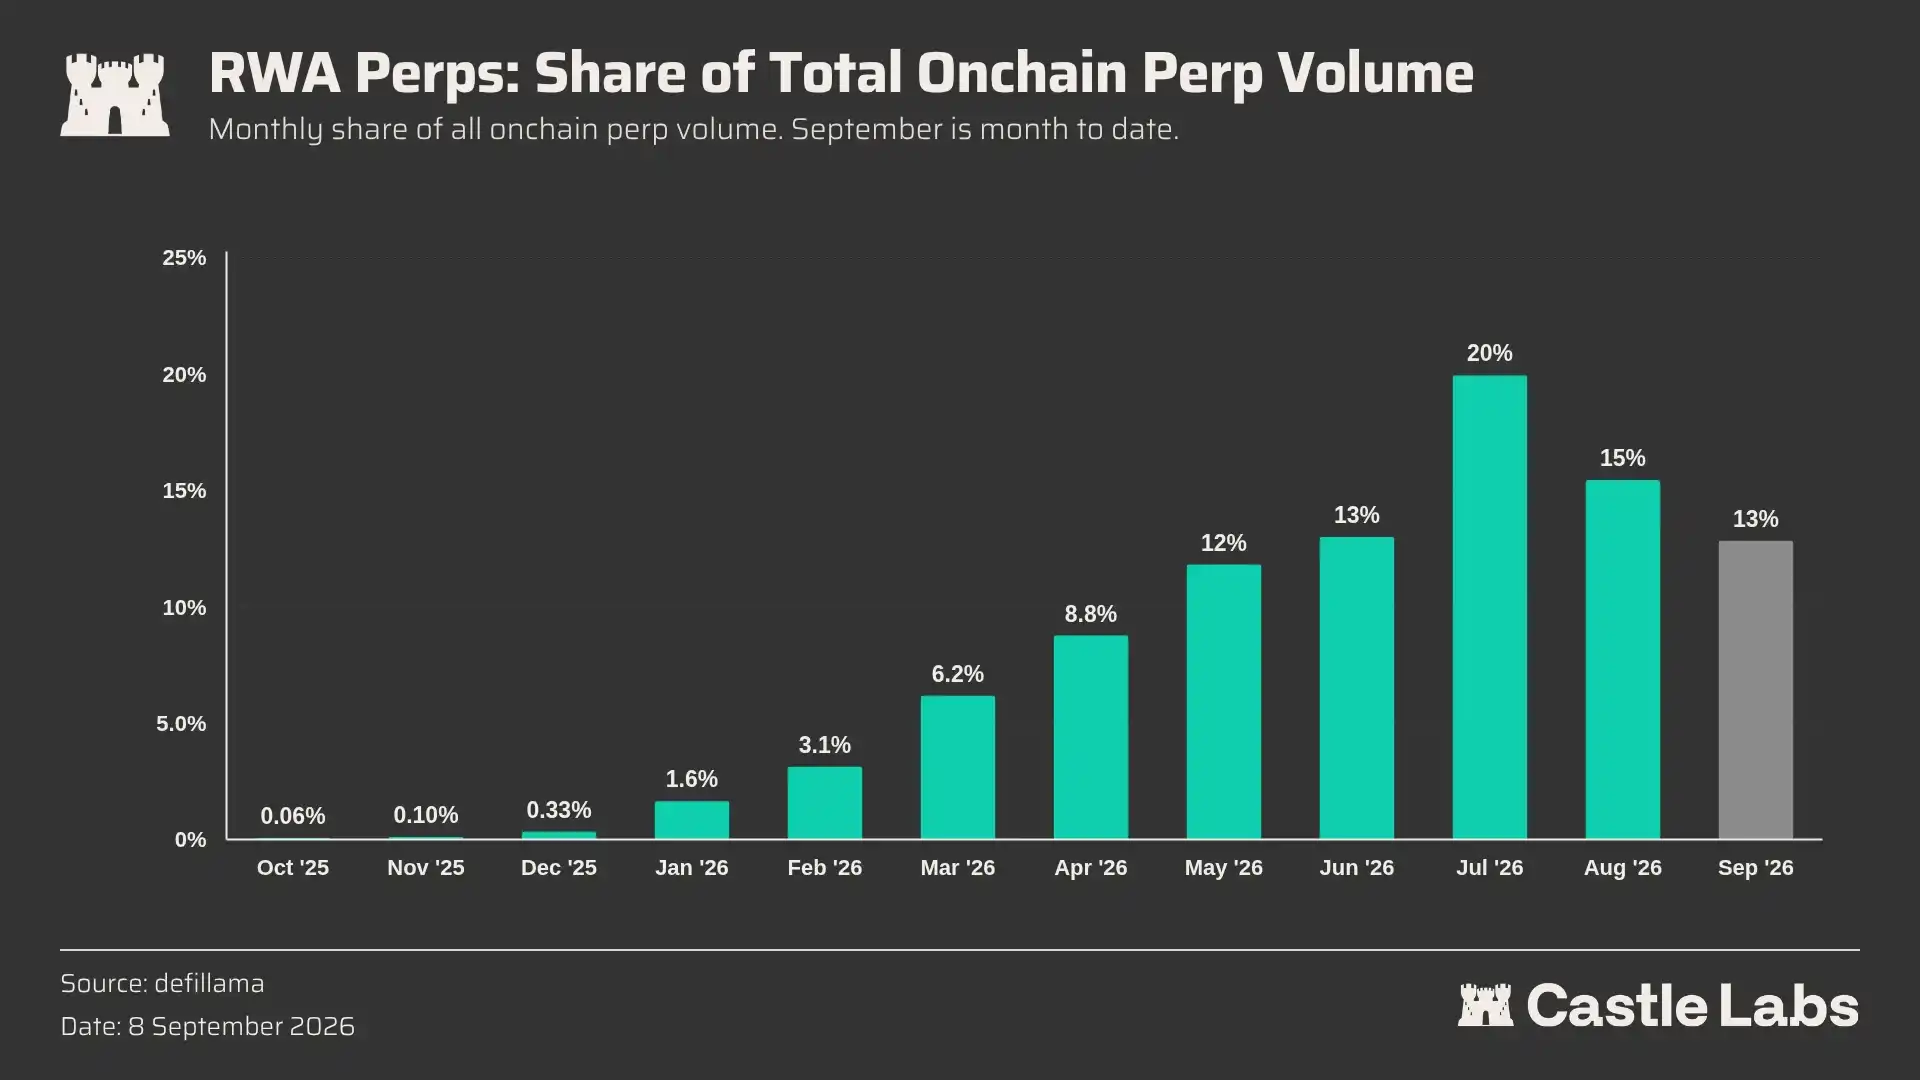
Chart: Monthly share of RWA perpetual contracts in total on-chain perpetual trading volume (Oct 2025 – Sep 2026), peaking at 20% in July 2026. Source: DefiLlama; Date: Sep 8, 2026.
Despite this rapid growth, the category remains highly concentrated. To date, the total open interest for RWA perpetuals is $4.9 billion, with the top two protocols, TradeXYZ and Variational, accounting for nearly 90% of the open interest, followed by GMTrade, Lighter, Ondo, and others.
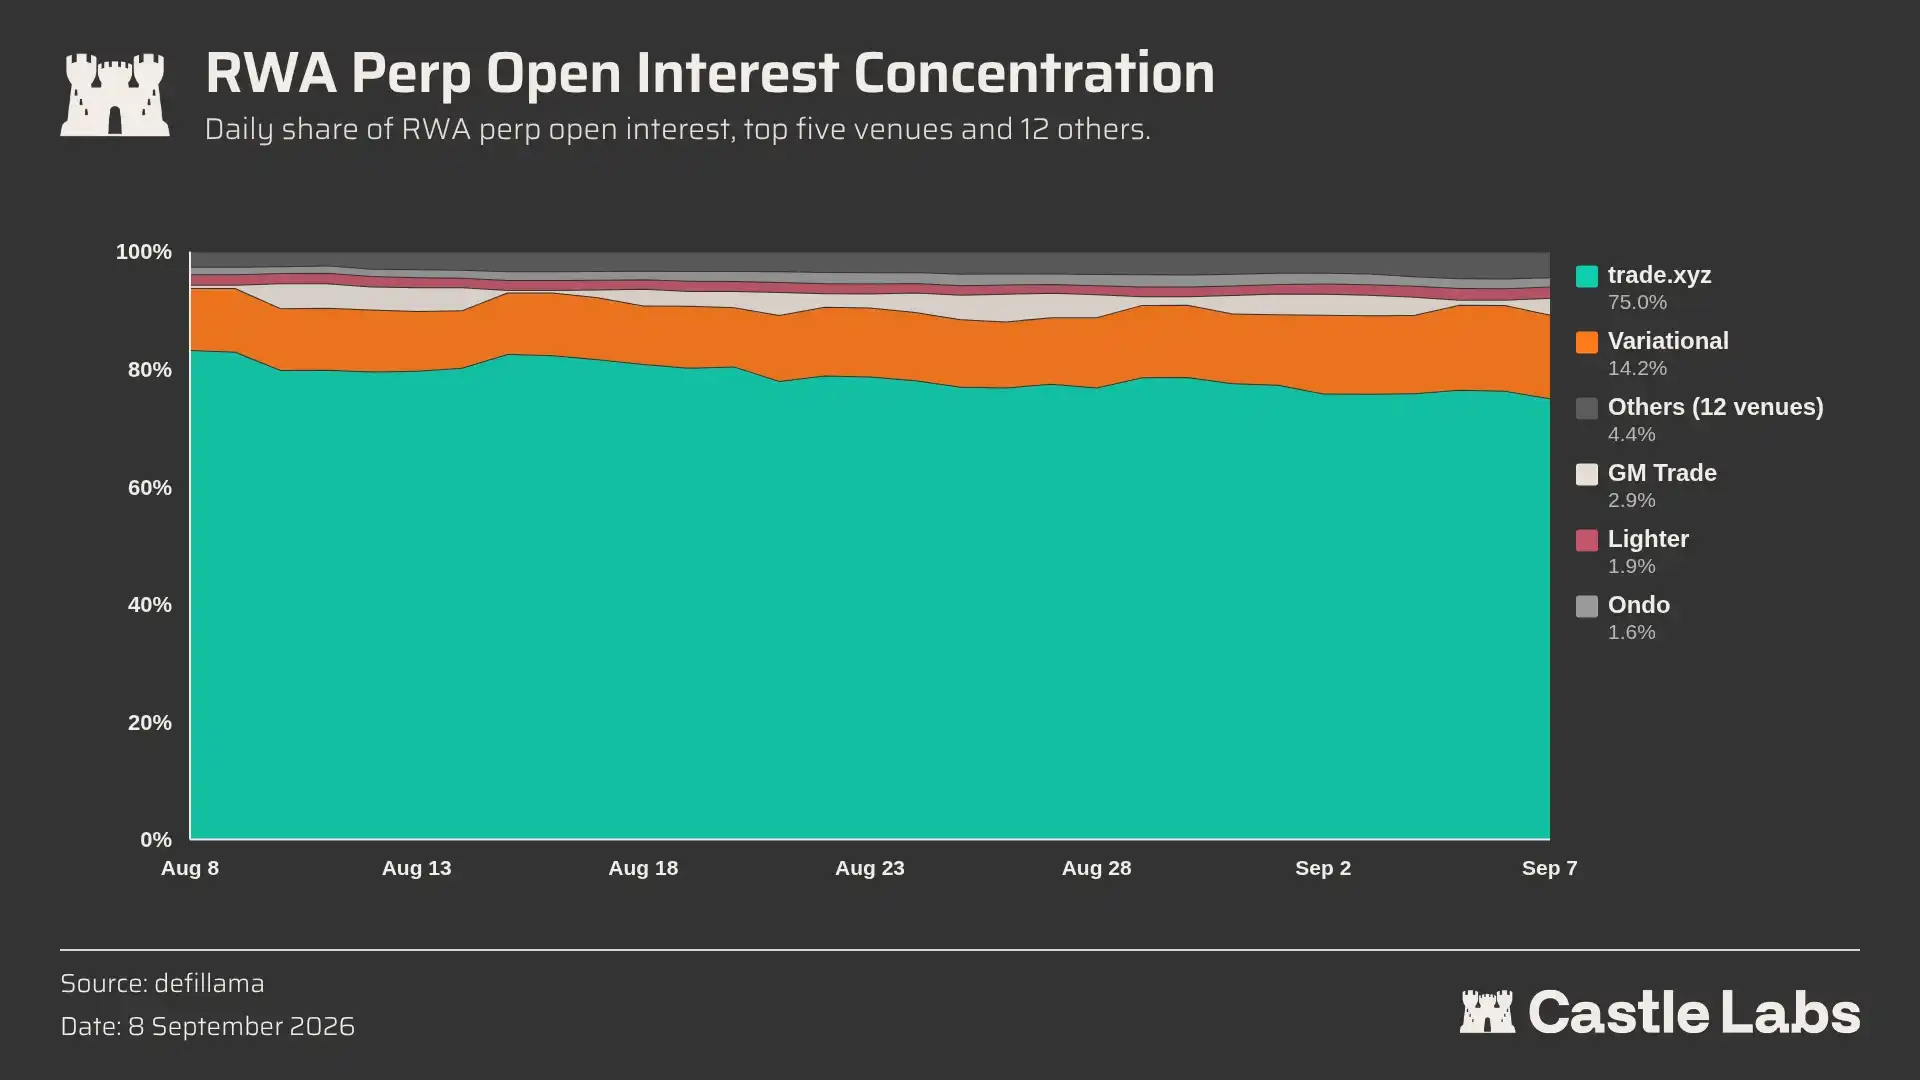
Chart: Concentration of RWA perpetual open interest (Top 5 platforms + Others), Trade.xyz accounts for ~75%, Variational ~14.2%. Source: DefiLlama; Date: Sep 8, 2026.
We expect this category to continue growing, with Variational Swaps being a major contributor. In the next section, we differentiate Swaps from perpetuals and explain why the former is a superior way to trade RWAs on-chain.
Swap or Perpetual?
This section defines Swaps as a new primitive, highlighting their differences from perpetuals as trading instruments.
At their core, both are "linear derivatives," meaning their payoff is a linear function: changes in the asset's price translate into the dollar value generated by the contract.
However, there is a fundamental difference in what perpetuals and swaps track.
Perpetuals were created to closely track the index price of the underlying asset. Therefore, they use funding rates to encourage rebalancing and closely follow the spot asset's index price.
Swaps, on the other hand, are used to "track the total return of an asset over a period of time."
This manifests in differences in funding rates. Compared to traditional perpetuals, Swaps charge a fee on positions only once per day, at the close (5 PM ET).
Unlike perpetual funding rates, which depend on supply and demand, Swap fees are better understood as a holding cost, calculated based on the "real cost of financing the underlying asset in traditional markets."
For stocks, this means the overnight rate of the index currency (e.g., SOFR for USD). For forex, it's the overnight interest rate differential between currencies, adjusted for the spread. For metals, it's the implied cost of borrowing or lending USD overnight.
These rates are strictly linked to traditional finance because they represent real market-based financing terms that Variational obtains from its TradFi liquidity partners.
Last but not least, Swaps also allow users to receive dividends: long positions receive the dividend amount, short positions pay it.
Initially, Swap markets will use isolated margin and have specific opening and closing times. Variational expects these markets to gradually move towards 7x24 operation and achieve cross-margin within the platform.
The first batch of Swap markets launched are US100, US500, XAU, XAG, and USOIL. Since their launch earlier this month, these markets have contributed $3.8 billion in trading volume, with a peak open interest of $245 million.
For Variational, evolving from perpetuals to Swaps was a necessary step, given that TradFi perpetuals already accounted for over 50% of its trading volume and open interest just two months after launch.
Instead of relying on supply-demand dynamics and frequent funding payments, Variational focuses on directly tapping into TradFi liquidity, turning volatile funding rates into annualized, predictable holding costs, making RWAs more accessible for institutional investors.
In summary, both Swaps and perpetuals can provide exposure to underlying assets.
Swaps source liquidity from a network of traditional finance partners, and funding rates are replaced by daily fees, which can be likened to a stable holding fee, "primarily anchored to USD borrowing costs."
Typically, in the launched Swap markets, this results in longs paying 4%-6% annually, while shorts earn 2%-3%.
An important note before proceeding: Swaps do not operate in isolation. To fully understand them, the next section delves into the Omni Liquidity Provider and how it symbiotically operates with Swaps.
Omni & Swap
Most perpetual exchanges need to bootstrap liquidity within their own platform. This works for mainstream assets, but problems arise once a platform tries to list more assets. Each new market requires market makers, inventory, incentives, risk limits, and enough two-way demand to support a deep order book.
A key differentiator for Swaps lies in how they source liquidity, which is also why they can offer better execution.
Variational avoids liquidity shortages through Request-for-Quote (RFQ) execution and its vertically integrated liquidity provider, Omni.
The Omni Liquidity Provider (OLP) is Variational's proprietary, integrated market maker.
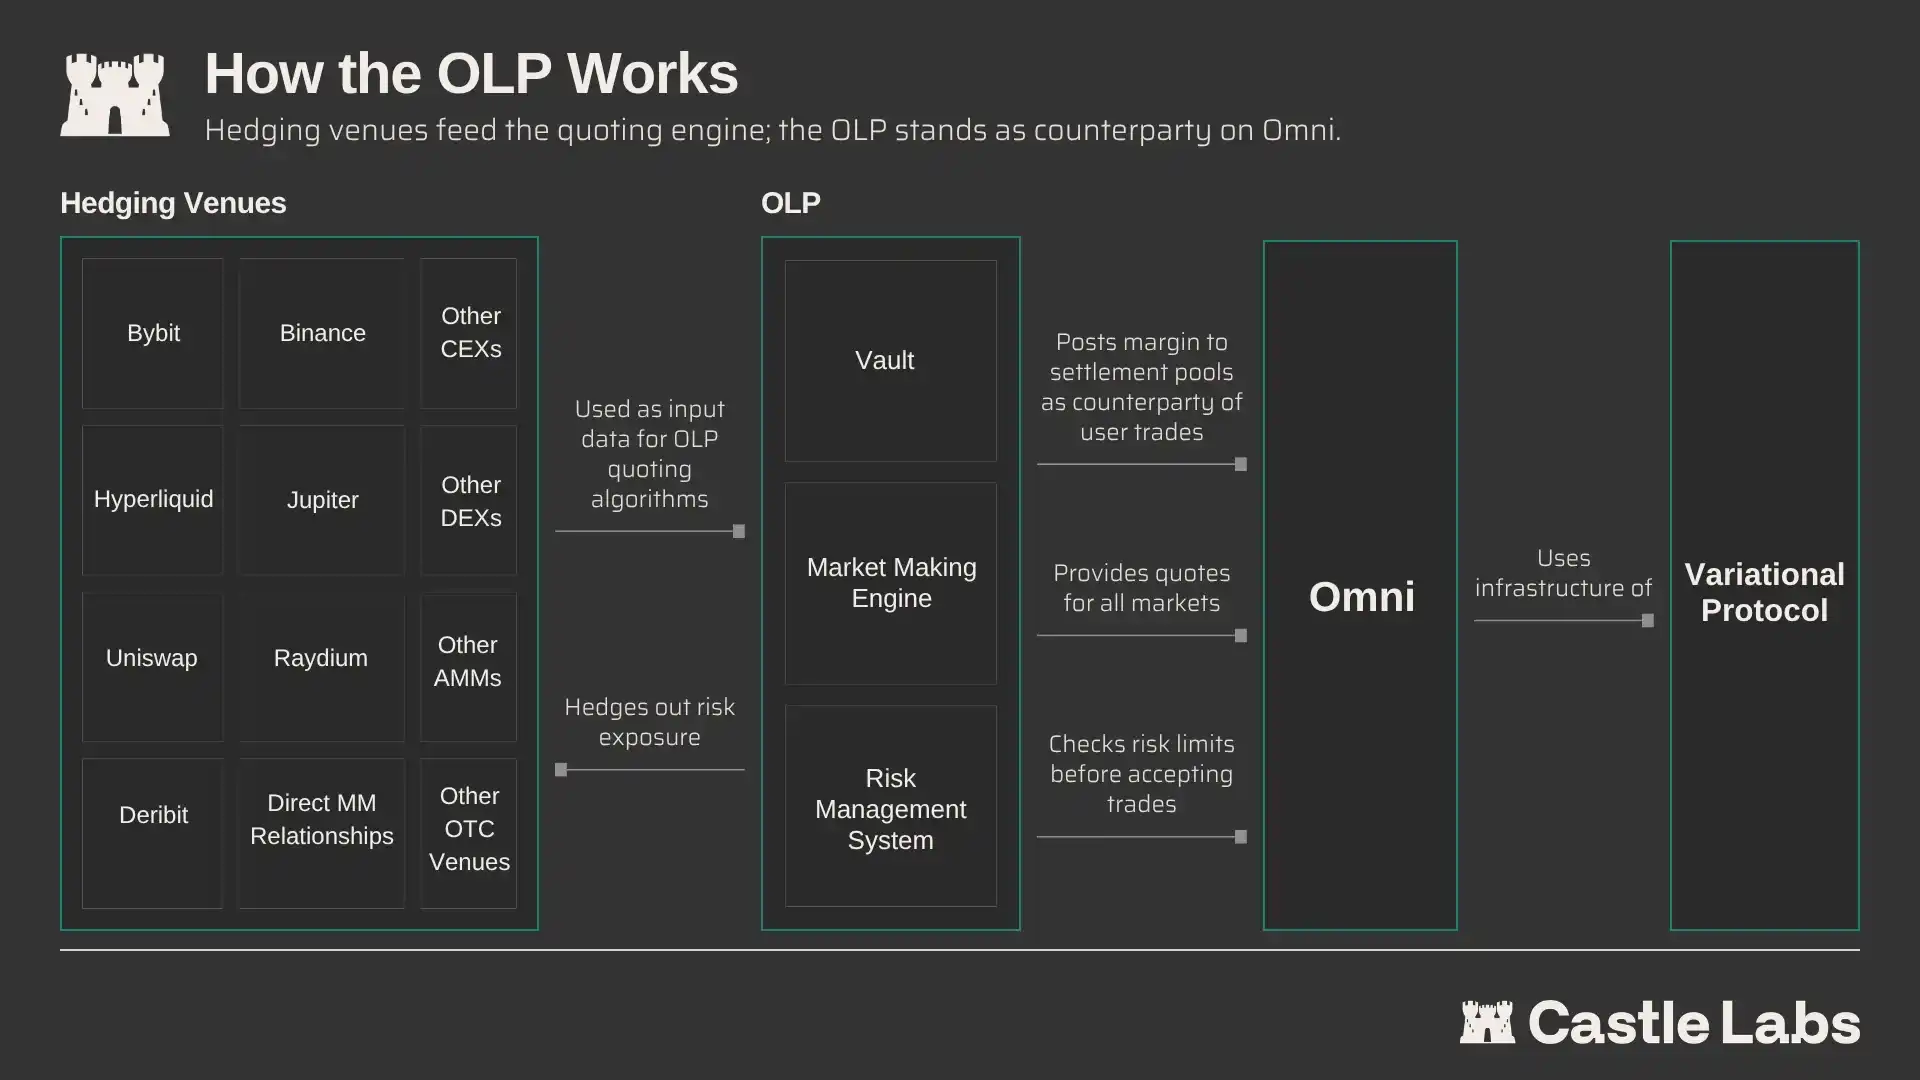
Diagram: How OLP (Omni Liquidity Provider) works: Hedge venues feed the quote engine, and OLP acts as the counterparty on Omni. Source: Variational / Castle Labs.
The OLP interfaces directly with liquidity providers in Variational's RFQ system, bringing that liquidity on-chain. Since the OLP is the counterparty to all trades on Omni, initial Swap markets had an open interest cap of $10 million (to be raised quickly) to give the team time to test the OLP's hedging strategies. The OLP uses external liquidity from centralized exchanges, decentralized exchanges, and TradFi sources to manage and hedge its risk.
Variational aggregates Swap liquidity from TradFi venues, so initially these instruments will follow traditional market hours. As more liquidity venues are aggregated and traditional markets continue evolving towards 24/7 trading, round-the-clock trading is expected.
The benefits of this approach are evident: Variational can launch new markets without building order books from scratch. Instead, they only need price feeds, reliable partners in the RFQ system, and hedging strategies for the OLP.
This design is not about taking on liquidity risk but involves trade-offs in pricing transparency and risk management.
In the next section, we test whether this holds true in practice by comparing order execution costs for Variational Swaps against other perpetual trading venues.
Swaps significantly reduce execution costs on Variational, making the cost of trading TradFi perpetuals 8 to 12 times lower than on the most liquid on-chain venues.
If you have been following our research, you should know this is the most critical aspect for anyone trading RWAs. While RWAs offer many advantages, including transparency, global accessibility, and execution efficiency, these on-chain assets ultimately need to be evaluated on whether their execution can match, or even surpass, their counterparts in TradFi.
Comparative Analysis of Swap vs. Perp Execution Costs
Perps are better suited for 24/7 crypto-style markets, where funding rates are determined by exchange supply and demand. In contrast, Swaps are more suitable for traditional assets, where financing costs, dividends, and external liquidity are more important.
The most compelling claim about Variational Swaps is not only that they offer more markets but also that they can provide better execution.
To measure this carefully, we compare the execution cost of Variational Swaps with major on-chain venues listing TradFi perpetuals. Our platform sample includes major on-chain perpetual trading venues such as TradeXYZ, Lighter, and Ostium.
Methodology
In our market sample, we analyzed and compared the US100, US500, XAU, and XAG markets, along with their corresponding products on other exchanges. Since venues execute orders differently, the measurement of execution cost also varies.
For order book-based venues like TradeXYZ and Lighter, we captured the order book in real-time, sorted it, and iterated through the levels to simulate market orders on the book. For quote-based venues like Variational and Ostium, we used the published quotes for different sizes.
We measured execution cost by averaging the cost for both long and short positions. This gives us a more comprehensive view of the actual state of quotes and order books.
Analysis
Some venues (like Lighter and Variational) do not charge any trading fees, so their execution cost is solely calculated from the spread. Other platforms charge fees, which increases execution cost.
The first market we analyzed is US100.
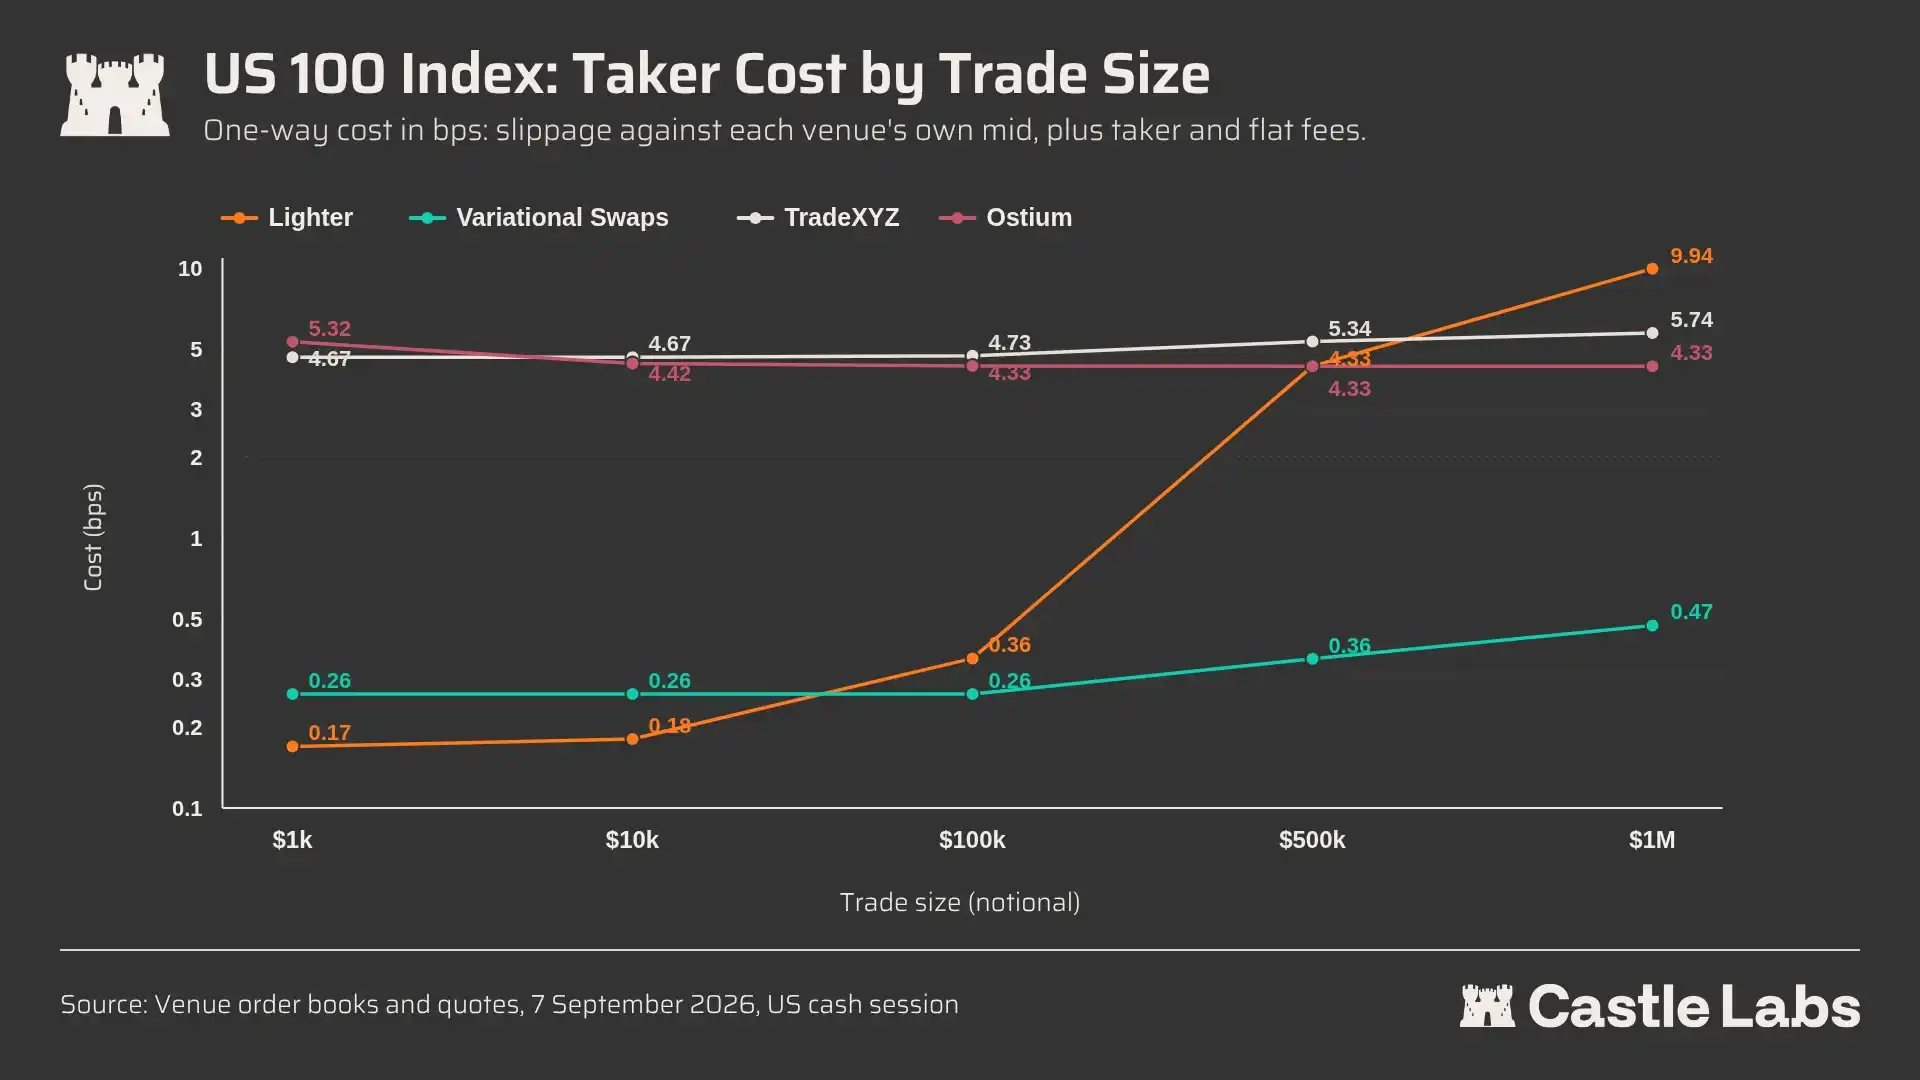
Chart: Taker cost (bps) for the US100 index across different trade sizes. Source: Various venues' order books & quotes, US market hours, Sep 7, 2026; Castle Labs.
For smaller sizes like $1,000 and $10,000, Lighter is the cheapest venue, charging 0.18 bps, but its execution cost rises quickly, from 0.36 bps for $100,000 to over 9.94 bps for a $1 million trade. Due to their fee structures, Ostium and TradeXYZ are the most expensive venues for small trades, charging 5.32 bps and 4.67 bps, respectively.
In contrast, Variational Swap's cost rises slowly, from 0.26 bps for a $1,000 trade to 0.47 bps for a $1 million trade, making it 12 times cheaper than TradeXYZ (5.74 bps) and nearly 21 times cheaper than Lighter (9.94 bps).
Similar trends were observed in other markets, such as US500.
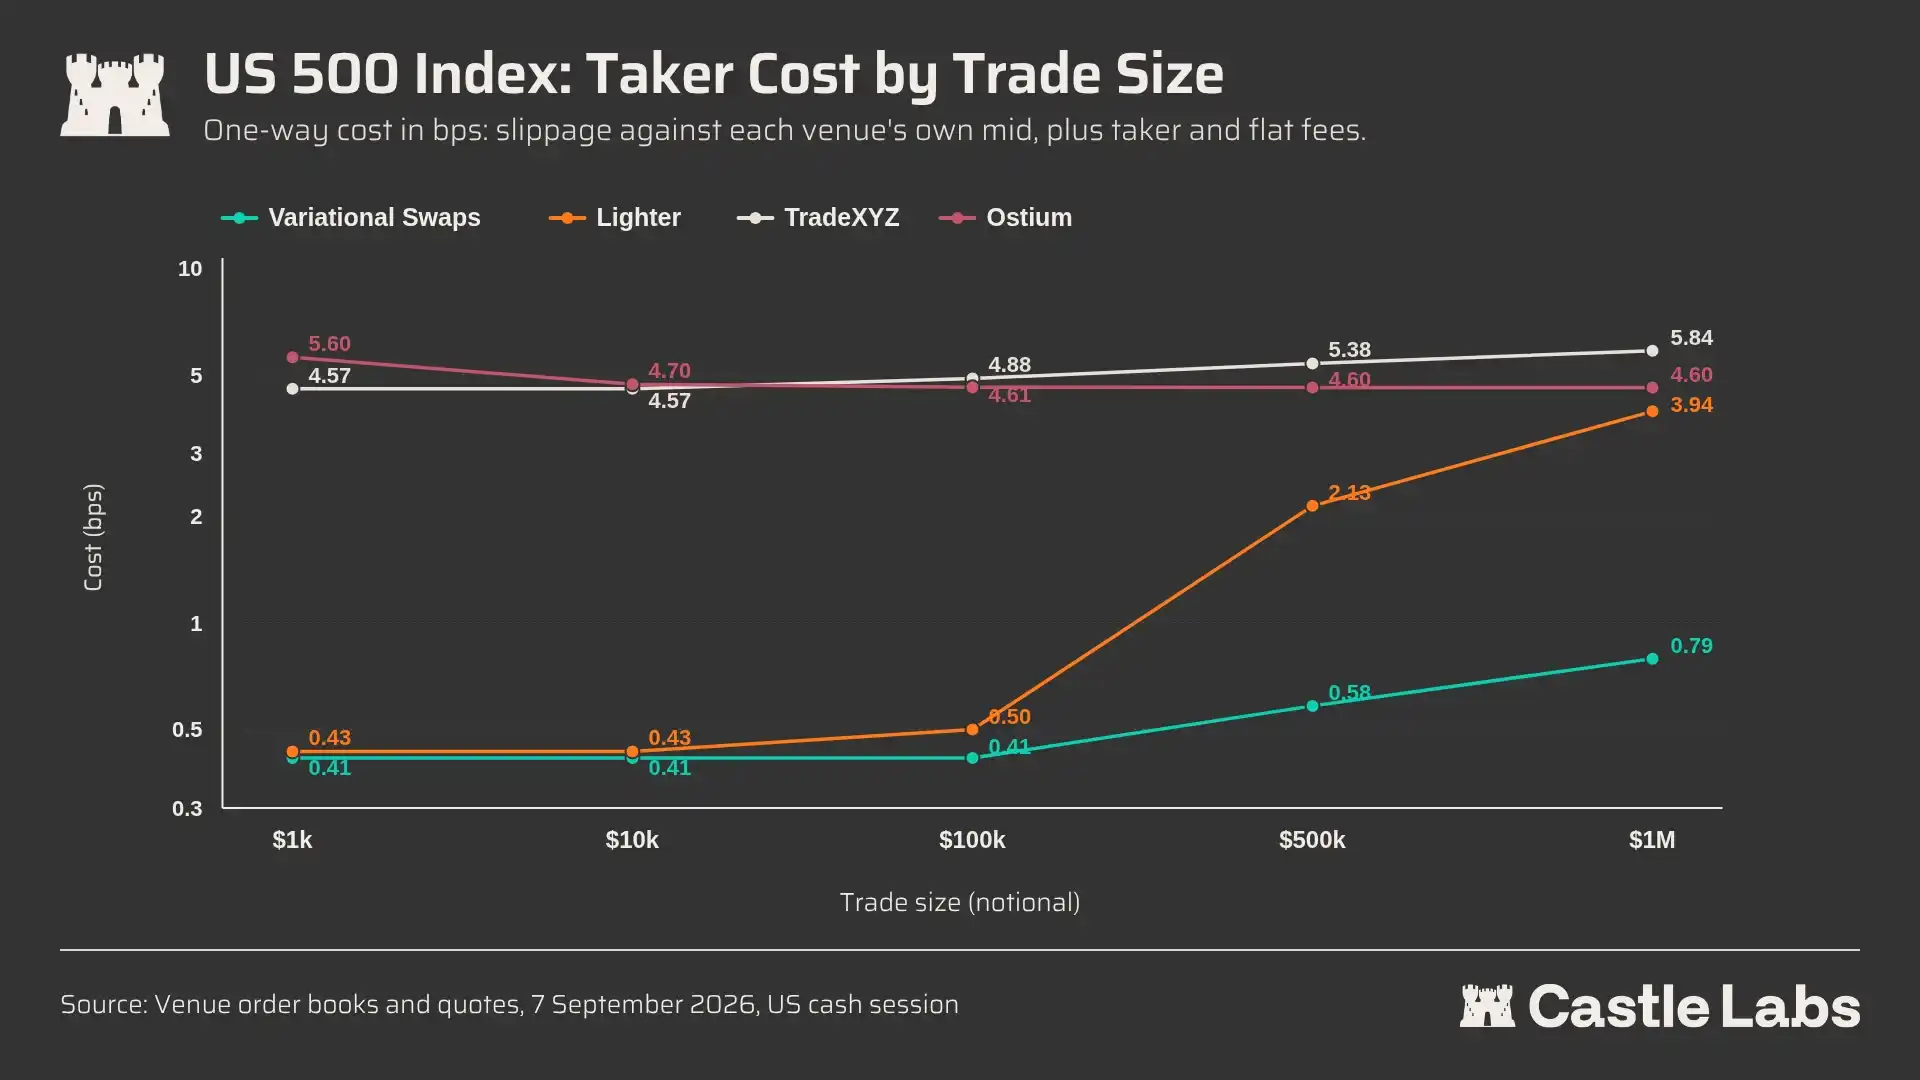
Chart: Taker cost (bps) for the US500 index across different trade sizes. Source: Various venues' order books & quotes, US market hours, Sep 7, 2026; Castle Labs.
In this specific case, Variational is the cheapest venue at every size, including $1,000 and $10,000 (0.415 bps vs. Lighter's 0.433 bps).
The gap between the two platforms is small at smaller sizes but widens to 5x by $1 million. This translates to a significant cost difference: $79 vs. $395 in execution cost. TradeXYZ and Ostium charge 5.84 bps and 4.60 bps, respectively.
Next, we analyze Silver (XAG) across platforms.
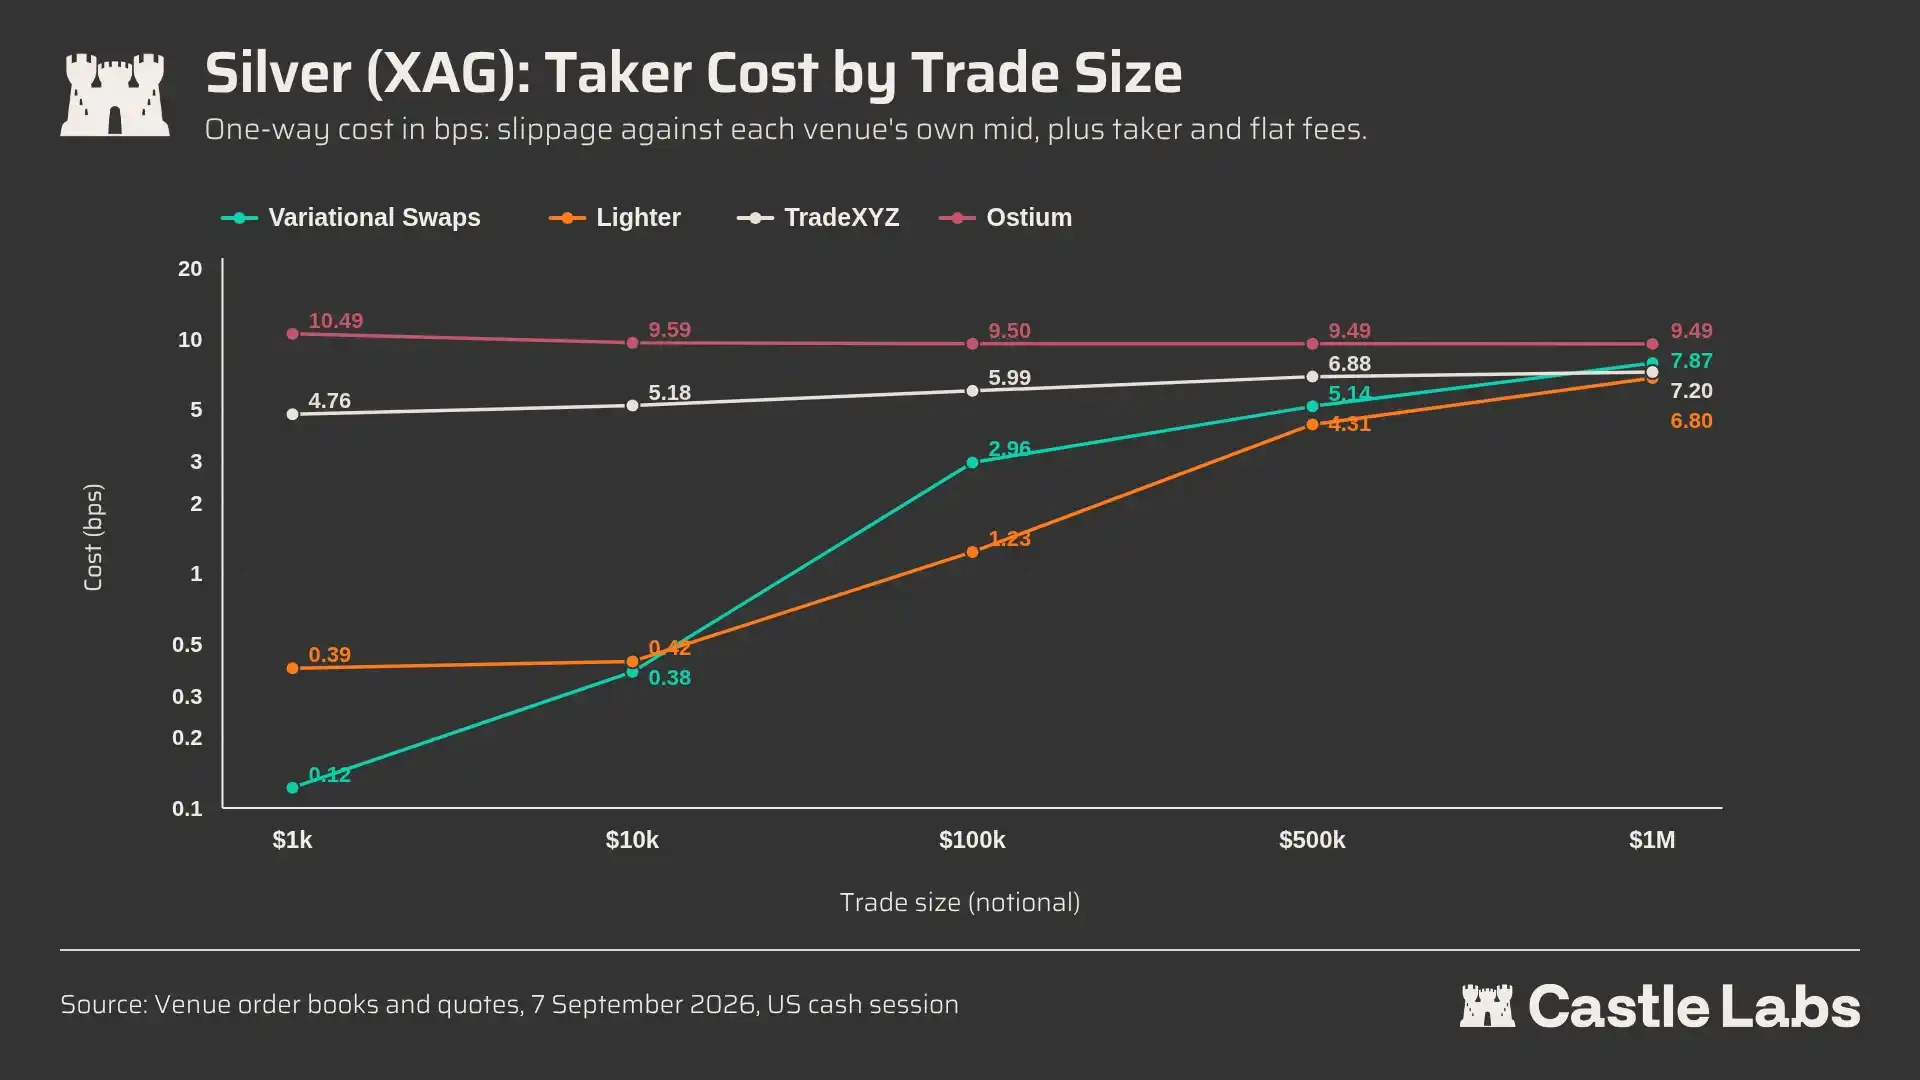
Chart: Taker cost (bps) for Silver (XAG) across different trade sizes. Source: Various venues' order books & quotes, US market hours, Sep 7, 2026; Castle Labs.
Variational is the cheapest venue at $1,000 (0.12 bps) and $10,000 (0.38 bps), but its execution cost rises at the $100,000 size, surpassing Lighter and becoming more expensive at larger sizes. A $500,000 order on Variational costs 5.14 bps, compared to 4.31 bps on Lighter, a difference of about 20%. XAG is currently the shallowest among the launched Swap markets, lacking the smooth quote profile of other markets. We expect these results to generalize to other markets as XAG grows.
Next is the Gold (XAU) market, which performs similarly to the US100 and US500 indices.
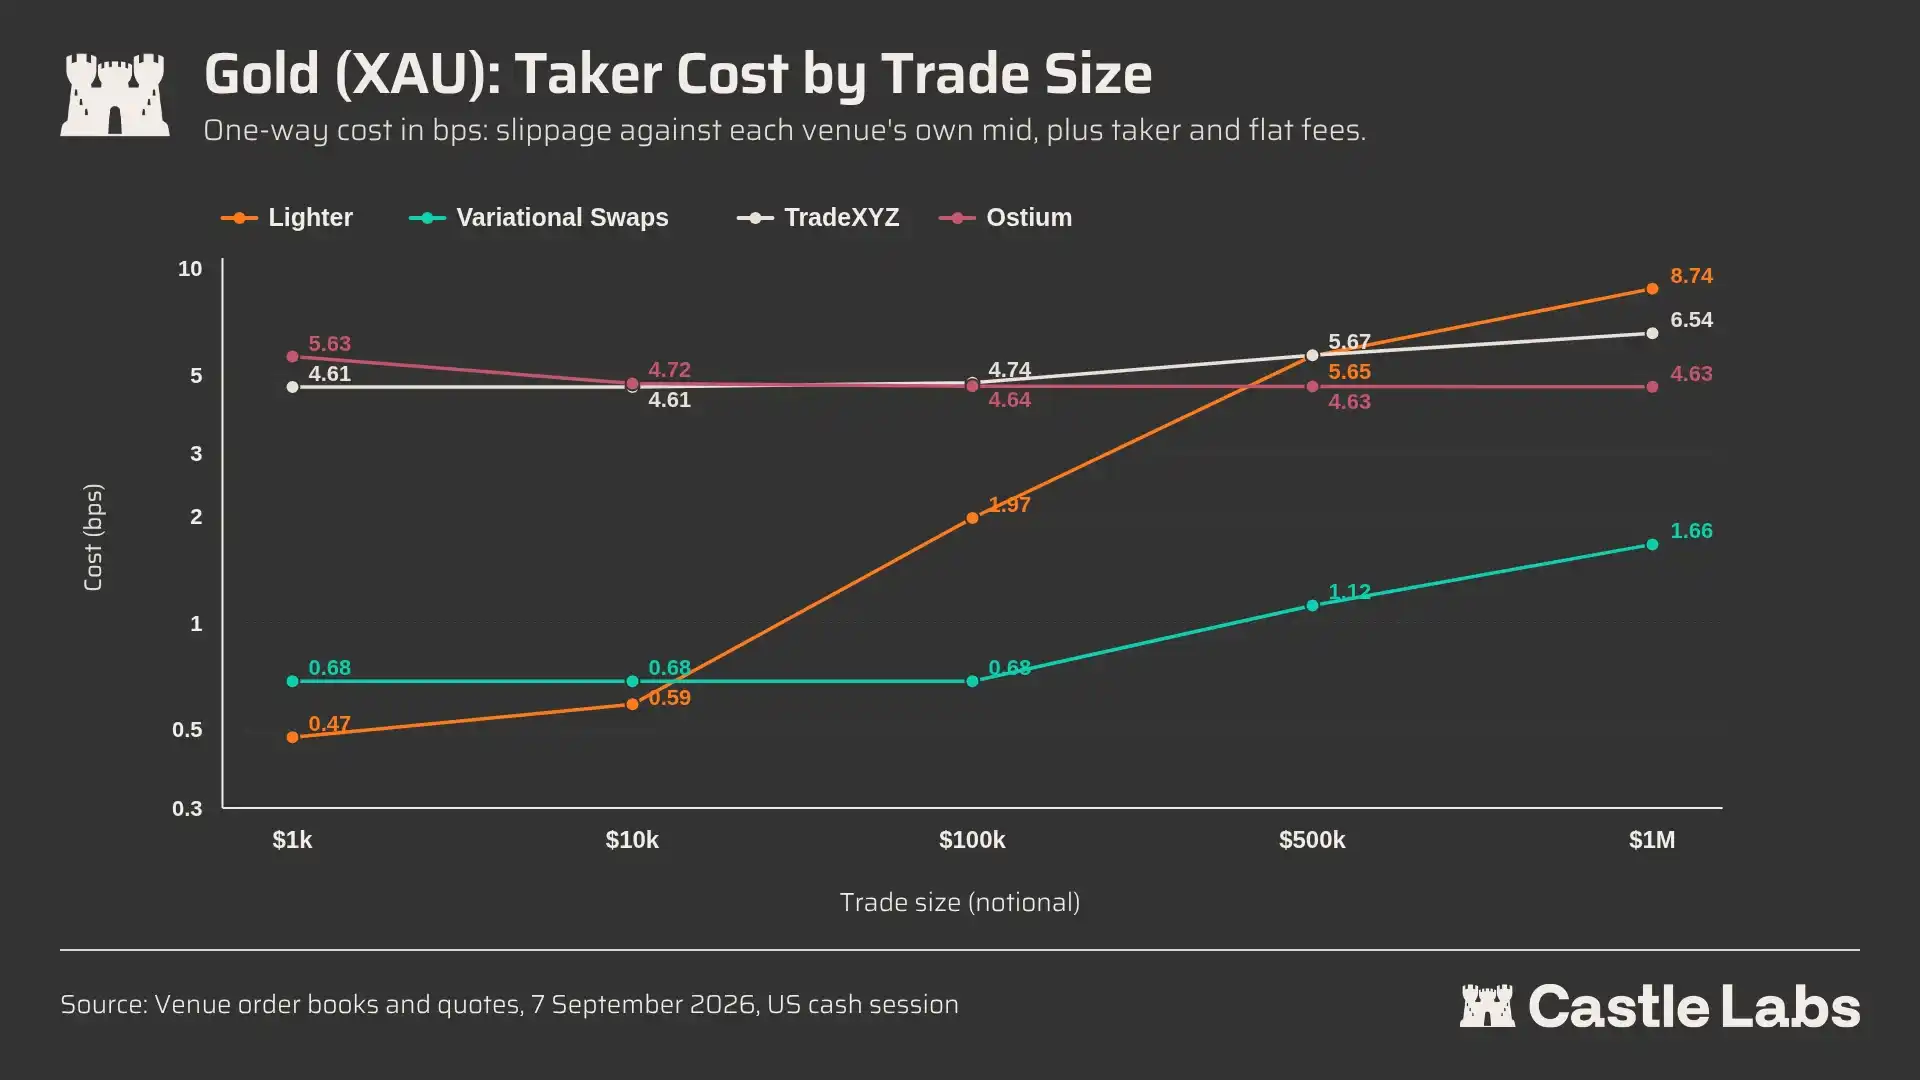
Chart: Taker cost (bps) for Gold (XAU) across different trade sizes. Source: Various venues' order books & quotes, US market hours, Sep 7, 2026; Castle Labs.
For smaller orders of $1,000 and $10,000, Lighter is the cheapest alternative, with opening costs of $0.05 and $0.60, respectively. Variational leads for larger sizes above $100,000, with a cost of only 0.68 bps, 65% lower than Lighter. Variational also maintains its lead for orders up to $1 million, with a fee of 1.66 bps, significantly below competitors: Ostium is closest at 4.63 bps, while TradeXYZ charges 6.54 bps, and Lighter soars to 8.74 bps. In most markets, Variational is the cheapest venue for larger orders, while Lighter leads for small orders (e.g., $1,000 and $10,000) in assets like Gold and US100.
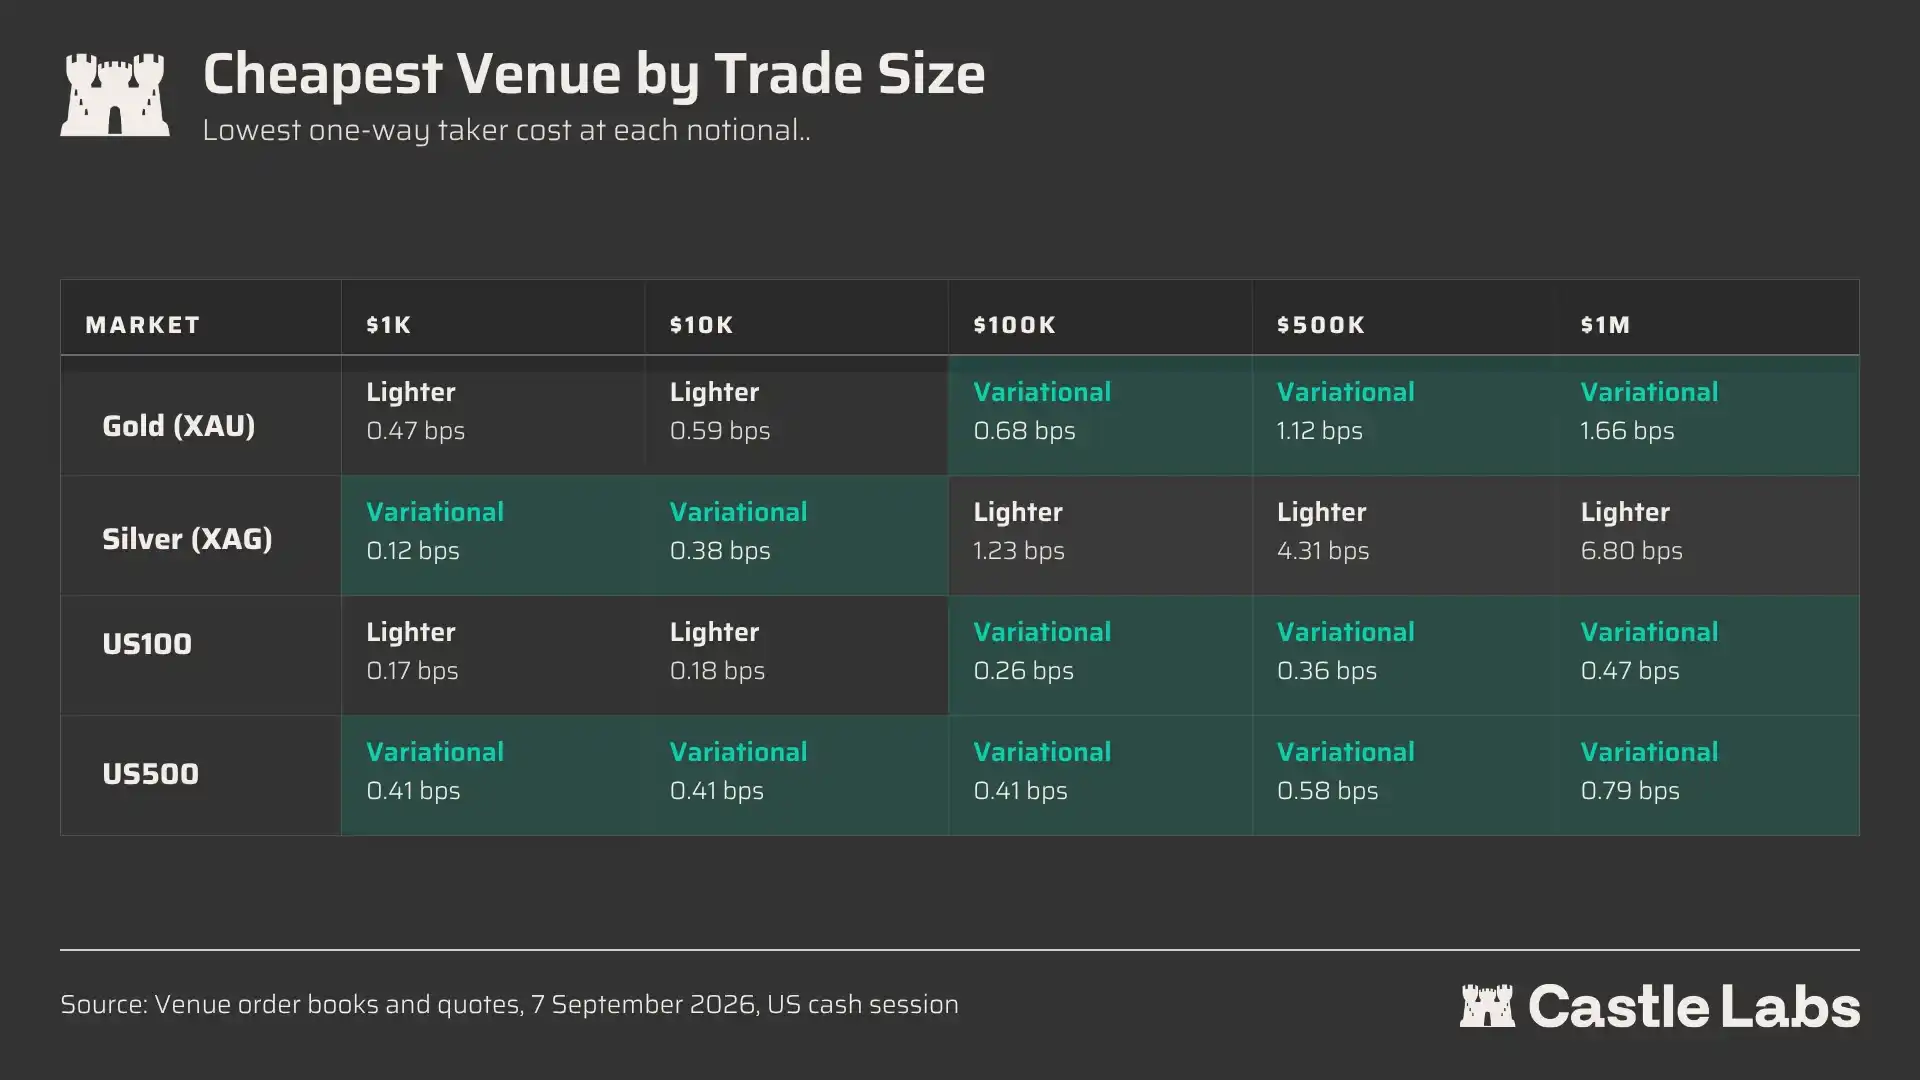
Chart: Comparison of venues with the lowest taker cost across different trade sizes for various markets (XAU, XAG, US100, US500). Source: Various venues' order books & quotes, US market hours, Sep 7, 2026; Castle Labs.
The on-chain trading landscape continues to evolve.
RWAs and TradFi assets are accounting for an increasing share of perpetual trading volume.
While there is strong demand from on-chain native users, the novelty of these assets and the accessibility advantages of being on-chain mean the markets are far from reaching the efficiency level needed to attract large institutional traders.
Perpetual protocols must constantly balance carefully between "listing attractive new assets" and "ensuring sufficient liquidity for efficient execution." Additionally, perpetuals are not user-friendly for RWA traders because funding rates are unpredictable and can impact the final profit or loss of a trade.
Variational Swaps present an interesting way to address both issues, benefiting both retail and institutions.
The former can benefit from predictable funding costs and a clear understanding of the true cost of holding exposure through a Swap position. The latter can rely on low execution costs, predictable funding rates, and tight linkage with the underlying markets.
The rapid growth of Swaps is proof: they already contribute to over 50% of Variational's daily trading volume, with open interest exceeding $220 million.
This is primarily driven by the US100 market. As of September 7th, this market accounts for over 50% of all Swap trading volume and 30% of open interest.
Among the first batch of launched markets, funding rates show longs paying between 4.6% and 5.7% annualized, while shorts earn about 2.4% annualized.
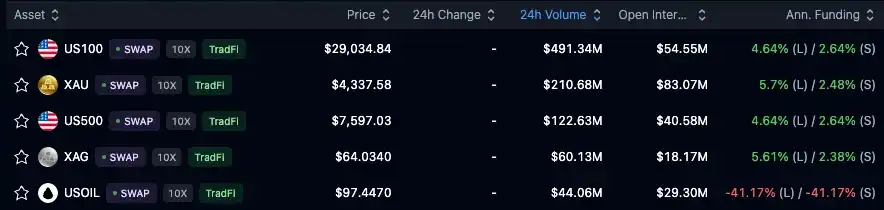
Chart: Market data for Variational's first batch of launched Swap markets (US100, XAU, US500, XAG, USOIL) including 24h volume, open interest, and annualized funding rates (Long / Short). Source: Variational.
So far, trading most RWA markets at scale with good execution has been difficult. Swaps bypass the need to bootstrap liquidity, providing TradFi-level depth for any market, redefining a perpetual trading venue as an on-chain derivatives protocol—one that can aggregate liquidity where it already exists and settle that exposure transparently.
This model has clear advantages. It can support more markets, avoid slow liquidity bootstrapping, and offer users exposure to assets that are difficult to launch via on-chain order books, all with predictable costs.
By doing so, Swaps also create a clearer structure for RWAs, where funding costs and trading hours reflect the underlying market, not a perpetual template driven by supply and demand.
The trade-off is that this model places higher demands on the OLP. Users do not rely on a broad public order book but on Variational's pricing, hedging, risk management, and ability to maintain competitive quotes across hundreds of markets via its RFQ system. All of this makes execution quality a core aspect that needs to be proven.
Our analysis confirms that, for most trade sizes and currently launched assets, Variational is the cheapest venue. For US100, a $1 million trade costs as low as $47. However, in some cases, like Silver, due to insufficient trading volume, execution costs are higher, with a $1 million trade costing $787, 20% higher than on Lighter.
Since the platform does not charge any fees, this further reduces execution costs, making it one of the most cost-effective venues for trading TradFi markets on-chain.