Author: Will Wang, Dukai Fintech
On September 29, 2026, Stripe published a lengthy article outlining its stablecoin product stack, breaking down what a bank can do into eight product modules, ranging from card issuance, payments and collections, fund management, all the way to issuing the US dollar itself. A few days later, it put the founder of the crypto wallet company Privy in charge of the entire crypto and stablecoin business.
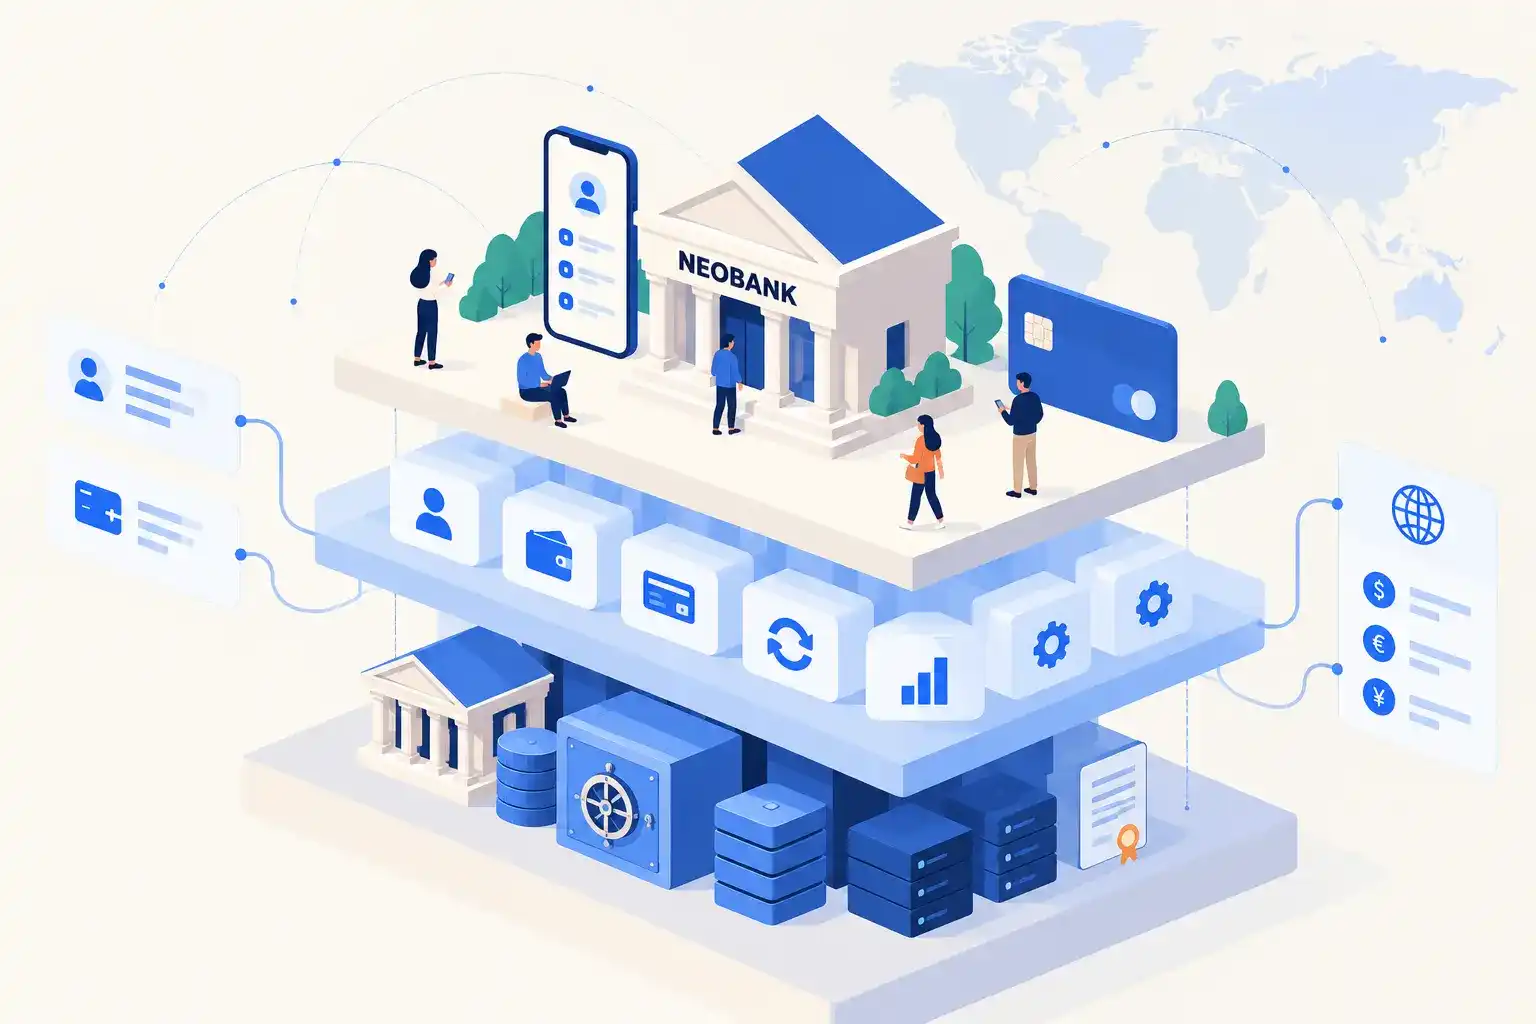
The batch of neobanks we previously knew well split banks into front-end and back-end, doing the front-end themselves and outsourcing the back-end to partner banks; in the current era of blockchain and AI, Stripe has further broken down the back-end into individual modules. With the help of blockchain, anyone can piece together a bank.
On September 25, the creator platform Whop launched a neobank template, claiming you could open a bank in 15 minutes;Nubank moved even earlier, entering the US on September 10. Before its own license was approved, it opened for business using Circle's stablecoin through its partner bank, Lead Bank. Previously, it took Nubank thirteen years in Brazil from founding to acquiring a banking license.
In the blockchain and AI era, when everyone can piece together a bank. However, our observation is:No one is born a neobank; they either expand from a specific point(Nubank started with local credit),or contract from a broad surface(Crypto is born global, then makes regional penetration).
The real questions to ponder are: where exactly has the neobank threshold been lowered? After being broken down, how does each layer of the stack make money? At what stage should a company position itself at which layer? And in the future, when agents start making transactions on behalf of people, will value capture end up in the hands of neobanks?
I. Banking is Becoming an Assembled Business
There is a concept in economics called Jevons Paradox: the higher the efficiency, the greater the consumption. Neobanks follow this same path: from branches where you had to go to a counter to open an account, to apps that only handle the front-end and outsource deposits and clearing to partner banks. Every time the cost of serving one person drops, another batch of people previously outside the banking system's reach comes in.
Today, the two most successful ones each captured a unique customer base:
-
Nubank started in Brazil in 2013 by targeting people without credit history, first offering no-annual-fee credit cards, then gradually adding accounts and loans. It took thirteen years to obtain a banking license.
-
Revolut started in 2015 with cross-border FX and prepaid cards, first using a Lithuanian license to cover Europe. It took eleven years to obtain a full UK banking license. One started with credit, the other with cross-border transactions, both taking a light-first-then-heavy approach, building as they went.
Neobanks built on blockchain and stablecoins, also known as crypto neobanks, do not change the path of 'rent first, build later'. What they change is the scope of what can be rented:
From a local bank, to a complete set of global, programmable financial capabilities.
In April 2026, a16z crypto provided a segmentation when outlining the stablecoin market: the last wave of Banking as a Service (BaaS) involved fintechs renting banking licenses and connecting to bank core systems;in this wave, companies can be built directly on-chain infrastructure and self-custody wallets, combining accounts, payments, wealth management, FX, and credit into complete products.
The changes manifest in two areas:
-
The USDC users hold in a stablecoin neobank is a liability of Circle, not a deposit of the neobank. The heaviest burdens—deposit licenses, capital adequacy—remain with the issuer along with the liability.
-
Accounts are recorded on public blockchains, denominated in US dollars, can flow cross-border, and are not restricted by traditional banking hours. Only the fiat on/off-ramp segments require local partners.
Stablecoins and Stripe's role for neobanks resembles AWS for internet companies: turning infrastructure that once had to be self-built into on-demand services. Stripe started by letting merchants integrate payments with seven lines of code; now it breaks down banking with eight APIs.
AI reduces a different cost. Félix moved cross-border remittances into WhatsApp, so users don't need to download an app; Nubank uses financial behavior data from about 135 million users to train models predicting defaults. Going a step further, when software starts initiating transactions on behalf of clients, a new set of authorization relationships emerges.
Following Jevons' logic, the outcome is easy to predict: more neobanks will open, covering an increasingly broader population. But as more open,the challenge shifts from whether it can be done, to where money can be made.
II. The Bottom Layer Relies on Qualifications, the Middle Layer on Accounts, the Top Layer on Customers
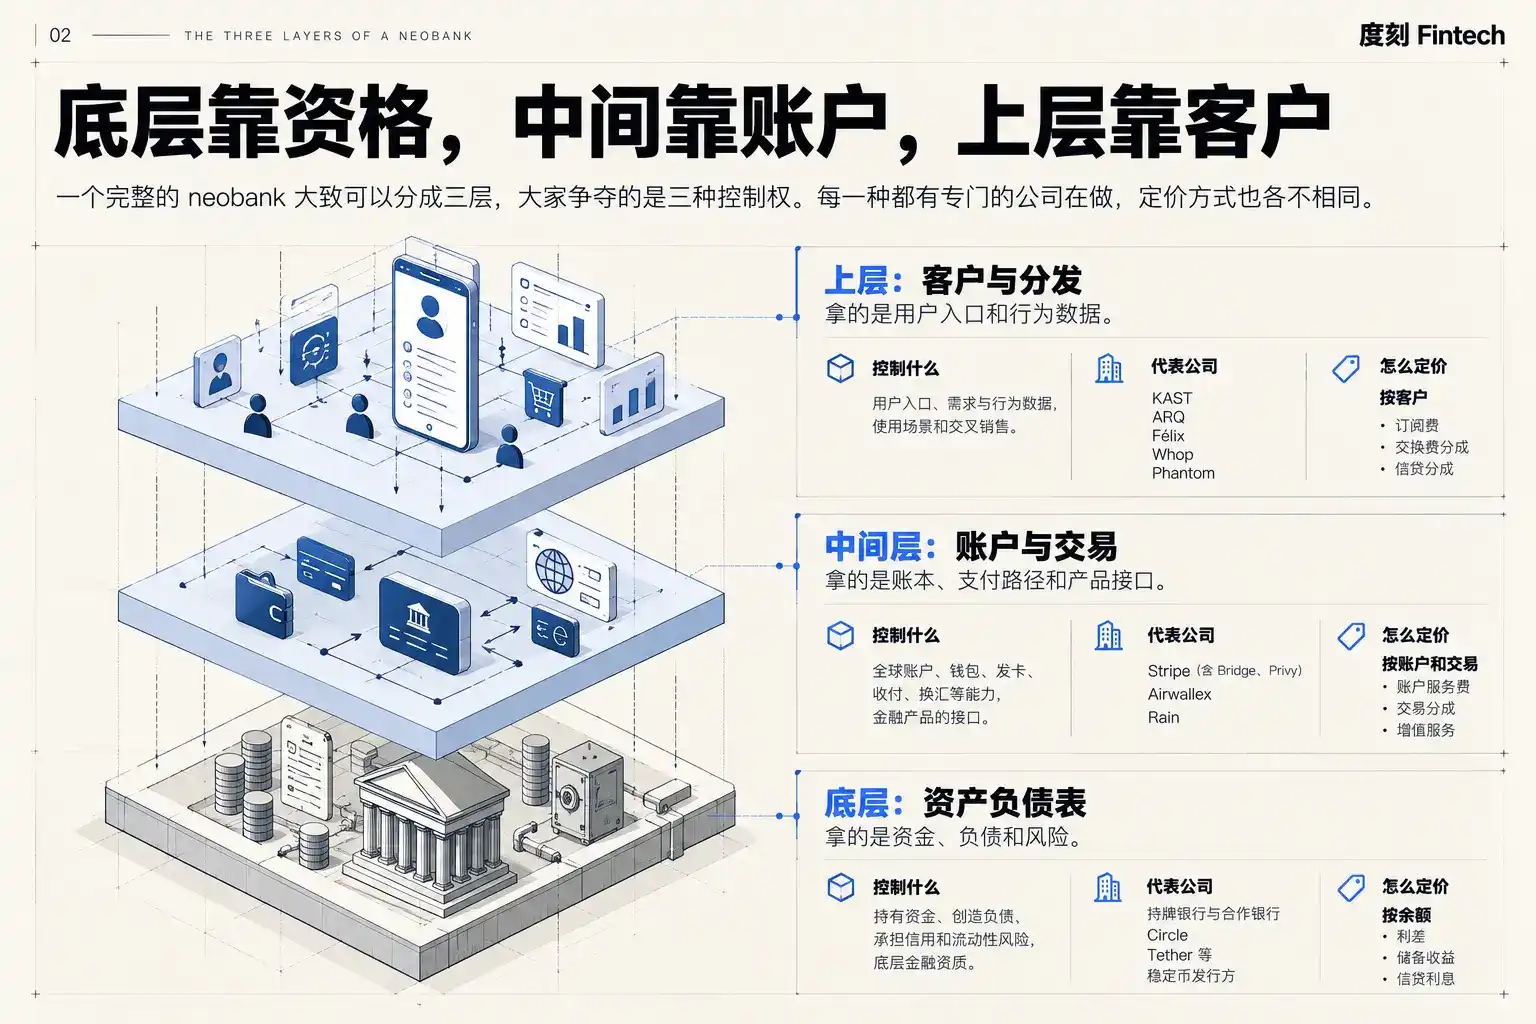
A complete neobank can roughly be divided into three layers, with competition for three types of control.
The bottom layer controls the balance sheet: who holds funds, creates liabilities, bears credit and liquidity risk. The middle layer controls accounts and transactions: who holds the ledger, wallets, payment rails, and product interfaces. The top layer controls customers and distribution: who holds the user entry point, demand and behavioral data, usage scenarios, and cross-selling opportunities.
Nubank and Revolut spent a decade gaining all three controls; today, each layer has specialized companies with different pricing models. How much value a company captures depends on how many controls it holds and whether others can easily replace it.
Revolut's income statement shows what it looks like when one company holds all three controls. In 2025, its revenue was £4.5 billion with a pre-tax profit of £1.7 billion; from the same customer, it can earn from balances, transactions, and cross-selling. While over 70% of revenue for many traditional banks comes from interest, 75% of Revolut's comes from fee-based income. Nubank leans more towards the bottom layer, with $16.3 billion revenue and $2.9 billion net profit in 2025, backed by a $41.9 billion deposit base supporting a $19 billion credit portfolio.
Having all three layers allows Nubank and Revolut to earn more complete revenue from the same customer, with less value leakage to partners. Their thick profits also depend on customer scale, acquisition cost, bad debt control, and interest rate spreads in their markets. But once the three layers are split among different companies, each layer takes a cut—everyone becomes a middleman earning a spread.
Let's compare these same revenue streams, now flowing to different layers in stablecoin neobanks:
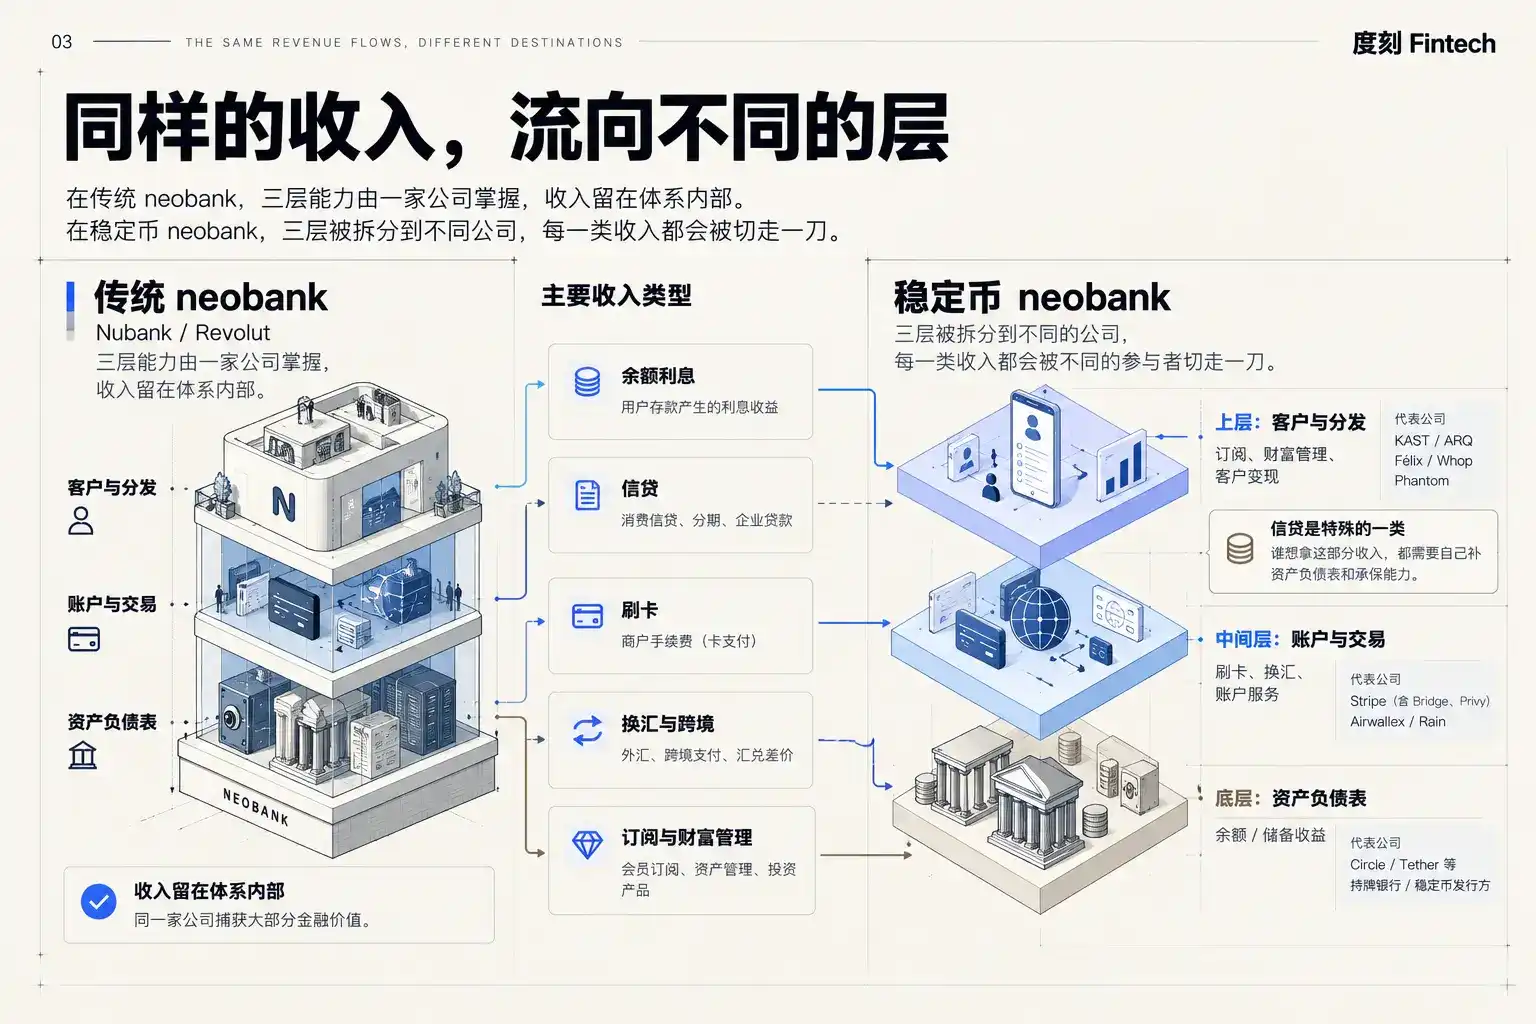
It is important to clarify: the barrier to assembling banking capabilities has dropped significantly, but the barrier to managing financial risk has not dropped alongside it.The burdens of funding, credit, compliance, and redemption have not disappeared; they have simply been transferred to issuers, partner banks, and various service providers.
Issuers bear redemption and reserve management risks; the middle layer faces price competition upon scaling; the top layer bears customer acquisition, service, and fraud losses; credit also must deduct funding costs, bad debts, and capital charges. Revenue attribution is not the same as final profit. One cannot just look at whose pocket revenue goes into, but also who bears the costs, risks, and who ultimately has the final say.
2.1 The Bottom Layer: Local Fiat Qualification and Stablecoin Issuance
The bottom layer controls where the funds land first. It has two sides: fiat banks and stablecoin issuers.
-
The fiat side consists of licensed banks that take deposits, directly connect to local clearing systems, are protected by deposit insurance. Banks like Lead Bank and Cross River behind many crypto neobanks fall into this category, as do Nubank and Revolut's own banking licenses. Over the past decade, partner banks have been the biggest vulnerability for crypto companies—relationships are hard to build and easy to lose. Today, a batch of crypto-friendly banks is filling this gap.
-
The stablecoin side consists of issuers like Circle and Tether, taking in US dollars and issuing stablecoin accounts (not bank accounts), then building a dollar ecosystem on-chain, effectively becoming banks for on-chain dollars.
Both sides earn a spread akin to deposit-loan interest. The lowered barrier hasn't hurt this layer. In his 2025 year-end report 'State of Fintech 2026', Simon Taylor, Head of Market Expansion at Tempo, wrote:
In 2025, the year when stablecoins and agentic commerce were most prominent, banking was not disrupted; instead, banks had a record year.
However, balances are not the same: fiat deposits, custodial client funds, stablecoin reserves, and user assets in wallets have different legal attributes. Only part of them can be lent out.
But the two sides are converging. On the issuer side, Stripe's Bridge received conditional approval from the OCC for a national trust bank charter in February 2026. Once fully approved, it can custody digital assets, issue stablecoins, and manage reserves. While a trust charter cannot accept insured deposits, it brings issuers inside the banking system's door. According to a16z, this license race is about securing a position in the future payment system: if regulation allows licensees to directly connect to the Federal Reserve's clearing system, early licensees will enter the core of the financial system.
Banks are also moving towards stablecoins. SoFi, holding a banking license, launched SoFiUSD in December 2025, claiming to be the first stablecoin issued on a public chain by a US national bank.
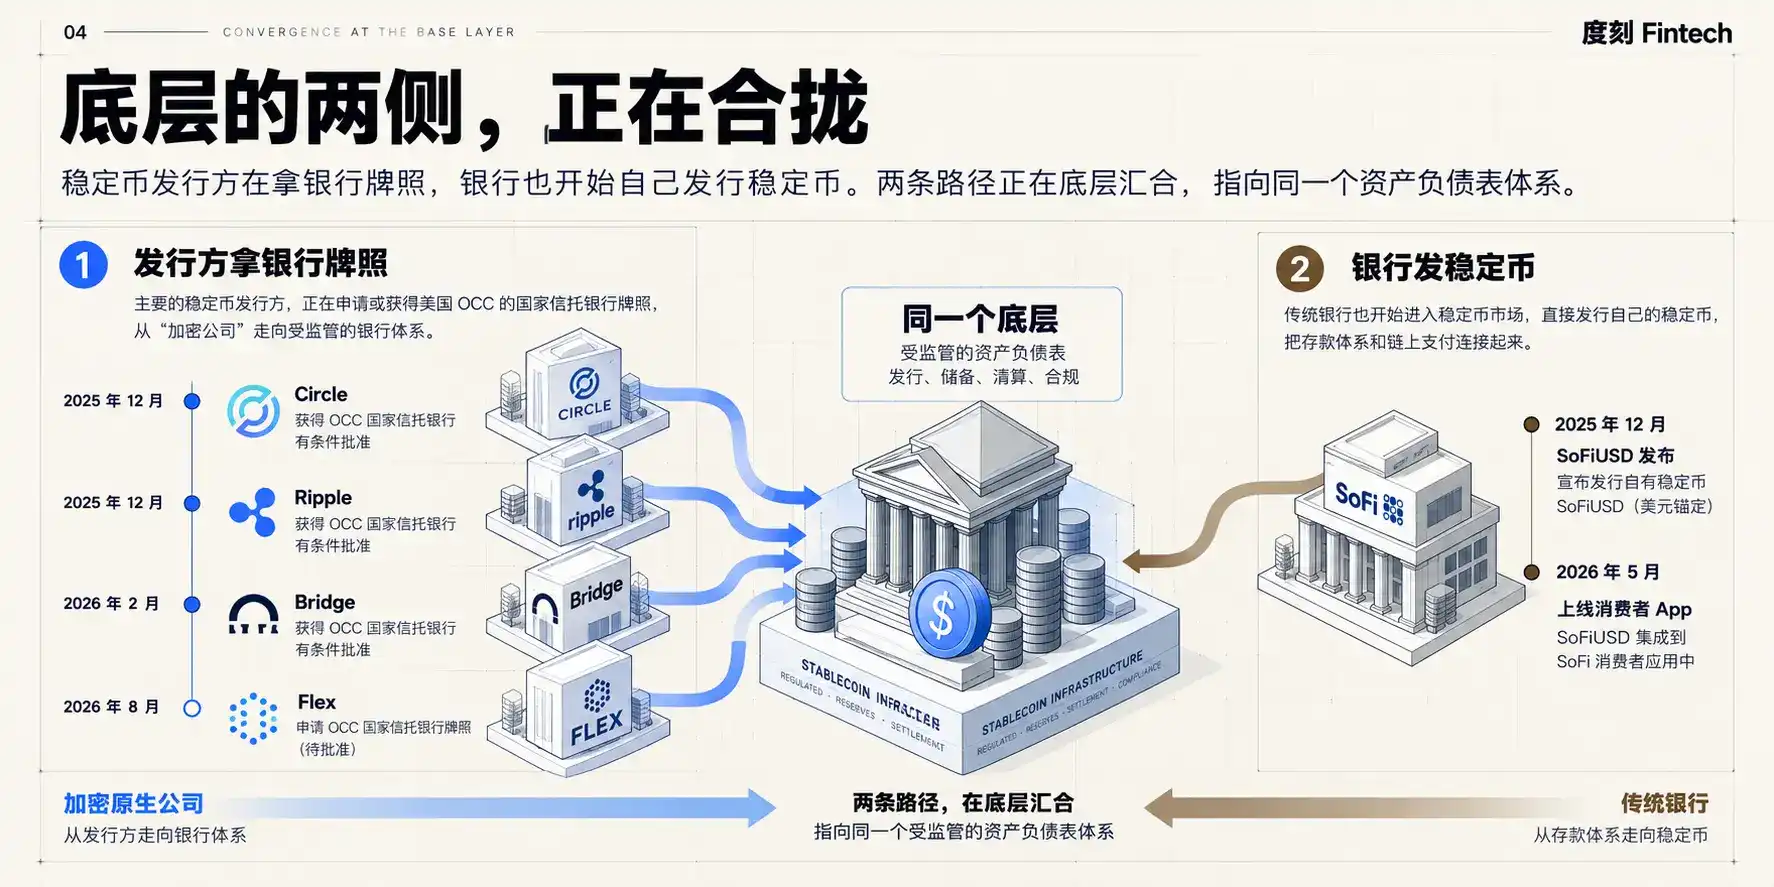
The boundary between the bottom and middle layers is determined by whose balance sheet the money sits on: the bottom layer holds the money; the middle layer organizes these capabilities into accounts and sells them via APIs. What makes the bottom layer hard to replace are licenses, clearing qualifications, and low-cost liability sources.
2.2 The Middle Layer: Global Accounts and the Money That Settles in Them
The middle layer competes for global accounts. An account that can store money, make payments, receive funds, and exchange currency, onto which wealth management, consumption, and lending can be layered.
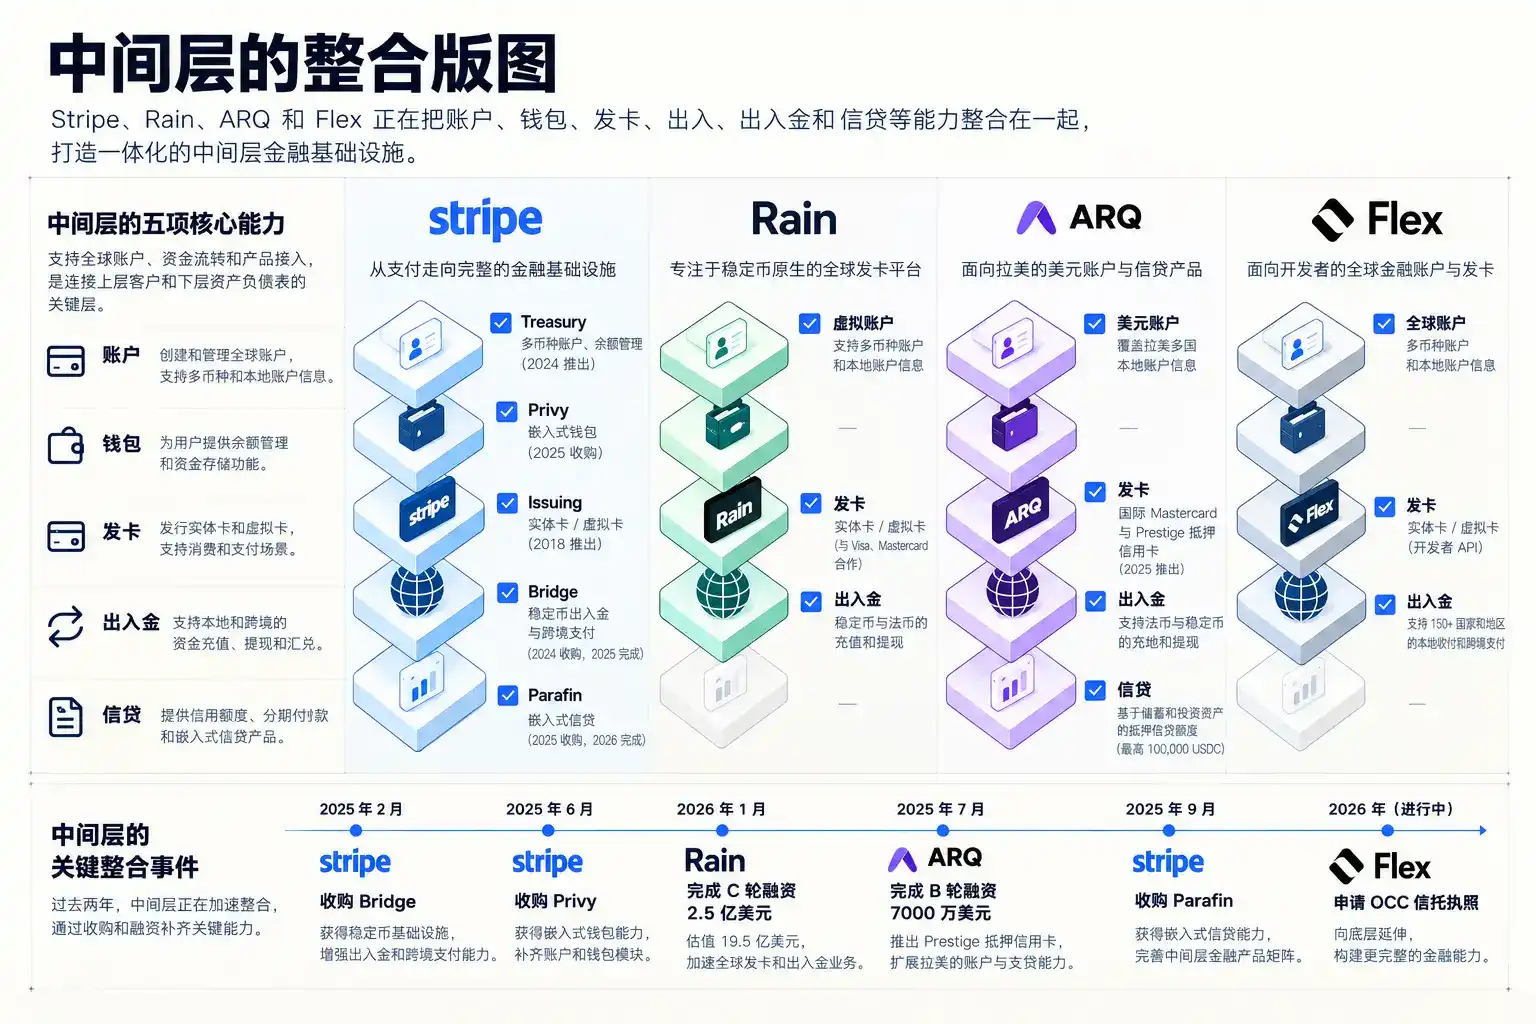
Stripe has placed the account at its strategic center. Henri Stern, the founder of Privy mentioned at the beginning, said when taking over Stripe's crypto and stablecoin business on October 5: the wallet is the center of digital ownership, but it gains power only when combined with orchestration, card issuance, and asset issuance. Stripe now calls its Treasury product the account layer for global financial products, where businesses can hold fiat and stablecoins in one account and send payments to 160 countries using just an email address.
Once an account is held, the middle layer starts competing at both ends. Upwards, it competes with the top layer for cross-selling. On September 30, Stripe announced its acquisition of Parafin, which allows platforms like DoorDash and Gusto to lend to merchants within their backends, having originated over $3 billion in loans. Ironically, Parafin's past selling point was precisely not being tied to a payment provider.
Downwards, it competes with the bottom layer for balances. Rain started with stablecoin card issuance, then added virtual accounts and on/off-ramps, and experimented with direct connections to ACH and SEPA. It is pushing the issuing bank, program manager, and processor into the same infrastructure layer to capture more interchange fees, FX spreads, and reserve earnings.
The more platforms the middle layer connects to, and the more services linked to the account, the harder it is for customers to migrate. It wants both cross-selling revenue from the top layer and balance sheet earnings from the bottom layer.
2.3 The Top Layer: Banking as a Product, or Embedding Banking into Products
The top layer's business depends on who captures the customer first. Two paths have emerged: companies like KAST and ARQ directly offer banking as a product;Whop embeds banking into its existing business. Simon Taylor's report mentions that Robinhood, Klarna, and Affirm are also using cards as growth levers—everyone wants to be a neobank.
Among the first type, the fastest moving are KAST, ARQ, and Félix. Take Félix as an example: it serves Latin American immigrants in the US, completes remittances within WhatsApp, settles in the backend with USDC; after obtaining credit lines, it has started extending into savings and consumer loans. KAST started with stablecoin accounts and cards, ARQ started with dollar accounts in Latin America—both are extending into credit and wealth management.
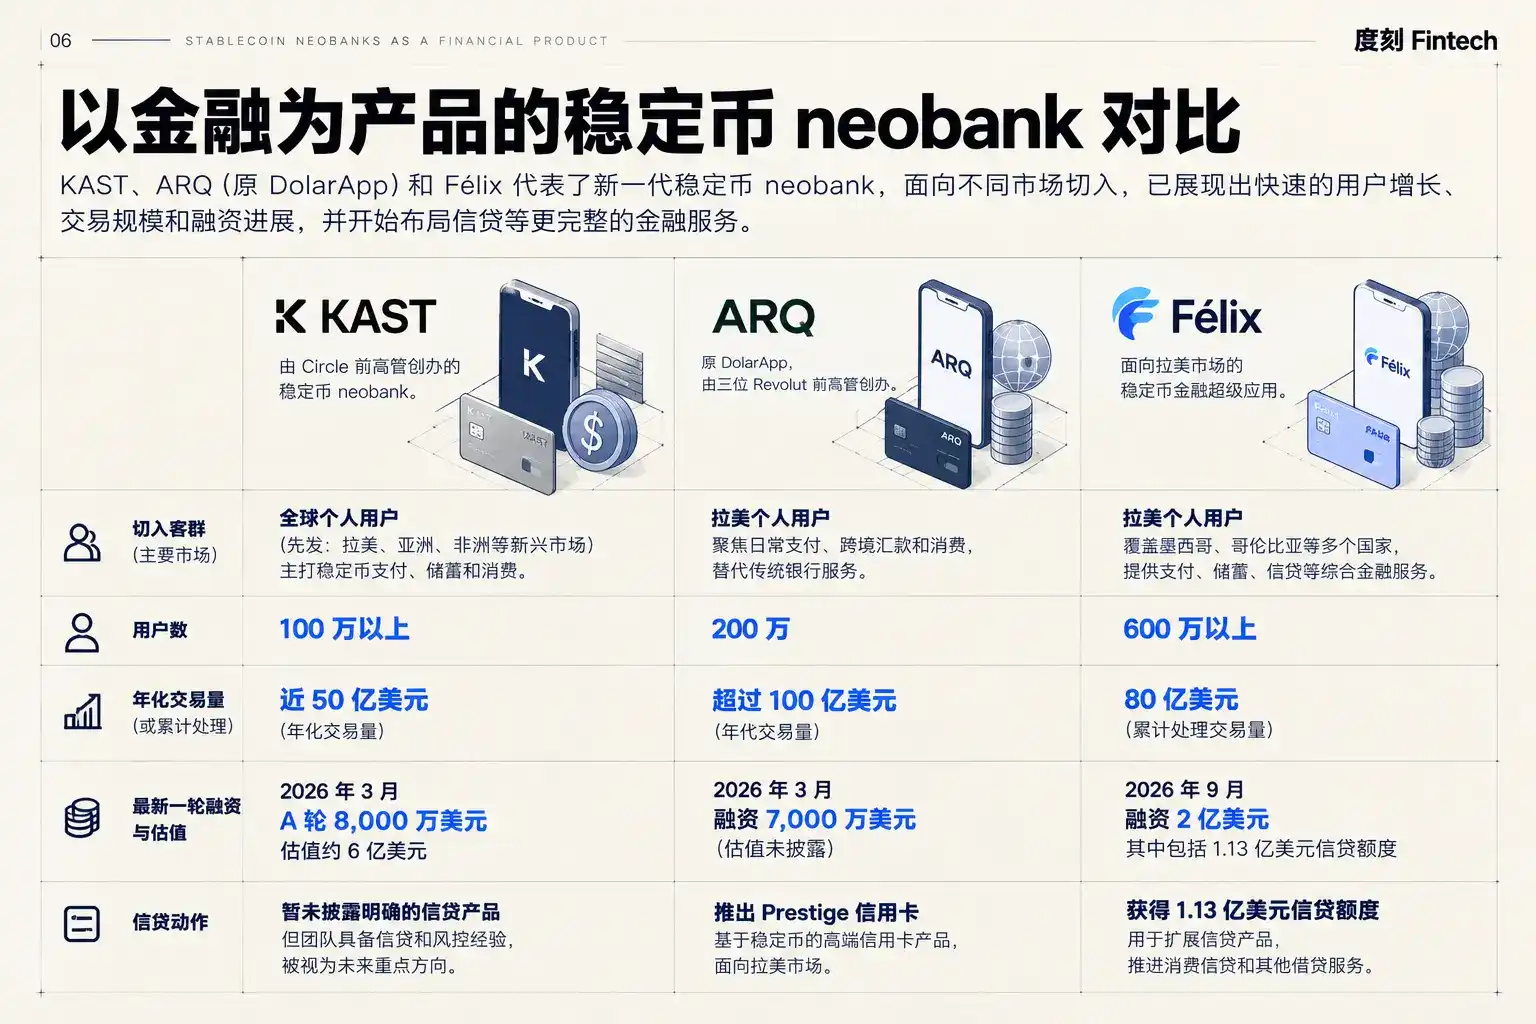
The dollar account is just the entry point; money is made after the account is opened. Once users have stable US dollar balances, credit, investments, wealth management, and insurance can all be layered on one by one.
The three are on the same path: acquire customers with global accounts, then monetize with financial services, with local credit being the most valuable. The main components of a global dollar account are now highly rentable, but local on/off-ramps, compliance, and clearing are not yet standardized components; capital can also be rented in stages—credit lines, securitization, partner banks are all methods; what cannot be rented is local underwriting capability proven through a full credit cycle, and low-cost, sustainable customer relationships. Lending is not hard; making money through cycles is.
a16z's judgment points here too: payments are Act I; credit is likely Act II. Once stablecoin float reaches trillions of dollars, that money will need somewhere to go. A new credit market will inevitably grow on-chain.
The representative of the second type is Whop. It was originally a creator digital goods marketplace, settling about $3 billion annually for sellers. By turning the settlement endpoint into a platform account, money stays on the platform, can be converted to stablecoins, placed into wealth management products, and spent via cards—Whop begins profiting from money staying and flowing. Phantom, Remote, and Shopify are also embedding finance into their products; in Latin America and Southeast Asia, MercadoPago and Grab have already taken similar paths.
Although functional neobanks assemble quickly, the cost is written in their terms. Lex Sokolin of Fintech Blueprint dissected Whop's terms of service: it is not a bank itself, liability is capped at 12 months of fees or $100; wallets come from Privy, cards issued by Third National and managed by Rain, balances placed into Aave via Veda vaults for interest; fiat funds are in commingled custodial accounts at partner banks, not FDIC-insured, the same structure that caused issues during Synapse's bankruptcy in 2024.
Lex Sokolin's conclusion is direct: the positioning is cool, and possibly dangerous. Banking is, after all, a business of managing risk.
Regulators have also noticed this structure. A Federal Reserve research paper in April 2026 pointed out that when a stablecoin's operational chain involves multiple third parties, in a crisis, the market may not distinguish where pressure is coming from, potentially amplifying panic.
What makes the top layer hard to replace are customer trust, scenarios, data, and low-cost distribution.
III. Which Layer You're On Depends on the Stage
There is no single answer for which layer a company should stand on.
At the starting stage, rent as much as possible, first prove you can capture customers; as scale grows, reclaim the links that most affect profit, data, and survival.
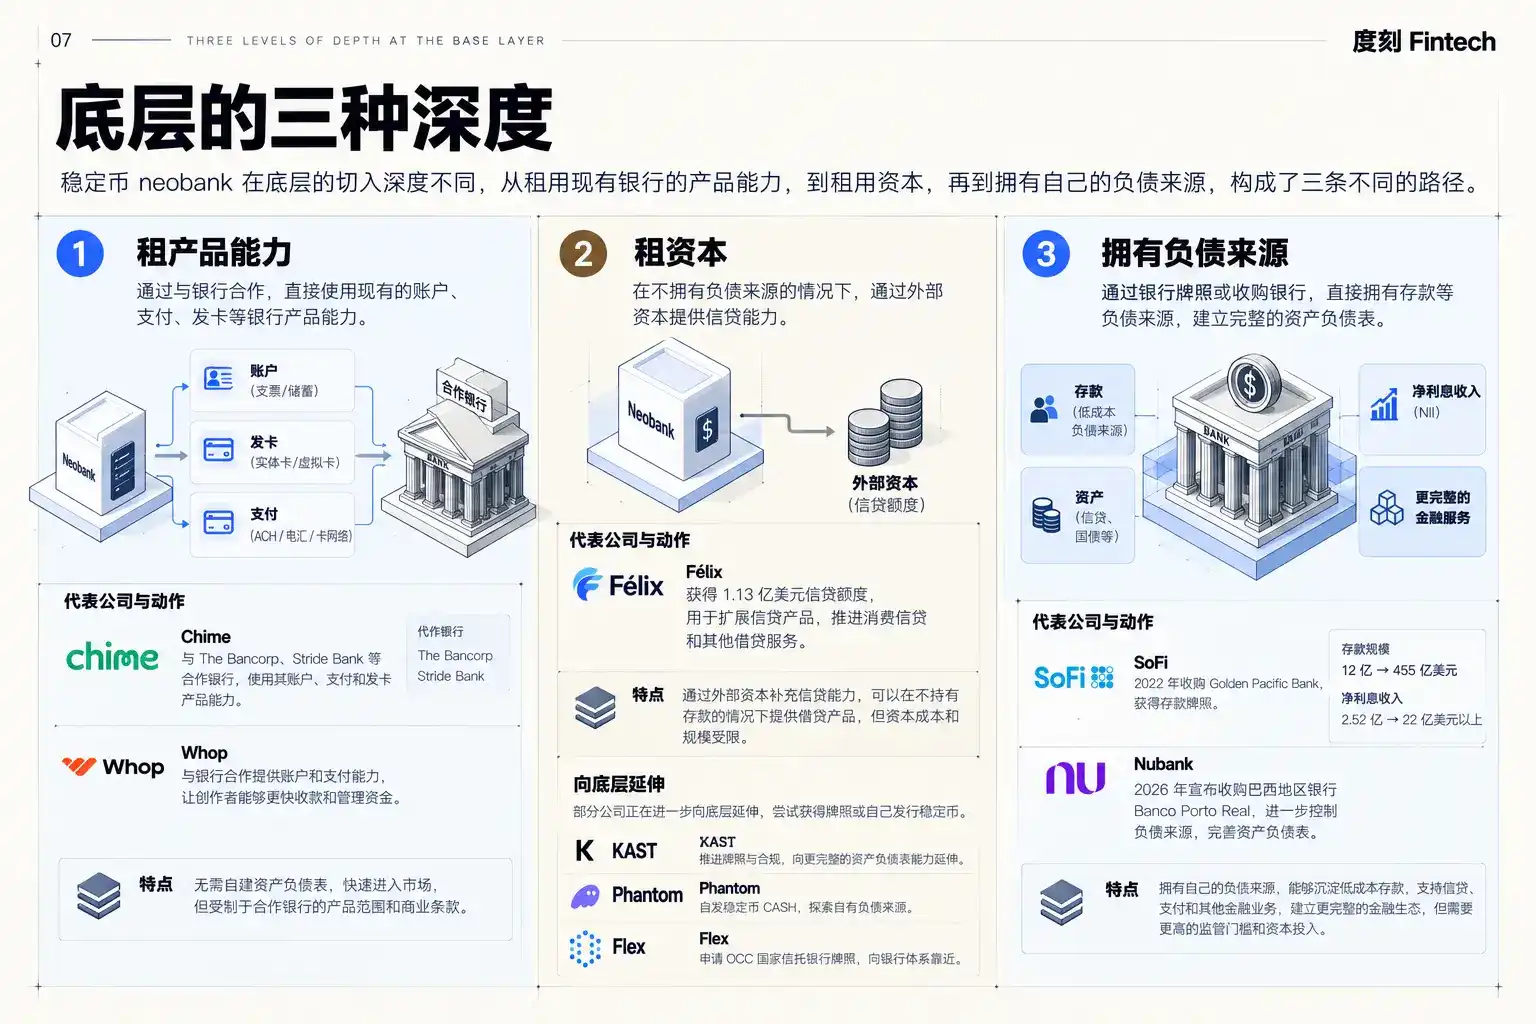
Start-ups rent the bottom layer, rent the middle layer, and only do the top layer, opening for business by capturing a customer segment. Most stablecoin neobanks today are here, as were the neobanks of yesteryear. Chime still doesn't have its own banking license, accounts are with partner banks, and it primarily makes money from card interchange fees. Thin profits, but quick to start.
As for which layer to reclaim, first look at where the company's real advantage lies. How much profit partners take is one calculation; whether the company can survive if a partner cuts supply is another. For companies that make money from credit, the answer is usually the bottom layer; for distribution platforms like Whop, owning a banking license may not be necessary; whether the middle layer should lend on its own is another calculation. Reclaiming key links does not mean going as full-stack as possible. It's worth crossing layers only when the benefits in profit, data, and stability outweigh the capital and regulatory costs.
SoFi is the clearest example. In 2022, it acquired the small bank Golden Pacific. After obtaining a national bank charter, it started lending using its own deposits, and deposit size grew over thirtyfold. Nubank's acquisition of Banco Porto Real in 2026 follows the same path.
Building out the bottom layer also has depth. Renting product capabilities, renting capital, and then owning stable, low-cost liability sources are three levels of integration of varying depth. Félix has reached step two; SoFi and Nubank have reached step three.
Nubank and Revolut have reached maturity, holding all three controls in their core markets. But entering a new market, they have to choose again. Nubank's choices this year best illustrate this: in the US, it quickly opened using Lead Bank and Circle; in Brazil, it only acquired the missing banking license; in the UK, in September, it abandoned negotiations to acquire Monzo for £8-10 billion, and Monzo is a full-stack digital bank with all three layers.
What's most valuable about Nubank is the customer base and underwriting capabilities accumulated in Brazil. This advantage cannot be copied as-is in the UK. Entering a new market, mature companies also have to recalculate: which capabilities to continue renting, and which are worth buying.
Another unavoidable question: Nubank and Revolut themselves can also add stablecoin accounts. Revolut launched the EURR euro stablecoin issued by Bridge in August 2026, and Nubank created Nu Global. What chance do the new generation have?
The answer lies in customer segments. The phenomenon we observe is: mature neobanks are moving upmarket, increasing per-customer value, extending into wealth management and high-end services; stablecoin neobanks are cutting in from populations with the strongest cross-border dollar demand and worst-served by the old system. ARQ serves dollar savings in Latin America, Félix serves immigrant remittances, KAST targets people lacking usable dollar accounts. The two sides will gradually converge, but new players start much cheaper. The time it takes for a licensed neobank to enter a new market might be enough for them to complete their startup phase.
Boundaries are not static either. Stripe extends downwards with its trust charter, Bridge, and Parafin, while reaching customers upwards via Link's 300+ million users.
IV. In the Agent Era, What Are We Competing For?
When the threshold drops another level, transactions are initiated not just by people. When personal AI starts shopping, booking services, and making pay-per-use payments on behalf of people, the financial system must accommodate a new type of delegation relationship: the account still belongs to a person or business, the agent initiates transactions within authorized limits, and it is not itself a new legal entity.
This delegation relationship spans the three types of control. User intent originates from AI products, translated into permissions and transaction instructions by middle layers like Stripe and Link, and finally, banks or issuers decide whether to accept and settle. If problems arise, responsibility still reverts to law and contracts. Authorization is likely to become a new control point contested between the middle and top layers: AI companies want to hold user intent and long-term authorizations; Stripe, Link, and Catena want to turn authorizations into verifiable, executable, accountable financial credentials.
Simon Taylor of Tempo said that every AI company will become a payments company. That's a bit of an overstatement, but the direction is correct: once AI starts taking actions on behalf of users, it cannot bypass payments. Whether to do it themselves is another matter. Meta Muse uses Stripe Link and one-time virtual cards to checkout for users, later integrating Shop Pay and PayPal; Stripe and Tempo have launched machine payment protocols, allowing agents to directly pay for data, compute, and software tools. AI companies hold user intent, but payment capabilities are mostly rented from the middle layer. What Stripe aims to do is provide agents with secure ways to access user funds and payment credentials.
The focus of competition is whether AI companies only hold user intent, or further hold identity, payment credentials, and account relationships.
Another path is for licensed institutions to directly handle identity, authorization, and settlement in agent transactions. Catena Labs aims to establish a financial identity for each agent, bound to the individual or business behind it, allowing them to first set spending limits, payee lists, and balance caps, then hand execution to the agent. On September 18, 2026, the OCC gave Catena Trust Bank preliminary conditional approval. What it wants to build is a financial delegation system covering entity identity, authorization scope, policy limits, transaction execution, and accountability records. Whoever controls identity, permissions, and transaction credentials may become a new value node in the agent era.
Banking is also calculating this account. Oliver Wyman believes that by 2030, agents will become the dominant customer acquisition channel.
When agents start spending on behalf of people, who holds the funds, payment credentials, and authorization rules? Is it the AI company, Stripe's Link, or financial institutions like Catena?
This competition is about who can safely turn human authorization into transactions that machines can execute and can be held accountable for afterward. Just issuing a wallet to an agent first doesn't count as winning.
V. What Can Be Rented, and What Cannot
Blockchain and AI reduce the cost of assembling financial capabilities and serving customers, but do not simultaneously lower the threshold for managing financial risk. Value thus accrues to the three types of control: the balance sheet, accounts & transactions, and customers & distribution.
At the start, rent what you can; as scale grows, reclaim the links that determine profit, data, and survival. When entering a new market, you have to choose again. Agents have turned authorization into a new point of contention: whoever holds user intent, payment credentials, and account relationships may become the new gateway between people and the financial system.
Rethinking neobanks, in the end, the term itself may become obsolete. Ten years ago, it referred to a type of company: banks without branches, relying solely on apps. Today, creator platforms, social companies, payment companies, even AI that spends on behalf of people, are all doing what neobanks do. When a bank can grow within every product that has users, 'neobank' ceases to be an industry, and becomes a capability.
Everyone is a neobank, but ultimately, neobanks may disappear into products.