Fomo Is Popular, But I Advise You Not to Fomo

marsbitОпубліковано о 2026-09-07Востаннє оновлено о 2026-09-07

Анотація

FOMO, a social trading app, is experiencing explosive growth, becoming a major gateway for new crypto users, largely driven by meme coin trading. In August, it generated $13.8 million in revenue, a near 30x increase year-over-year, with daily active users soaring from 7,500 in June to over 100,000 recently. Its rise has been fueled by integration with platforms like Hyperliquid and, notably, the meme coin frenzy on Robinhood Chain. However, data reveals a stark reality for most users. An analysis of roughly 293,000 wallets over 90 days showed only about 6.16% were profitable, with median losses around $120. Total user losses were estimated at $1.26 billion, while profits were highly concentrated—few wallets gained over $10,000. In contrast, the platform itself and a small number of top traders profited significantly, with FOMO earning millions in fees. The "copy trading" feature also faces criticism, as leading traders can potentially sell into the buying pressure created by their followers. Despite its popularity and record-breaking metrics, the evidence suggests that while FOMO is booming, the vast majority of its users are losing money.

By: Bootly

How popular is Fomo right now? In a word: In on-chain social trading, it's the one that broke through this summer.

Millions of users, single-day revenue exceeding one million dollars, once squeezing into the top three on the US Finance app chart, and now being propelled forward by the meme frenzy on Robinhood Chain. It's not the next Cash App, but it has already become the first real 'trade with one tap' crypto entry point for many people.

Last month, many were still only saying it was 'going mainstream.' In the three weeks since, Fomo's growth momentum has not only not slowed but has accelerated further.
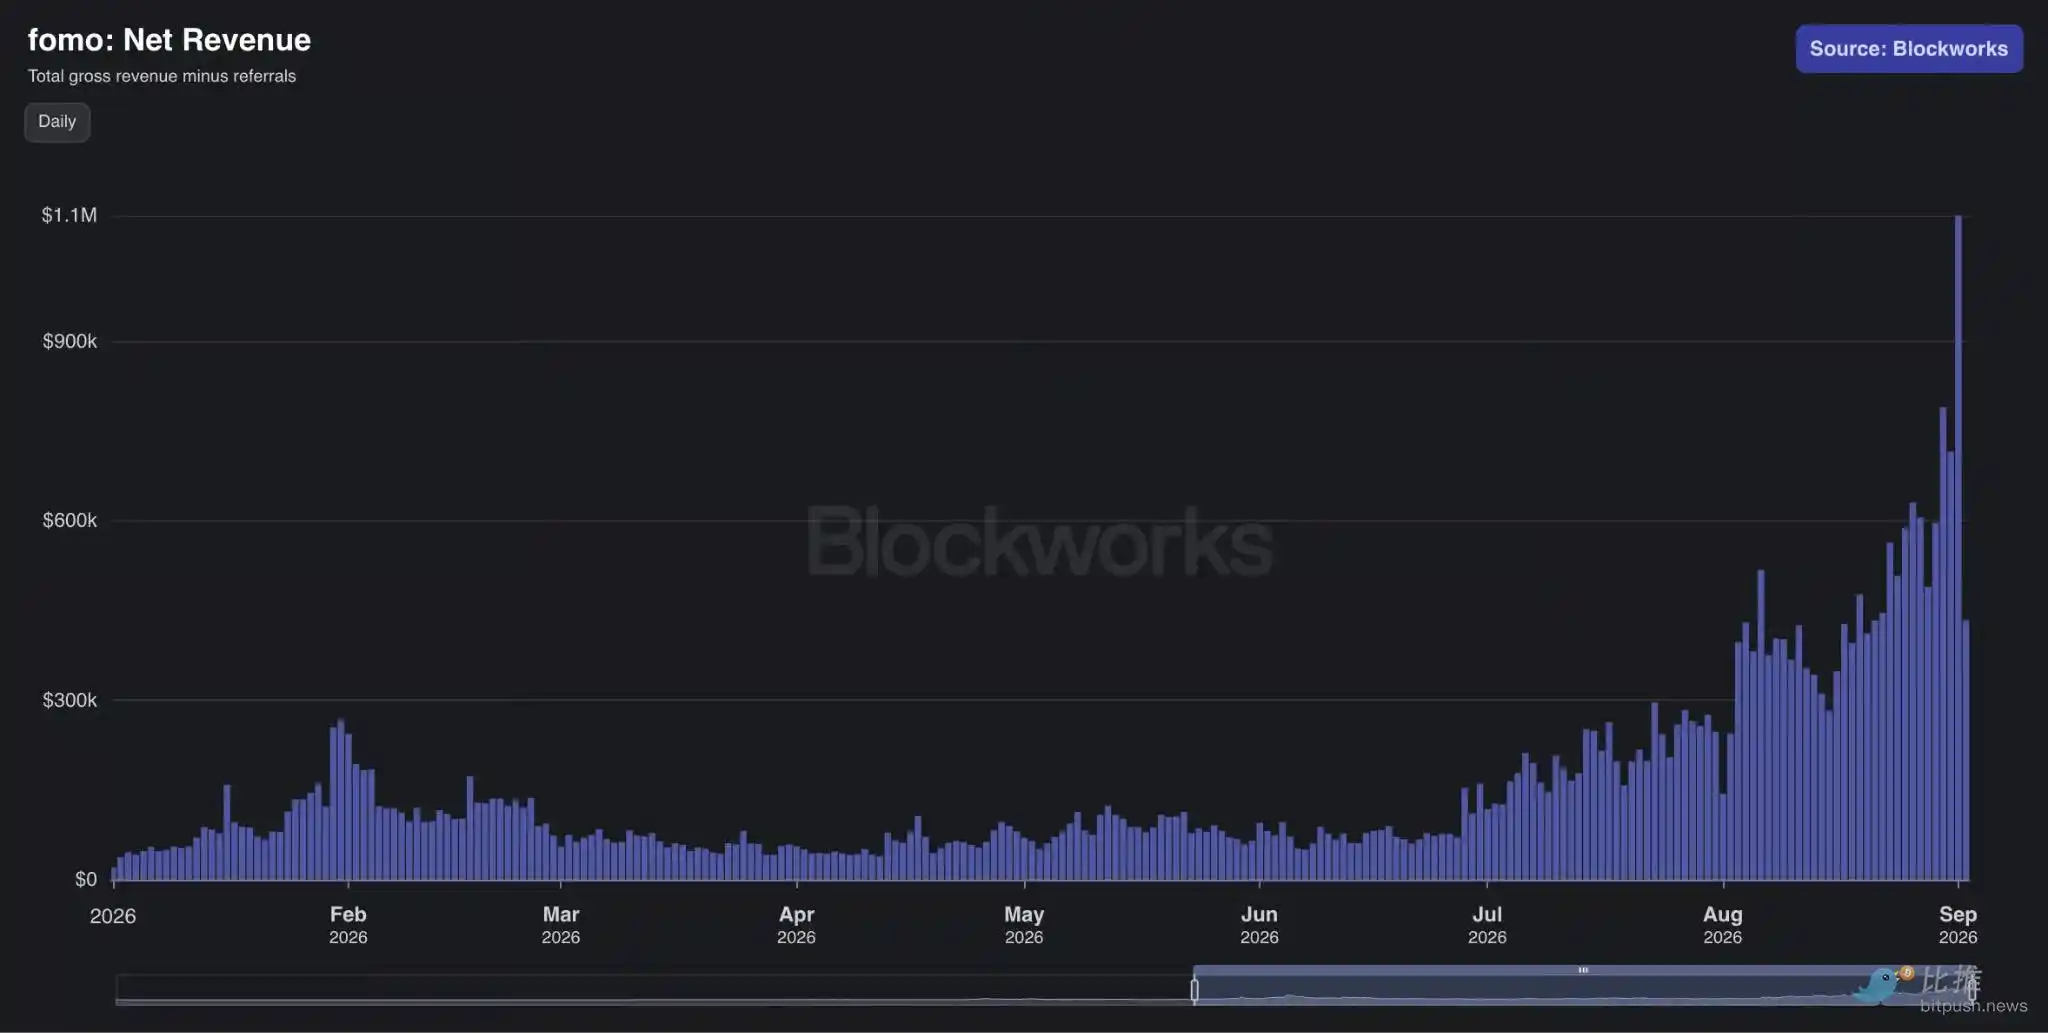
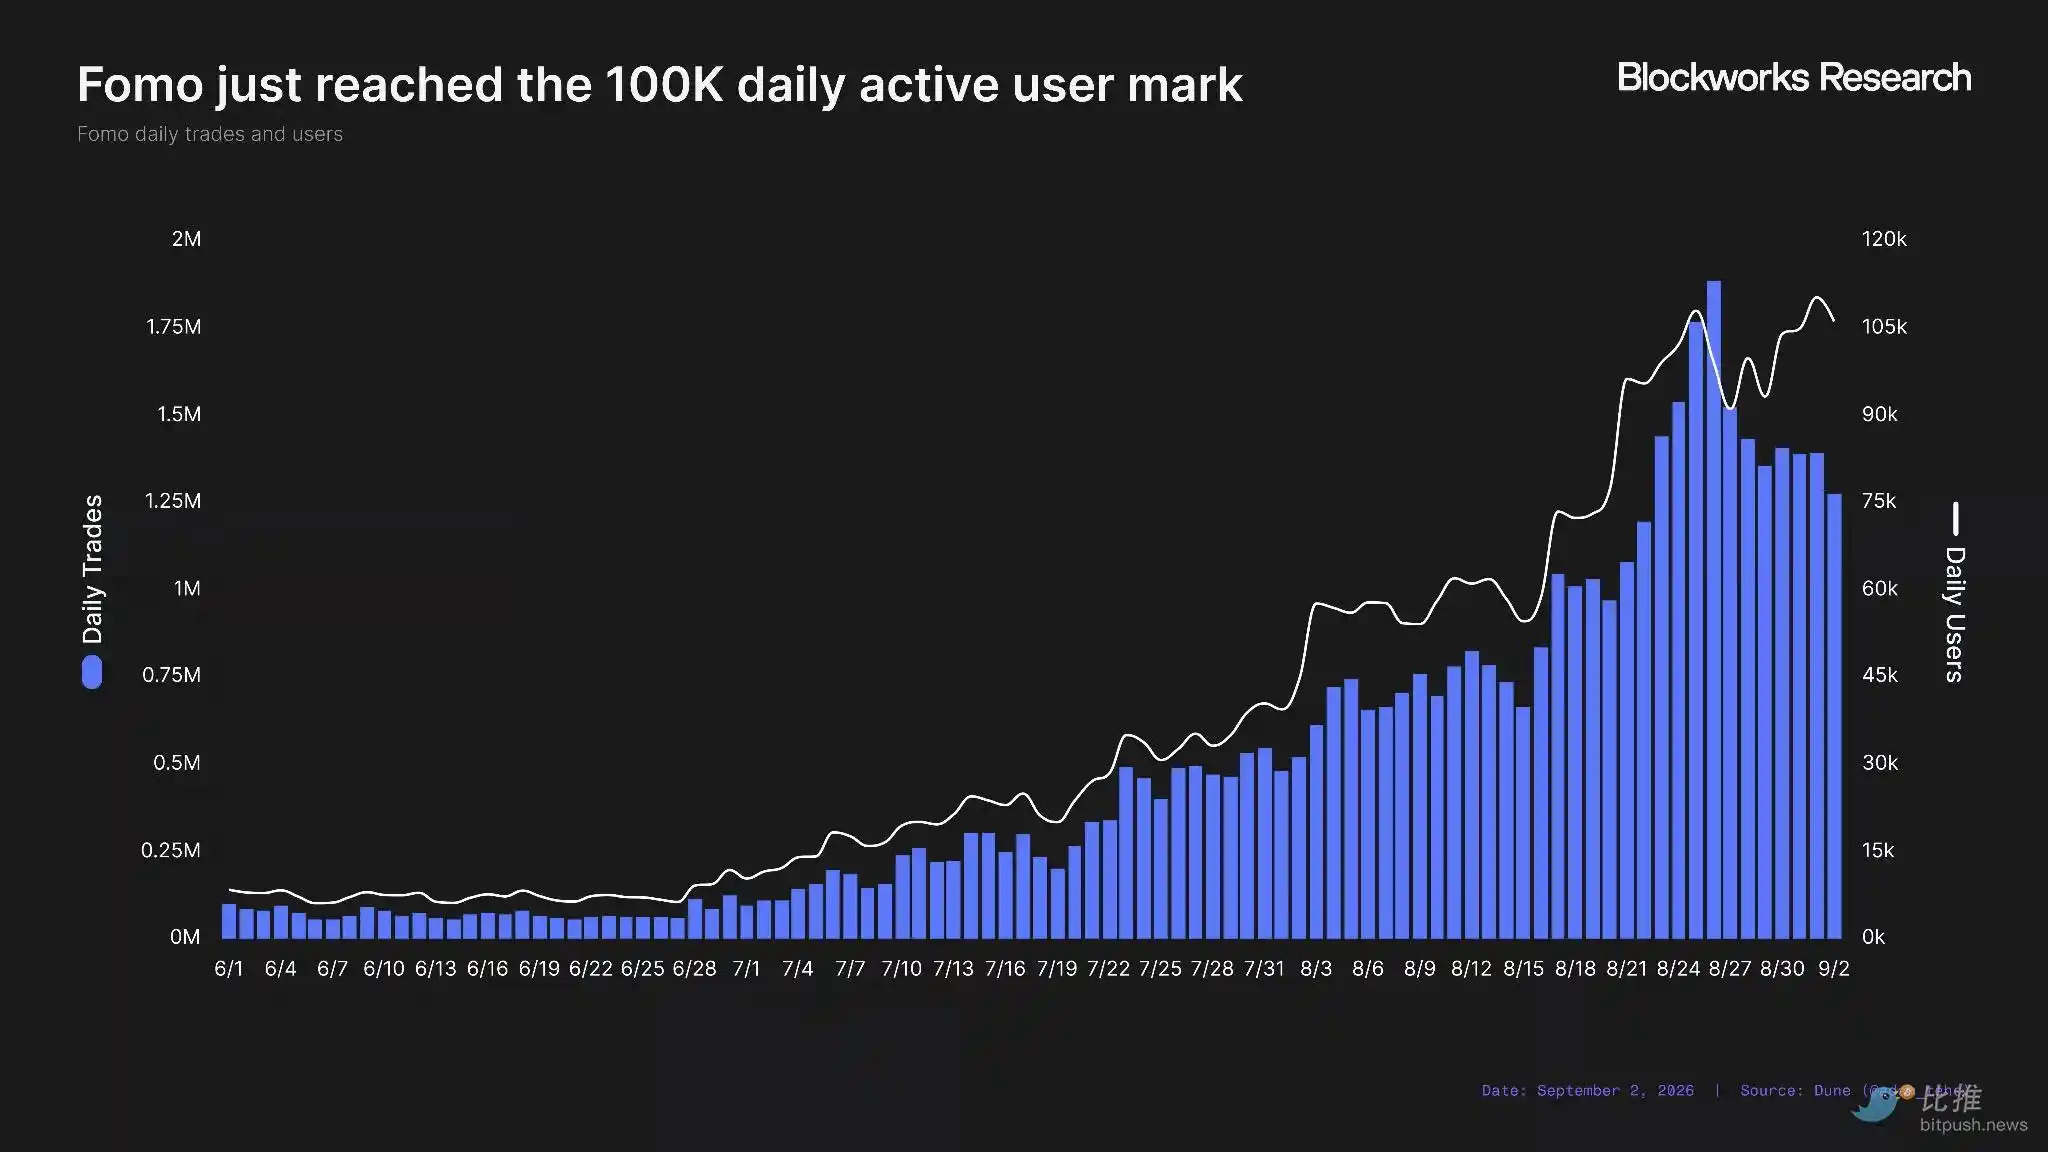
In August, Fomo recorded $13.8 million in revenue (annualized $165.6 million), easily surpassing the $6.4 million record set in July. And September continued its surge — on September 1st, single-day revenue reached $1.1 million, setting a new historical peak. Compared to $450,000 in August last year, monthly revenue skyrocketed nearly 30 times, a parabolic growth.

More notably, this explosive growth is not propped up by a few 'whales' but by a rush of new users. In June, Fomo had only 7,500 daily active users; by the most recent week, that number had soared to 101,000. With the surge in users, its ranking in the US App Store's Finance category rose to number 15, indicating Fomo is genuinely bringing 'new blood from outside the circle' into the crypto world.
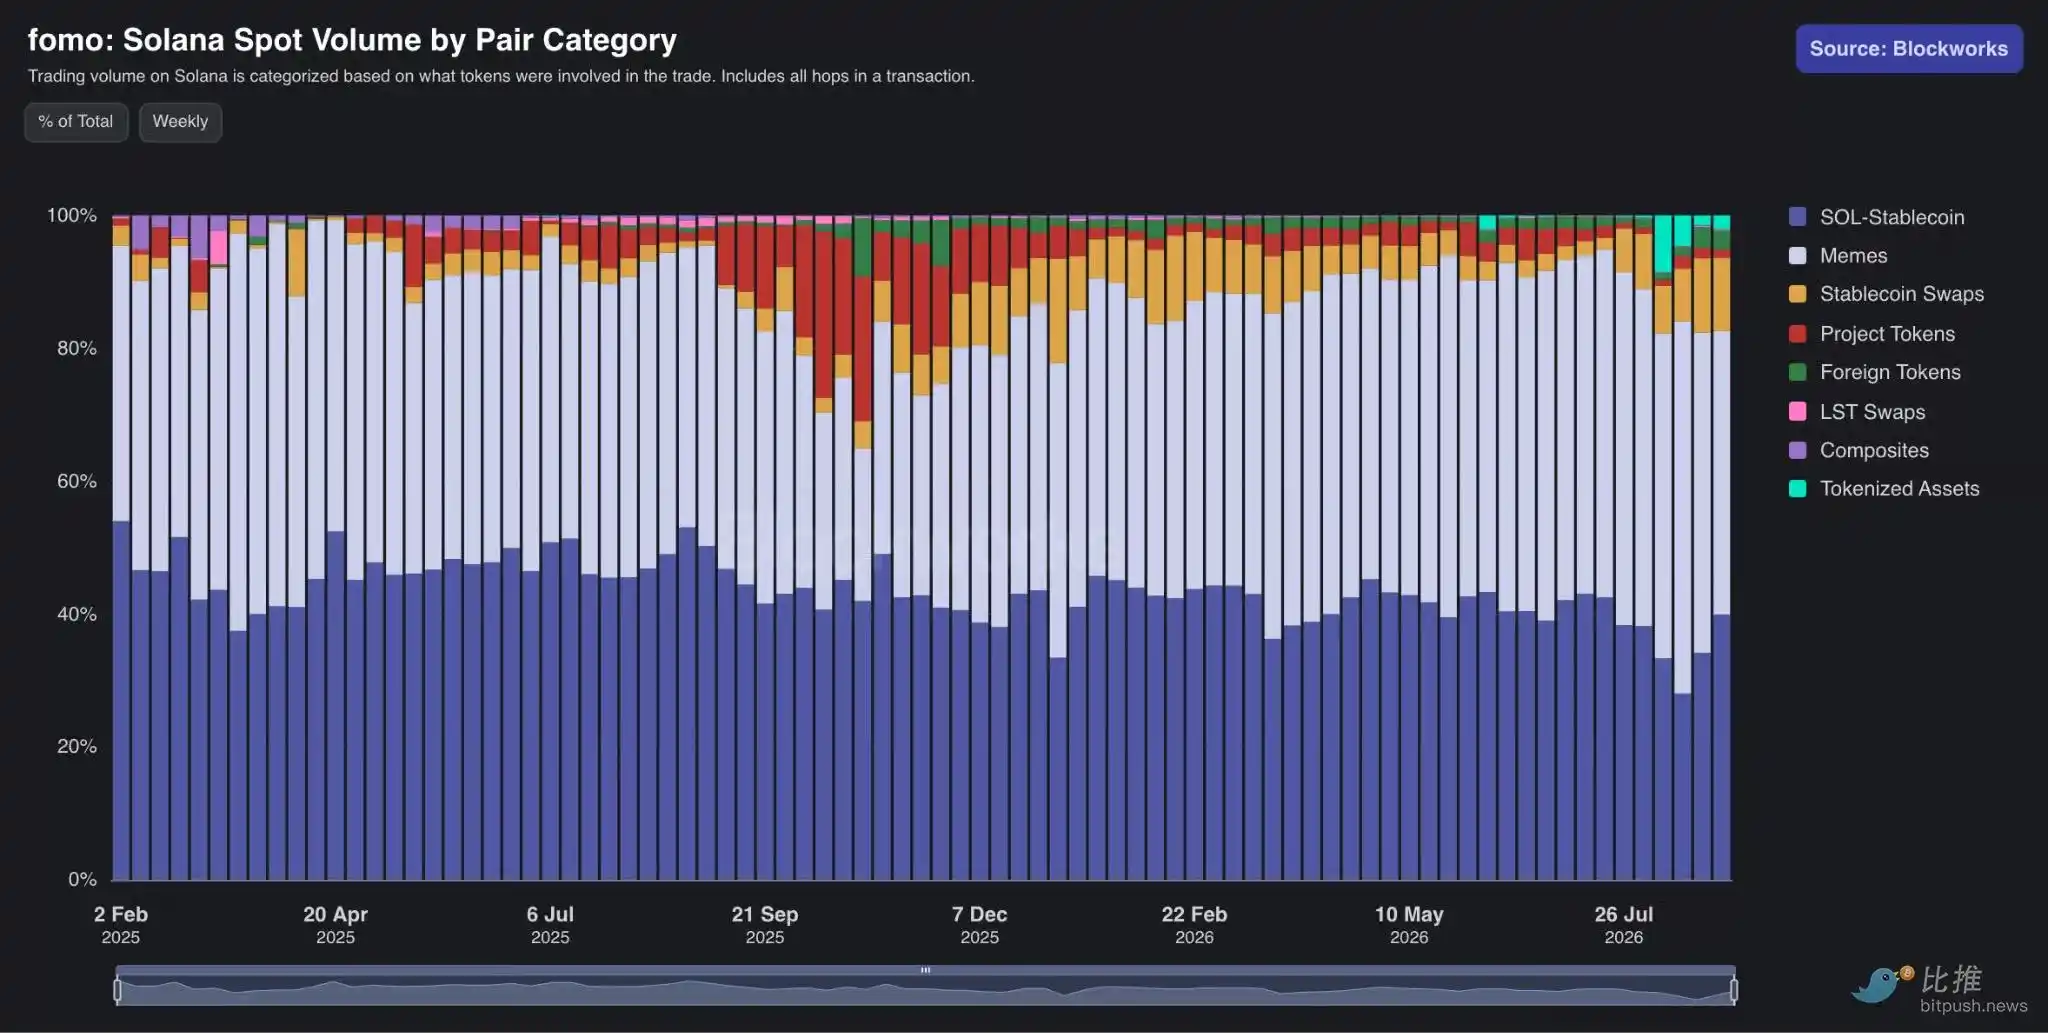
As before, what's attracting newcomers are meme coins. Looking at Fomo's Solana spot trading pair data, meme coin trading pairs consistently account for 40% to 60%, while SOL-stablecoin pairs also occupy a similar proportion. Since Fomo is priced in stablecoins, the SOL-stablecoin pairs actually largely represent meme trading behind the scenes — each time someone buys a meme coin, the capital flow is USDC→SOL→meme coin.

Because of this, many sneer, thinking Fomo is just another meme casino.

But signs show users are not satisfied with just trading memes. Earlier this year, Fomo integrated Hyperliquid's builder code, allowing non-US users to trade on Hyperliquid through it. The initial reaction was lukewarm, but activity exploded in August, with nominal trading volume reaching $1.3 billion for the month, compared to only $448.5 million in July.

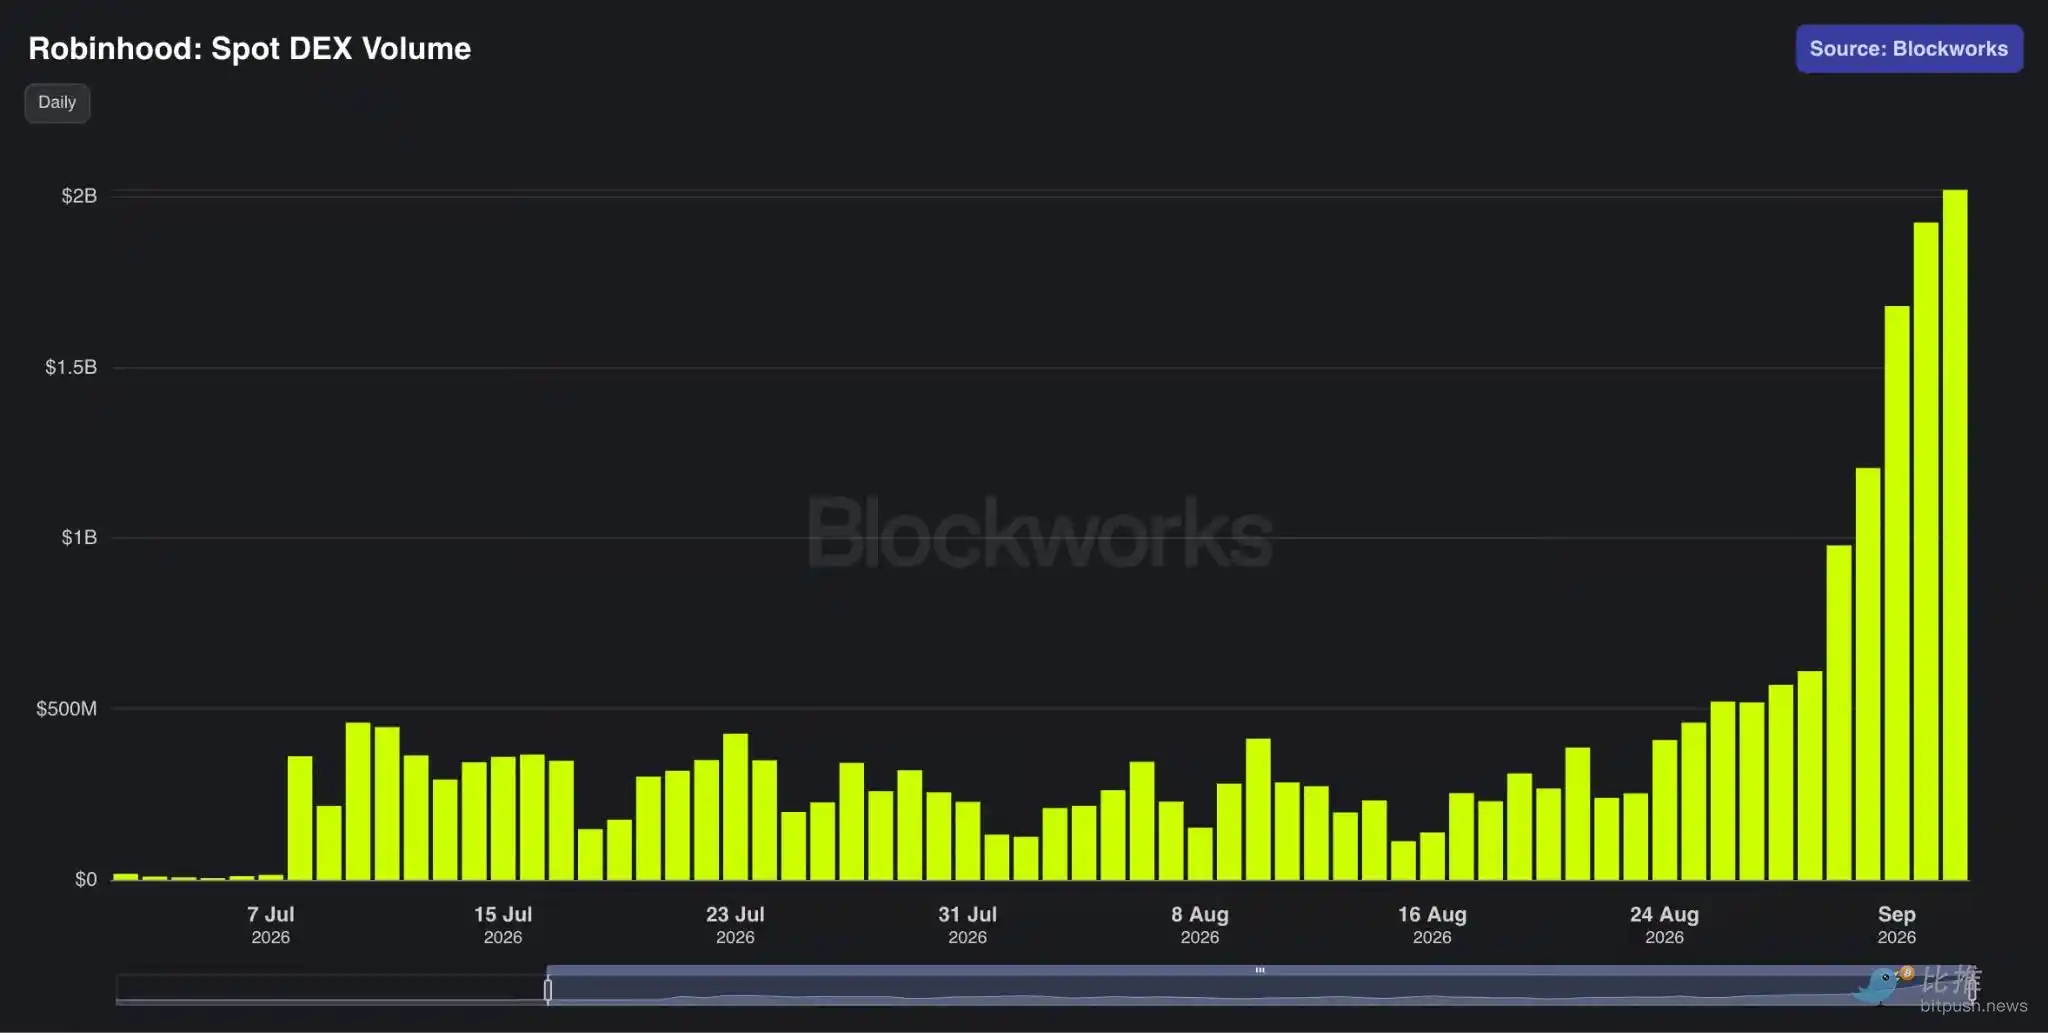
The biggest recent growth driver has undoubtedly been Robinhood Chain — its daily spot DEX trading volume broke $2 billion for the first time, with meme coins contributing significantly. Fomo恰好恰巧恰巧acts as the 'front-end entry point' for Robinhood Chain, naturally reaping the benefits.

For Fomo, this is undoubtedly a moment in the spotlight, and there are currently no signs of cooling off.
But a sobering question is: Have retail investors made money in this app?

An app being hot doesn't mean most people are making money.
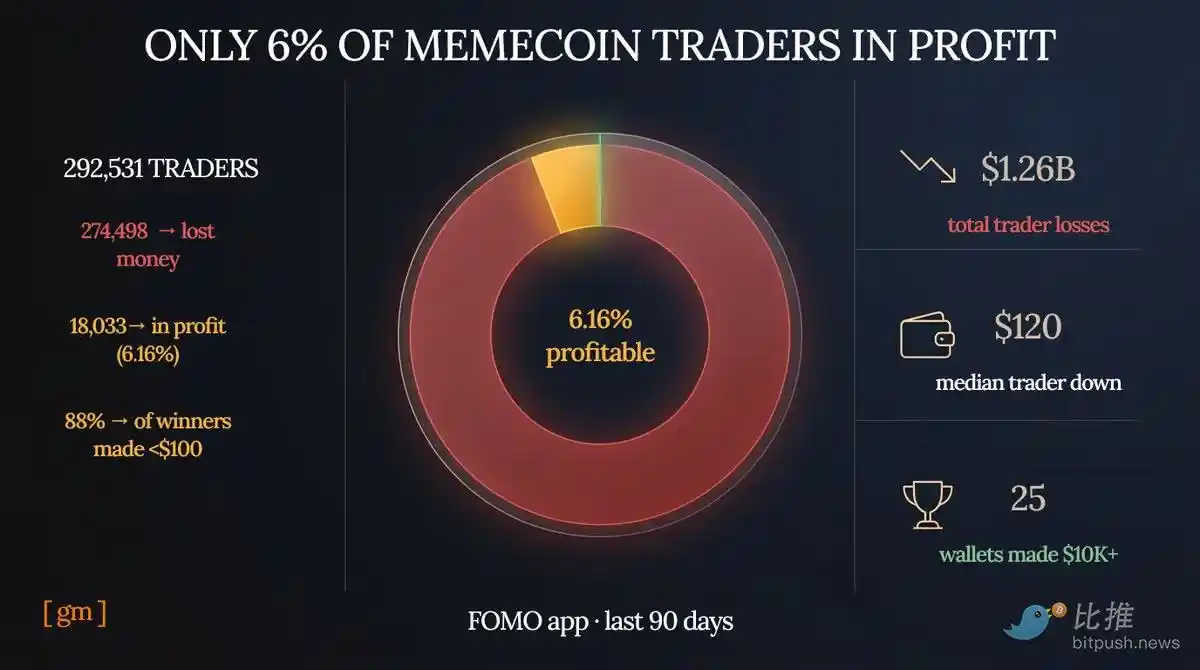
In mid-August, analyst MidCurveMortal used Fomo's fee routing for a public Dune query: Over the past 90 days, out of approximately 293,000 wallets that traded through the app, only 18,000 recorded positive profits, a profit rate of about 6.16%. The group collectively lost about $126 million, with the median trader losing roughly $120. Among that 6% of profitable wallets, about 88% had profits of less than $100; at the time, only about 25 wallets had profits exceeding $10,000.

A comparison was made with a gambling platform charging about a 1% commission, where user profit rates were about 37%. Later, broader sample analysis yielded similar conclusions — the loss side absolutely dominates, while the profit side is highly concentrated in small, positive returns.

Yet the official leaderboard tells a different story: At the end of August, the platform stated that on the top profit list for the past 30 days, 25 traders had paper gains exceeding $1 million, with about 26 people accumulating over a million in total; monitoring in early September showed the top trader added another approximately $9.8 million in a single month.
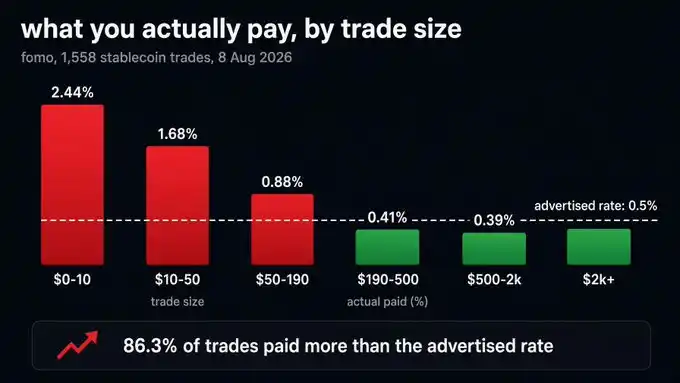
The copy-trading narrative is also being questioned — those being copied can sell at the peak when the copy-trading flow rushes in, leaving retail investors as exit liquidity. Meanwhile, Fomo itself earns transaction fees, with August revenue already at the tens of millions level. Users' expected profits did not double along with the DAU.

The conclusion is straightforward and harsh: Most people are losing money; only the platform and large players are steadily making money.

Пов'язані питання

QWhat is the main argument presented in the article about Fomo's popularity and user profitability?

AThe article argues that while Fomo, a social on-chain trading app, is experiencing explosive growth in revenue and user adoption, the vast majority of its retail users are losing money, with only the platform and a few large traders profiting significantly.

QAccording to the article, what are the key factors driving Fomo's recent growth in August and September?

AFomo's recent growth is primarily driven by meme coin trading, integration with Robinhood Chain which acts as a front-end gateway, and a surge in new users, particularly from outside the traditional crypto space.

QWhat specific data does the article cite to demonstrate that most Fomo users are not profitable?

AThe article cites a Dune Analytics query showing that in the past 90 days, only about 6.16% of approximately 293,000 trading wallets made a profit. The median trader lost around $120, and the group collectively lost about $1.26 billion.

QHow does the article contrast the public perception of successful traders on Fomo with the overall user profitability data?

AThe article contrasts Fomo's official leaderboards, which highlight traders with millions in profits, with the broader data showing that profits are highly concentrated. For example, among the small percentage of profitable users, about 88% made less than $100, and only around 25 wallets had profits exceeding $10,000.

QWhat potential conflict of interest regarding the 'copy trading' feature on Fomo does the article suggest?

AThe article suggests a conflict of interest where popular traders being copied can sell their positions at a high price when followers' funds pour in, essentially using the followers as exit liquidity, while Fomo itself profits from transaction fees regardless of user outcomes.

Пов'язані матеріали

The Life and Death of an Ordinary Meme Coin

The Life and Death of a Meme Coin Despite their association with retail speculation, meme coins effectively attract attention and liquidity to new ecosystems. However, their viral nature and low creation barriers mean they typically have extremely short lifecycles. An analysis of 150 meme coins using survival analysis techniques reveals a harsh reality. The median meme coin reaches its all-time high (ATH) just 17.2 days after its first trade, with a quarter peaking within 1.6 days. The journey from ATH to a 95% crash takes a median of 370 days. Price performance is overwhelmingly negative: over half of the coins trade more than 95% below their ATH. Only 5 out of 151 sampled coins (3.3%) have ever reclaimed their ATH after a 90% drop. By 300 days post-launch, most coins retain only 10% of their initial value. The analysis of local peaks versus the ultimate ATH shows that two-thirds of Solana-era meme coins experienced only one significant price surge, peaking within days and never recovering. Chain activity, measured by addresses with a balance over $1, mirrors this pattern, with current activity for major meme coins below 7% of its peak. While the data paints a bleak picture for long-term holding, meme coin speculation is deeply embedded in market culture and continues to migrate to new platforms. The pursuit of asymmetric returns persists, driven by gambling dynamics rather than rational investment, suggesting this trend will continue evolving alongside on-chain financialization.

marsbit1 год тому

The Life and Death of an Ordinary Meme Coin

marsbit1 год тому

The Nightmare of Timers: Missing the Best 15 Days of Performance Over the Past 3 Years, Bitcoin Returns Would Underperform Cash

**Title: The Market Timer's Nightmare: Missing Bitcoin's Top 15 Days Leads to Underperformance vs. Cash** A Grayscale report highlights a critical risk for Bitcoin investors: the immense opportunity cost of being absent from the market during its brief, explosive rallies. Over the past three years, Bitcoin delivered a cumulative return of approximately 225%. However, its gains are hyper-concentrated. If an investor missed just the 5 best trading days, the return collapses to 95%. Missing the top 10 days slashes it to 27%. If the top 15 days (less than 1.4% of the period) are missed, the return turns negative at -11%, underperforming cash. In stark contrast, the Nasdaq 100 would still retain a 21% gain after removing its own best 15 days. These crucial surge days typically occur under conditions of peak pessimism—following panic sell-offs, regulatory clarity, or short squeezes—when holding cash feels safest. The repricing is also extremely rapid, often happening within hours before a clear "right-side" trend is apparent. Therefore, the greatest investment risk for assets like Bitcoin is not volatility or drawdowns, but the high probability of missing the few days that generate virtually all excess returns. The report concludes that time in the market is superior to timing the market, emphasizing strategies like dollar-cost averaging to ensure participation during these decisive moments.

marsbit1 год тому

The Nightmare of Timers: Missing the Best 15 Days of Performance Over the Past 3 Years, Bitcoin Returns Would Underperform Cash

marsbit1 год тому

Торгівля

Спот
活动图片