By Su Yang Edited by Xu Qingyang
On October 12, the South Korean stock market experienced a significant correction. The Korea Composite Stock Price Index (KOSPI) closed down 3.65% at 6,384.25 points. The semiconductor sector underperformed, with Samsung Electronics closing down 4.39% at 250,500 won and SK Hynix falling 4.52% to 1,605,000 won. In the subsequent trading session on October 13, the Korean market continued to decline, with programmatic selling being temporarily halted at one point.
Looking back, since hitting a high of 9,385.59 points on June 22, the KOSPI has retreated nearly 32% in about four months.
This round of decline can be explained as a technical correction triggered by profit-taking at high levels. However, when shifting focus from this grand capital feast to the micro-level nodes of the AI industry chain, the pressure facing the market may go beyond short-term capital outflows.
It contains three underlying concerns: First, whether the continuous expansion of AI infrastructure investment can be smoothly converted into actual revenue and profits. Second, price squeezes from upstream equipment and components are rewriting the investment return expectations for the chip industry chain. Third, whether the high growth rate of revenue for leading large model labs can be sustained.
Once profit expectations begin to loosen, adjustments to high valuations could reinforce each other with foreign capital outflows. Coupled with margin trading and leveraged funds amplifying market volatility in a downturn, which can easily trigger margin calls and forced liquidations, the "margin call alarm" for retail investors sounds once again.
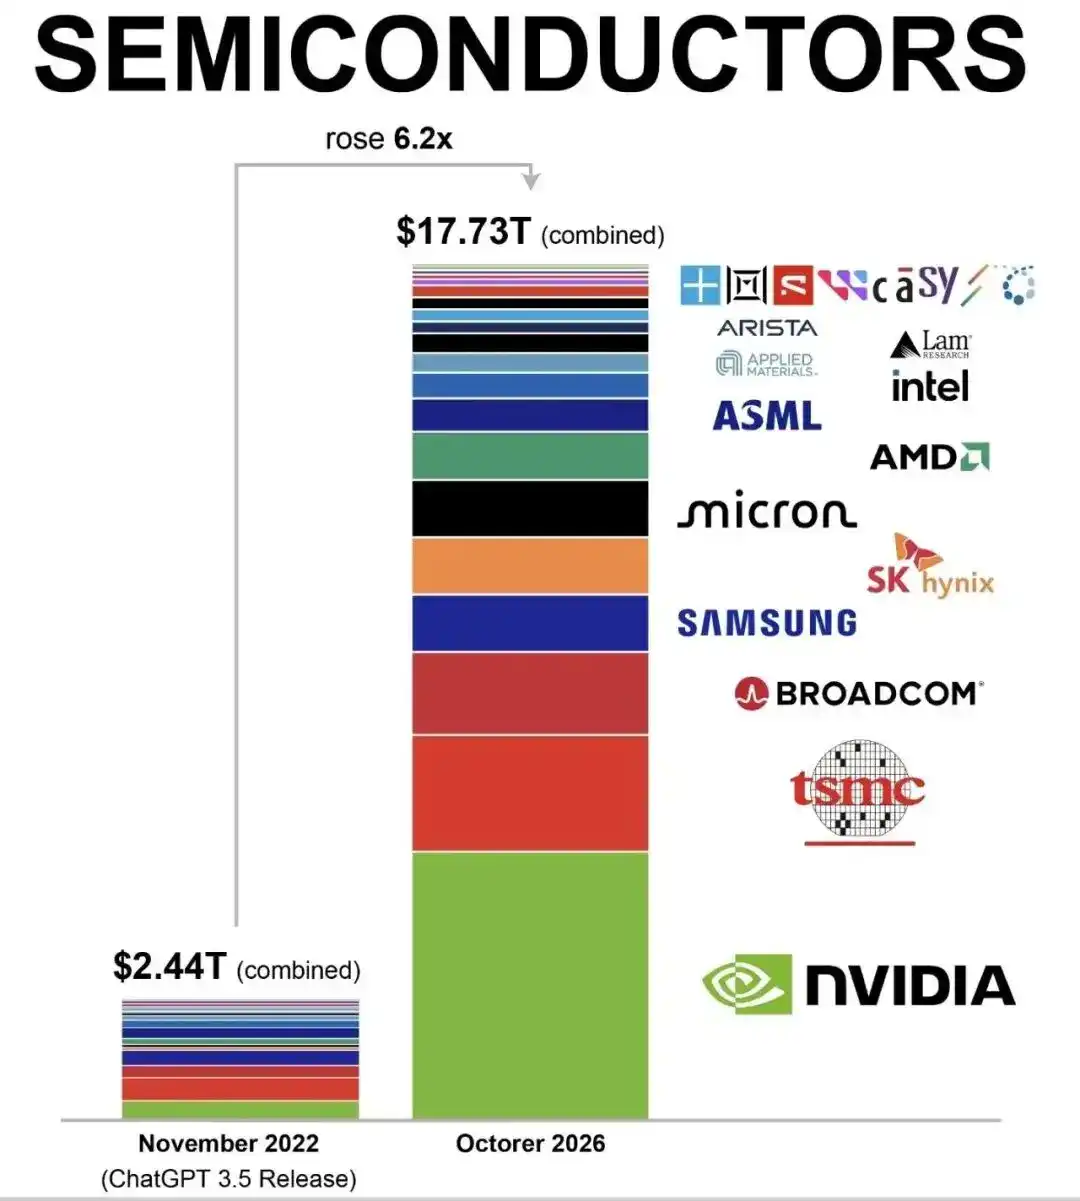
Since the release of ChatGPT 3.5, the total market value of the global semiconductor and AI industry chain has soared 6.2 times, with the chip sector becoming the core winner of this AI mega-cycle.
01 Anxiety Over "Peak Cycle"
Samsung Electronics' chip factory in South Korea
The weakness in the Korean stock market and the memory sector this time was precisely triggered by an "impressive" earnings preview.
On October 8, Samsung Electronics released its latest third-quarter earnings guidance: consolidated sales for Q3 are approximately 195 trillion won (estimated range 194 to 196 trillion won), and consolidated operating profit is about 10.74 trillion won (estimated range 10.73 to 10.75 trillion won). This represents significant year-over-year growth and falls at the upper end of analysts' previous expectations.
The strong performance is mainly attributed to the continued robust demand for AI-driven HBM and DRAM. Samsung Electronics and SK Hynix jointly dominate the HBM and DRAM markets, fully enjoying the structural dividends brought by global AI infrastructure investment.
However, the market did not see the expected cheers.
After the earnings preview was released, Samsung Electronics' stock price fell, dragging down the KOSPI index and semiconductor heavyweights like SK Hynix.
Investors reacted cautiously or even chose to take profits at highs, primarily because of a reassessment of the sustainability of the memory boom cycle. Multiple institutional analyses pointed out that Q3 profit growth may have approached the stage peak of this cycle, with Q4 quarter-over-quarter growth expected to slow to about 8%.
As the rate of memory price increases flattens and new industry capacity gradually comes online, "whether the supply shortage can last until 2028" has become a core question for the market.
In plain terms, people used to fear memory shortages; now they worry about memory not being in short supply.
This can also be seen as anxiety over a "cycle peak," after all, memory is an extremely cyclical industry.
02 The "Messy" Bill
OpenAI CEO Sam Altman
The "messy" revenue accounting standards of leading labs are also a key trigger for this round of correction.
According to disclosures by the Financial Times and multiple financial media outlets, as of the end of September 2026, OpenAI's true annualized revenue is close to $50 billion. This creates an expectation gap of about $20 billion compared to the $70 billion circulating on Wall Street and in some media outlets in previous weeks.
In other words, the market previously overestimated the revenue-generating capabilities of leading labs.
The key to this discrepancy lies in accounting standards — peers like Anthropic book sales through cloud partners on a gross basis, while OpenAI only books its own revenue, i.e., net of channel fees. Some primary market investors, seeking direct comparability between the two companies, adjusted OpenAI's data, resulting in the $70 billion figure.
After the news broke, on October 8 Eastern Time, U.S. semiconductor and cloud service stocks generally fell: NVIDIA closed down 2.94%; Oracle, which has computing power collaboration expectations with OpenAI, fell over 6%, closing down 5.48%; Micron Technology closed down 4.79%; SanDisk closed down 4.90%; CoreWeave closed down 7.77%. The Nasdaq Composite Index's decline widened to 1.25%.
Memory stocks, as a core link in the AI hardware chain, were particularly sensitive to the sentiment transmission.
According to the Financial Times report, as of the end of September this year, OpenAI's annualized revenue is about $50 billion, far below the widely expected $68 billion. Similar situations exist with other AI companies.
On October 9, insiders told Bloomberg that OpenAI still expects its annualized revenue to reach or exceed $70 billion by the end of the year, primarily driven by enterprise business growth. This "news" somewhat alleviated short-term panic, but the market has already raised its requirements for the comparability of AI revenue narratives.
Analysts point out that this turmoil largely stems from information asymmetry.
The fact that revenue data from the private company OpenAI can already affect the stock prices of public companies like Microsoft, Oracle, and NVIDIA shows that it has become an important reference for global AI asset pricing. Brokerage research indicates no signs yet of cloud infrastructure providers cutting capital expenditure.
In other words, the temporary sharp drop in the secondary market is more like profit-taking at highs and emotional stampedes, rather than a comprehensive collapse of fundamentals.
Morgan Stanley and Goldman Sachs reports still project the combined capital expenditure of global core cloud giants to reach between $1.2 trillion and $1.4 trillion by 2027. There is a natural "sedimentation lag" between the massive capital outlays for AI hardware infrastructure and the monetization speed of upstream AI software applications.
Thus, some summarize that the storage supercycle is still ongoing, but the era of "blindly buying" is over.
03 Valuation Discounts and High Capital Expenditure
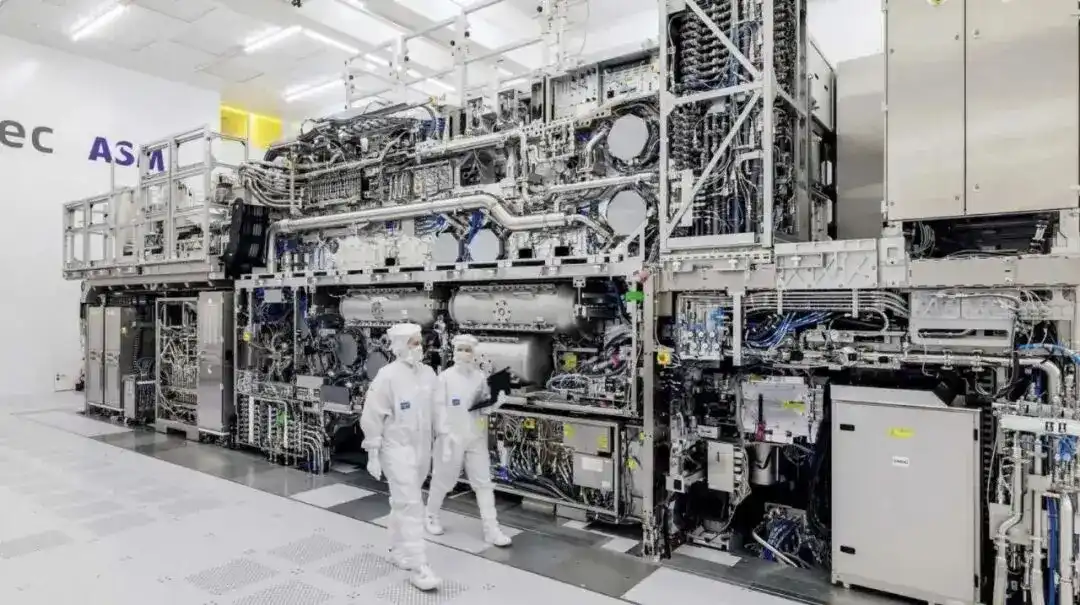
Despite short-term market sentiment pressure, the strong demand for high-performance memory from AI infrastructure construction still provides fundamental support for memory makers. However, the three manufacturers have different paths to benefit and face distinct potential challenges.
Micron mainly benefits from HBM and server DRAM demand growth. SanDisk benefits from AI data center demand for enterprise SSDs. As a key player in the HBM market, SK Hynix, with first-mover advantages and partnerships with top customers, has strong demand visibility.
However, robust AI demand is only the starting point for growth; the key is converting that demand into sustained profits and cash flow.
As earnings season approaches, memory makers' capital expenditure, advanced process investments, and advanced packaging expansion plans will also become important indicators for judging the demand outlook for upstream semiconductor equipment.
Bearish voices and market concerns are equally evident, focusing on the immense capital expenditure pressure and upstream cost squeezes — in the battle for dominance in the HBM3e and next-generation HBM4 markets, memory giants are caught in the most intense equipment and capacity arms race in semiconductor history.
Samsung Electronics has pledged to invest over 110 trillion won (approximately $8.26 billion) in capital expenditure and R&D funds in 2026, setting a company record for annual budget. SK Hynix is fully building the Cheongju M15X facility dedicated to HBM4 and spending $3.87 billion to establish an advanced packaging base in Indiana, USA.
Industry data shows that to meet the squeeze on HBM demand, by the end of 2026, up to 25% of global memory giants' DRAM wafer capacity will be forcibly locked for HBM production. Massive capital expenditures significantly increase subsequent equipment depreciation and amortization costs for companies.
Even more severe is the squeeze from upstream supply chain costs, which is further eroding profit expectations.
Previously, lithography giant ASML explicitly notified that, effective January 2027, it will uniformly raise the price of EUV and DUV lithography machine replacement parts supplied to Samsung Electronics and SK Hynix by 10%. Meanwhile, lithography machine price hike plans are also being prepared.
Against this backdrop, SK Hynix's current dynamic price-to-earnings ratio is only 6.96 times, significantly below the semiconductor industry average. While seemingly offering a valuation discount, whether this discount is reasonable largely depends on whether it can maintain the quality and sustainability of future profits under the dual pressures of high capital expenditure and rising operating costs.
04 Retail Investors in the Fear of Margin Calls
The risks of high-leverage trading among South Korean retail investors had already sounded alarms as early as this summer.
The 24-year-old Seoul university student Lee Seung-ho, previously reported by Reuters, became the most vivid early warning and typical example of this leverage risk.
Seoul university student Lee Seung-ho who suffered losses and margin calls
Reuters reported that Lee Seung-ho saved 20 million won and engaged in 5x leverage trading through a trading app, with his account assets once surging to 300 million won (approximately 1.55 million RMB). However, as market volatility intensified in May, margin calls and forced liquidations followed. He lost all his gains and principal within just four weeks.
In the report, he described his physical and mental state at the time as "literally unable to breathe."
However, the risks accumulated through high-leverage trading were not timely resolved. Instead, they have been simmering and spreading to the present, along with the popularity of single-stock leveraged products among retail investors.
On October 12, the South Korean stock market suffered a brutal decline, unleashing a concentrated outburst of this long-suppressed panic and anxiety on social media. After the market closed, Korean investors flooded social platform X with expressions of confusion and discontent.
Some retail investors compared the Korean stock market's performance with that of U.S. and Japanese stocks, questioning why the Korean market continued to be under pressure. Others pointed fingers at the continuous outflow of foreign capital, believing that the Korean market failed to fully benefit during global market rallies but bore greater pressure during corrections.
These posts reflect strong dissatisfaction among retail investors with market performance, but behind the sentiment lie more noteworthy capital flow changes.
According to recent trading data, foreign capital net sold nearly 2 trillion won of Korean stocks on October 12 alone, with cumulative net sales reaching 29.7 trillion won (approximately 156 billion RMB) over the past month. If confirmed, this means foreign capital exodus from Korean stocks has become a significant source of pressure in this market adjustment.
If foreign outflows explain why the market is under pressure, leverage trading relates to why declines could be further amplified.
Controversy surrounding Korean single-stock leveraged ETFs has been simmering in investor communities recently.
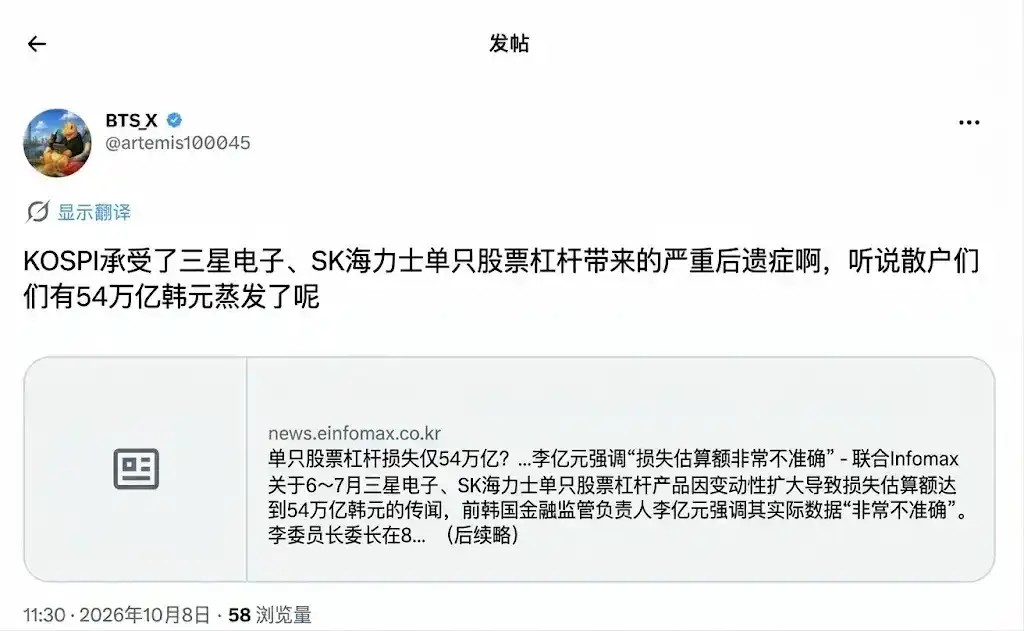
One post cited related estimates that retail investors' asset losses on single-stock leveraged products amounted to 54 trillion won (approximately 2.835 trillion RMB). This figure reflects the immense destructive power of high-risk derivatives during market volatility, but has also sparked much debate about its statistical scope and calculation sample.
Leveraged products significantly amplify stock price volatility.
When the market falls, portfolio shrinkage can trigger margin calls, forcing investors to liquidate positions passively and exacerbating downward pressure. Whether the daily rebalancing mechanism of single-stock leveraged ETFs amplifies selling pressure on underlying stocks on specific trading days requires specific analysis based on product structure and actual fund flows, and cannot be generalized.
From Lee Seung-ho's margin call and zeroing out in July, to the outcry on social media over the 54 trillion won massive loss, the extreme fragility of high-leverage trading during market reversals has been exposed.
Therefore, this adjustment in the Korean stock market involves both investors' reassessment of the AI industry's growth prospects and exposes the vulnerability of high-leverage trading during market reversals — when stock prices no longer rise continuously, the profit advantages brought by leverage can quickly turn into risks.
For some retail investors, the cruelty lies not in temporary losses, but in being forced to exit the market due to insufficient funds before a rebound occurs.
The "tragedy" of former OpenAI researcher Leopold Aschenbrenner, hailed as the "Wall Street AI New Stock God" at 25, who was taken out by a four-fold leverage margin call on the eve of the tech stock rebound in late July, is a typical example.