Global Stock Market's Storm Center: South Korea's Stock Market De-leveraging Is Largely Complete

链捕手Опубліковано о 2026-07-21Востаннє оновлено о 2026-07-21

Анотація

Storm's Eye: South Korean Market De-leveraging Nears Completion The recent sharp correction in South Korean equities, with the KOSPI index dropping 32% from its June high, has been a key trigger for global tech stock volatility. The core driver was not a fundamental shift but a forced de-leveraging process within the market's unique structure, which is now largely complete. Two main leverage channels amplified the sell-off: 1. **Leveraged ETFs:** Their size, proportionally four times larger than in the U.S., peaked near $50 billion. Their mandatory daily rebalancing mechanism created a vicious cycle of "price drop → forced selling → further drop." Approximately 75% of this excess has been unwound, shrinking to $26 billion, with regulatory curbs now blocking new inflows. 2. **Hedge Fund Leverage:** Using swaps to magnify exposure, hedge funds saw their net long positioning fall by over 50% from peak levels. The most intense phase of this institutional de-leveraging is over. In contrast, **retail margin debt** poses minimal systemic risk. At 0.5% of market cap, it is far lower than in the U.S. or China, lacks automatic triggers, and is concentrated in smaller stocks. The conclusion: the high-leverage structures most prone to "chain-reaction selling" have been substantially cleared. The market is transitioning from a liquidity-driven crash to one priced more on fundamentals. The article argues that the AI trend—centered on Korean memory chips—remains intact. This episode r...

Recent severe volatility has emerged in the South Korean market, with the South Korean KOSPI index experiencing a maximum drawdown of 32% since its high of 9385.6 points on June 19.

As the most concentrated 'storm center' in this round of the global AI thematic market, the adjustment in the South Korean market has become a key trigger for this wave of global technology stock volatility, leading to widespread corrections in global tech stocks.

In terms of sequence, this round of decline originated from fundamental expectation disruptions and short-term capital rotation,but the core variable that truly magnified the decline is the highly concentrated leverage capital structure in the South Korean market.

Notably,from the current perspective, the fundamentals of the South Korean market have not fundamentally changed, and the passive unwinding process driven by leverage has entered its final stage.

Leveraged ETF Unwinding Progress at 75%

The core trigger for this market volatility is the massive expansion and concentrated unwinding of leveraged ETFs.

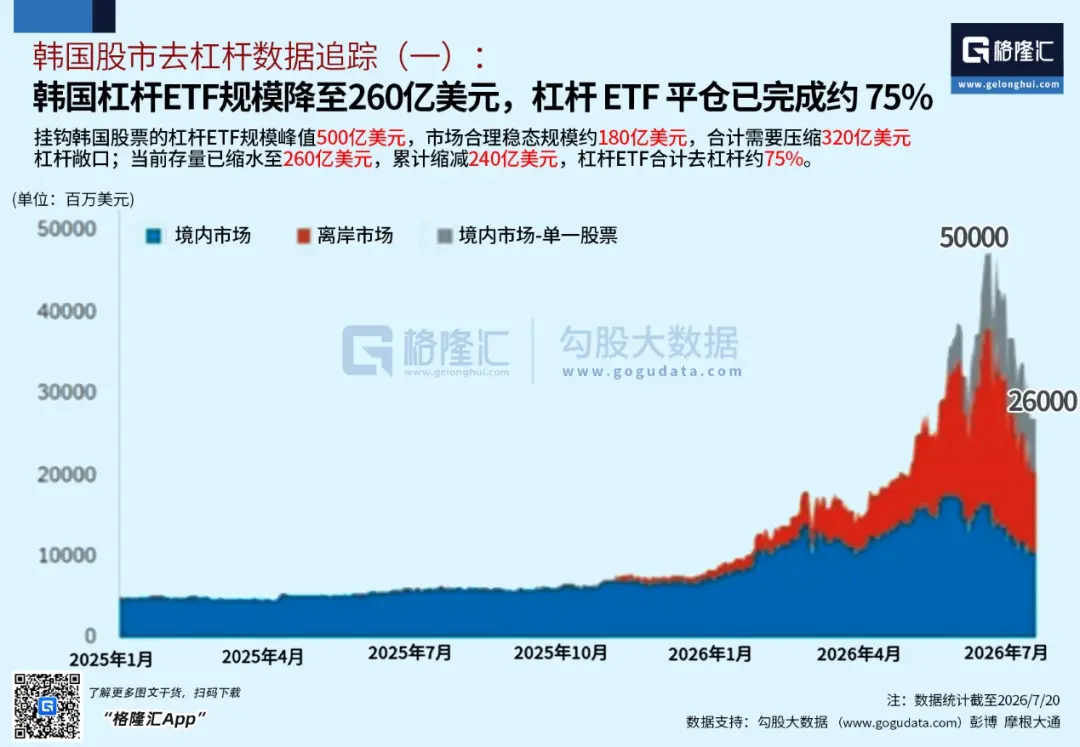
During the earlier phase of rapid stock market gains, the scale of leveraged ETFs once approached $50 billion, with their share of the total South Korean stock market capitalization being about four times that of the US market, significantly amplifying the market's inherent volatility.

This high-leverage structure meant price movements were no longer driven purely by fundamentals but were dominated more by position structures.

High volatility, on one hand, deterred the entry of volatility-sensitive long-term capital, and on the other, significantly increased the operational difficulty for asset managers and brokerages under risk control constraints.

Entering June-July, with the global AI hardware sector temporarily weakening, coupled with the leveraged ETFs' 'daily rebalancing' mechanism—characterized by passively adding positions on gains and concentrated selling on losses—any correction in leading stocks easily triggered a negative feedback loop: 'stock price decline → margin calls → forced liquidation → further stock price decline'.

In late June, several leveraged ETFs experienced single-day declines exceeding 25%, driving the market to trigger circuit breakers, with the volatility index VKOSPI once soaring to five times the level of the US stock market's VIX index, and market liquidity temporarily approached a standstill.

According to institutional estimates, the scale of leveraged ETFs has rapidly contracted from a peak of about $50 billion to $26 billion, a cumulative reduction of approximately $24 billion.Based on a reasonable existing stock estimate of about $18 billion, the current unwinding progress has reached about 75%, with about 25% remaining adjustment space, showing significant convergence.
Simultaneously, regulators have begun constraining leverage expansion at the institutional level.

Regulators will implement strict new rules starting in August:From August 5th, suspending all new single-stock leveraged ETF issuances, raising the minimum transaction cash threshold from 10 million KRW to 30 million KRW; from August 19th, only cash can be used as initial margin; starting November, the minimum trading unit for single-stock leveraged ETFs will be increased from 1 share to 20 shares.
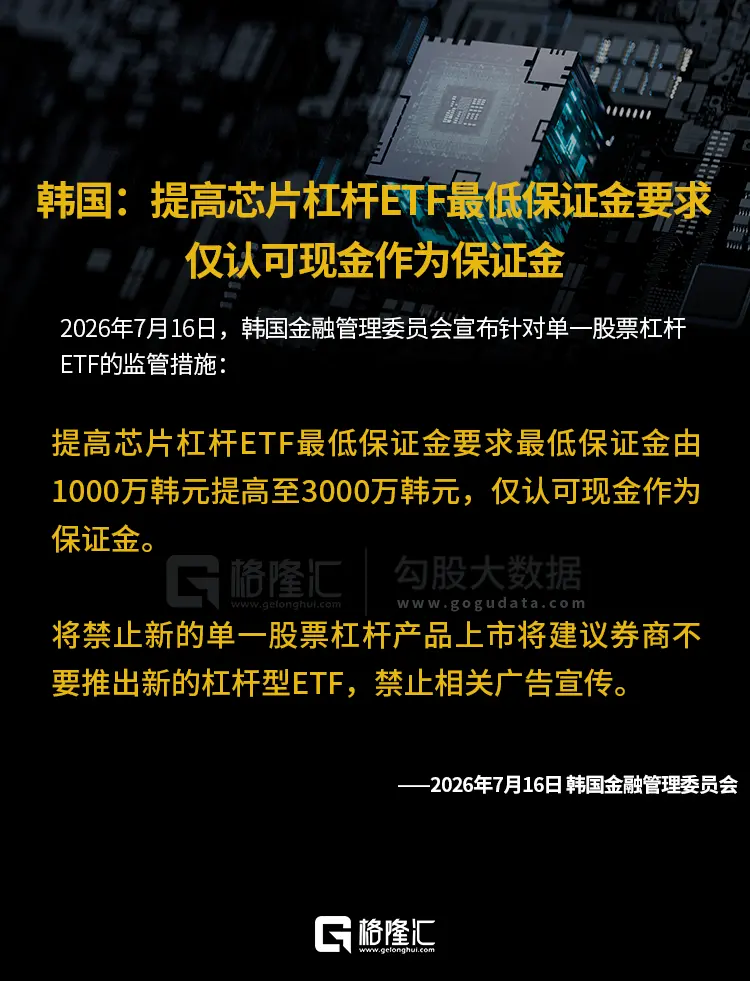
As these policies are gradually implemented, channels for new high-leverage capital entry are effectively blocked, and the scale of leveraged ETFs is expected to contract further, reducing the mechanistic risk of amplified volatility from the source.

Hedge Fund De-leveraging Exceeds 50%

In addition to leveraged ETFs, the high-leverage allocations of hedge funds were also a significant amplifier of this volatility wave.

Since April this year, global equity and macro hedge funds significantly increased allocations to the South Korean market, using Total Return Swaps (TRS) provided by brokerages to amplify stock exposure. During the uptrend, this structure significantly boosted market elasticity; but during corrections, it simultaneously amplified de-leveraging pressure.

With the index's decline and the memory chip sector underperforming the broader market, the strain on swap limits has noticeably eased.

Institutional estimates show thatthe long-short ratio has fallen from a peak of about 5.5 times to below 4 times; using the extreme period's roughly 7 times long-short ratio and corresponding 6 times net long position as a reference, the current net long position of about 3 times implies leverage has declined by over 50%.
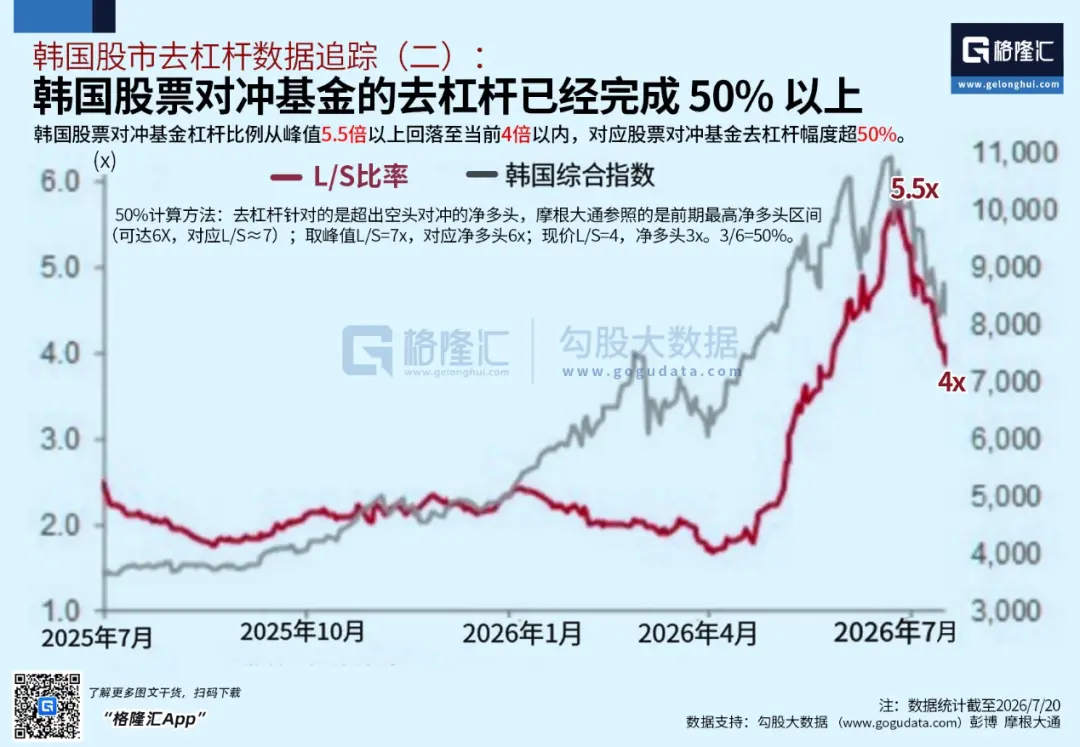
Meanwhile, as stock price declines led to reductions in MSCI index weights, the forced selling pressure from passive index funds has largely been released, significantly alleviating liquidity run risks on the institutional side.

Overall, the 'passive de-leveraging' process at the hedge fund level has completed its most intense phase.

Korean Retail Margin Financing Is Not the Major Risk Source

Compared to leveraged ETFs and hedge funds, South Korean retail margin financing contributes relatively limitedly to systemic risk.

Currently, the balance of South Korean retail margin financing has declined from over $25 billion to about $21 billion, accounting for about 0.5% of the total South Korean stock market capitalization. This level is not only lower than the US market's approximately 1.9%, but also significantly lower than the A-share market's margin financing ratio of about 2.8%.
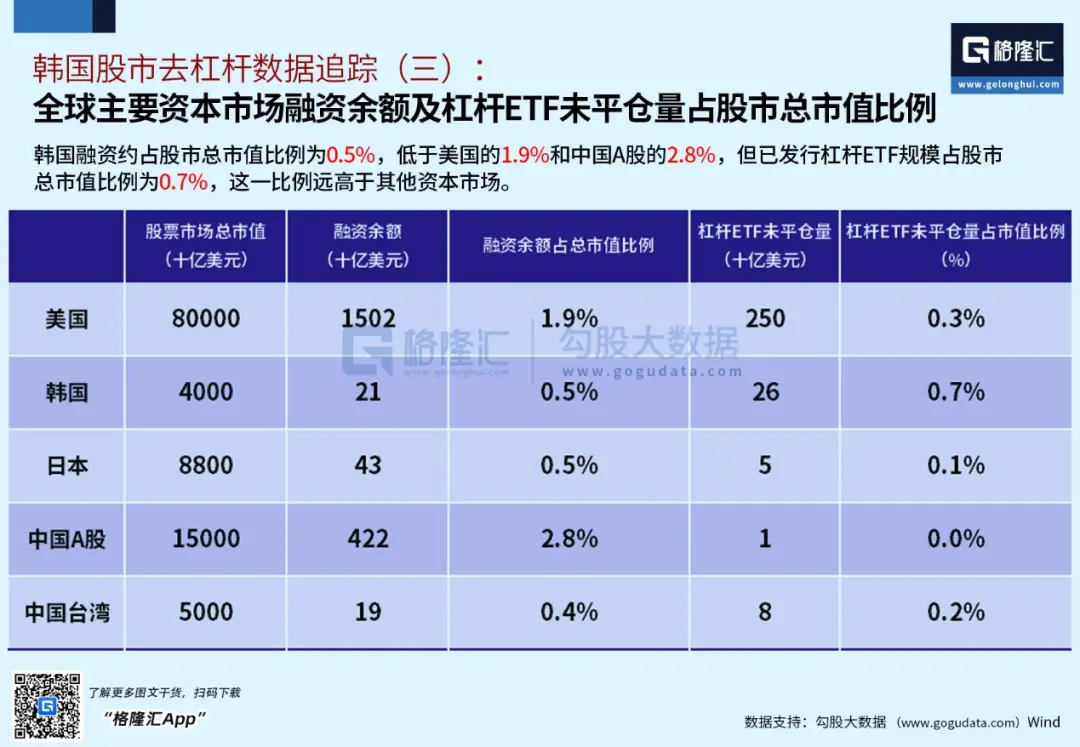
Structurally, retail margin financing is more concentrated in the KOSDAQ market, which has a higher proportion of small and mid-cap stocks, and has a relatively limited direct impact on the core KOSPI-weighted stocks.

More crucially, ordinary margin accounts do not have a similar 'mechanical rebalancing' mechanism like leveraged ETFs.During stock price declines, investors are not forced to quickly reduce positions, making it difficult to form a chain reaction of panic selling.

Additionally, South Korean household assets still include cash, overseas assets, and previously accumulated stock gains, providing a certain buffer space.

Therefore, from a transmission mechanism perspective, retail margin financing is unlikely to become the core variable triggering systemic risk, nor does it have a realistic basis for large-scale, cascading liquidations.

Overall, the de-leveraging process in the South Korean market can be clearly summarized as follows: leveraged ETFs have unwound about 75%, hedge fund de-leveraging exceeds 50%, retail margin financing risks are controllable, and foreign passive selling pressure has been largely released.

Compared to the initial stage of the decline, the high-leverage structures most likely to trigger 'chain reaction selling' have largely completed their unwinding. The market is gradually transitioning from a 'liquidity-driven decline' to 'fundamentals-driven pricing'.

Against this backdrop, as long as fundamentals do not show a trend reversal, this round of adjustment is closer to a concentrated unwinding of crowded trades, rather than the end of the AI thematic market.

Conclusion

Looking further ahead, we must hold a firm conviction:The AI megatrend is irreversible, the silicon-based revolution is irreversible.

Almost all technological revolutions in history have followed a similar path: first, a compelling narrative is established, and capital rapidly flows in; subsequently, due to excessive crowding and leverage amplification, severe volatility is triggered; finally, true reshuffling of holdings is completed during the unwinding process. Each decline, superficially a price retracement, is essentially an optimization of structure.

This time is no exception.

The reason the South Korean market became the storm center is not because it is more fragile; on the contrary, it's precisely because it stands at the most crucial position in the AI industrial chain—memory chips. Capital first rushes to the most certain place, and it's easiest for crowding to form there. When leverage is superimposed on a trend, volatility is no longer a risk but an inevitability.

But now, the most dangerous stage is passing.

What we truly need to consider now is never short-term price movements, but: is this race still on?

If the answer is yes, then volatility is a cost, not a risk.

The megatrend of AI has not changed in any way due to this round of adjustment. Computing power demand is still growing exponentially, large language models are still accelerating iteration, and data centers, optical communication, and advanced packaging—every link is expanding. This is not an industrial path that can be easily disproven; it's a productivity revolution unfolding before us.

One could even say—it has no way back.

Our generation, in fact, does not lack hard work; what we lack is the 'entry point' for generational dividends. Many people looking back at their parents' generation often have complex feelings: during the reform and opening-up era, it seemed opportunities were everywhere—those who went into manufacturing, went into business, engaged in trade—many who seized one opportunity changed their entire lives.

You might also have asked: why could they, but why can't we?

But the issue is that the form of opportunities differs for each generation.

Today's opportunities are no longer about opening factories or doing trade, but about standing on top of the technological wave and participating in industrial upgrading through capital. AI is not just an opportunity for a single company; it's the entire era's dividend distribution mechanism being restructured.

Semiconductors, large language models, computing power networks, optical modules—these fields, which sound complex and have high entry barriers, indeed are not areas ordinary people can participate in by 'jumping in personally.' But the capital market precisely provides a path—you don't need to become an engineer or an entrepreneur; you only need to understand the trend and participate in it.

What's truly important is not whether you can precisely select every single investment target, but whether you are positioned in the right direction.

With the right direction, volatility is just part of the process; with the wrong direction, no amount of effort is anything but waste.

So, returning to the core question

If AI is ultimately proven wrong, then our generation may indeed have lost its most important opportunity; but if it is right, then every adjustment now is an opportunity for later-comers to get back on board.

The market won't stop because you hesitate, nor will the era slow down because you are uncertain.

The only thing you need to decide is whether to get on board.

Пов'язані питання

QWhat is the core driver behind the sharp decline in the Korean stock market according to the article?

AThe core driver was the highly concentrated leveraged capital structure in the Korean market, particularly the massive expansion and subsequent unwinding of leveraged ETFs, which significantly amplified market volatility.

QWhat progress has been made regarding the deleveraging of leveraged ETFs in the Korean market?

AThe article states that leveraged ETF scale has contracted from a high of about $50 billion to $26 billion. Based on a reasonable estimate of $18 billion, the deleveraging progress has reached approximately 75%, with only about 25% of adjustment remaining.

QHow much has the leverage for hedge funds operating in the Korean market been reduced?

AHedge funds have seen their leverage reduced by more than 50%. The long-short ratio has fallen from a peak of about 5.5x to below 4x, and the current net long position level of about 3x indicates significant deleveraging.

QIs retail margin financing considered a major systemic risk source for the Korean market?

ANo, it is not considered a major source. Retail margin balance has decreased from over $25 billion to about $21 billion, accounting for only about 0.5% of the total market capitalization. Unlike leveraged ETFs, it lacks a mechanical rebalancing mechanism that triggers chain reactions.

QWhat is the article's overall conclusion about the nature of the recent market adjustment and the future of the AI trend?

AThe article concludes that the adjustment represents a concentrated unwinding of crowded trades and a structural optimization, not the end of the AI trend. It asserts that the AI revolution is irreversible, and as long as the fundamentals remain unchanged, volatility is merely a cost, not a fundamental risk.

Пов'язані матеріали

Beyond APR: After Staking, Who Really Owns Your ETH?

Beyond APR: Who Actually Controls Your ETH After Staking? The article challenges the common focus on Annual Percentage Rate (APR) when choosing ETH staking services. It argues that as staking yields converge, the more critical question is who controls the staked assets. The core of non-custodial staking lies in Ethereum's key separation design. A validator uses two keys: a **Signing Key** (for online consensus tasks) and a **Withdrawal Credential** (the ultimate control over funds). Service providers can manage the Signing Key to run the validator but cannot access the staked ETH. The user retains the Withdrawal Credential, which can be kept offline. Post-EIP-7002, users can even force a validator exit directly from their wallet if a service provider disappears. Four roles are involved: 1. **User:** Retains ultimate fund control via the Withdrawal Credential. 2. **Wallet:** Acts as an interface for managing permissions, not an asset owner. 3. **Node Service Provider:** Manages validator operation (Signing Key), carrying risks related to performance and slashing, but not fund theft. 4. **Ethereum Protocol:** Governs the immutable rules for activation, exit, and withdrawal. The piece contrasts this with Liquid Staking like Lido. Users receive a liquid token (e.g., stETH) representing a claim on pooled staked ETH, enabling DeFi composability. However, they do not control individual validator withdrawal credentials; redemption relies on the protocol's withdrawal queue. This trades direct control for liquidity and lower entry barriers. The conclusion is pragmatic: Liquid staking suits users with smaller amounts or high liquidity needs. For long-term holders with 32+ ETH, where yield differentials are minimal, the security model and direct control of a non-custodial, native stake become paramount. The essential question shifts from "What's the APR?" to "Who holds the keys to my staked ETH?"

marsbit18 хв тому

Beyond APR: After Staking, Who Really Owns Your ETH?

marsbit18 хв тому

Riemann Hypothesis Pushed to 99.55% of Theoretical Boundary: Meta-Architecture AI Reshapes Its 'Brain' Through Thinking

When we marvel at large language models writing poems or coding, scientists face a more challenging question: how can AI tackle complex, long-term scientific problems that require months or years of sustained, uncertain reasoning? Traditional AI approaches use a fixed architecture—like forcing a mathematician, physicist, and engineer to share the same brain. While versatile, such a system often lacks specialization for specific, complex tasks. Recently, an international academic team introduced the Eureka framework, a groundbreaking solution. Instead of a fixed brain, Eureka allows AI to dynamically grow task-specific architectures during problem-solving—creating the optimal dedicated brain for each challenge. In rigorous testing, Eureka completed all 170 complex recursive long-horizon tasks, generating 3,948 verifiable certificates without a single instance of erroneous self-approval or false completion. Eureka demonstrated remarkable adaptability across two distinct scientific challenges: 1. Advancing the Riemann Hypothesis: For this mathematical milestone, Eureka constructed a specialized agent that expanded the scope of a key proof path—local Weil quadratic form positivity—from a ≤ 1/4 to a ≤ 69/200 (0.345). This reaches 99.55% of the theoretical first barrier, representing a significant, verifiable step forward. 2. Reconstructing Physical Theory: In exploring quantum processes and spacetime theory, Eureka generated a theory-discovery agent. It produced five progressive structural findings, rigorously proving that behavioral equivalence does not imply essential equivalence—providing a stricter standard for comparing physical theories. Why Fixed Architectures Fall Short: Predefined AI structures—whether single- or multi-agent—are efficient for known problems but struggle with the long-term uncertainty and structural variability of scientific discovery. They face issues like architecture mismatch and planning failures when early assumptions are invalidated. The Eureka Approach: A Meta-Architecture for Self-Evolution Eureka integrates task execution and brain shaping. Its workflow includes: - Dynamic task compilation into a flexible "obligation graph." - Identifying "architectural hotspots" where specific tools, memory, or collaboration patterns are repeatedly needed. - "Architectural promotion": compiling dedicated "macro-agents" with their own memory, tools, verification standards, and workflows to handle specialized subproblems. - Controlled self-evolution: upgrading macro-agents only when benefits clearly outweigh costs. Results and Outlook: Eureka reduced core contextual overhead by 57.8% and avoided 65.38% of redundant computations. In concurrent testing with 16,000 tasks, it ensured perfect consistency with sequential execution, eliminating data conflicts. This approach paves the way for AI in high-difficulty scientific domains—accelerating mathematical research, aiding theoretical physics discovery, and managing large-scale engineering problems like chip design or drug development. Eureka represents a paradigm shift: future AI capability may depend less on model scale and more on dynamic, task-aware brain shaping.

marsbit23 хв тому

Riemann Hypothesis Pushed to 99.55% of Theoretical Boundary: Meta-Architecture AI Reshapes Its 'Brain' Through Thinking

marsbit23 хв тому

Want to Buy a Dog? Buy NVIDIA First: Are Equity Memes the Engine of This Bull Market?

The article explores the emergence of "stock-meme" coins on the Robinhood Chain, a new trend where meme tokens like Artificial Inu are paired directly with tokenized stocks like Nvidia (NVDA). This mechanism forces trading activity for otherwise static tokenized equities. The narrative suggests this fusion could be a catalyst for the next crypto bull market, akin to how ETFs brought traditional finance capital last cycle. However, the model faces critical challenges. A case study involving HIMS stock tokens revealed a 460% premium over the real stock price on a weekend, exposing a fundamental flaw: token supply is controlled by a single authorized participant who can only mint new tokens when the underlying stock market is open. This leaves the 24/7 crypto market vulnerable to disconnection from real-world pricing and liquidity. Data analysis shows frenetic but shallow activity: 61% of wallets are one-day users, bots generate over half the trading volume, and median transaction sizes are small. While tokenized stock holders increased 155% in 30 days, regulatory uncertainty and geographic restrictions (blocking US, Canada, UK users) limit new capital inflow. The article concludes that while "stock-memes" can ignite short-term hype, their sustainability as a "bull market engine" depends on attracting genuine external capital rather than just recycling existing crypto funds.

marsbit23 хв тому

Want to Buy a Dog? Buy NVIDIA First: Are Equity Memes the Engine of This Bull Market?

marsbit23 хв тому

Торгівля

Спот
活动图片