# Dilution İlgili Makaleler

HTX Haber Merkezi, kripto endüstrisindeki piyasa trendleri, proje güncellemeleri, teknoloji gelişmeleri ve düzenleyici politikaları kapsayan "Dilution" hakkında en son makaleleri ve derinlemesine analizleri sunmaktadır.
Metaplanet's Executive Option Program Draws Shareholder Ire, CEO Addresses MMXX Links

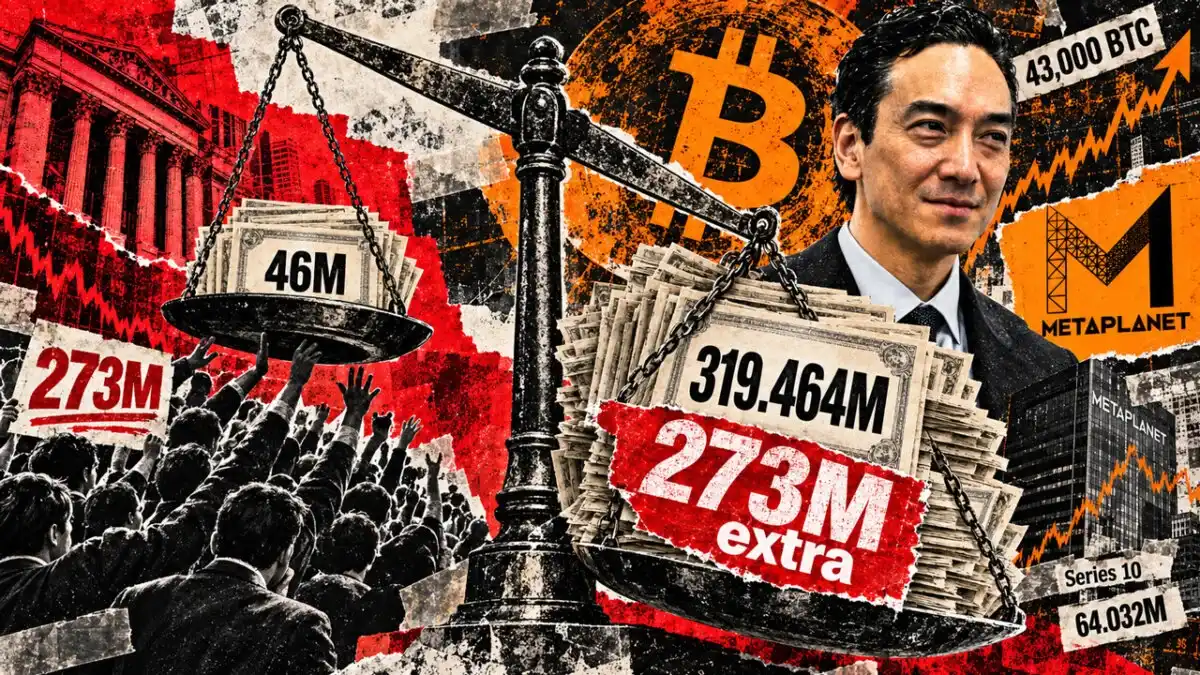
Metaplanet's executive stock option program continues to draw shareholder ire over dilution concerns. Several shareholders have criticized the 10th series of options, designed to cover 20% of fully diluted shares and automatically expand as the company issued new shares to fund Bitcoin accumulation. Bitcoin Magazine CEO David Bailey defended the model, stating that granting the team 20% of the company over five years is "not some crazy metric." However, critics, including pseudonymous shareholder Bitcoin Pharaoh, argue the program grew from 46 million to 319.5 million shares, significantly diluting existing holders. They allege Bailey personally benefited from options granted at a deep discount. Metaplanet CEO Simon Gerovich pledged to review corporate governance and compensation policies and distanced himself from shareholder MMXX Ventures, stating he is a significant but not majority owner and holds no executive role there. He noted the company froze the program at 319.5 million shares on August 18. VanEck's Matthew Sigel suggested Metaplanet should freeze further vesting of the 10th series, seek voluntary forfeiture of excess rights, and replace the plan with a shareholder-approved incentive tied to Bitcoin per share. Metaplanet acknowledged the expansion "enhances the dilution borne by existing shareholders." Its shares closed higher in Tokyo on Wednesday, trimming a five-day loss.

cryptonews.ru09/09 15:58

Metaplanet's Executive Option Program Draws Shareholder Ire, CEO Addresses MMXX Links

cryptonews.ru09/09 15:58

Metaplanet's Bitcoin Strategy Accidentally Spawns Exorbitant CEO Pay Package, Sparking Shareholder Outrage

Metaplanet's aggressive Bitcoin treasury strategy has sparked shareholder backlash over a massive, unintended increase in executive compensation. The controversy centers on the company's "Series 10" stock acquisition rights plan. An adjustment clause in this 2023 plan, designed to keep the option pool at roughly 20% of fully diluted shares, caused the potential award pool to balloon from 46 million to approximately 319.46 million shares as Metaplanet repeatedly issued new stock to fund Bitcoin purchases. Although Metaplanet abolished the adjustment mechanism in August 2024, citing concerns over shareholder dilution and potential conflicts of interest, it froze the pool at the enlarged size. This left roughly 273 million "extra" potential shares still allocated to management. Shortly after, CEO Simon Gerovich exercised part of his award, acquiring 64.032 million shares at a deep discount, creating a paper profit of nearly ¥15 billion. Shareholders, led by investor Ragnar, are demanding the cancellation of the 273 million extra shares. They argue this unearned award, which lacks performance conditions, unfairly dilutes the key metric of "Bitcoin per fully diluted share." Removing these shares would boost the ratio by about 20%. The dispute has extended to governance concerns regarding Gerovich's links to a major shareholder, MMXX Ventures. While Metaplanet has acknowledged communication failures and is reviewing its governance, it has not committed to reversing the pre-abolition share award, leaving the core shareholder demand unmet.

marsbit09/09 10:50

Metaplanet's Bitcoin Strategy Accidentally Spawns Exorbitant CEO Pay Package, Sparking Shareholder Outrage

marsbit09/09 10:50

Stanford Business School Internal Guide: Look Beyond the Reputation, How to Accurately Identify the 5% of Truly 'Top VCs'

"Stanford Business School Internal Guide: Beyond Reputation, How to Precisely Identify the Top 5% of 'Elite VCs'" Professor Ilya Strebulaev of Stanford Graduate School of Business, using data from 230,000 investments, reveals that the top 5% of venture capital firms generate approximately 90% of the industry's profits. For founders, choosing the wrong investor can mean a tenfold difference in returns. The article introduces the data-driven 2026 Strebulaev-Jackson VC Ranking, an alternative to lists like Forbes Midas. It scores nearly 13,000 investors across 30 years based on six factors: dilution-adjusted ownership, net profit (investment cost subtracted), value-add (e.g., lead investor/board role), and attribution of credit between firms and individual partners. Key findings from the top 100 firms: - Sequoia Capital leads with 10,158 points. - Performance follows a power law: the #1 firm scores ~41x more than #100. - Unicorn count is a poor performance proxy (e.g., SV Angel with 139 unicorns ranks #31). - 21 of the top 100 were founded in 2015 or later. - 23 firms have their top-scoring investment in frontier AI/AI infrastructure. - Geography remains concentrated: 62 in California, 19 in New York. The author cautions against using the rank order blindly. Founders must prioritize: 1. Strategic fit (stage, sector, involvement model) over raw rank. 2. Due diligence on the specific partner, not just the firm brand. 3. Recognizing that VC partnerships are long-term commitments akin to marriages. The ranking is a tool to identify the elite 5%, but the final choice requires deeper research into partner dynamics and how investors behave during a company's difficult times.

marsbit08/25 07:06

Stanford Business School Internal Guide: Look Beyond the Reputation, How to Accurately Identify the 5% of Truly 'Top VCs'

marsbit08/25 07:06

Strategy Repays Its Costs and Starts Hoarding US Dollar Cash Again

The article details a strategic shift by MicroStrategy, the world's largest corporate Bitcoin holder, as it pivots from aggressive Bitcoin accumulation to building substantial cash reserves. Following a 13% weekly Bitcoin rally above $78,000—which brought its massive 840,447 BTC holding back above its average cost basis of $75,385 per coin—MicroStrategy took no new Bitcoin purchases. Instead, the company raised approximately $2 billion by selling shares. It allocated these funds into two new US dollar pools: a restricted "USD Reserve" for debt/股息 payments (now holding $5.1B) and a flexible "USD Cash" pool ($1.59B) for potential market opportunities. This move marks a departure from CEO Michael Saylor's long-held narrative that cash is "melting ice." The primary driver is the need to meet fixed financial obligations, like the 12% dividend on its STRATeGY Preferred Shares (STRC), which have traded below their $100 face value. To support STRC's price, MicroStrategy has sold Bitcoin and used equity proceeds to repurchase these shares under a $1 billion buyback program. Analysts note this shift addresses immediate liquidity needs but highlights challenges in MicroStrategy's famed "flywheel" model. The model, which relied on issuing premium-priced stock to buy more Bitcoin, is impaired as the company's stock premium has evaporated. While the new cash reserves provide flexibility and time, they do not eliminate the underlying financial obligations. The article frames this囤积 of the once-scorned "melting ice" as a pragmatic adaptation to market pressures and a bid for operational flexibility amidst Bitcoin's volatility and regulatory scrutiny.

marsbit08/25 01:50

Strategy Repays Its Costs and Starts Hoarding US Dollar Cash Again

marsbit08/25 01:50

活动图片