Written by: Yang Chen, Wall Street News Agency
The upcoming wave of buying for SpaceX does not stem from improved fundamentals, but is a mechanical result triggered by a rarely noticed index compilation rule. The unlocking of restricted shares that drives the weight increase is precisely the largest source of potential selling pressure in the coming months.
The quarterly rebalancing of the Nasdaq 100 index, effective September 21, is expected to raise SpaceX's weighting from 1.25% to approximately 1.51%. According to calculations by a team of strategists at JPMorgan led by Min Moon, this adjustment will trigger about $12.4 billion in net passive buying.
The direct driver for the weight jump is the increase in free float proportion from less than 10% post-IPO to nearly 30%—after over 1 billion restricted shares are unlocked, index rules automatically amplify the inclusion weight of this giant with a market cap exceeding $2 trillion.
But the unlocking is not over: before the end of October, over 1 billion shares will be unlocked, and after the Q3 earnings report in mid-November, another approximately 1.3 billion restricted shares will become tradable, totaling over 2.3 billion shares. The interplay between short-term mechanical buying and medium-term supply shocks is becoming the core variable for SpaceX's pricing in Q4.
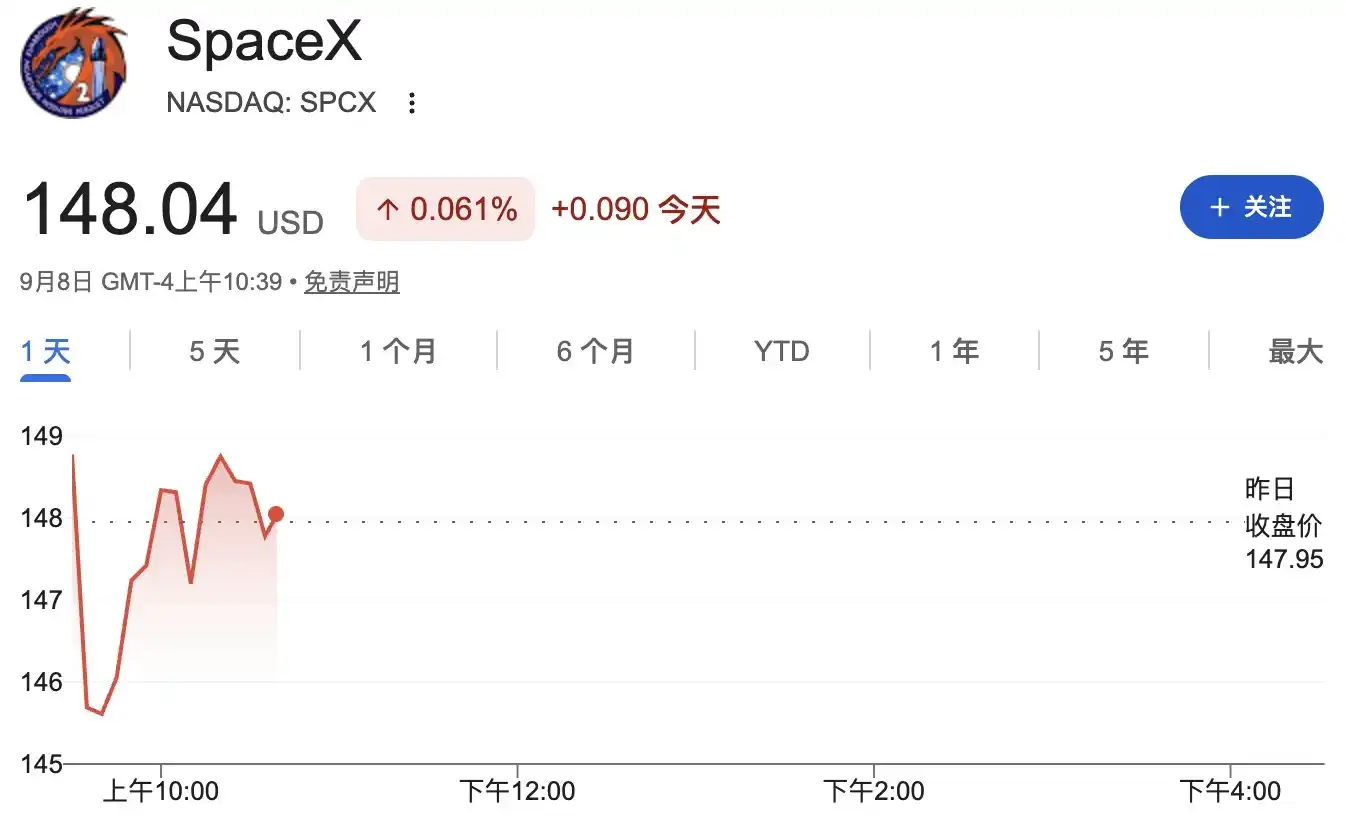
As of the time of writing, SpaceX rose 0.06% on Tuesday, with its stock price near a two-month high.
Weight Doubling Mechanism: Chain Reaction of Free Float Proportion Jump
The weight calculation for the Nasdaq 100 is based on the lower of total shares outstanding and three times the number of free-float shares. Shares with a low free float proportion have their market capitalization significantly discounted when included in the calculation—free-float shares exclude insider holdings and shares subject to lock-up restrictions.
This was previously the case for SpaceX. Due to lock-up restrictions, its free float proportion was below 10%. Despite a market cap over $2 trillion, ranking sixth in the index, its weight was only 1.25%, placing it 19th. As over 1 billion restricted shares are unlocked, raising the free float proportion to nearly 30%, it directly triggered a recalculation of the weight.
According to calculations by the team of JPMorgan strategist Min Moon, after the weight increases to about 1.51%, it will generate approximately $12.4 billion in net passive buying demand.
According to Nasdaq statistics, as of Q2 end, about $1.7 trillion in assets tracked the Nasdaq 100 index, including the well-known Invesco QQQ ETF (ticker: QQQ). The rebalancing plan will be announced after the market close on Friday. As more shares are unlocked over the next year and the free float proportion continues to rise, SpaceX's weight may increase further.
2.3 Billion Shares Unlock: Supply Flood Peak Behind Short-Term Buying
The jump in free float proportion is essentially the result of restricted share unlocking, and an even larger unlocking volume lies ahead.
According to the schedule, over 1 billion restricted shares will be unlocked before the end of October; after the Q3 earnings release in mid-November, another approximately 1.3 billion shares will become tradable. Combined, these two batches total over 2.3 billion shares.
The first unlocking in August (coinciding with SpaceX's first earnings report) raised concerns about large-scale selling, but insiders largely held their shares, and the selling pressure did not materialize.
Ed O'Gorman, CEO of River Wealth Advisors, believes the truly critical event will come when the November earnings report triggers the unlock, bringing a substantial number of shares to the market.
Steve Sosnick, Chief Strategist at Interactive Brokers, stated that newly unlocked shares will either be sold to potential passive buyers, or the stock price will rise due to increased demand from index funds, with products like QQQ expected to bring additional demand.
Bull-Bear Divergence: Can Passive Buying Hedge Unlocking Selling Pressure?
In the short term, about $15.5 billion in passive buying is relatively certain. In the medium term, the scale and pace of unlocking selling pressure depend on insiders' willingness to sell, creating the largest expectation gap currently.
Over the past four weeks, SpaceX's stock price has consolidated sideways in the $133 to $150 range, fluctuating around the $135 IPO price, lacking fundamental catalysts. Ed O'Gorman pointed out that the market price will, to some extent, be driven by forced buying, and it will take some time to truly gauge the market's view on this stock.
Similar rules are not unique to Nasdaq. S&P Dow Jones Indices also uses free-float adjusted market cap for weight calculation; two years ago, after Berkshire Hathaway reduced its Apple holdings, Piper Sandler estimated it would trigger about $40 billion in passive fund buying.
SpaceX was included in the Russell 1000 index this June, but the S&P 500 requires at least 12 months of trading history, meaning it won't be eligible for inclusion until at least mid-2027, leaving room for further incremental passive buying.
The unlocking triggered by the Q3 earnings report in mid-November will be the key node to test SpaceX's true market depth and determine the short-term outcome of the bull-bear tussle.