Author: Aleks Larsen, General Partner at Blockchain Capital
Compilation: Chopper, Foresight News
The financial industry has long faced high costs associated with asset packaging. Each type of asset exists within its own separate carrier and operates within its own system: a mortgage is a collection of countless contracts, PDF files, databases, and service agreements; a private fund share corresponds to a subscription agreement and a line entry in a transfer agent's ledger; stock holdings are dispersed across multiple chains of records held by brokerages, custodians, and depositories. The examples are countless.
When assets transfer between institutions, they often need to be unpacked, verified, reconciled, and then repackaged to fit the receiving system. The root cause of this significant redundant effort is that different institutions maintain their own separate data records for the same underlying asset or income right.
Globally, this market fragmentation imposes enormous hidden social costs. While global balance sheets hold vast quantities of assets, the vast majority require custom operational costs to freely transfer across institutions. This friction hinders capital from flowing to emerging companies, infrastructure projects, residential real estate, and other productive areas.
Tokenization addresses this pain point at its root. Tokens provide a standardized, machine-readable interface for assets or financial claims. Once an asset can be recognized and invoked on a shared network, exchanges, lending platforms, custodians, asset servicers, and applications can directly connect to the asset without repeatedly building the entire underlying financial infrastructure from scratch. Ultimately, capital markets will operate on a common programmable infrastructure, drastically reducing friction costs associated with asset transfer, settlement, and activation.
To understand the logic of how tokenization reshapes the world, the shipping container is the most apt analogy.
How Shipping Containers Gave Rise to Modern Global Supply Chains
Prior to the 1960s, goods transport took myriad forms: coffee in sacks, machinery in wooden crates, cotton in bales, crude oil in barrels. Each type of cargo had its own loading and unloading requirements, with all goods handled manually by dockworkers. Skilled longshoremen possessed specialized techniques: tightly packing, balancing weight, securing cargo to prevent damage or shifting during voyages. The fundamental reason for this cumbersome process was the lack of a uniform loading container in global trade. The direct consequence was that ships spent more time idling in ports than sailing at sea. General cargo was repeatedly transferred and counted between ships, trucks, trains, and warehouses, with frequent issues of damage, breakage, loss, and theft.
In 1956, North Carolina trucking entrepreneur Malcolm McLean converted a tanker, the 'Ideal-X', and sailed from Newark to Houston loaded with standardized containers. Upon arrival, trucks could directly take the containers away without any unpacking. The Ideal-X's cost per ton loaded was far lower than traditional break-bulk methods, marking the birth of the modern shipping container.
Over the next two decades, containers achieved ISO standardization, and the entire supply chain was restructured around the box, with each segment achieving specialization. Ships were designed with vertical cellular holds to safely stack containers; cranes were adapted into high-speed lifting equipment fitting standardized boxes; truck chassis and railcars were produced with uniform dimensions and locking structures; ports transformed into massive intermodal hubs transferring standardized containers between transport modes.
The primary impact was a dramatic reduction in transportation costs (both time and money). Shipping times from Australia to Europe plummeted, and vessel capacity quadrupled. Trade began to shift towards manufactured goods and intermediate products, with firms dispersing production stages across countries; new logistics providers emerged to coordinate increasingly complex global networks, and supply chains scaled rapidly.
Secondly, economic activity grew substantially. The World Bank estimates that in the fifteen years after trading partners both adopted container shipping, bilateral trade volumes among developed countries surged. Relying on containers and the accompanying infrastructure rebuild, global supply chains achieved massive scale, ushering in a period of rapid global economic growth.
Tokens are the Shipping Containers of Finance
Tokens are the containers carrying financial claims. What they hold is not physical goods, but various economic rights and state: ownership, transfer permissions, cash flow distribution rules, access restrictions, and interaction logic callable by software programs.
Once an asset possesses a standardized, machine-readable interface, exchanges can list it for trading, lending markets can use it as loan collateral, custodians can safeguard it, and wallets can automatically distribute cash flows. Various software applications can recognize the asset and execute its trading rules without needing to individually integrate with each partner institution. This is the essential difference between tokenization and merely digitizing documents or adding database entries: all participants in the market can treat the token as the unified operational interface for the asset. As this effect compounds across the ecosystem, the energy it unleashes will be immense.
Stablecoins are the most immediate case study demonstrating tokenization's potential. Cross-border wire transfers moving dollars via traditional banking systems can take days, whereas stablecoins can transfer value globally in seconds at near-zero cost. The foundation for this is the recognition of this token interface by a vast array of global exchanges, custodians, on/off-ramp services, payment processors, and wallets. They are the new financial ports, cranes, trucks, trains, and freighters, relying on tokens to move value. This infrastructure was initially built for Bitcoin and Ethereum. Once the system formed, stablecoins and other tokens could reuse this network. The success of stablecoins attracts more users, liquidity, applications, and infrastructure, and subsequently issued tokens benefit from the growing network effects.
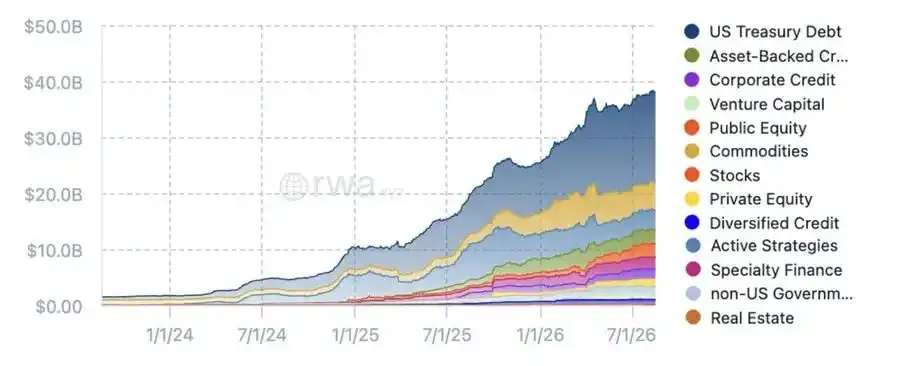
Source: rwa.xyz
The results speak for themselves: a massive volume of stablecoins circulates, facilitating enormous transaction flows with a velocity far exceeding traditional M1/M2 money. Cross-border remittance costs have fallen by an order of magnitude, granting vast global populations stable access to a dollar payment system. Stablecoins have already validated the value of this dollar network, achieving a qualitative leap in cost, speed, and reach, multiplying the scale of economic activity enabled per dollar.
Today, this high-liquidity dollar pool is attracting more assets to connect to stablecoin deposit channels. The current scale of RWA tokenized assets has grown approximately 10x compared to two years ago, and the growth rate is accelerating. Underlyings include US Treasuries, money market funds, commodities, private credit, equities, and various fund shares, covering a diverse range of global markets.
Capital Markets Will Be Rebuilt Around Tokens
Just as global supply chains were restructured around containers, global capital markets will be rebuilt with tokens at their core in the future. The DeFi sector already shows the blueprint. A project in our portfolio, Aave V4, allows eligible token holders to pledge assets as collateral to access floating-rate credit from a lender market. The protocol embeds the full set of trading rules, with the asset itself dictating access. This completely inverts the traditional lending market structure. Today, if an individual or company wants to borrow against assets, they first approach a financial institution. The institution controls access, assesses the borrower according to its own risk processes, and offers financial products through its own channels. Financial services are tied to institutional relationships.
In the Aave ecosystem, the sole criterion for access judgment is the asset itself. Smart contracts recognize the token, execute transparent rules, and directly connect to capital markets. The binding relationship between asset holders and financial services is completely reversed: financial capability attaches to the asset itself, not the relationship between the user and an institution.
In other words, tokens make assets executable like software. Once an asset is on a public chain and recognized by the network, various applications can compete to layer value-added services onto it: exchanges provide trading liquidity, lending markets provide borrowing capacity, wallets automate cash flow distribution, etc. The asset issuer only needs to bring the asset on-chain once, without building separate systems for each application scenario.
This will fundamentally change the business models of financial institutions. Currently, banks, brokerages, and asset managers bundle custody, underwriting, liquidity services, asset management, and compliance into closed product systems for distribution. Crypto networks, however, promote the unbundling and independent specialization of these functions. One institution might handle credit origination and servicing, while others provide funding, risk pricing, trading, insurance, or ancillary application services. Assets, with their unified interface, flow freely between modular services without needing to be re-entered and built within each provider's system.
The locus of competitive advantage shifts from large institutions to open networks. In traditional finance, large institutions can offer more products because they can bear the fixed infrastructure costs for each asset class and customer segment. In public blockchain crypto networks, much of the underlying infrastructure is a shared resource. New service providers can connect to assets, capital, and users without rebuilding ledgers, exchanges, custody, and settlement systems, dramatically lowering the barriers to entry and operation.
The network effects of stablecoins have entered a virtuous cycle. Capital markets will gradually transform into open networks, with a multitude of specialized financial services operating around tokenized assets. In this new paradigm, institutions compete on the quality of capital, underwriting ability, risk management, asset management, and distribution prowess—not on exclusive ownership of databases or monopolizing the sole channel for users to access markets.
The Global Balance Sheet Will Ultimately Be Fully On-Chain
The most important outcome of this transformation will be the creation of a borderless, global capital market.
Today, capital markets are bottlenecked by institutions. The vast majority of individuals and businesses cannot directly access capital markets and are limited to the finite product menus institutions are willing to offer. Institutions autonomously decide which customers to serve, which geographies to cover, which asset classes to deal in, and what transaction limits to set.
Investors face the inverse constraint: they cannot freely invest in all global assets, only those that institutions have underwritten, packaged, and connected to distribution.
Ultimately, the vast majority of the world's economic value is locked outside existing capital markets. Small receivables, local infrastructure projects, private businesses, emerging market credit, non-standard cash flows—even if economically valuable—remain unfinanced due to the high operational costs of traditional finance for assets that are too fragmented, geographically dispersed, or small. Investment opportunities exist, and capital supply is ample, but there is no connecting network between them.
Tokenization changes this by providing assets with a standard interface, making them discoverable globally. As the financial system is rebuilt on this new interface, participation costs for everyone will drop dramatically. Finance becomes a software-native capability, allowing applications to specialize in niche asset classes and regional markets, reaching areas traditional finance cannot. Business processes previously unable to access sophisticated financial services can easily embed payments, working capital financing, collateral management, and treasury functions. Vast quantities of idle 'sleeping assets' can connect to the on-chain capital market. Objectively, tokenization cannot magically make worthless assets financeable, but many quality assets currently excluded from the system have the potential to participate in market trading in the future.
Artificial intelligence will further amplify this transformation by taking over various operational tasks. AI agents can assess assets, price risk, allocate capital, manage collateral, and execute settlement in a globally machine-readable market, continuously driving down the cost of financial services. AI combined with crypto payment rails will transform customized, intermittent trading markets into 24/7, global, automated markets, thereby creating more opportunities worldwide and breaking down institutional barriers to capital.
Capital allocation is humanity's core tool for directing society. It determines which companies expand, which technologies are deployed at scale, where homes and factories are built, and shapes regional economic development. For assets that are too small, local, customized, or operationally expensive for the traditional financial system, they become commercially viable for underwriting when the costs of connection, financing, and management plummet.
This mirrors the deeper change brought by containers. Containers made new models of trade and production economically feasible. Goods could be produced where costs were lowest, assembled elsewhere, and sold globally, as the integrated cost of coordinating the supply chain fell dramatically.
Tokens will replicate this same transformation for capital. Over the coming decades, the global balance sheet will evolve from a collection of isolated ledgers into an open market traversable by software, where capital flows freely based on the asset's inherent value, no longer constrained by who controls the financial pipes. Stablecoins have already shown us the way: this system has the potential to drive a massive expansion of global capital markets into previously unreachable domains.