Original Author: Zhao Ying
Original Source: Wall Street Insights
Michael Hartnett, Chief Investment Strategist at Bank of America Securities, warns that soaring global bond yields to two-decade highs are becoming the biggest threat to the AI capital expenditure boom, and the upcoming U.S. midterm elections could be the trigger that ignites the market.
In his latest "Flow Show" weekly report, Hartnett points out that if Democrats sweep both houses of Congress in the midterms, U.S. stocks would face a decline of over 10%, the dollar would weaken, bond yields would fall, and the AI bubble would be at risk of bursting. He characterizes a "Democratic sweep" as one of the biggest tail risks for the current market, a risk for which investors have almost priced in nothing.
Polymarket data shows the probability of Democrats sweeping both houses has risen to 50%, far higher than the 10% probability of a Republican sweep. President Trump's approval rating currently hovers only in the 35% to 40% range, significantly below the historical average of 53% two months before midterm elections, a political fundamental that reinforces the logic of Hartnett's warning.
The Bond Market Sounds the Alarm First
Hartnett believes the most noteworthy market event last week was not the stronger-than-expected jobs data, but the comprehensive rout in the global bond market.
The yield on the 10-year U.S. Treasury rose to 4.81%, approaching levels seen during the 2008 financial crisis; the 30-year U.S. Treasury yield rose to 5.31%, its highest since 2007. Meanwhile, Japan's 10-year government bond yield broke through 3.0% for the first time since 1996; the 30-year JGB yield reached 4.2%, roughly four times the Bank of Japan's policy rate. In Europe, Germany's 10-year Bund yield rose to 3.38%, a new high since 2011; the spread between French and German yields widened to 88 basis points, and the Italy-Germany spread reached 84 basis points, both touching levels last seen during the 2012 European debt crisis. The Bloomberg Global Aggregate Bond Index yield has risen to its highest since 2007, just 1 percentage point away from its highest level this century.
Hartnett distills this phenomenon into a core judgment: "Bonds dominate the bubble." He believes long-end yields—not stock narratives—are the true anchor for the current AI trade, and points out that until global 30-year yields fall below 5%, builders and investors in AI infrastructure will continue to underperform the adopters of AI technology.
Midterm Elections: An Underpriced Market Variable
Hartnett admits that the midterm elections are not a "regime change" election like Thatcher/Reagan in 1980 or Brexit/Trump in 2016, and will not fundamentally alter the upward trajectory of U.S. government spending. However, he emphasizes that the structural differences in election outcomes have a non-negligible impact on asset prices.
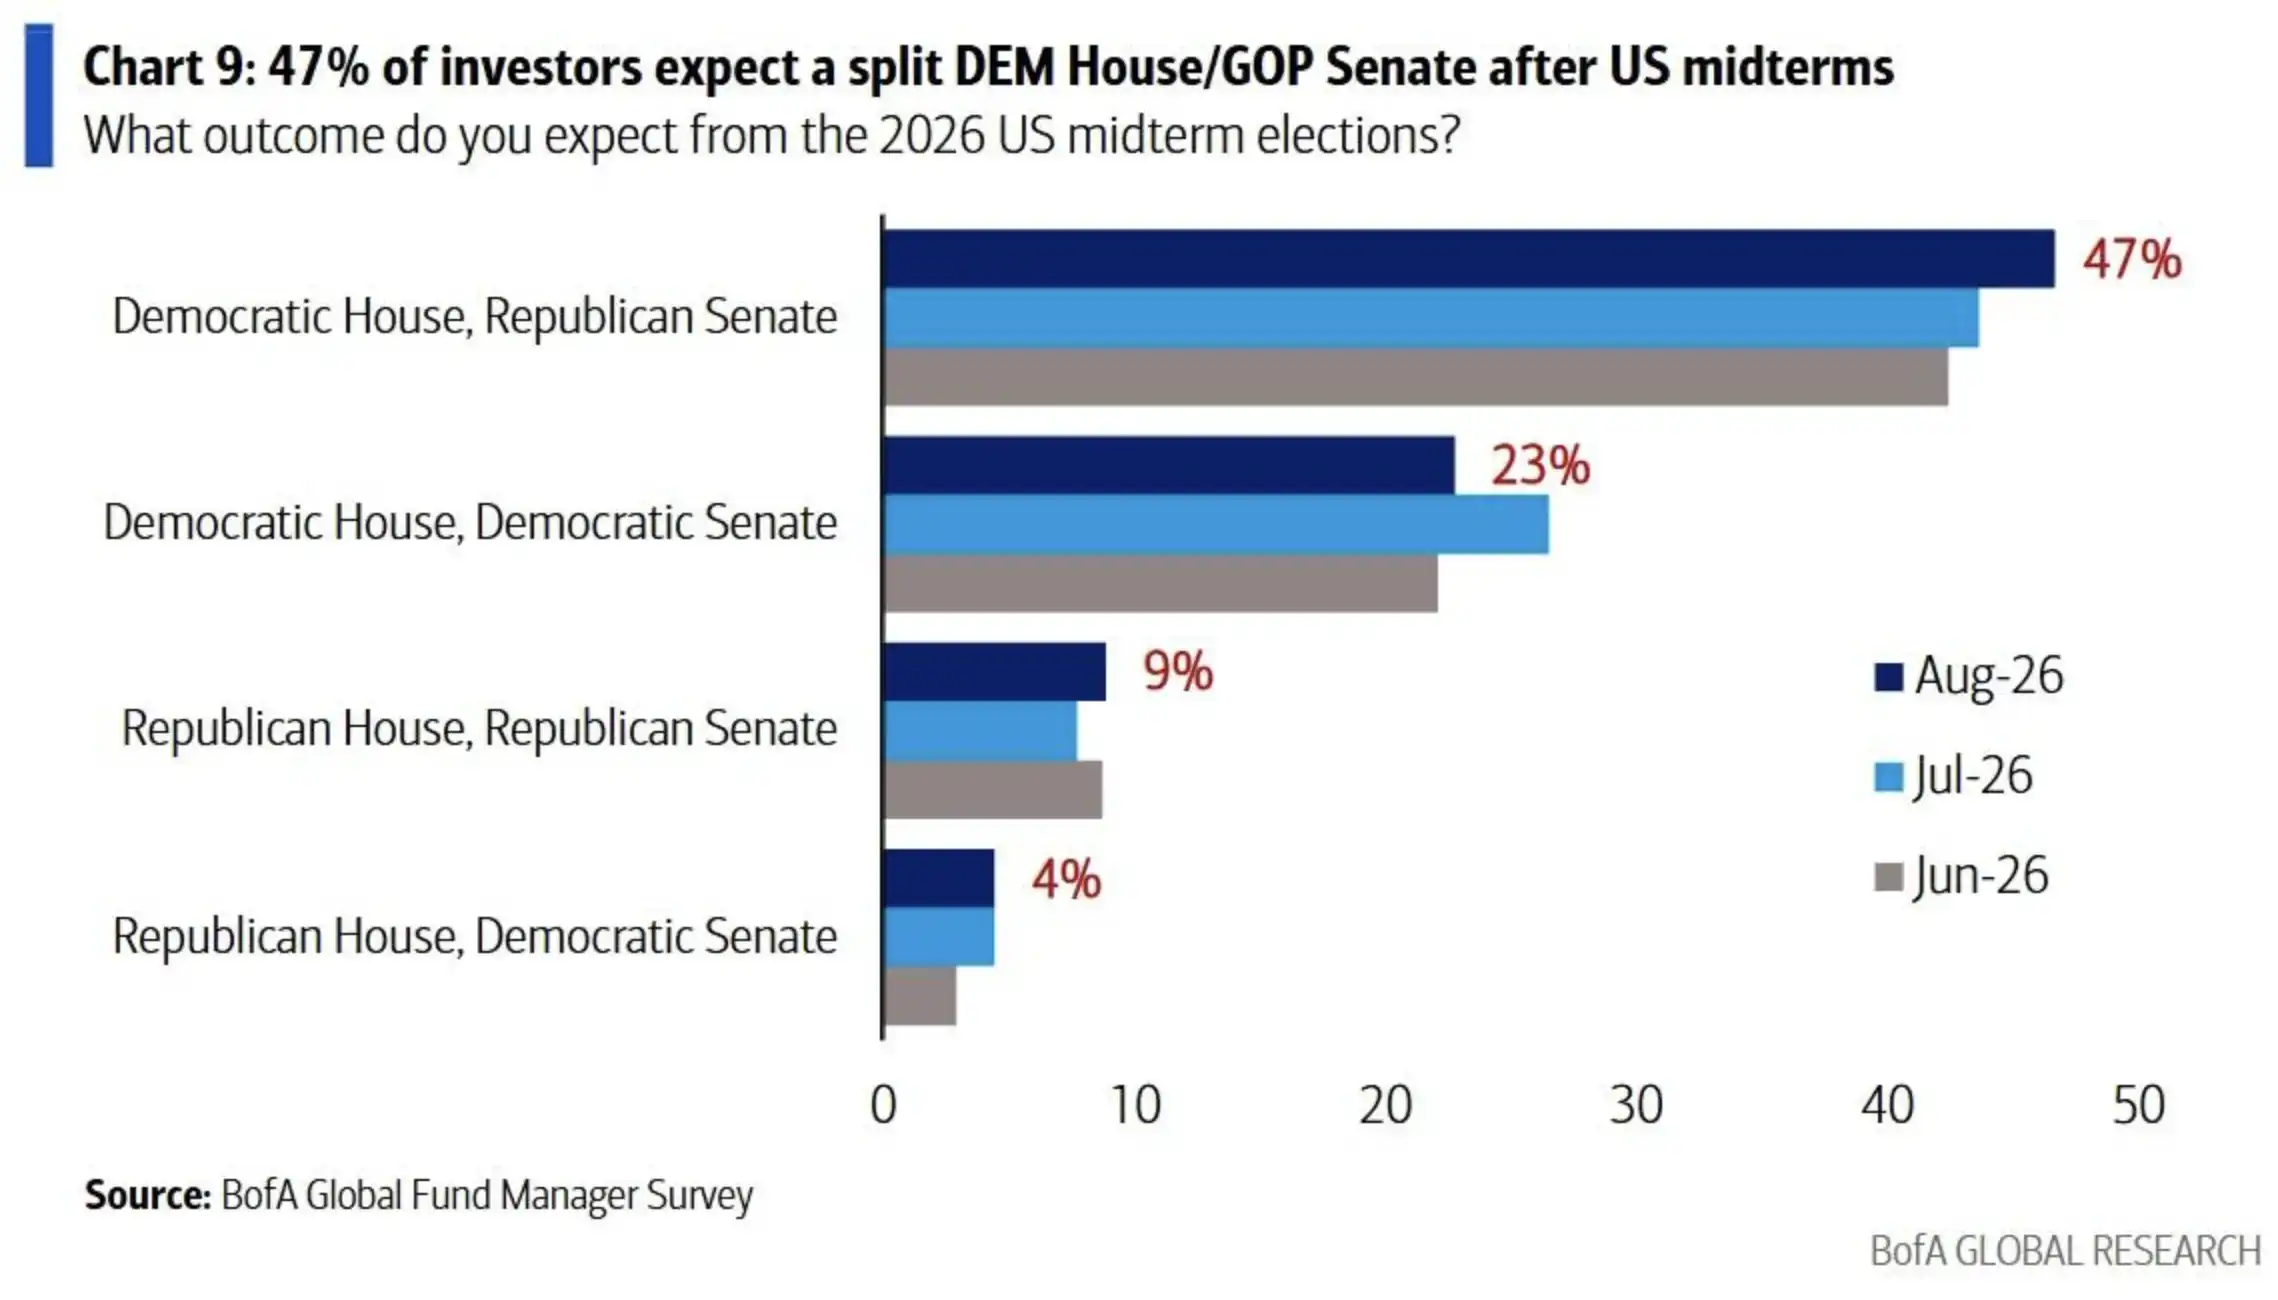
Bank of America's August Fund Manager Survey shows 47% of respondents expect the outcome to be "Republican-controlled Senate, Democrat-controlled House," 23% expect a Democratic sweep, and only 9% expect Republicans to maintain control of both houses. Currently, Republicans lead in the Senate 53 to 47 and in the House 218 to 212.
Regarding Senate races, for Democrats to achieve a sweep, they would need to win at least four of six vulnerable Republican seats in North Carolina (flip probability 92%), Maine (69%), Alaska (64%), Ohio (55%), Texas (51%), and Iowa (37%), while also holding onto their own vulnerable seats like Georgia (94%), New Hampshire (84%), and Michigan (65%). Hartnett singles out Ohio, Texas, Iowa, and Michigan as key battleground states for investors to closely track.
Notably, Wall Street has turned its gaze to the Texas gubernatorial race—the contest between incumbent Republican Governor Abbott (polling at 49%) and Democratic challenger Hinojosa (45%) is seen as an important bellwether for the policy direction of AI data center expansion. Abbott was recently forced to announce a moratorium on data center construction to curb his declining poll numbers.
The Market Impact Path of a Democratic Sweep
Hartnett provides a clear transmission logic for the market impact under a Democratic sweep scenario.
He believes a shift in the electoral landscape from "populist capitalism" to "populist socialism" would mean a reversal from tax cuts and deregulation to tax hikes and increased regulation, posing a negative shock to corporate profits. This would be accompanied by policy orientations aimed at lowering inflation, improving healthcare accessibility, and alleviating K-shaped wealth inequality, directly impacting the AI capital expenditure boom and the "too big to fail" Wall Street ecosystem. Additionally, a loss of political capital for Trump would weaken his ability to execute on priority issues like AI, resource monopolies, and diplomatic pressure.
Synthesizing the above judgments, Hartnett's asset allocation advice for a Democratic sweep scenario is: short financial stocks and the U.S. dollar as the optimal hedge; the stock market would fall over 10%, the dollar would weaken, and bond yields would decline; international equities would relatively outperform, with Europe better than Asia.
Conversely, if Republicans unexpectedly retain both houses, it would mean a broad-based risk-on rally, a green light for the AI bubble, and a rekindling of the "American exceptionalism" dollar narrative. The most probable outcome of a "Republican Senate, Democratic House" would correspond to a moderate risk appetite—"gridlock is Goldilocks."
Strategic Allocation: Long Commodities & Gold, Beware of Crowded AI Trades
Within this macro framework, Hartnett maintains his core cross-cycle allocation advice: long commodities and gold as hedges against inflation and geopolitical risk. He notes that governments' "whatever it takes" fiscal interventions are suppressing long-end yields and supporting a boom in nominal GDP. In this context, the strategic logic that "any asset is better than bonds" still holds.
Regarding the AI trade, Hartnett's warning is more direct. He points out that the free cash flow of hyperscale cloud providers has turned negative under the pressure of capital expenditure commitments, and the AI bubble "could burst at any time." He proposes a post-bubble operational framework of "long humiliation, short hubris," suggesting a pivot to long-duration bonds and defensive sectors, including consumer staples, mining/materials, and healthcare, while avoiding crowded AI infrastructure-related plays.
From a long-cycle perspective, Hartnett also notes a contrarian signal: U.S. stocks' 10-year rolling return is 15%, commodities' is 11%, while U.S. Treasuries' is -2%, the worst performance in nearly a century. Historical data shows that when long-term bond returns turn negative, it has often been a good buying signal for stocks (1939, 1974, 2009) and commodities (1933, 2018), providing historical grounds for his tactical bullishness on Q4 bonds.