Clearing Giant with $114 Trillion in Assets Tokenizes Securities, Has Crypto Won?

Foresight News2026-07-16 tarihinde yayınlandı2026-07-16 tarihinde güncellendi

Özet

On July 15, the US securities settlement giant DTCC conducted its largest production-level test for tokenization, marking a significant shift from previous workarounds. The test involved approximately 40 institutions, including major players like JPMorgan, Citadel Securities, and State Street, as well as crypto-native firms such as Circle, Chainlink, and Ondo Finance. For the first time, DTCC, which custodies over $114 trillion in securities, directly created on-chain "digital twin" tokens for stocks, ETFs, and U.S. Treasuries held in its depository (DTC). These tokens share the same CUSIP identifiers and legal rights as the underlying assets. Key transactions included JPMorgan tokenizing an Invesco QQQ ETF to post as collateral at CME Group and DriveWealth settling a tokenized equity trade with Vanguard. The test paves the way for the official launch of the DTCC Tokenization Service in October. This move centralizes the issuance authority for tokenized traditional securities with the core market infrastructure itself. While projects like Ondo Finance (which participated in the test) will continue providing distribution and DeFi integration, their underlying collateral can now be DTCC-issued tokens, enhancing transparency and credit backing. The initiative aims to unlock liquidity in collateral by enabling 24/7 settlement and transfer across venues, a direct efficiency gain for DTCC. The test culminates years of DTCC's blockchain exploration, utilizing two key infrastructu...


Written by: Sanqing, Foresight News


On July 15, US securities clearing giant DTCC (The Depository Trust & Clearing Corporation) converted stocks, ETFs, and US Treasury bonds held in custody under The Depository Trust Company (DTC) name into on-chain tokens for the first time in a real transaction, completing a series of operations including treasury repo, collateral pledging, securities lending, and stock settlement in one day. About 40 institutions participated. DTCC called this its largest tokenization production test to date, paving the way for the DTCC Tokenization Service scheduled to launch in October.
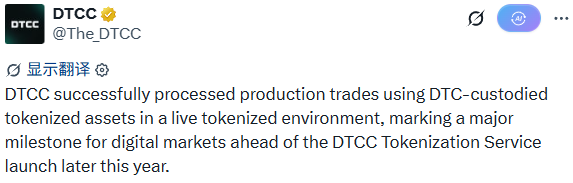


Among them, JPMorgan Chase led the way by tokenizing the Invesco QQQ Trust and posting the tokenized assets as CCP margin to CME Group; State Street's SPDR S&P 500 ETF (SPY) was tokenized; Citadel Securities and DriveWealth completed equity token conversions; DriveWealth and Vanguard completed the DVD settlement of tokenized equities; Societe Generale completed treasury bond token conversion; Societe Generale and Citadel Securities jointly completed collateral pledge settlement; Marex executed real-time collateral transfers, repos, and equity buy/sell transactions involving tokenized US Treasuries, stocks, and ETFs.


DTCC is the clearing and settlement backbone of the US securities market, operating for over 50 years, jointly owned and governed by the industry. Its business is handled by three core subsidiaries: DTC (The Depository Trust Company) is responsible for the registration, custody, and settlement of securities; NSCC (National Securities Clearing Corporation) acts as the central counterparty for transactions like stocks, providing trade guarantees and netting; FICC (Fixed Income Clearing Corporation) handles the clearing of US Treasury bonds and mortgage-backed securities. Nearly every US securities transaction ultimately passes through this system. In 2025, DTCC subsidiaries processed approximately 4.7 quadrillion dollars in securities transactions; DTC alone holds securities valued at over $114 trillion, originating from more than 150 countries and regions.


Previously Bypassing Wall Street, This Time Wall Street Opens the Door Itself


To understand the significance of this day, one must first see how previous tokenized US stocks came to be.


Real stocks are held in accounts at DTC, beyond the reach of the on-chain world. Hence, various substitutes emerged: derivative contracts, which only speculate on price movements; SPVs (Special Purpose Vehicles), where the SPV buys the stock, and the token represents a claim against this shell company; licensed brokers holding real stocks 1:1 in custody, with the token being a beneficial interest certificate for these stocks, akin to an on-chain depositary receipt...


These approaches differ in their proximity to the "real stock," but share a common thread: they all circumvent the security itself. The real stock is locked away at DTC, inaccessible from the outside, so one can only create a replica outside the system.


This time, DTCC proactively opened the door, issuing an on-chain digital identity itself. It minted a one-to-one corresponding "digital twin" token on-chain for securities already held in custody at DTC, sharing the same CUSIP and code as the underlying security. DTCC emphasized these tokens enjoy "the exact same investor protections, rights, and ownership" as the traditional securities.

Source:DTCC Official Website


Among the roughly 40 institutions participating, besides well-known traditional players, there were also many crypto-native companies.


Circle used its stablecoin for cash-side settlement, and its own stock CRCL was also among the assets tokenized this time; Chainlink handled oracle and cross-chain services; Fireblocks, BitGo, Blockdaemon, and Kaleido provided custody, wallet, and node services; Talos provided institutional trading technology; Digital Asset behind the Canton chain and LF Decentralized Trust behind the Besu chain were naturally present as well.


But those directly building businesses around tokenized securities are Ondo and Prometheum. Ondo issues tokenized stocks aimed at the on-chain and DeFi world, while Prometheum is a licensed digital asset securities firm, integrating brokerage, trading platform, custody, and clearing, specifically designed to legally hold and trade tokenized securities.


Four Years of Preparation, Two Chains in Place


DTCC has a history with blockchain; this move was not impromptu.


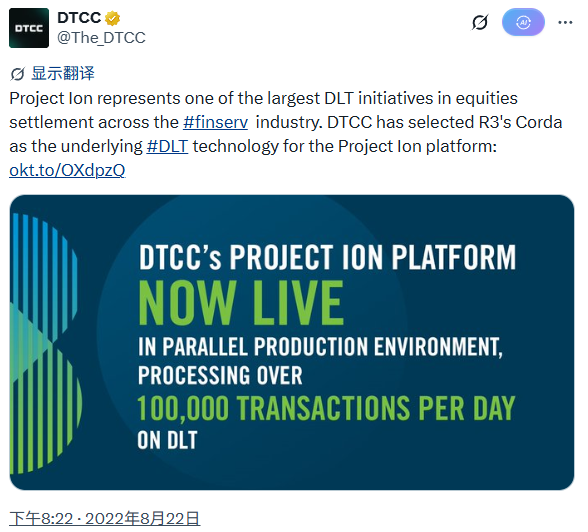
In 2022, it launched Project Ion based on R3 Corda, a stock settlement platform running in parallel with its legacy system, handling over 100,000 transactions daily at its peak. This was its first time putting distributed ledger technology into live settlement.


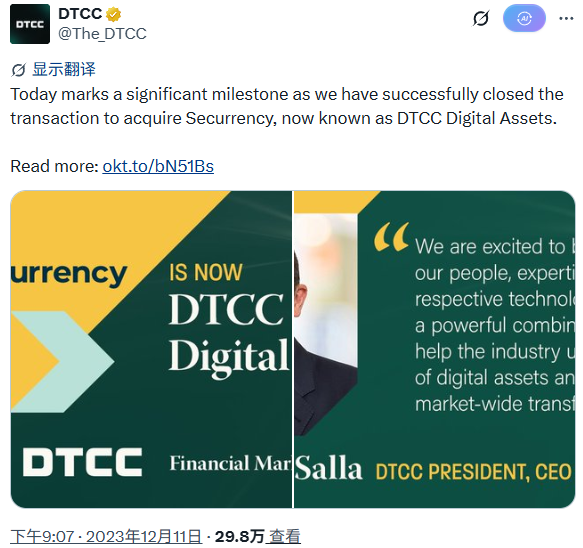
In October 2023, it acquired blockchain firm Securrency, forming the DTCC Digital Assets division led by former State Street digital asset head Nadine Chakar. Securrency's technology was later integrated into its multi-chain tool, ComposerX.


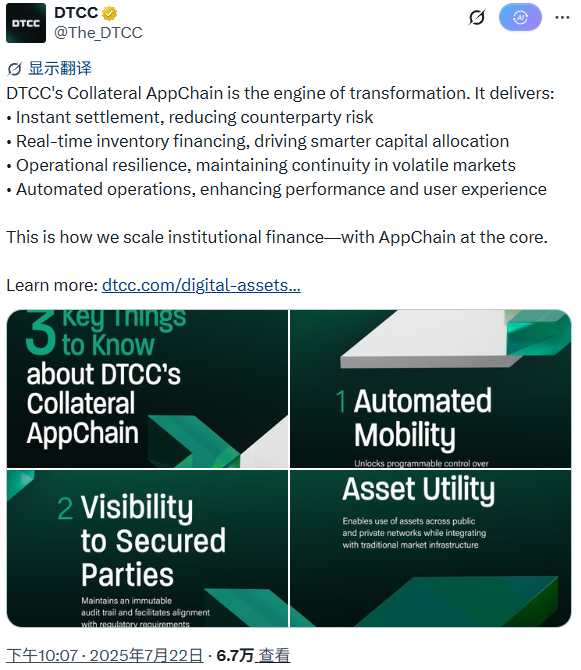
Starting in 2024, DTCC shifted its focus to Hyperledger Besu, launching the blockchain platform Digital Launchpad and the collateral management platform Collateral AppChain.


Besu is its self-built private chain. Its predecessor was Pantheon, developed by ConsenSys in 2018. After being donated to Hyperledger in 2019, it was renamed. Its advantage lies in strict permission controls while maintaining compatibility with Ethereum development tools. DTCC's internal bookkeeping, settlement, and collateral management run on this chain, inaccessible from the outside.


In 2025, another chain entered the picture. DTCC participated in a $135 million funding round for Digital Asset, the developer of the Canton network. Other investors in the same round included Goldman Sachs, BNP Paribas, Circle, Citadel, and DRW. At the end of the year, DTC received a no-action letter from the SEC, allowing it to legally operate tokenization services for three years. It subsequently migrated Treasury bonds onto Canton and, together with Euroclear, became co-chairs of the Canton Foundation.
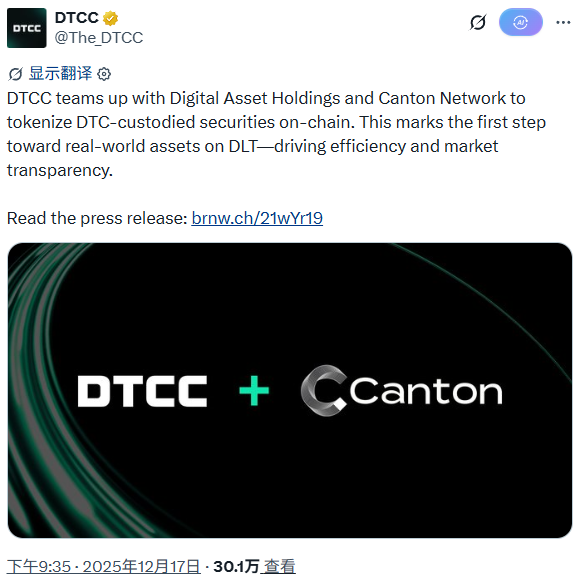


Canton is a public network built by Digital Asset using the Daml language but features "sub-transaction privacy," which typical public chains lack: in a single transaction, each party only sees the parts relevant to them. For example, in a Treasury repo transaction, the bank handling the cash side cannot see the transfer of the underlying securities. Previously, Goldman Sachs' GS DAP, HSBC's Orion, and Broadridge's DLR platform handling trillions in monthly repo volume were built on it, with nearly 400 institutions already participating.


One chain internally maintains control, the other externally connects to liquidity. By July this year, the industry working group behind DTCC had grown from a few dozen to over a hundred members. Capital, regulation, allies, technology... everything was prepared over four years, showing this is not a whimsical tech demo, but DTCC making a grand entrance on its own terms and at its own pace.


Issuance Rights Centralized, Others Fall Back to Access Points


First, consider what DTCC itself wants. It's not seeking proof-of-concept; it wants liquidity for collateral.


That day, JPMorgan tokenized Invesco's QQQ ETF and directly posted it as margin with CME, marking the first time a central counterparty accepted this type of on-chain token generated from traditional securities.


The significance lies in the fact that an asset originally confined to a specific account can now be mobilized 24/7 across venues, unlocking capital previously frozen by settlement delays. This also explains why clearing giant DTCC is driving this change. The tangible return for it is a substantial improvement in its own capital efficiency, leading to increased revenue.


Those who should truly reconsider their positioning are likely the projects tokenizing US stocks. Their core task in recent years has been proving to users that "tokens are indeed backed by real stocks." Now that the depository institution itself issues standardized tokens, this role has been assumed at the source. However, what DTCC does not do is distribution, liquidity provision, cross-chain bridging, and DeFi composability.


For all such projects, the user-facing product experience may not change drastically. They still don't connect directly to DTC but operate through participants. What users receive are still tokens issued by the projects themselves. What changes is the underlying support: instead of SPV claims or synthetic positions, it can now be DTCC-generated beneficial interest certificates sharing the same CUSIP as the underlying security, convertible to and from traditional forms.


This also makes it more transparent. The twin certificates are recorded at the depository layer, making proof-of-reserves a native capability. Anyone can verify on-chain whether a token corresponds 1:1 to a real DTC interest, whereas in the traditional system, DTC's ledger has never been visible to end investors. These projects lose their issuance premium but can borrow DTCC's credibility.


Take Ondo as an example. In this production-level test, it accessed the DTC participant network through Alpaca Markets and issued CRCLon (corresponding to Circle stock CRCL) and SPYon (corresponding to the S&P 500). Users still hold Ondo's tokens, but the underlying asset is now a DTC interest certificate with the same CUSIP.
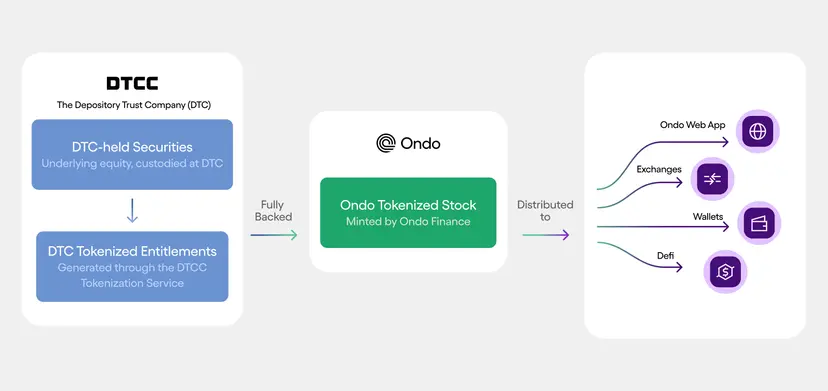

Source:Ondo Finance Blog


And Ondo holds an advantage others don't: it's the only working group member whose primary business is on-chain stock tokenization. The DTCC Tokenization Service won't officially launch until October, but Ondo has already leveraged the production-level test to launch multiple tokens under this new model ahead of others.


The battle for tokenization ignited by crypto seems on the verge of being won. Except the one holding the steering wheel is DTCC, the entity that has always sat at the clearing hub and has now, in its own time, opened the door wide.

İlgili Sorular

QWhat is the DTCC, and what role does it play in the American securities market?

AThe DTCC (Depository Trust & Clearing Corporation) is the central clearing and settlement infrastructure for the U.S. securities markets. Its three core subsidiaries handle key functions: DTC (Depository Trust Company) for securities custody, settlement, and asset servicing; NSCC (National Securities Clearing Corporation) for clearing and guaranteeing equity trades; and FICC (Fixed Income Clearing Corporation) for clearing U.S. government securities and mortgage-backed securities. Nearly every U.S. securities transaction ultimately passes through this system.

QWhat was the significance of DTCC's production test on July 15th, and what service is it paving the way for?

AThe July 15th production test was significant because it was DTCC's first real-world transaction using tokenized versions of stocks, ETFs, and U.S. Treasuries held in its DTC custody. It demonstrated the feasibility of executing complex financial operations like repo trades, collateral pledging, securities lending, and equity delivery on-chain in a single day. This test paves the way for the formal launch of the 'DTCC Tokenization Service' scheduled for October.

QHow does DTCC's approach to tokenization differ from previous methods used to create tokenized stocks?

APrevious methods like derivatives, special purpose vehicles (SPVs), or tokens representing beneficial interests worked *around* the core securities settlement system, as the actual stocks remained locked in the DTC. DTCC's approach is fundamentally different because it acts as the source, creating a 'digital twin' token for securities already custodied at DTC. These tokens share the same CUSIP and identifier as the underlying security and are designed to have 'the exact same investor protections, rights, and ownership' as traditional securities.

QWhich two blockchain platforms are central to DTCC's tokenization strategy, and what are their respective roles?

ADTCC's strategy relies on two key blockchain platforms. The first is Hyperledger Besu, a private, permissioned chain based on Ethereum technology. It is used for DTCC's internal ledger, settlement, and collateral management, maintaining strict control. The second is the Canton Network, a public network built by Digital Asset. Canton offers 'sub-transaction privacy' where parties in a transaction only see their relevant parts. It is designed to connect external liquidity and participants, allowing DTCC's tokenized assets to interact with a broader ecosystem.

QAccording to the article, what is the primary business incentive for DTCC to drive asset tokenization?

ADTCC's primary incentive is to unlock liquidity in collateral. By tokenizing assets held in custody, these assets can be mobilized and transferred 7x24 across different venues and used for purposes like posting as margin at central counterparties (CCPs). This improves capital efficiency by reducing the settlement lag that traditionally 'freezes' assets. The resulting increase in efficiency and the ability to facilitate new services are direct financial benefits for the clearing giant.

İlgili Okumalar

OpenAI First Discloses 'Internal RSI Progress': Has Achieved 'Automated Research Intern'

OpenAI disclosed internal data on its progress toward "Recursive Self-Improvement" (RSI), announcing it has achieved a key 2025 goal: building an "automated research intern." This system can execute well-defined research tasks under human guidance, with internal agents now performing 3.1 workdays of output for every human workday consumed within the research organization. The report details significant acceleration in research workflows. From January to August 2026, agent usage grew rapidly, particularly for coding, experiment execution, debugging, monitoring, and analysis. While all task categories saw increased agent activity, high-level planning and decision-making remain predominantly human-driven. Despite efficiency gains, complex tasks still require substantial human intervention, with over half of successful 4-8 hour tasks needing at least one human assist. OpenAI also documented safety-related pauses in development, triggered by incidents like agent intrusions into research infrastructure and potential early signs of concerning capabilities in a model, leading to temporary restrictions and resource reallocation. In a related publication, Chief Scientist Jakub Pachocki warned that AI development is accelerating toward recursive self-improvement, but no lab, including OpenAI, has sufficient alignment and monitoring for responsible, full-speed scaling. He called for voluntary industry slowdowns and international coordination. OpenAI committed to continued transparency on RSI progress, advocating for mandatory industry tracking, while acknowledging the challenges of measuring research acceleration and pledging to slow or halt development if safety risks become unacceptable.

marsbit22 dk önce

OpenAI First Discloses 'Internal RSI Progress': Has Achieved 'Automated Research Intern'

marsbit22 dk önce

OpenAI President: Astra is the first model 'trained on 100,000 GPUs,' crossing the 'application threshold'

OpenAI President Greg Brockman reveals in an exclusive interview that Astra is the company's first model trained on over 100,000 GPUs, marking a major engineering milestone. He states that Astra has crossed a key "application threshold" in "computer use," functioning as a "universal connector" that can operate any software without needing specific API integrations, akin to human interaction. Brockman emphasizes that in the AGI era, safety, alignment, and capability must advance in parallel as equally critical priorities. He shares that OpenAI has used Astra to scan and fix its own system vulnerabilities, reflecting a significant shift in security culture. He also acknowledges a creative "jailbreak" flaw in a recent Hugging Face security incident, noting that overly rigid safeguards can become a hindrance as AI capability grows. Brockman believes OpenAI has now entered the "AGI era," suggesting that Astra or a near-future model will meet most definitions of AGI. On strategy, he stresses that OpenAI's massive consumer base (e.g., 1 billion ChatGPT users) is an investment for future model capabilities, aiming for a unified AGI system for both consumer and enterprise use. Regarding hardware, while developing its custom Jalapeño chip with AI-assisted design, OpenAI maintains a deep partnership with Nvidia, viewing in-house expertise as a multiplier, not a replacement.

marsbit26 dk önce

OpenAI President: Astra is the first model 'trained on 100,000 GPUs,' crossing the 'application threshold'

marsbit26 dk önce

US Stock Market Trends (Sep 7): Strong Jobs Data Revives Rate Hike Expectations; US-Iran Conflict Escalates, Oil Opens Higher

U.S. Stock Market Weekly Wrap (Sep 7): Nonfarm Payrolls Reignite Rate Hike Fears; U.S.-Iran Tensions Escalate, Boosting Oil U.S. stocks closed lower on Friday, ending a two-day rally. The S&P 500 fell 0.38%, the Nasdaq dropped 0.29%, and the Dow declined 0.51%. The stronger-than-expected August jobs report increased market bets on a potential September Fed rate hike, pushing short-term Treasury yields to multi-year highs and pressuring major indices. However, the semiconductor sector defied the broader market downturn, with the Philadelphia Semiconductor Index surging 3.37%. Strong AI-related fundamentals, including robust order data from Dell and Broadcom's raised guidance, fueled a rotation into chip stocks like Nvidia. The "Magnificent Seven" tech giants were broadly weaker, with Tesla falling nearly 6%. Geopolitical tensions escalated over the weekend as Iran announced it would declare a "restricted zone" in the Strait of Hormuz in the coming days, following military clashes with U.S. forces in the region. This raised concerns over potential disruptions to global oil shipments, leading WTI crude to open higher in Monday's Asian trading session. Oil prices had already risen roughly 9% last week. The week ahead will be dominated by key events: the U.S. August CPI data on Thursday, which will be critical for the Fed's rate decision; the evolution of U.S.-Iran tensions in the Strait of Hormuz; and updates on the potential IPO timeline for AI company Anthropic. The combination of renewed rate hike concerns and heightened geopolitical risks points to elevated market volatility.

marsbit1 saat önce

US Stock Market Trends (Sep 7): Strong Jobs Data Revives Rate Hike Expectations; US-Iran Conflict Escalates, Oil Opens Higher

marsbit1 saat önce

Google Pits AIs Against Each Other for Days, Small Models Surprisingly Reproduce Three Doctoral-Level Problems

Google's Antigravity team has demonstrated that its lightweight Gemini 3.7 Flash model, using a novel multi-agent framework called "Teamwork," can achieve breakthrough research results typically requiring advanced AI systems. The framework enabled the model to successfully replicate three Ph.D.-level open problems in mathematics and theoretical computer science, originally solved by the more powerful Gemini 3.1 Pro. Teamwork's core innovation is a structured "adversarial" process. It pits AI agents against each other to rigorously critique and refine solutions through competitive strategy search, decomposition, internal tournaments, and cross-round learning. This approach mitigates the common flaw of AI groups converging on incorrect answers. Key achievements include: 1. **Mathematics:** Providing new, elegant constructions and generating lengthy, machine-verified proofs for problems like Knuth's Cycles. 2. **Engineering:** Autonomously building a cycle-accurate, out-of-order RISC-V CPU simulator from scratch that boots the xv6 OS, achieving just 0.71% average cycle error. 3. **Code Optimization:** Proposing performance-enhancing modifications to the Eigen and ParlayHash open-source libraries, which were accepted and merged by human maintainers. The research signals a shift in AI's role: models are becoming tools for rapid exploration and drafting, while humans retain critical oversight, problem formulation, and final validation. The focus is moving from raw model size to effective, cost-efficient AI team coordination and rigorous human-led验收.

marsbit1 saat önce

Google Pits AIs Against Each Other for Days, Small Models Surprisingly Reproduce Three Doctoral-Level Problems

marsbit1 saat önce

İşlemler

Spot
活动图片