How to Understand the CFTC's Regulation of Prediction Markets?

marsbitPublished on 2026-10-13Last updated on 2026-10-13

Abstract

On October 9, the U.S. Commodity Futures Trading Commission (CFTC) released two conflicting documents concerning event contracts in prediction markets. A proposal seeks to classify contracts on sports, politics, and other events as "swaps" under CFTC jurisdiction, while a separate interim rule explicitly excludes licensed sports betting and casino games from the swap definition. This creates a regulatory split where bets on the same NFL game could be regulated as state-level gambling if placed at a Las Vegas sportsbook, but as a federally regulated swap if traded on a CFTC-registered exchange like Kalshi. CFTC Chairman Michael Selig argues these event contracts are commodity derivatives for hedging, speculation, and price discovery. However, the move faces legal challenges. The NFL and 39 states oppose the CFTC's stance, arguing these contracts create new gambling risks rather than hedging existing ones. Federal appeals courts are divided: the Third Circuit ruled such contracts are swaps, while the Sixth and Ninth Circuits concluded they are not. This circuit split has prompted New Jersey to petition the Supreme Court for review. The proposed rules are not yet in effect, pending publication and a comment period. The ultimate outcome hinges on court decisions and the future composition of the CFTC commission. The core conflict remains whether event contracts on prediction markets fall under federal derivatives regulation or state gambling laws.

Author: Huohuo, The Block

On October 9th, the U.S. Commodity Futures Trading Commission (CFTC) released two documents with opposing directions on the same day. One proposal aims to include event contracts for sports, politics, culture, weather, etc., found in prediction markets, within the definition of a swap, while another interim final rule explicitly excludes licensed sports betting and casino games from the definition of a swap.

In plain terms, a swap is a contract where payments are determined by an outcome. Under U.S. derivatives law, once a certain type of contract is classified as a swap, it typically falls under the exclusive regulatory oversight of the CFTC, preempting state gambling licenses and state taxes. This is federal preemption.

Therefore, the core issue of contention is: who writes the rules for the same NFL game? If placed at a Vegas counter or in the DraftKings app, it is state-regulated gambling; if turned into an event contract and placed on a federally registered exchange like Kalshi, the CFTC argues it is a swap.

CFTC Chairman Michael Selig is the only sitting commissioner among the five-member commission. He stated directly that Americans use event contracts to hedge, speculate, and obtain information, and these products fall within the category of commodity derivatives under the CFTC's exclusive jurisdiction. Casino-style products, however, are not derivatives.

The trading volume is the backdrop for this round of actions. The CFTC reported that event contract volume on U.S. registered exchanges (DCMs) reached approximately $1.5 billion in August, with about $1.2 billion related to sports. Market estimates are much larger. For example, Kalshi and Polymarket combined traded roughly $85.6 billion over a weekend in October, with sports contracts being the primary driver of this surge in volume.
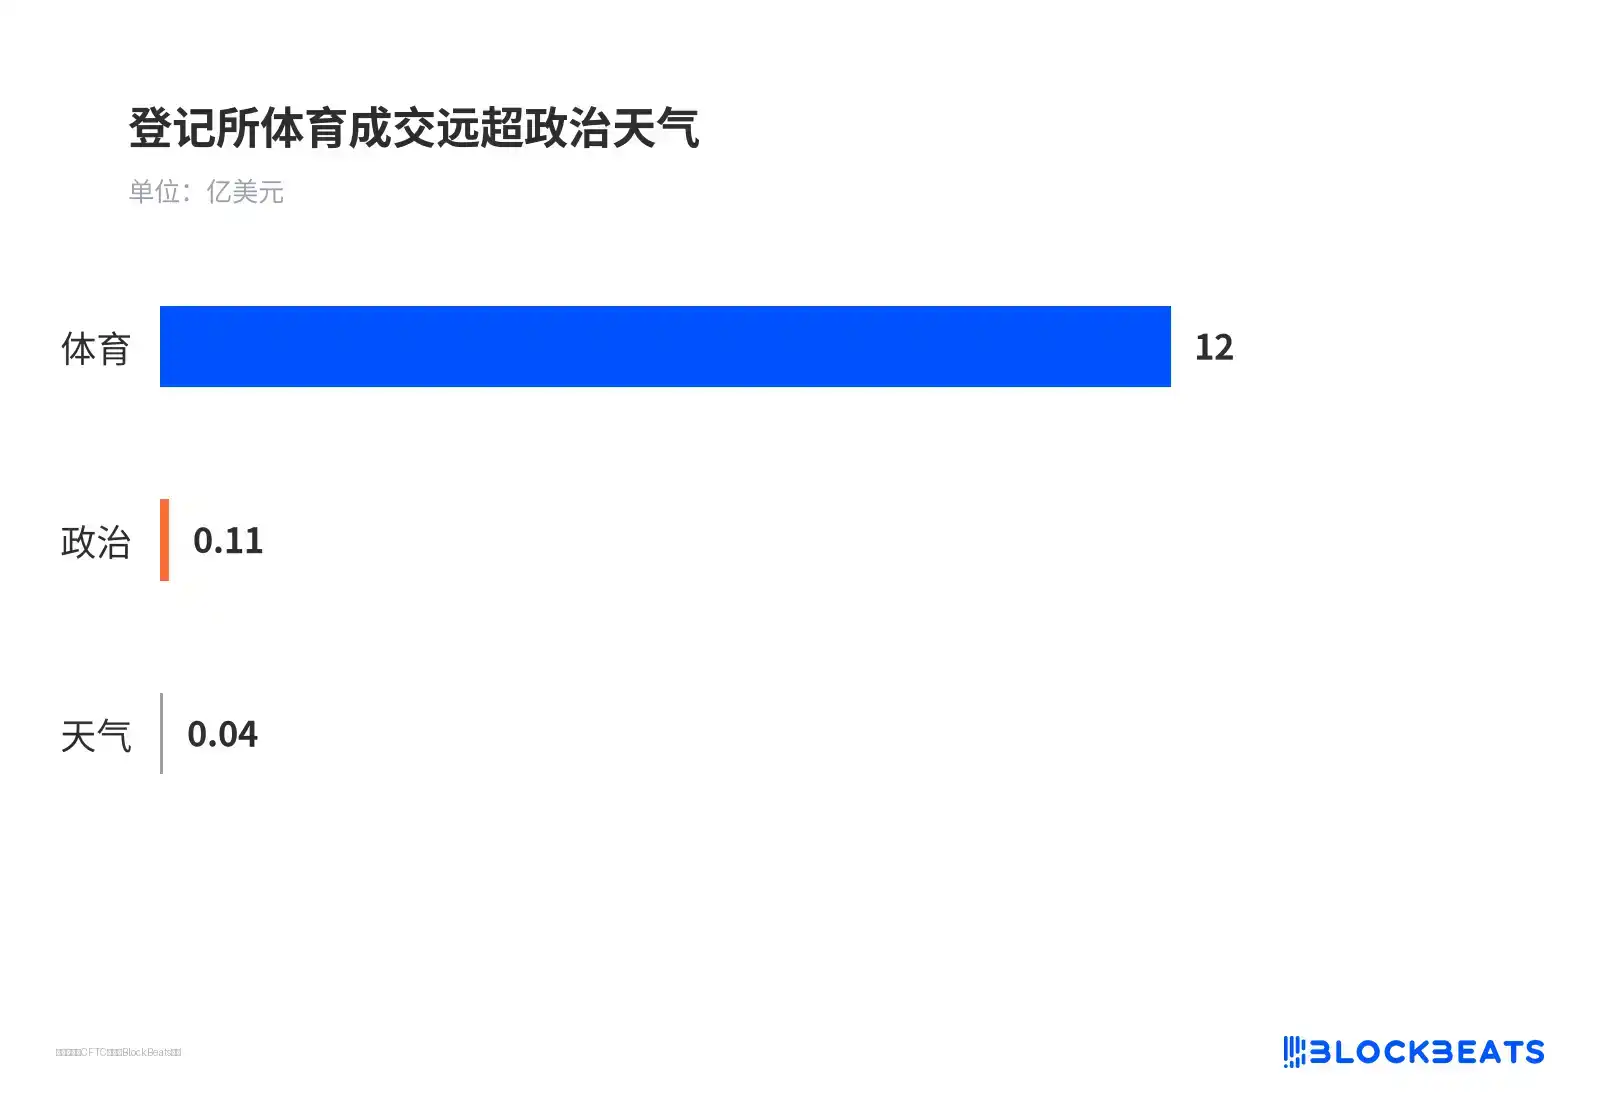
Trading volume for registered sports contracts far exceeds that for politics and weather

One inclusion, one exclusion: Two directions being written into the swap definition

The proposal answers what counts as a swap, while the interim final rule answers what does not. The latter uses two tests to define the boundary. Only wagers offered by licensed state or tribal gaming operators and that are not matched on a multilateral exchange platform are excluded. Both conditions must be met to be considered a casino-style wager.

Combining these two boundaries essentially splits sports betting in half—one half remains with the states, the other is handed over to the federal government. The same sports bet, if placed at a counter in Las Vegas, is gambling; if placed on a federally registered exchange like Kalshi, it becomes a swap.
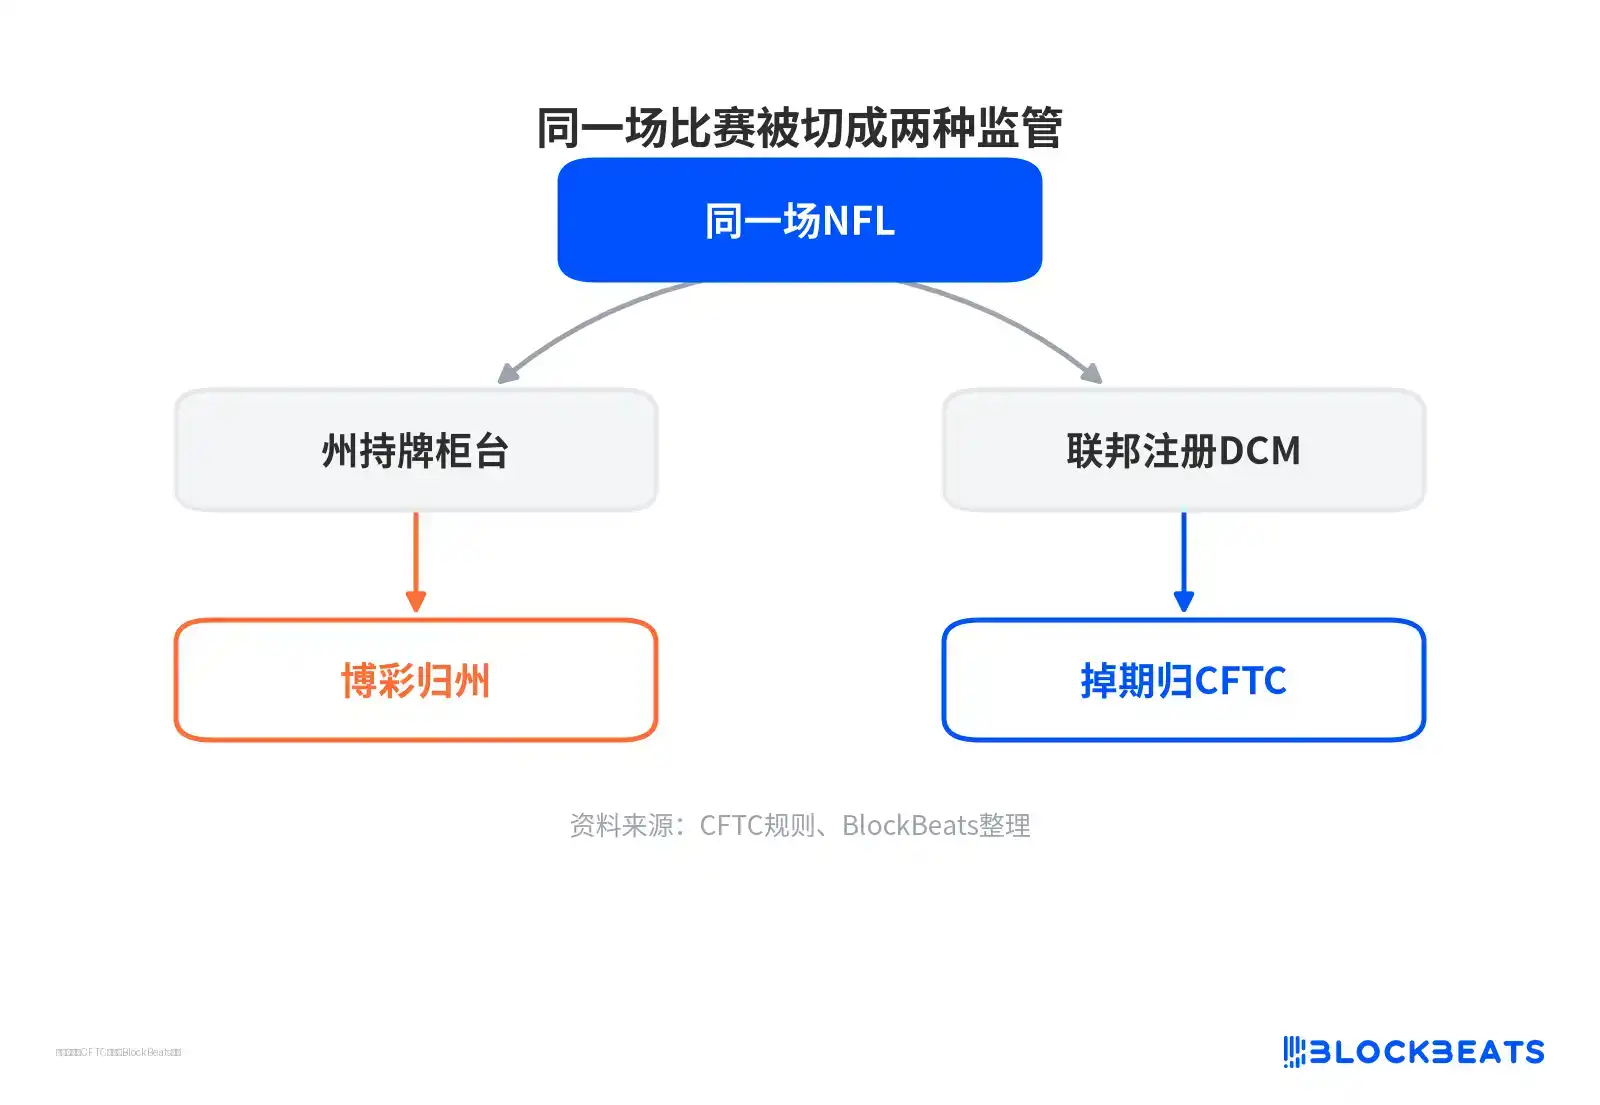
The same game is being cut into two types of regulation

Similar questions appear in the court brief filed by the American Gaming Association: if a sports bet is considered a swap, should bets placed at Las Vegas counters also have to be on a DCM?

TD Cowen policy analyst Jaret Seiberg offers another interpretation. States have repeatedly argued in lawsuits that the CFTC's definition of event contracts as swaps is too broad, potentially making wagers at state and tribal casinos federally illegal.

The interim final rule, by first carving out casino games, is precisely meant to dismantle this line of attack in court. Seiberg's judgment is that this move is mainly to improve the CFTC's legal position; whether it will be effective is another matter.

If this classification fails to hold up in court, states could potentially use the casino line to pull event contracts back under state law.

The NFL and 39 States: Who should set the rules for the same game?

A clear judicial split has already formed. New Jersey has petitioned the Supreme Court over its jurisdictional dispute with Kalshi. The NFL and 39 states plus Washington, D.C., have filed amicus briefs supporting New Jersey.

The NFL argues that sports event contracts create new risk for gambling, rather than hedging existing risk like a swap, and points out that the CFTC does not prohibit easily manipulated betting lines, nor does it cover lines related to player injuries, referees, or enforce a minimum age of 21. On the first Sunday of this season, prediction markets traded approximately $3.3 billion, with $1.8 billion related to football.

U.S. federal appeals courts are divided into circuits. Different circuit courts can issue contradictory rulings on the same legal question. When such a circuit split occurs, the Supreme Court is more likely to intervene. Three federal appellate circuits have already reached opposite conclusions this year:

Third Circuit (April this year): Held that sports contracts on DCMs are swaps and can preempt state law.

Sixth Circuit (September) and Ninth Circuit (August): Reached the opposite conclusion, holding that these contracts are not swaps and state law applies.
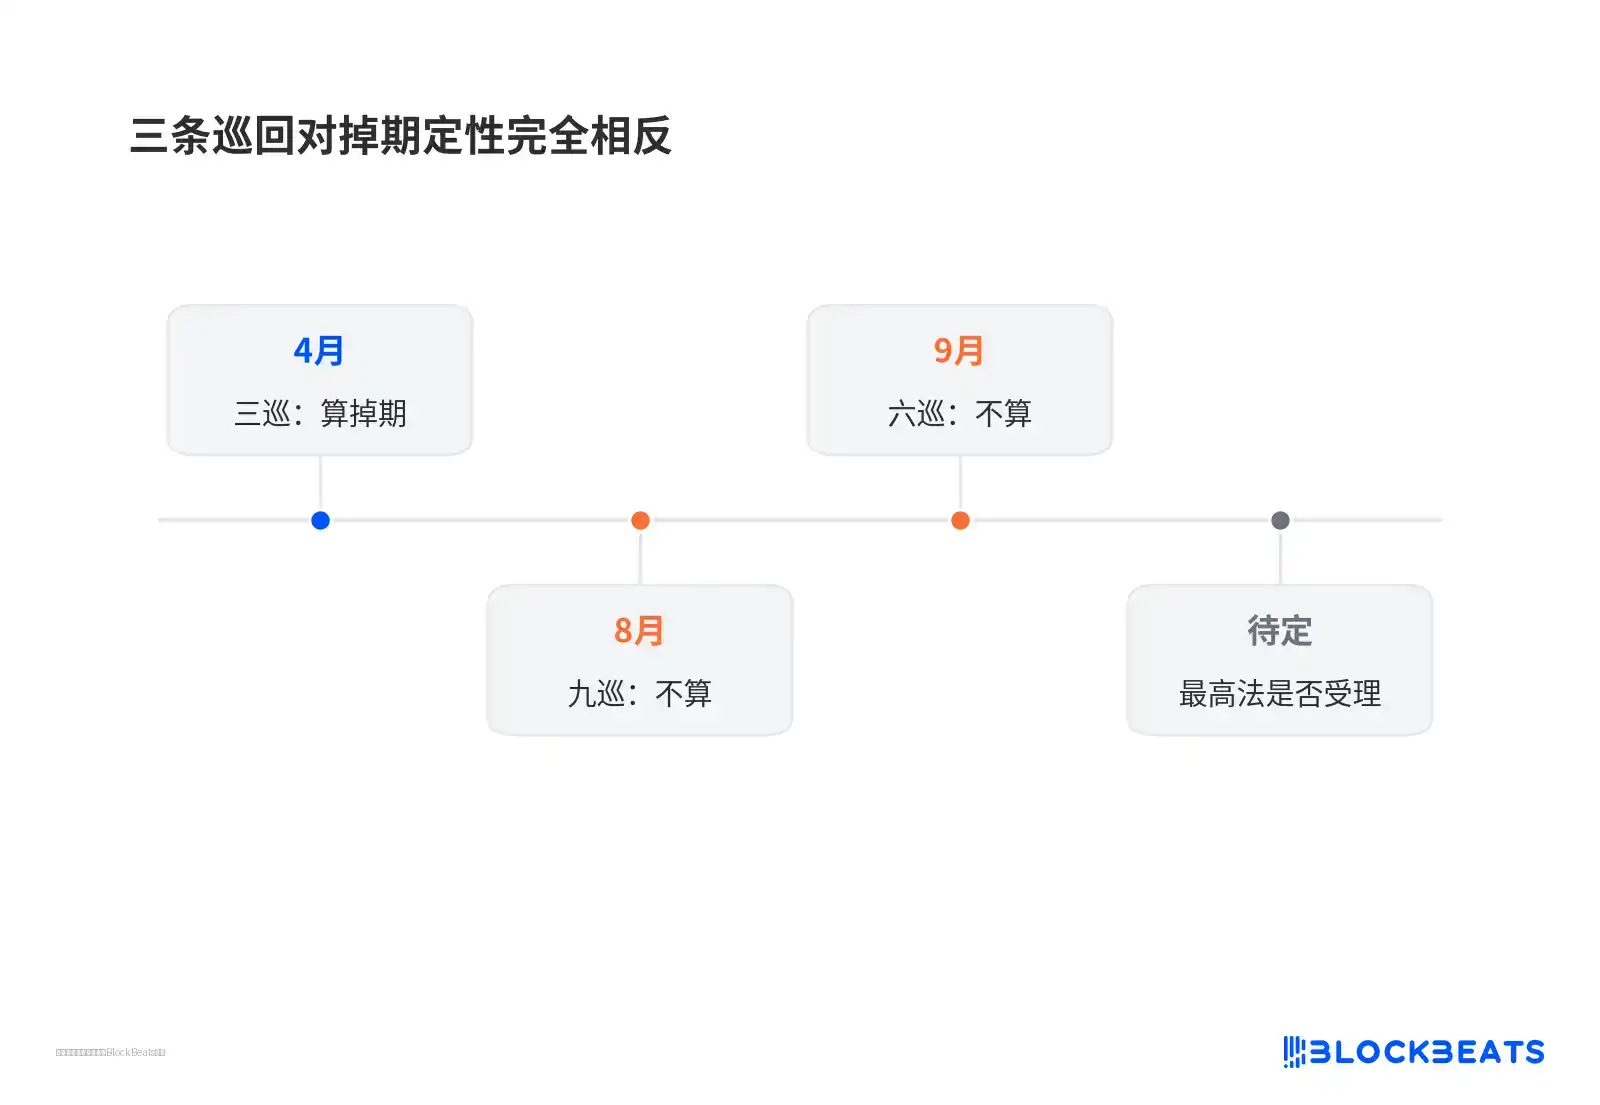
Three circuits hold completely opposite views on swap classification

With the three circuits at odds, the same contract could receive contradictory classifications in different jurisdictions. This is precisely why New Jersey wants to bring the issue to the Supreme Court. Kalshi's response deadline is November 9th, and the Supreme Court has not yet decided whether to hear the case.

Rules Not Yet in Effect; Variables Lie with Courts and Commissioner Seats

As of now, neither document has been published in the Federal Register. The comment period for the proposal begins from the publication date and lasts 30 days. The interim final rule also only takes effect upon publication. Calling them "already entered into consultation" or "already in effect" at this stage is inaccurate.

A more critical variable lies with the courts. New Jersey's petition has placed the split between the Third Circuit and the Sixth/Ninth Circuits before the nine Supreme Court justices. There is no news yet on whether they will hear the case. Administrative rules can strengthen arguments for the Third Circuit's template, but the ultimate authority to interpret the law rests with the judges.

Selig is the only sitting commissioner among the five-member commission. Pushing rules forward under a short-staffed commission may be legally tenable, but the oversight is thin. Once the commission is fully staffed, or if the courts do not adopt this definition, today's protective measures could be rewritten.

In this round of contention, the regulated parties themselves have remained quiet; Kalshi and Polymarket have yet to make any public, on-the-record statements.

Related Questions

QWhat are the two main actions taken by the CFTC on October 9th regarding event contracts, and what are their intended effects?

AThe CFTC issued two documents. One is a proposal to include event contracts for sports, politics, culture, and weather within the definition of a 'swap.' The other is an Interim Final Rule explicitly excluding licensed sports wagering and casino games from the swap definition. The intended effect is to carve out a regulatory boundary: similar sports bets offered on federally registered exchanges like Kalshi would be regulated as swaps under CFTC jurisdiction, while bets placed at state-licensed sportsbooks in places like Las Vegas would remain under state gambling law.

QWhat is the core legal and regulatory conflict at the heart of the CFTC's recent actions on prediction markets?

AThe core conflict is jurisdictional preemption. Under U.S. derivatives law, if a contract is defined as a 'swap,' it falls under the exclusive jurisdiction of the CFTC (federal preemption), overriding state gambling laws and taxes. The dispute centers on who gets to set the rules for the same event (e.g., an NFL game): state regulators for traditional sports betting or the CFTC for event contracts traded on federally registered exchanges.

QWhat contradictory rulings have emerged from U.S. federal appeals courts regarding the classification of sports event contracts, and why is this significant?

AThree U.S. Circuit Courts of Appeals have issued contradictory rulings in 2024: The Third Circuit (April) ruled that sports contracts on Designated Contract Markets (DCMs) are swaps and can preempt state law. The Sixth (September) and Ninth (August) Circuits reached the opposite conclusion, stating these contracts are not swaps and state law applies. This 'circuit split' is significant because it creates legal uncertainty, with the same contract having different statuses in different jurisdictions, making the issue ripe for potential review by the U.S. Supreme Court.

QAccording to analysts cited in the article, what is a strategic reason behind the CFTC's Interim Final Rule that excludes licensed casinos?

AAnalyst Jaret Seiberg suggests a key strategic reason is to improve the CFTC's position in ongoing court battles. State opponents argued that the CFTC's broad definition of 'swap' for event contracts would render state and tribal casino wagers federally illegal. By explicitly carving out licensed casino games via the Interim Final Rule, the CFTC aims to defuse this specific legal attack and strengthen its argument that event contracts are distinct from traditional gambling.

QWhat are the current procedural and political variables that could change the outcome of the CFTC's proposed regulatory framework for prediction markets?

AKey variables include: 1) The courts: The Supreme Court has not yet decided whether to hear New Jersey's petition highlighting the circuit split. Judicial interpretation will ultimately decide the rules. 2) The CFTC Commission: Currently, only Chairman Rostin Behnam is seated on the five-member commission. Future decisions by a fully staffed commission could rewrite or reverse the current proposals. 3) The rulemaking process: The proposals are not yet final. The comment period for the proposal and the effective date for the Interim Final Rule only begin once they are published in the Federal Register.

Related Reads

"All the Bad News Hit at Once," Yet US Stocks Rebounded Against the Trend: Wall Street Stages a "Nothing Left to Sell" Short Squeeze

In a week packed with bad news—Nvidia founder Jensen Huang's scandal-driven resignation, a third straight CPI upside surprise, PPI at a four-year high, and Fed officials floating a 50bp December hike—US stocks defied gravity, with the S&P 500 up 2% and the Philadelphia Semiconductor Index posting its best week since April. The explanation: shorts had no cards left to play. A classic "no inventory to sell" squeeze unfolded as hedge funds cut leverage to five-year lows, leaving few sellers to absorb the bad news. Meanwhile, bonds bore the entire macro shock, with 2-year yields surging 35bp (the biggest weekly jump since October 2024) and 10-year yields breaking 5.15%. Nvidia fell about 11% for the week, but retail buying hit a record 41x normal levels, and capital rotated into AMD (+30%) and Broadcom (+24%) rather than leaving AI. By Friday, equities began "reading the bond market's mail," with the S&P 500 hitting resistance at its 100-day moving average. Goldman's Rich Privorotsky warned the market needs oil to stabilize and rates to fall—neither of which happened. The bond selloff was driven by real rates, not inflation expectations, with TIPS yields up 90bp year-to-date. Credit markets showed no panic at the index level, but cracks are widening: chip-sector CDS spreads exceeded hyperscaler spreads for the first time, and CCC spreads widened 270bp in three months. Geopolitically, hopes for Iran de-escalation died as Trump closed the diplomatic door, and oil rebounded after the Strait of Hormuz saw daily tanker mine strikes. Global equity funds drew $51 billion, the largest weekly inflow since late September, though US inflows slowed. Next week's tests include Nvidia earnings on November 17 (Colette Kress's first as interim CEO), Anthropic's IPO seeking up to a $1 trillion valuation, Treasury supply and foreign demand, and Fed speakers. As Privorotsky put it: "The AI trade survived Huang's departure, but Waller is a different kind of trouble—because he won't resign."

marsbit3m ago

"All the Bad News Hit at Once," Yet US Stocks Rebounded Against the Trend: Wall Street Stages a "Nothing Left to Sell" Short Squeeze

marsbit3m ago

OpenAI and Meta Join Forces, Bridging the "Last Mile" of Agent Commerce

On November 13, 2026, two major announcements landed the same day, together addressing the "last mile" of agent commerce: how AI assistants get through the door, and how they pay. Sierra and Meta released Poppy v1.0, a Personal Agent Protocol built on OAuth, HTTPS, OpenAPI, and the Model Context Protocol. Poppy lets businesses cryptographically verify three things: which assistant is making a request, which user it represents, and what permissions it holds. Companies publish a discovery file at /.well-known/poppy describing endpoints and allowed actions, while both user and business must consent to each interaction via two-way authorization. Shopify automatically enabled Poppy discovery files for merchants in 175+ countries, giving the protocol immediate scale, with over 100 design partners including Delta, 1Password, Okta, and Cloudflare. Separately, OpenAI launched ChatGPT Wallet for its personal assistant dots. The assistant can search, compare, and fill a cart, but must stop at checkout—users confirm via biometric authentication. Neither the assistant nor the merchant ever sees the real card number; card networks issue a one-time payment credential instead. Built with Amex, Mastercard, and Visa, the wallet runs entirely on traditional fiat rails—explicitly not crypto or stablecoins. It initially opens only to US Pro subscribers aged 18+. Notably, Visa and Mastercard span both initiatives, and OpenAI itself appears among Poppy's design partners—despite dots and Meta's Muse competing for the consumer entry point. The shared logic: consumer-facing competition, but shared infrastructure on the business side. The common bottom line is "human in the loop"—agent autonomy stops at the shopping cart. Open questions remain: liability when an assistant errs or is manipulated by malicious prompts, coverage beyond Shopify and US Pro users, and whether mandatory biometric confirmation for every small purchase will become friction that undermines the convenience promise.

marsbit9h ago

OpenAI and Meta Join Forces, Bridging the "Last Mile" of Agent Commerce

marsbit9h ago

Has the Time Come to Buy the Dip on Nvidia?

Nvidia announced on November 12 that Jensen Huang resigned as President, CEO, and Director, effective immediately. Shares fell as much as 14% intraday to $148.8, down nearly 40% from October highs, with over $600 billion in market value briefly erased. The founder's departure triggered the selloff, but the market is repricing the entire company rather than reacting to a single risk. Nvidia now trades at roughly 12x forward PE, its lowest in 15 years and below the S&P 500's ~18x, despite strong fundamentals: FY2026 revenue of $215.9 billion (+65%), data center revenue of $62.3 billion in a single quarter, ~75% gross margins, and Q2 FY2027 revenue of $96.2 billion with $21.3 billion free cash flow. Most investment banks cut targets but maintained Buy/Overweight ratings (Barclays $210, Goldman $220, Citi $225, RBC $230), implying ~20% upside, while Truist downgraded to Hold at $174. The consensus: the business is intact, but its valuation multiple needed resetting. Supporting demand, Huang forecast at GTC 2026 that Blackwell and Rubin AI chip demand would reach at least $1 trillion by 2027, double the prior 2026 estimate. However, risks remain beyond CEO succession. CUDA's lock-in effect is eroding on the inference side—Anthropic disclosed that its Claude Mythos Preview autonomously ported core GPU kernels to AMD flagship GPUs in three days with minimal human intervention, prompting investor Marcelo P. Lima's widely cited claim that "Nvidia's CUDA moat no longer exists." Supply bottlenecks lie in HBM and packaging, not wafers: TSMC can cut over 400 million GPU dies annually, but Nvidia ships only ~10 million GPUs yearly, constrained by HBM capacity (~3.75EB globally, ~70% allocated to Nvidia, ~260GB per GPU) and tight packaging, with HBM4 adjustments possibly delaying Rubin. Huang also leaves behind highly personalized assets—strategic technology judgment, supply chain negotiation with TSMC and SK Hynix, and direct channels to customers and governments—that interim CEO Colette Kress, the long-time CFO, may not fully replace. In short, the business remains, but the "faith premium" is being systematically stripped away. At 12x forward PE, much pessimism is priced in, offering a favorable risk-reward window if AI capex holds and demand materializes. Yet cheapness alone isn't sufficient: CUDA's erosion is slow but irreversible, HBM and packaging limit revenue upside, and succession uncertainty means the founder premium may not be fully removed. As Bernstein noted, "if you see two ants in the kitchen, there are more than two," warning that chains from scandal to governance vacuum to government probes could trigger further selloffs. Until the dust settles, what a Jensen-less Nvidia is worth remains an open question.

marsbit10h ago

Has the Time Come to Buy the Dip on Nvidia?

marsbit10h ago

AI Bull Market Trap? The Big Short Seller Strikes Again

Recent signals from Goldman Sachs, the Federal Reserve, and prominent short-seller Michael Burry are converging on concerns about the AI trade. Goldman warns that AI capital expenditure growth will likely peak in early 2027, with the boost to S&P 500 earnings falling from a 12-point peak in 2026 to a 5-point drag by 2028, shifting the market from a one-way rally to two-way volatility. The Fed has flagged AI as a potential threat to asset valuations and financial stability. Burry has doubled his Nasdaq 100 put options and rebuilt short positions in a semiconductor ETF, calling this a "bull market trap" analogous to the 2000 dot-com bubble, with Nvidia's influence a key worry. Four pressures weigh on the AI narrative: peaking capex growth, high interest rates that hit long-duration AI assets and leveraged GPU cloud providers like CoreWeave and Nebius, circular financing risks among interconnected tech firms, and tighter regulation under Democrats affecting data center energy, land, and permitting. Nvidia-related turmoil has shaken the pricing anchor for the entire supply chain. However, a valuation bubble bursting does not mean the AI industry is declining. Goldman notes US cloud giants trade at just 19.7x forward P/E, below their 20-year historical range and even below defensive staples, suggesting much pessimism is already priced in. Opportunities are shifting from upstream hardware "shovel sellers" toward fairly valued cloud giants with improving free cash flow, AI application companies delivering real ROI, and deeply discounted cyclical names like Korean memory. Conversely, GPU cloud providers dependent on Nvidia orders and cash-burning startups without products are most vulnerable. Investors should diversify, hedge, and focus on assets that convert spending into stable returns.

marsbit10h ago

AI Bull Market Trap? The Big Short Seller Strikes Again

marsbit10h ago

Just Offered 3.3 Million Yuan Salaries to Poach Talent, OpenAI Suddenly Dissolves Robotics Team—Is the Industry About to Change!

OpenAI has disbanded its standalone robotics research team, confirmed shortly after booking booth 208 at the CoRL robotics conference in Austin went empty on November 13. The move surprised many, given that just months earlier OpenAI was aggressively hiring robotics talent—some roles paying up to $500,000 base salary—and had expanded its San Francisco data-collection lab to about 100 workers across three shifts, with a second lab planned in Richmond, California. Researchers from the robotics team are now folded into Chief Research Officer Mark Chen's core research division, while robotics applications and hardware staff move to President Greg Brockman's Applied division. OpenAI says robotics remains part of its long-term vision and the reshuffle is meant to accelerate progress. This is not OpenAI's first robotics retreat: it ended its first independent robotics effort in 2020 to focus on large language models, which produced ChatGPT, and only rebuilt a team in 2024. OpenAI explains the latest pivot technically—researchers initially believed video-generation models like Sora could teach robots physics, but general models such as GPT-6 Astra proved capable of directly controlling robots, so robotics work is being merged into the general foundation-model team. The broader industry context supports this shift. Unitree's Wang Xingxing said his biggest mistake over the past decade was not trusting AI enough, noting GPT-6 integration exceeded expectations and that humanoid intelligence's tipping point may arrive within one to two years. Anthropic's Claude Fable 5.2 scored 64.9% on the RoboDojo Sim benchmark versus 29.8% for GPT-6 Astra, and Nvidia's Astranomy study showed GPT-6 Astra controlling simulated robots with 74.8% success using an agentic approach, beating the prior specialized-model best of 51.0%. Yet challenges remain: general models are costly and slow—GPT-6 Astra averaged 18.56 seconds per inference and about 30.9 million tokens (roughly $36.40 in API fees) per successful task—problematic for real factories where conveyor belts don't pause. Google DeepMind, Nvidia, Unitree and AgiBot continue training specialized robotics models; Google's Apollo 2 achieved 96% success sorting parts in Mercedes factories using paired reasoning and action models, while Nvidia's GR00T 2 reached 95% success after brief fine-tuning. Analysts suggest OpenAI now treats robotics as a downstream application of general intelligence, leveraging core model advances while using its data-collection and hardware capabilities to validate models on real robots.

marsbit10h ago

Just Offered 3.3 Million Yuan Salaries to Poach Talent, OpenAI Suddenly Dissolves Robotics Team—Is the Industry About to Change!

marsbit10h ago

Trading

Spot
活动图片