Author: Simon Taylor, Founder of Fintech Brainfood
Compiled by: Jiahuan, ChainCatcher
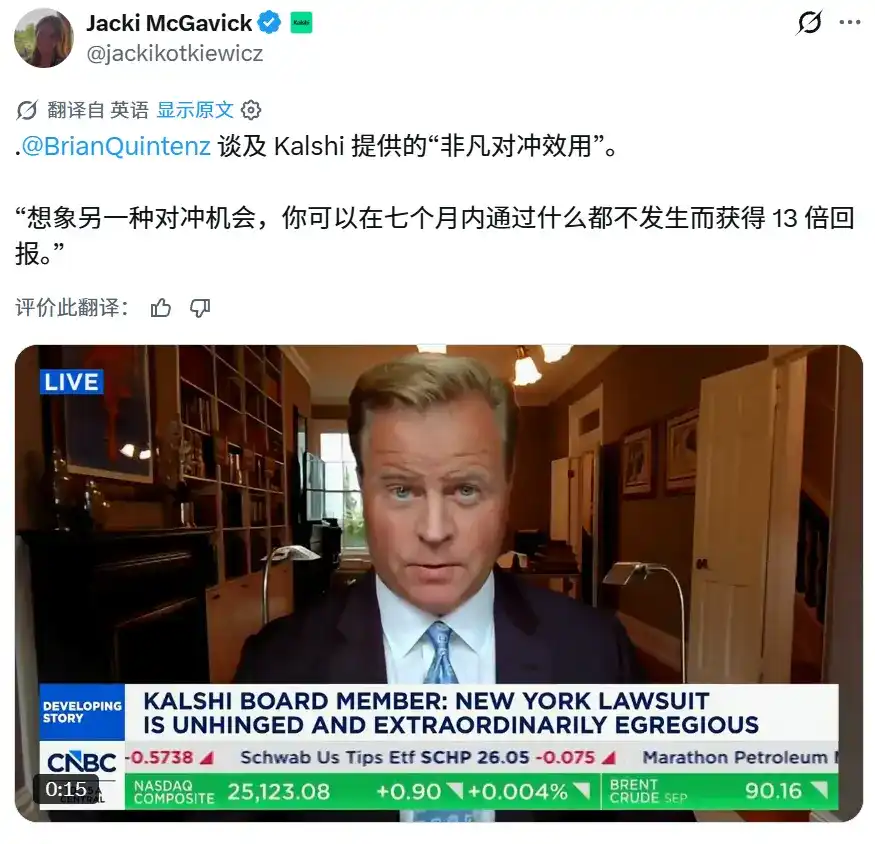
"Imagine what other hedging opportunity could let you make 13 times your money in 7 months?" That's how former CFTC commissioner and current Kalshi board member Brian Quintenz recently described one of Kalshi's contracts on CNBC.
The contract bets on how many times the Federal Reserve will cut rates in 2026. In January this year, the "zero cuts" contract was priced at just 6 cents; now it's up to 82 cents. If you had bought $10 worth in January, it would now be worth about $137. If you had made the same correct judgment through Fed funds futures, the tool professional investors typically use to trade interest rate expectations, the gain might have been just a few cents. This difference is crucial for any business reliant on stable rates.
But prediction markets are like a Rorschach test. A former derivatives regulator calls a 13x return a hedging opportunity; a corporate treasurer might see it as insurance; and for an average consumer on a phone app, it's a 13-to-1 bet. Three people are looking at the same contract, the same market, and the same price.
The power of prediction markets comes precisely from their simplicity. A "yes/no" contract lets you trade the answer to almost any question: Will the Fed cut rates? Can the Knicks repeat? Will Fintech Nerdcon be the best event of 2026? When the "zero cuts" contract is priced at 82 cents, it means the market assigns an 82% probability to that outcome. If there are indeed zero cuts, the contract pays $1. The price is the probability.
Event contracts are also very good business. In its Q2 earnings, Robinhood disclosed that prediction market revenue surpassed crypto and stock trading for the first time: event contract revenue was $156 million, stock trading $129 million, and crypto $100 million; among all transaction-based businesses, only options were higher at $342 million.
One thing Robinhood excels at is capturing consumer attention with speculative products. If a speculative asset can bring users onto the platform, it's a fantastic customer acquisition tool. Think about it the other way: if Robinhood had never offered these speculative products, would it really have 28.4 million funded accounts?
There's already some evidence that some users who come to Robinhood for prediction markets eventually build long-term investment portfolios. Robinhood Gold subscribers reached 4.8 million, up 39% year-over-year; net deposits hit a record $21.7 billion, and total assets under custody reached $369 billion.
Better hedging tools, more effective user acquisition, and, for others, better probability data on outcomes than pollsters—this is the strongest defense one can make for prediction markets.
But there are three problems with this picture.
First, sports is becoming the largest category in prediction markets, directly replacing some traditional sports betting, thereby triggering relevant taxes in various US states. Kalshi and Polymarket are already facing at least 20 legal actions initiated by state regulators, Native American tribes, and individuals. Both companies are also counter-suing and appealing, while the CFTC is similarly suing several of these states, pushing the disputes to higher levels. Will courts resolve these issues within the next year? Probably not.
Second, prediction markets primarily launch contracts through "self-certification" with the regulator, the CFTC. This system relies on the regulator's interpretation of the law, which often changes with shifts in government and leadership. The current CFTC is very friendly to prediction markets and actively defends this model. But what if the winds change in the future?
Most importantly, prediction markets are competing for the attention of the same people as traditional sports betting platforms. Those who might have placed sports bets in the past are now entering prediction markets, but they may not be covered by the same state or federal protections aimed at reducing consumer harm that exist in the traditional industry, while problematic betting behavior itself is increasing. Of course, platforms designated as DCMs (Designated Contract Markets, licensed derivatives exchanges regulated by the CFTC) must still adhere to at least 23 core principles, and new regulatory requirements keep piling up.
If legal issues won't be resolved for a long time, if regulators might change in two years, and if consumers are not so much clients as they are 'data inputs' for this market, then the only thing I can be certain of is that everything is full of uncertainty.
Perhaps we should open an event contract on the regulatory fate of prediction markets themselves?
But unfortunately, the future of prediction markets won't be settled simply like a "yes/no" contract. And the future of financial markets, as well as consumer interests, may all depend on how we ultimately resolve this issue.
Before rushing to judgment, we need to more fully understand the pros and cons of prediction markets. So, here is my attempt.
1. Sports Becomes the Biggest Growth Engine for Prediction Markets
The growth numbers look like a product that's exploding.
-
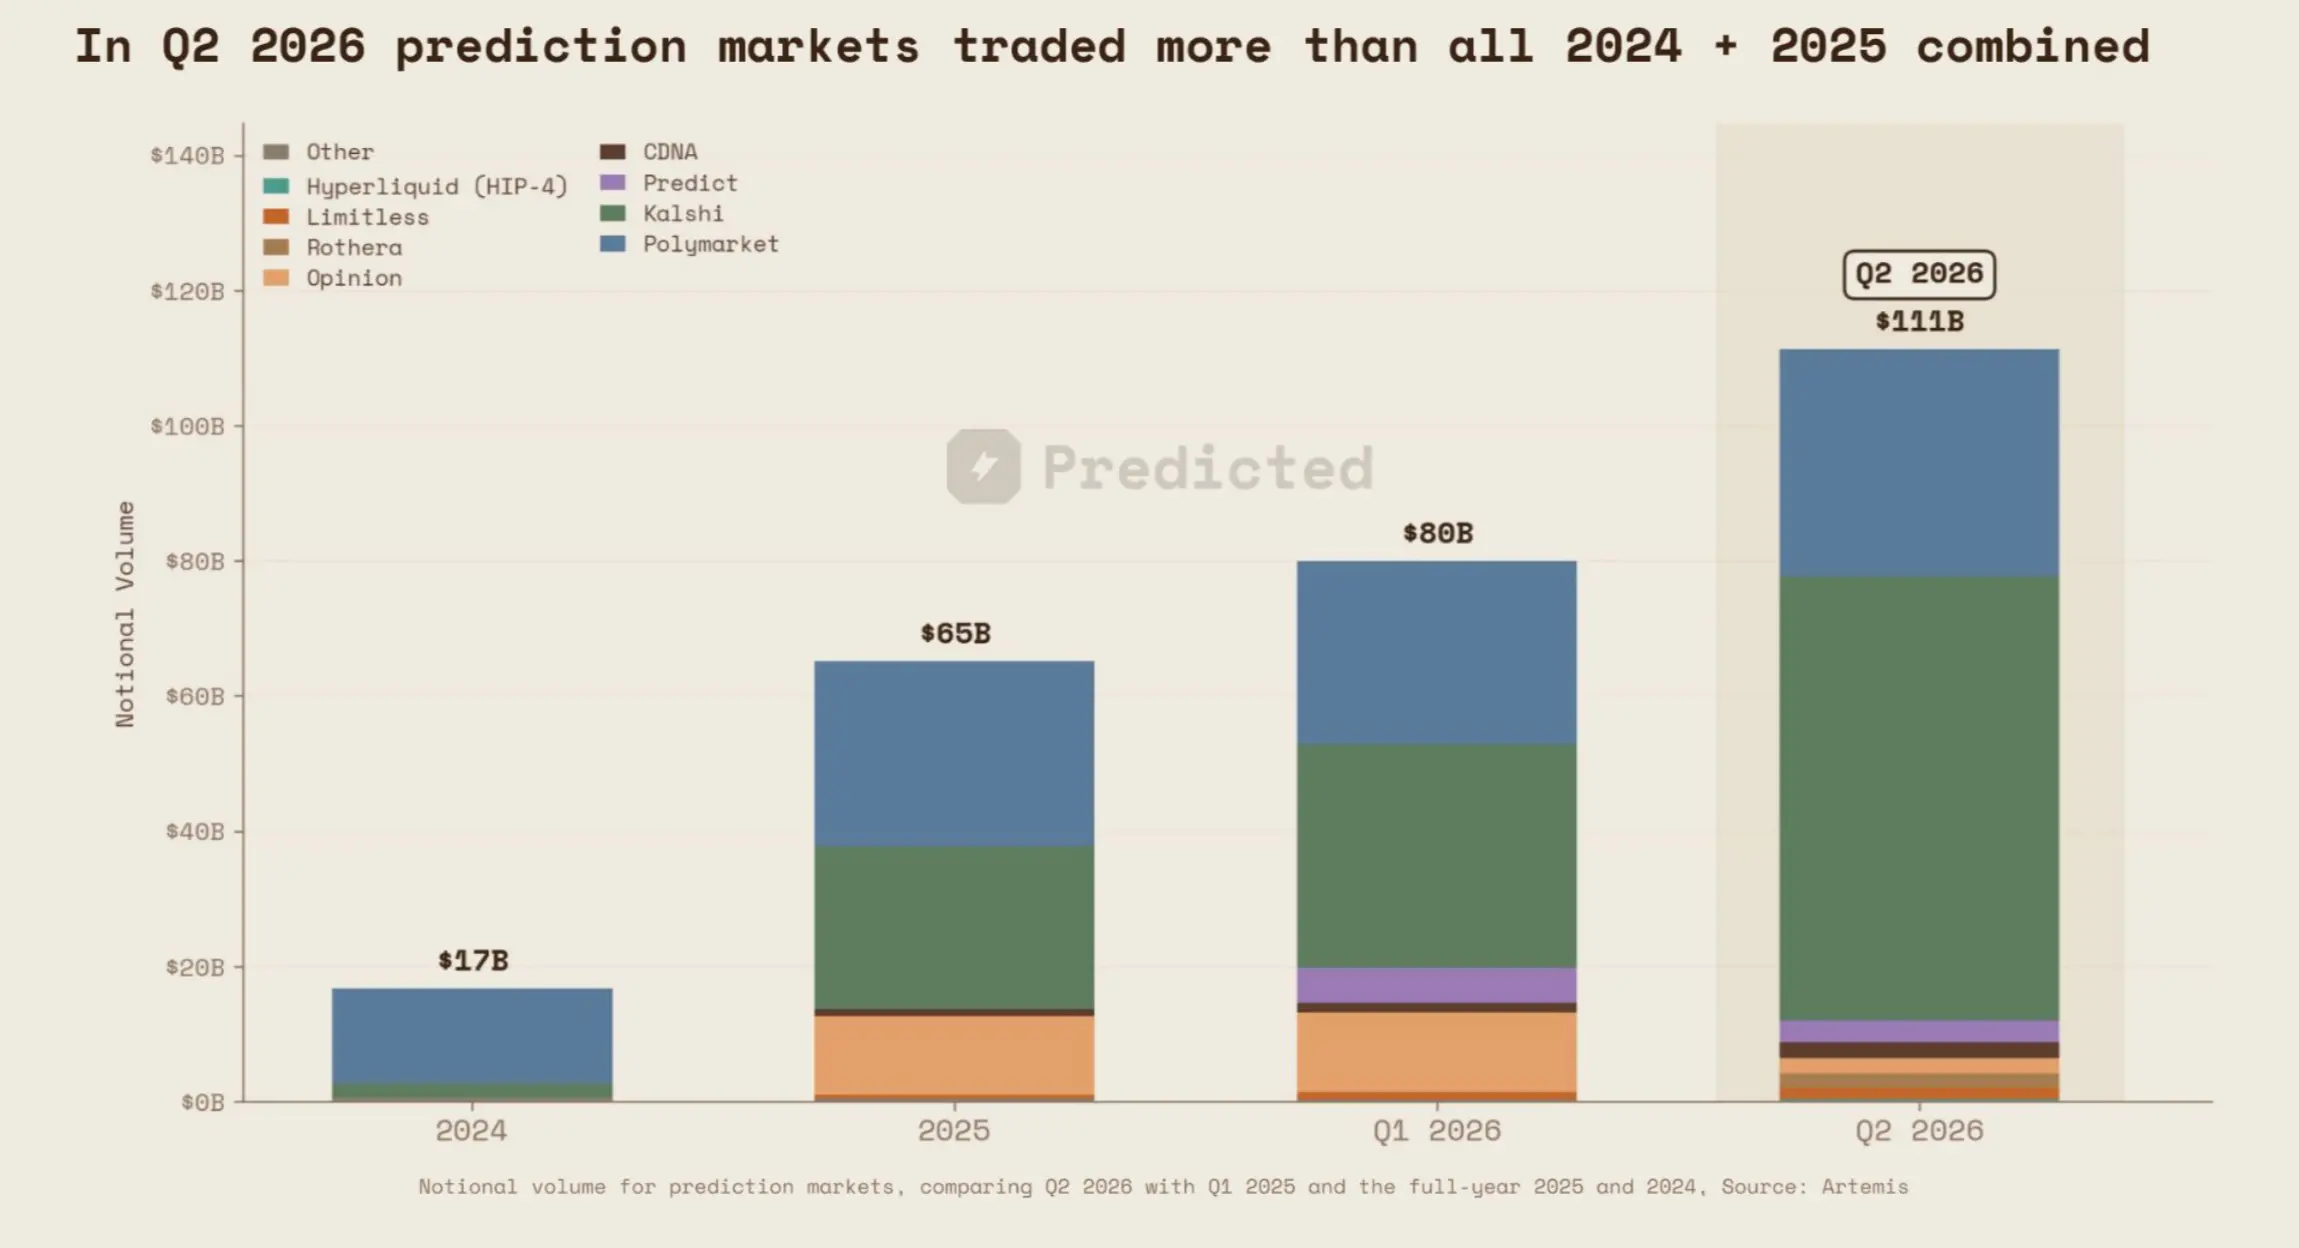
In Q2 2026, prediction market trading volume reached $111 billion, exceeding the combined annual volume of 2024 and 2025, a staggering 1795% year-over-year increase.
-
June became the highest trading volume month ever for prediction markets, at $52.7 billion, largely driven by the World Cup.
-
Prediction markets related to the World Cup alone saw nominal trading volume of $17 billion.
-
According to Prediction Atlas data, there are currently 125 active prediction market platforms, with Kalshi and Polymarket accounting for 91% of all nominal trading volume.
-
There were 23 public financing rounds in Q2, raising a total of $1.288 billion. Kalshi raised $12 billion at a $22 billion valuation; by the end of June, the Financial Times reported it was negotiating a deal at a $40 billion valuation. ICE, the parent company of the New York Stock Exchange, has invested $2 billion in Polymarket, which only started charging fees in January this year and reached an annualized revenue run rate exceeding $1 billion by June.
Sports is driving this growth. 87% of Kalshi's June volume came from sports; 97% of Robinhood's open event contracts that month were related to the World Cup. The World Cup itself generated $17 billion in trading volume, with some estimates putting it at $20 billion. During the tournament, according to a Predicted report cited by Bloomberg, prediction markets accounted for roughly 27% of all US sports betting activity.
In the first half of June, Kalshi and Polymarket together accounted for 73.5% of new sports betting app downloads, while DraftKings had only 13.7% and FanDuel only 8.9%. During the World Cup, Kalshi added 3 million users, and at its peak, daily trading fees even exceeded $10 million.
These apps may operate differently from traditional sports betting platforms, but clearly, they are competing for the same users. The data proves it: according to Apptopia, Kalshi and Polymarket's daily active users surpassed those of DraftKings and FanDuel during the World Cup.
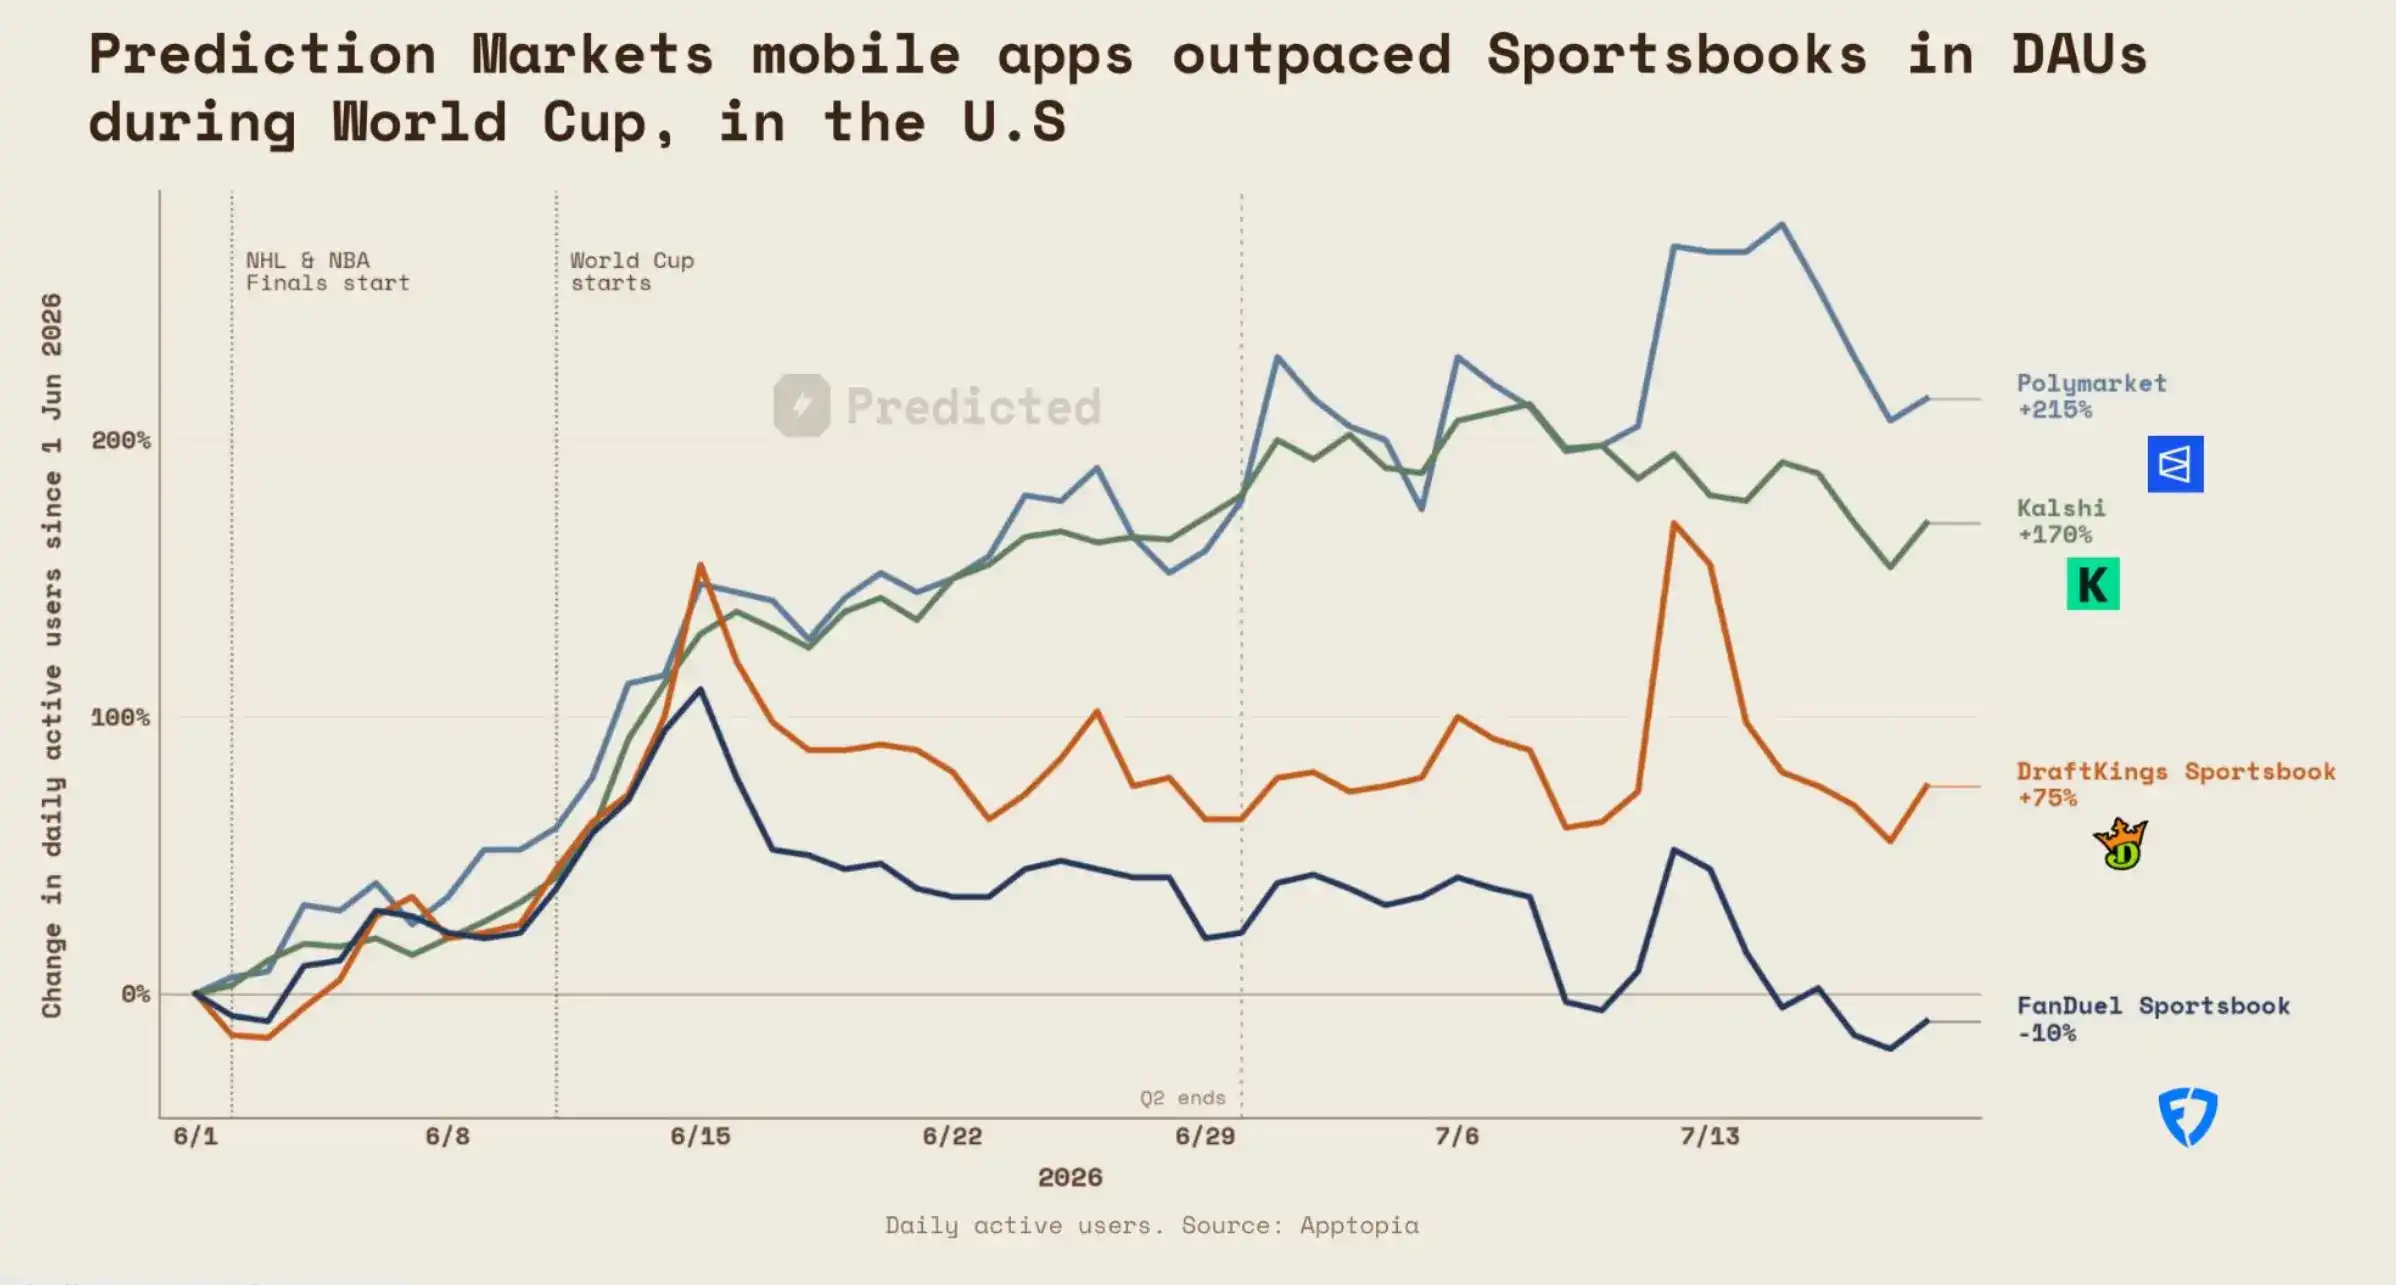
So, prediction markets aren't creating a whole new demand out of thin air; they are directly taking share from ordinary bettors, and they are winning. This naturally raises a question: are prediction markets just sports betting with a federal license?
Not exactly.
On traditional sports betting platforms, the platform is your counterparty. It sets the odds to guarantee its own profit, and if you win too much, it might even limit your account. When clients make money, the platform loses money, so these platforms need a large pool of users who lose slowly over the long term.
An exchange doesn't care who wins or loses. The market sets the price, another trader is on the other side, and the platform just makes money from trading activity. Betfair proved 25 years ago in the UK that the exchange model works. What's truly new today is the regulatory license, US dollar payment rails, and distribution power.
But "not caring who wins" creates another problem: those who end up making money are usually no longer the platform, but professional traders and market makers.
In May 2026, the Wall Street Journal analyzed 1.6 million Polymarket accounts and found that just 0.1% of accounts took 67% of all profits, while over 70% of accounts ended up losing money. These 0.1% of advantaged traders are the so-called "sharps," profiting from the casual bets of a large number of ordinary users.
Kalshi's own data also shows that for every profitable user, there are 2.9 losing users, though co-founder Luana Lopes Lara responded that even so, people's probability of making money in prediction markets is still higher than in sports betting or day trading.
So the situation is this: prediction markets are growing rapidly on the backs of ordinary bettors, ordinary users' money ultimately flows to professional players, and they receive less consumer protection than in comparable markets.
So why can we still say prediction markets are "better markets"?
2. The True Value of Prediction Markets Lies Beyond Just Predicting Outcomes
The strongest defense for prediction markets goes something like this.
Brian Quintenz's example about Fed rates is indeed startling, but remember, he now sits on Kalshi's board. So let's set him aside and look at other scenarios. You'll find that a vast number of events with real economic value can be given a price by prediction markets.
The financial sections of major prediction markets today already allow trading on oil prices, stock prices, Fed policy, election outcomes, inflation rates, even "the highest-grossing movie of 2026." If your business profits depend on any of these variables, the same logic as the Fed rate contract applies.
Moreover, these odds might be among the best probability estimates of outcomes we can currently get. Fed staff researched Kalshi's interest rate markets this year and published a paper titled "Kalshi and the Rise of Macro Markets." The study found Kalshi's predictions matched or even outperformed Fed funds futures and survey results from large professional forecasting firms; since 2022, before every single FOMC meeting, it has maintained a perfect record on "the most likely outcome."
Of course, this is just a Fed staff paper and does not represent the Fed's official stance. The authors also caution that market prices are not completely unbiased probability estimates, but the result is still quite remarkable.
Today, if you want to trade Fed decisions, you typically use Fed funds futures or instruments like TLT (the long-term Treasury ETF), but both carry basis risk. Public's COO Stephen Sikes explained it bluntly on the Tokenized podcast:
"I don't want to trade TLT because it has basis risk relative to the ultimate Fed decision. I just want to trade the Fed's decision directly."
That's what prediction markets do.
You can even use them to hedge very indirect risks. A bar in the Upper East Side of New York, The Jeffrey, once promised free drinks to customers if the Knicks won. To hedge the risk of this marketing campaign, the bar spent $5,000 buying "Knicks win" contracts; after the Knicks actually won, it got back about $8,000 from the contracts, exactly covering the cost of the drinks.
This bar faced a real risk, but no insurance company would design insurance for such a small, binary, and time-specific event. Prediction markets can. Even for basic business risks like foreign exchange, less than 10% of small businesses hedge, while the rate among Fortune 500 companies is 92%. Kalshi has formally submitted a corporate hedging program to the CFTC.
Exchanges can also price things that traditional betting platforms or other markets wouldn't touch. For example, an outcome that ultimately depends on a private, personal decision.
In July 2026, the market for "LeBron James' next team" saw cumulative trading volume exceeding $245 million across Kalshi and Polymarket. Traditional regulated betting platforms wouldn't open such markets at scale because no company can accurately model a person's private decision to build its own profit margin stably. But an exchange doesn't need to do that; the market finds the price. Of course, this time the market was wrong—LeBron ultimately went to Philadelphia.
Some prediction market hedges already look very close to insurance. La Liga team Osasuna paid a €1.2 million premium to buy roughly €6 million worth of relegation risk protection. Relegation is when a team finishes at the bottom of the league and drops to a lower division, losing substantial TV broadcast revenue.
This protection was designed by insurance broker Howden, reportedly executed through Kalshi, with quantitative trading firm Susquehanna as the counterparty on the other side. Osasuna ultimately stayed up, Susquehanna made over $1 million, and the hedge the team bought expired worthless. But that's exactly what should happen with insurance.
This trade also reveals an uncomfortable truth. Osasuna could execute this hedge because on the other side stood a highly specialized institution, Susquehanna; and Susquehanna was willing to be there largely because of the large volume of ordinary consumer trading.
Ordinary user volume is liquidity for hedgers.
This is precisely the core contradiction of the whole issue: we seem to have found a way to build a more efficient financial market by relying on less-than-professional consumers.
E-commerce companies can also use prediction markets to hedge inventory. One e-commerce company hedged inventory risk around a Latin American national team's World Cup performance; the trade was executed through a broker on Polymarket, sized in the hundreds of millions of dollars. The firm took the opposite side of its inventory risk, completing the hedge.
Dragonfly partner Rob Hadick said to me on the Tokenized podcast: "The institutional side possibilities are almost limitless."
Even future compute power prices can be priced by prediction markets. The demand for GPU from AI is currently immense; Meta, Microsoft, Alphabet, and Amazon plan to invest hundreds of billions in AI capital expenditure, a significant portion financed by debt. But without a reference price for future GPU earnings, lenders find it difficult to price credit based on GPUs.
So on July 14th, Kalshi launched a GPU rental price forward curve—the first public compute power forward price. In 2023, renting an H100 GPU cost over $8 per hour; according to the Ornn Index, it's now around $1.70. If your biggest input cost can drop 80% in three years and potentially spike again, you desperately need a forward price curve.
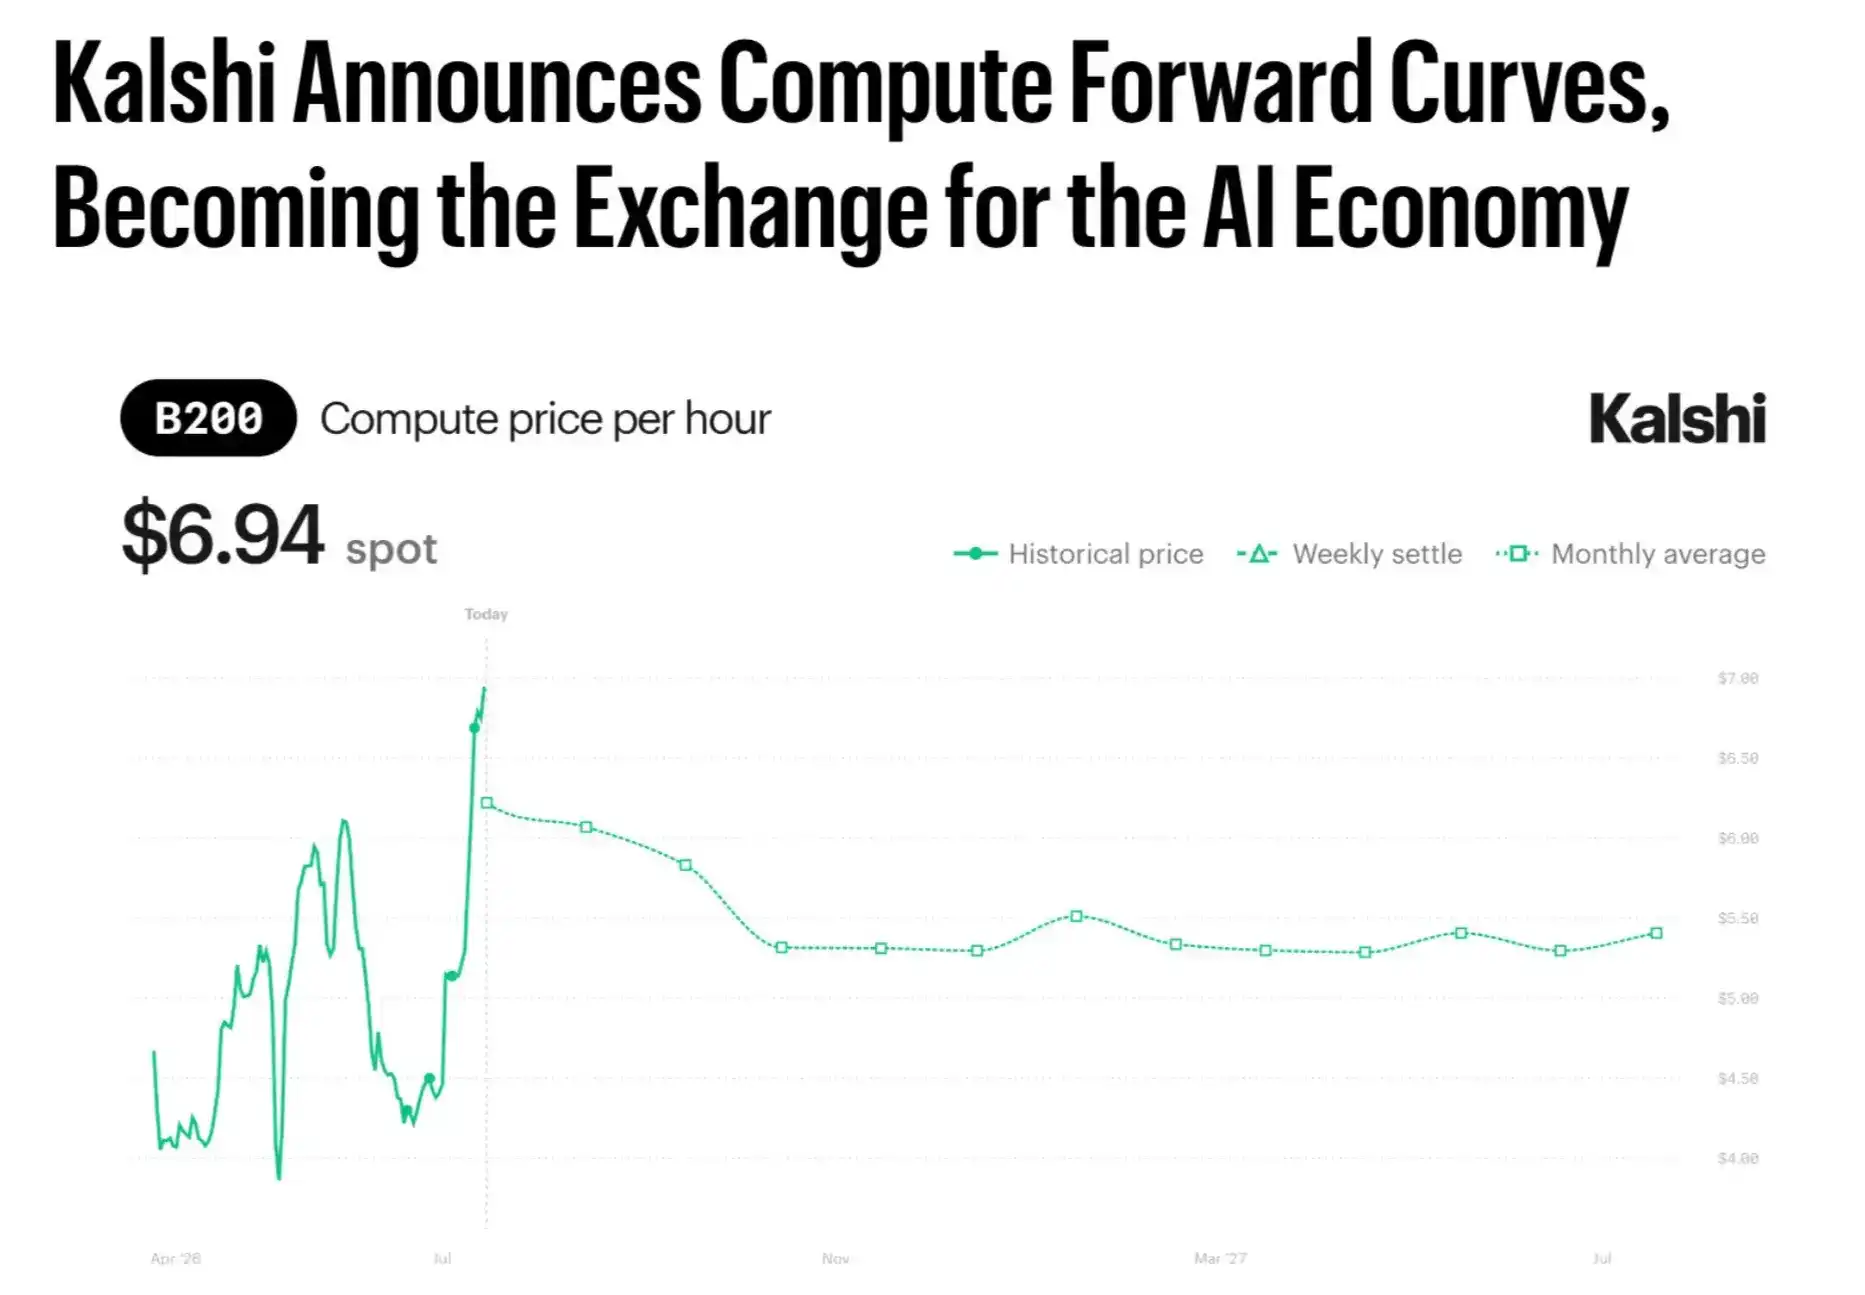
CME is developing compute futures, and ICE is working with Ornn on a cash-settled version, but both are still awaiting regulatory approval. Kalshi is already live because licensed exchange event contracts can be launched via "self-certification" (the exchange can self-certify that a new contract complies with regulations and launch it).
Today, lenders don't yet issue loans based on future expected GPU prices. But once that changes, prediction markets could redefine pricing in the entire debt capital markets almost without anyone noticing.
Of course, these applications are still at a very early stage. There's a long road from being a platform favored by sports bettors to truly becoming part of the future capital markets, and that road will inevitably be filled with legal and regulatory battles.
3. Who Really Regulates Prediction Markets?
Walk the same contract into three different buildings, and it becomes three completely different things. At the Cboe in Chicago, it's a binary option regulated by the SEC; at Kalshi, it's a swap contract regulated by the CFTC; and at some state's sports gaming regulator, it might be considered unlicensed sports betting.
Almost everyone is fighting over this legal ambiguity.
The CFTC's stance is very clear: event contracts are derivatives. The agency is currently suing nine states, seeking to stop them from shutting down prediction markets, and arguing that event contracts fall under the CFTC's exclusive regulatory authority. Since Michael Selig was confirmed as CFTC Chairman late last year, the agency has been strengthening its jurisdictional claims in this area.
The CFTC has also proposed a comprehensive new framework. Under this plan, broader sports contracts like "will a team advance" or "who will win a match" can exist because they serve price discovery functions; but contracts deemed "contrary to the public interest," such as betting on player injuries, referee decisions, or specific in-game events, would be prohibited.
In the past four months, the CFTC has issued over 500 pages of new regulations, hoping to quickly fill the gaps. It recently also explicitly opposed platforms using "American odds" display formats, which DraftKings and FanDuel have done. One can't help but wonder if they did it on purpose to get scolded by regulators.
But the states completely disagree with the CFTC's logic. In their view, these sports event contracts are essentially sports betting products.
Kalshi and Polymarket are already facing at least 20 actions from state regulators, Native American tribes, and individuals. Recently, 44 state attorneys general jointly wrote to the CFTC, arguing the agency has no authority to regulate sports event contracts.
Days later, the world's largest financial center joined the fray. The New York State Attorney General sued Kalshi in Manhattan state court, seeking damages potentially as high as $36 billion. One of the allegations is that Kalshi allowed 18- to 20-year-olds to participate in sports event trading on the platform. New York AG Letitia James's position is direct: prediction markets like Kalshi are betting platforms, "plain and simple."
Traditional exchanges and sports leagues want stricter regulatory boundaries. CME's general counsel wrote to the CFTC, saying its definition of "gaming contracts" is an "astonishing overreach" that effectively usurps state regulation of sports betting. The NFL also urged the CFTC to tighten rules, arguing the current framework doesn't sufficiently protect game integrity and consumers.
Then there's another thornier issue: insider trading.
As I wrote in "The Everywhere Insider" this past April: we created prediction markets to find truth, only to later discover that those who profit most are often precisely those who know the truth in advance.
In April 2026, federal prosecutors charged an Army Special Forces sergeant with using classified intelligence about Venezuela operations to bet on Polymarket on Maduro's arrest, profiting about $400,000. In May, a Google engineer was charged with using internal data to bet on search trends, making $1.2 million.
In July, Kalshi's own surveillance systems found a White House teleprompter operator betting on whether Trump would say certain specific words in speeches, while he himself had access to the speech drafts. Kalshi subsequently froze over $90,000 in his account. Three political candidates have settled with Kalshi for betting on their own election outcomes.
Platforms are starting to take action. They're introducing professional monitoring services, requiring employees to disclose occupation information, and actually enforcing against violators. At least on the insider trading issue, control mechanisms seem to be starting to work, and those caught pay a high price.
So finally, the issue can only be left to the courts, and the answers from courts so far are a mess. In April this year, the US Third Circuit Court of Appeals gave Kalshi its first federal appellate-level victory, ruling 2-1 that sports event contracts are swap contracts and thus subject to exclusive CFTC regulation.
But at the district court level, Kalshi's arguments based on the Commodity Exchange Act have already lost in New York, Maryland, Nevada, Michigan, Massachusetts, Utah, and Washington, while winning in Arizona and Tennessee, with multiple cases still pending. Minnesota even made trading sports event contracts a felony starting August 1st, though a federal judge has temporarily blocked that ban.
These cases continue to be appealed, and at least one is likely to end up in the US Supreme Court.
The states' motivations, of course, aren't entirely about protecting consumers either. In 2025, US state regulators and local governments received a record $18.09 billion in direct tax revenue from commercial sports betting and related industries. If trading volume that would have been sports betting moves to federally regulated prediction exchanges, that money doesn't go into state coffers.
The "self-certification" mechanism allows prediction markets to launch new contracts quickly but also creates huge ambiguity. Essentially, Kalshi or Polymarket can launch a contract first, and regulators review it afterward. That's why Kalshi could already launch compute forward contracts while CME and ICE are still in line waiting.
From a risk appetite perspective, this is actually very similar to Uber's playbook back in the day.
If you run a prediction market, your situation is this: courts won't resolve the issue for years; today's regulators are friendly, but no one knows what will happen in two years; and every quarter you grow, your bargaining chip in future regulatory negotiations gets bigger. So rationally, the best strategy is to keep going, keep grabbing market share, keep fighting the legal battles.
But in this regulatory fog of war, who is truly on the consumer's side? Everyone says they are, but are they really?
4. The Faster the Growth, the More Prominent the Consumer Protection Problem
If prediction markets end up just creating a more efficient way for people with gambling problems to lose money, then we've completely failed, because the current data on problematic gambling isn't pretty.
After sports betting legalization, the number of people seeking addiction help grew 61%, according to University of California San Diego researchers. According to Bloomberg, since the start of this year, Kalshi users have net lost $294 million through trading methods similar to "parlays"; in July this year, such contracts accounted for 36% of all contract volume on Kalshi. During the World Cup final, a very popular parlay had an implied probability of success of just 2.7% at kickoff.
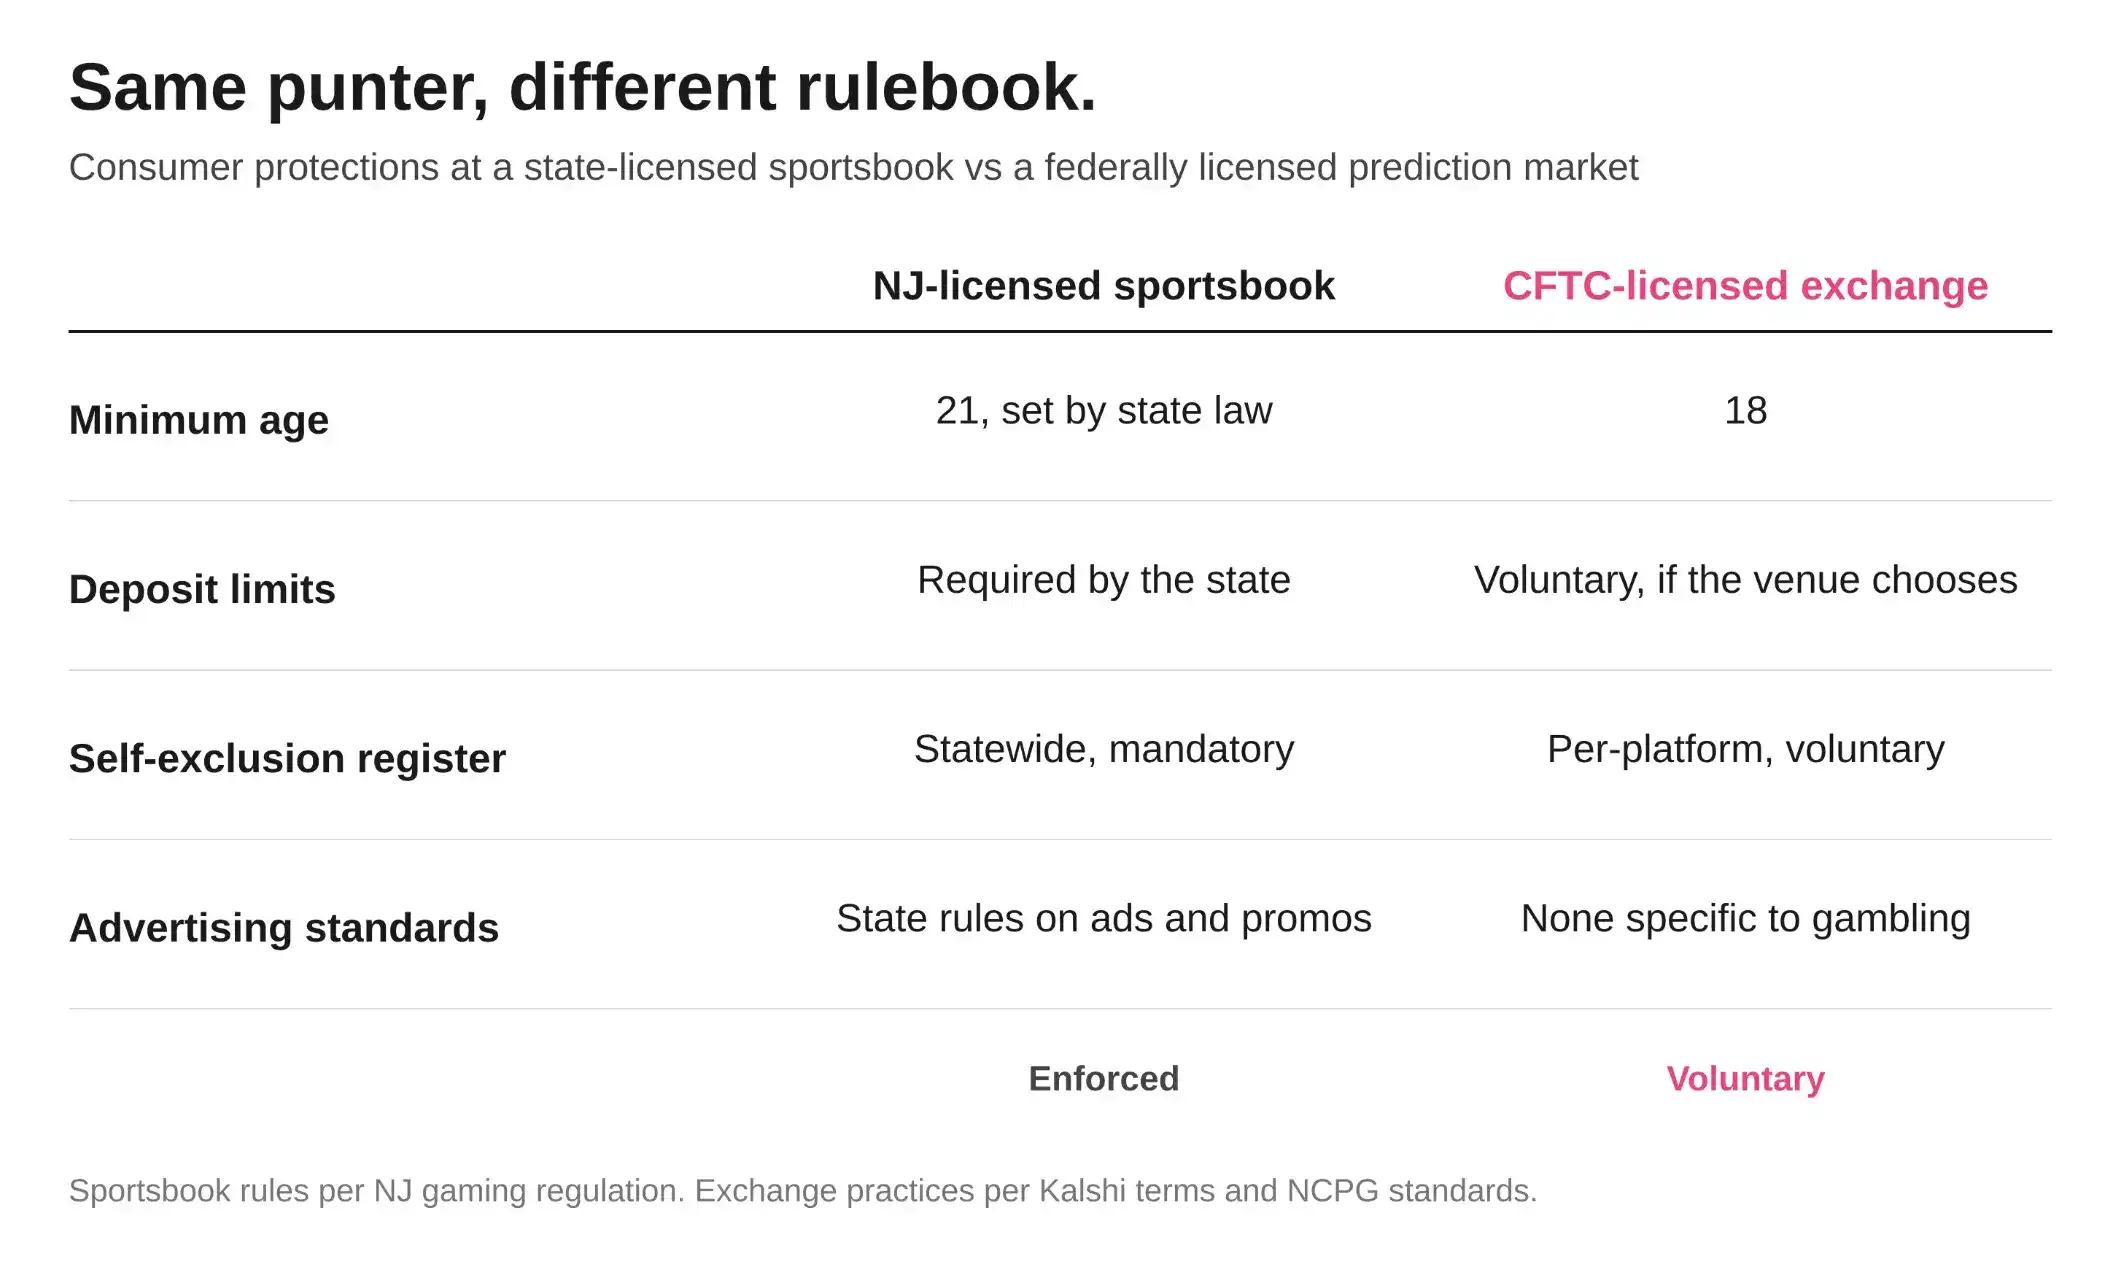
Kalshi allows 18-year-olds to open accounts. The National Council on Problem Gambling has called on prediction platforms to raise the minimum age to 21 and prominently display helpline information. The New York lawsuit alleges that 18- to 20-year-olds are currently trading on Kalshi. Kalshi itself admits that the majority of its users end up losing money.
What's more troublesome is that these platforms are marketing products almost exactly like traditional sports betting, even directly promoting parlays (combining multiple game outcomes into one bet, all must win to profit).
No one buys parlays for price discovery or risk hedging. A parlay is essentially a prettily packaged, high-risk betting slip. There's a reason it's one of the highest-margin products in the traditional sports betting industry: according to state data, per dollar wagered, the average single-game bettor loses 6 cents, while the average parlay bettor loses 19 cents.
Then there's the ubiquitous advertising. The Wall Street Journal and Politico found that Polymarket once created a "clone website" almost identical to its official site, using a capital I to replace a lowercase l in the URL, then gave it to college-age content creators to record videos of themselves "making a killing" on simulated bets. Had those trades occurred in the real market, over half would have lost money.
To be fair, Kalshi has introduced features like self-exclusion, deposit limits, and mental health support. The problem is, these are platform-specific product choices, not legal requirements.
A traditional sports betting platform operating in New Jersey must provide similar protections because the state mandates it. User age must be 21, and advertising is explicitly restricted. But a prediction market that can operate nationwide currently provides as much protection as it's willing to implement itself.
The reason is simple: the CFTC's regulatory rules were written for wheat farmers and swap trading desks. They weren't written for the average user doing World Cup parlays on their phone at 2 a.m.
Public's COO Stephen Sikes told me they completely agree with the "prediction markets are better markets" logic. Public is also preparing to launch prediction markets, but they won't touch sports:
"High-risk gambling shouldn't be in an investment account. We won't do those products."
I deeply respect that decision, but I also know what this choice costs. Speculative trading products like crypto, and now prediction markets, are the top of the funnel for customer acquisition at companies like Robinhood. Robinhood has 28.4 million funded accounts, while Public recently disclosed member numbers over 3 million—about one-tenth of Robinhood's.
Many users come to the platform for speculation, but some of them eventually stay and start using longer-term investment products.
The question then becomes: if a business choosing to "do the right thing" means giving up its strongest growth engine to competitors unwilling to self-limit, how many boards of directors will actually choose the right thing?
It's hard to expect these companies to restrain themselves. For them, the most rational business choice is still to charge ahead.
And when everyone is fighting, the ones who ultimately lose are often ordinary people.
5. How to Make Prediction Markets Better Markets?
Prediction markets are indeed better markets, but they don't yet offer better consumer protection.
I don't think the solution is to ban prediction markets. The data value here is too great, and there are too many real hedging uses; a blanket ban would just push ordinary users offshore to platforms with even weaker consumer protections.
But I think at least four things can be done:
-
Build protection mechanisms directly into the market. Implement cooling-off periods; set position limits based on verified income levels; assess affordability before users make large trades; reward prediction quality, not bet size. I suggested something similar last October. These measures won't destroy the market. The gaming industry understood years ago that "friction" in products can sometimes be part of the feature. Of course, the problem is, once you start adding these consumer protections, a so-called "market" starts looking more and more like a gaming product, but it's still a positive step.
-
Make risk warnings match the product's actual behavior. If the National Council on Problem Gambling thinks the minimum age should be 21 and pages should display helpline info, then at least for sports and parlay products, risk disclosures, age restrictions, and advertising norms should resemble those of sports betting platforms, not securities brokerage accounts. Also, could we stop the insane push of parlay ads? At least add more risk disclosures.
-
Create a path from bettor to investment portfolio. Robinhood already has all the needed products: Gold has 4.8 million subscribers, it offers retirement account subsidies, and net deposits hit a new record. Since platforms can attract users with speculation, the same machinery could theoretically also gradually lead them toward saving and long-term investing. There's already evidence that some prediction market users eventually build long-term portfolios, though it's thin. So, thicken the evidence, measure it, publish the data, and put it in the earnings report alongside parlay revenue.
-
Carve out sports event contracts and pair them with consumer protection. There is genuine hedging demand in sports, but it's very niche. The vast majority of sports event contracts are essentially competing with traditional sports betting products. So why not separately tax sports-related activities and establish uniform position limits and consumer protections, instead of continuing to rely entirely on voluntary platform implementation?
If turning "speculative impulses into financial health" sounds too naive, look at what Britain did 70 years ago. They not only did it, but did it consciously on a national scale.
6. Putting a Lottery Mechanism Into a Savings Account
In April 1956, Britain faced two problems simultaneously: inflation and insufficient savings.
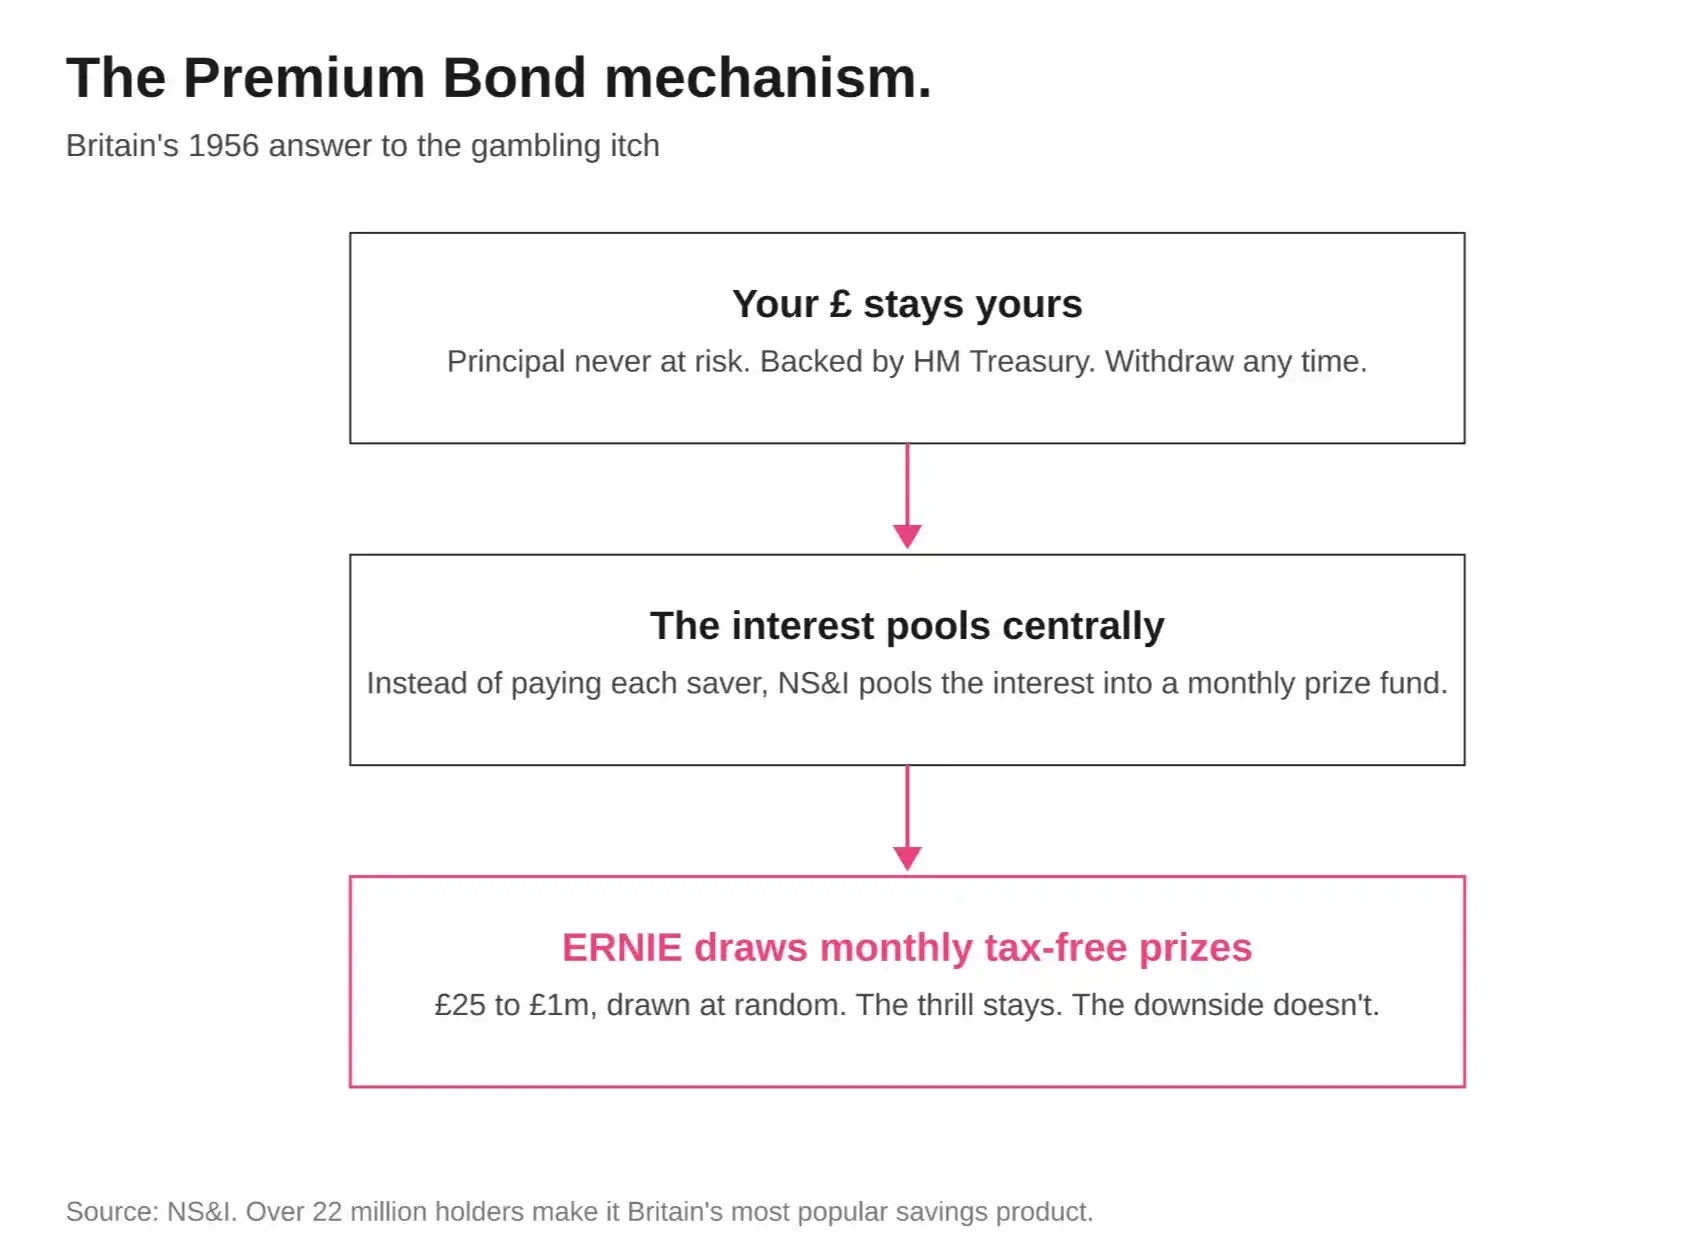
Chancellor of the Exchequer Harold Macmillan wanted to absorb more funds from circulation, but simply raising interest rates wasn't enough to attract ordinary people to save. So on Budget Day, he announced Premium Bonds.
Your principal isn't at risk, but instead of paying you a fixed interest, the government pools everyone's interest and distributes tax-free prizes via a monthly draw. The draws were run by a machine called ERNIE, designed by an engineer who had worked at Bletchley Park on code-breaking.
The opposition called it a "squalid little lottery." It was a brilliant phrase, but the public didn't care. On the first day, Brits bought £5 million worth of Premium Bonds.
Seventy years later, Premium Bonds are the UK's most popular savings product, held by over 22 million people. A single monthly draw now distributes around £447 million, or about $590 million, in tax-free prizes.
If we're destined to live in an era of increasingly prevalent speculation, we can at least try to ensure that impulse doesn't ruin people's lives.
The US actually legalized its own version back in 2014—"prize-linked savings"—but hardly anyone has scaled it. In a year where US inflation once reached 4.2% and nearly every household felt price pressure, turning speculative urges into savings isn't some nostalgic old idea; the solution has been sitting there all along.
That event contract at the beginning of the article, the one that could make 13 times, is also pricing the same question in real time: inflation. Quintenz's so-called "hedging opportunity" is observing the very number Macmillan was desperately trying to address in 1956.
A Disappointed Father of Prediction Markets
I can't help but see the potential in things.
The crypto industry is slowly growing up; stablecoins emerged, tokenization emerged. But now, I have another prodigiously talented, yet also troublesome, problem child: prediction markets.
In my entire career, including digital assets, I've never seen a market product with as much potential as prediction markets. But now, the stalemate between US states, the CFTC, and prediction market platforms isn't addressing what we truly care about: consumer protection.
Last October, I wrote that we probably had about 18 to 24 months to build sufficient protective mechanisms. Otherwise, once the backlash comes, regulators might impose overly harsh rules that ultimately destroy the truly valuable parts of prediction markets along with the rest.
Ten months have passed. New York State has filed a lawsuit seeking up to $36 billion; 44 state attorneys general want to overturn the CFTC's regulatory logic. The backlash came earlier than I imagined, and the US midterm elections haven't even started yet.
Prediction markets are better markets, but for the vast majority of ordinary people, they're currently no more friendly than other high-risk gambling products.
I do believe this will eventually change.
Those companies that can survive and grow today while genuinely steering their products toward healthier directions are actually preparing for the next era. That era might only arrive after something truly breaks and courts finally issue definitive rulings.
I just hope that exchanges, state governments, and regulators wake up a bit earlier and decide to do things a little better.
After all, tomorrow is another day.