A decimal point difference could directly determine whether the Fed raises rates next week: a month-on-month Core CPI of 0.2% implies a hold, while 0.3% triggers a hike. The Fed is visibly split, with bond markets, the dollar, yen, and equity markets all on high alert. Goldman Sachs warns that if the data is moderate and the Fed chooses to hold, bond market concern over a "policy error" will far outweigh the damage from hiking in the face of above-target inflation. The August CPI report released tonight will be one of the most nerve-wracking inflation data releases in recent years. A difference of a single decimal point is enough to decide whether the Fed initiates another rate hike in this cycle next week—a gamble that has top Wall Street economists now calculating to the third decimal place.
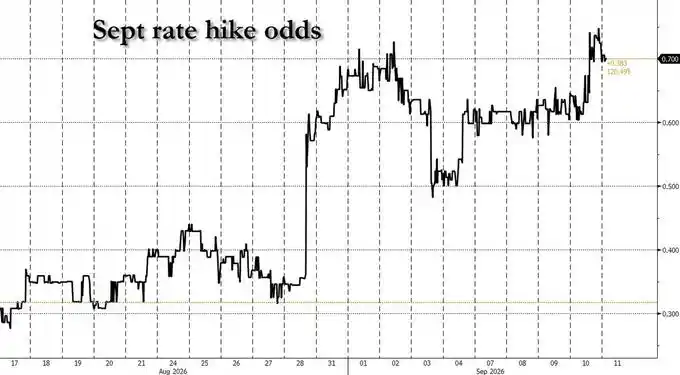
The money market currently prices the probability of a 25-basis-point rate hike at the September 16 FOMC meeting at around 70%. Last week's strong non-farm payroll data and escalating Middle East geopolitical tensions have jointly pushed hawkish expectations higher. Fed Governor Waller previously provided the clearest policy reaction function to date: if the August inflation data shows the disinflation process continuing, he favors keeping rates unchanged; if the data is hot, he would support a hike. Fed Chairman Warsh, meanwhile, stated at the Jackson Hole conference that the policy job is not done unless inflation is moving toward the 2% target at a sufficient pace.
Mainstream Wall Street predictions cluster around a month-on-month Core CPI of 0.2%, but this is precisely the outcome most difficult for the market to price. According to J.P. Morgan's Market Intelligence team analysis, 0.2% (rounded) implies a hold, while 0.3% implies a hike. Anna Wong, Chief U.S. Economist at Bloomberg, said her team is forecasting PCE inflation to the thousandths to gauge the policy implications of this "one of the most watched CPI reports in history." Tonight's data will directly reshape market pricing for the September, October, and even December rate paths.
Institution Forecasts: Core CPI Landing Around 0.2%
Predictions for August Core CPI from major Wall Street institutions are highly concentrated, but subtle differences are crucial.
J.P. Morgan forecasts August Core CPI month-on-month increase at 0.21%, annualizing to about 2.37%, barely holding at 2.4% after rounding. For Core PCE, J.P. Morgan expects a month-on-month rise of 0.20%, and 3.2% year-on-year. The bank also notes that 13 of the last 17 CPI prints have missed expectations, with the current inflation surprise index in the weakest 10% range in nearly a decade, thus maintaining a below-consensus forecast and continuing to hold short positions.
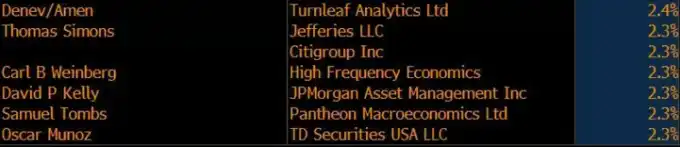
Bank of America Securities predicts Core CPI month-on-month up 0.22%, Core PCE up 0.24%, annualizing to about 2.9%, with the year-on-year figure expected to rise to 3.4%. BofA economist Stephen Juneau believes this outcome would not be enough for the Fed to relax about the inflation trend and would be sufficient to support another FOMC rate hike in September.
Goldman Sachs predicts Core CPI month-on-month growth of 0.22%, expecting this to translate into a 0.22% month-on-month rise for Core PCE. Goldman particularly highlights three key components: used car prices expected to rise 0.5%; Owners' Equivalent Rent (OER) and rent components to rise modestly by 0.22% and 0.23% respectively; airline fares expected to jump 4.0%, reflecting ongoing pass-through of jet fuel costs.
Citi's forecast is more dovish, expecting Core CPI month-on-month up 0.18%, Core PCE up 0.19%, and believes this result would support the Fed holding steady in September.
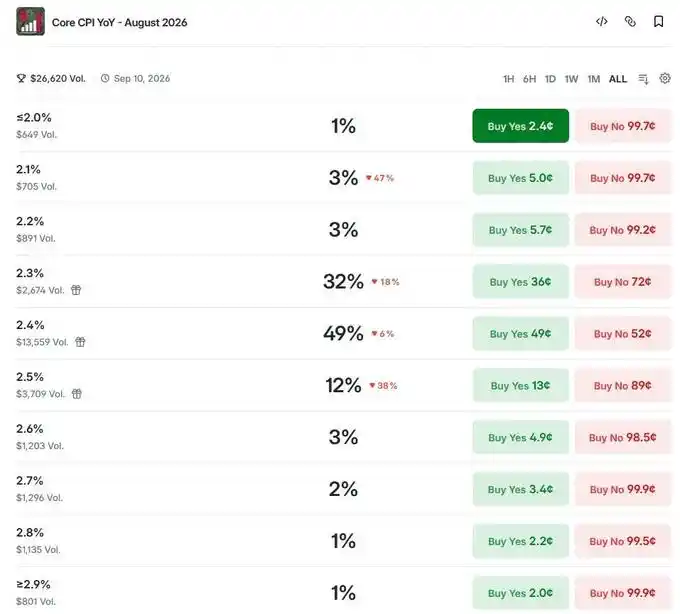
The Polymarket prediction market shows a median economist forecast of 2.4% year-on-year, with the market pricing the probability of a miss (2.3% and below) significantly higher than a beat (2.5% and above).
Warsh vs. Waller: Two Signals, One Game
Divergence within the Fed makes interpreting this CPI data even more complex.
Chairman Warsh's Jackson Hole speech leaned hawkish, explicitly stating that unless core inflation is clearly converging toward the 2% target at a sufficient pace, the Fed has more work to do. This wording was interpreted by the market as having an extremely low tolerance for inflation.
Waller's remarks were relatively moderate, forming a clear hedge. He said he is seeing signs of cooling inflation, with significant improvement in three-month core inflation, and if the August data continues the cooling trend, he supports a hold in September.
His specific reference point was: if the three-month annualized core inflation rate falls to 2.8%, "that is acceptable." But he also retained the stance of supporting a hike if the data is hot. Waller also downplayed the inflationary pull from energy prices and tariffs, believes wage growth is consistent with the path back to target, and suggested Core PCE may not be the best gauge of inflation trends, arguing that underlying inflation is actually "performing better" than what the core data shows.
Goldman's FICC co-head Anshul Sehgal described the signals from Warsh and Waller as "two very different reads," believing whether this cycle needs a hike is still undecided and depends largely on energy price moves and geopolitical developments. His view is: This cycle is unlikely to see more than three hikes; the 1-year 1-year forward rate priced at 435 bps implies about two and a half hikes, which "sounds about right."
Bond & Rate Markets: 0.25% is the Critical Line Between Hike and Hold
Rate traders have focused their gaze on the precise decimal of Core CPI.
Scenario analysis by BofA rates strategist Meghan Swiber shows: if Core CPI month-on-month is 0.1%, the 2-year Treasury yield could fall 10 to 5 bps; if 0.2%, volatility around ±5 bps; if 0.3%, the yield would rise 5 to 8 bps. She specifically notes that a rally on soft data would be larger than a sell-off on hot data—because hike expectations are already fairly priced, and the market overall holds many short positions.
Goldman's macro trading desk's Brian Bingham points out that the Fed is in its "most contradictory position," possibly deciding policy based on the rounding of government data. He also worries that if data is moderate and the Fed holds, bond market concern over a "policy error" will far outweigh the damage from hiking in the face of above-target inflation.
Historical data from Bank of America Securities shows that 90% of the Fed's hawkish surprise actions occurred when the market had priced in 3 bps or less two days before the meeting, meaning if pricing is too high then, the Fed actually not hiking could become the bigger surprise.
FX Market: Dollar at Lows, Data May Intensify Two-Way Volatility
The dollar enters this critical report with weakness near four-month lows.
Goldman's head of FX strategy, Mike Cahill, believes if data is hot (month-on-month around 0.25%) and broad-based enough, the Fed will find it hard to avoid a hike, as it would breach the range outlined by Williams and Waller. If data is soft (0.18% to 0.20%), the Fed could easily hold without triggering adverse market reactions. He attributes recent dollar weakness to three factors: a dovish Fed tilt, the Treasury's policy preference for the exchange rate to bear adjustment, and independent strengthening of currencies like the Chinese yuan, Japanese yen, and Korean won.
Bank of America FX strategist Alex Cohen points out that under the market consensus scenario (Core CPI month-on-month 0.2%), the dollar will exhibit two-way volatility, as whether September sees a hike would remain uncertain. If data is soft, the dollar's decline would be greater than its rise on hot data, with the DXY's decline estimated at a minimum of 0.5% to 0.75%, and expectations for October and December hikes would also recede significantly. If data is hot, the hike probability would move toward 90%, the dollar would initially rally, but if the Fed subsequently fails to follow through, further damage to dollar credibility would deepen, and the dollar could weaken in tandem with long-end Treasuries.
Regarding the yen, after USD/JPY recently broke below the 155 range, Goldman's G10 spot desk's Luke Molyneux believes that if data meets expectations supporting a hold, USD/JPY could extend its decline, targeting the 152.10 low area; if data is hot, it could briefly rebound to the 157.50-158.00 range but would still be seen as a selling opportunity.
Equities & Risk Assets: Upside Bias, But Volatility to Persist
In the equity market, J.P. Morgan's market strategy team sees the risk-reward ratio overall skewed to the upside.
If data supports a hold or a "hawkish hold," tech, momentum, and cyclical sectors are expected to be the main drivers of a rebound. J.P. Morgan positioning tracking data shows hedge funds have increased overall exposure for four consecutive trading days over the past week, with the weekly net increase reaching its highest level since late June (+1.3 standard deviations). Re-leveraging capacity remains ample, constituting a potential upside catalyst.
But J.P. Morgan also notes that market moves will remain choppy ahead of the data release, which is the direct reason the bank recently adjusted its short-term rating to "tactical neutral." The options market currently implies a roughly 1.0% one-day move for contracts expiring on September 11.
The biggest tail risk lies in core inflation significantly exceeding expectations. Should that happen, rate hike expectations for October and December, currently around 27% and 54% respectively, would be rapidly repriced, putting substantive pressure on equities.
A Number's Paradox: Precision to Three Decimal Places
Another deeper implication of this report is an extreme stress test of the "data-dependent" monetary policy itself.
Bloomberg's Chief U.S. Economist Anna Wong writes that her team is projecting Core PCE to three decimal places to judge which side this hike decision leans. This was cited by FX trader Brent Donnelly, creating a thought-provoking contrast with a prior statement by Warsh himself—Warsh criticized the "data-dependent" policy as having limited value in a 2025 speech, arguing that excessive focus on the second decimal place of government data was a manifestation of "false precision and analytical laziness."
Yet, as Donnelly points out, "We are now in that very situation." Tonight's number may become the most delicate game between Fed policy credibility and market expectations.