Original | Odaily Planet Daily(@OdailyChina)
Author|jk
On the evening of August 6, Unitree Technology announced its STAR Market issue price at 150.80 yuan per share, corresponding to an issuance market capitalization of 60.993 billion yuan. On the day of online subscription, August 10, 9.78 million retail investors rushed in, with the preliminary effective subscription multiple reaching 8288.82 times, setting a new historical low for the lottery winning rate on the STAR Market. On the Hyperliquid perpetual contract platform, Unitree's pre-market quote once surged to 90 dollars, which translates to a market cap of over 240 billion yuan, four times its 60.993 billion yuan issuance market cap. These numbers together paint a picture of a near-nationwide frenzy for the new share subscription. But behind the frenzy, more and more voices are starting to question whether this price has already priced in too much imagination.
Odaily Planet Daily today takes you through the five reasons to short behind the euphoria.
1. P/E Ratio Far Exceeds Industry Levels
Unitree Technology announced its issue price on August 6 at 150.80 yuan per share, corresponding to an issuance market cap of approximately 60.99 billion yuan. What truly made the market gasp was its underlying P/E ratio: 219.23 times. For comparison, the average static P/E ratio for the general equipment manufacturing industry released by the China Securities Index over the recent month is only around 38.56 times. Unitree's pricing is about 5.7 times the industry average.
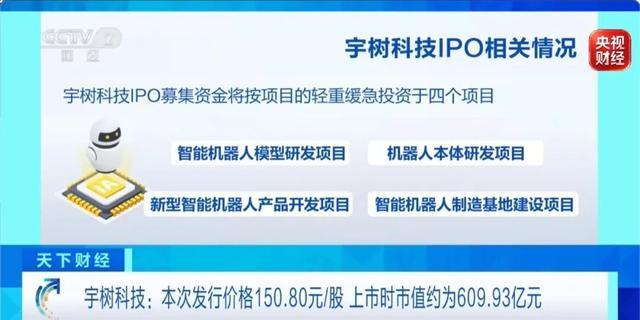
CCTV's report on Unitree. Source: CCTV
Some investors have already jokingly called this P/E ratio the "dream P/E ratio," meaning that at this price, you're not buying current profitability, but a distant dream.
2. Off-Market Quotes Are Even More Absurd Than the Issue Price
On overseas secondary market platforms like Hiive, Unitree's quote reached as high as 61.63 dollars per share during August 10-11. Based on this conversion, the overall valuation was close to 22.4 billion dollars, more than double the valuation corresponding to the issue price.
On Hyperliquid, the situation was even more extreme. Data as of the time of writing shows that the pre-market perpetual contract UNITREE-USDC for Unitree Technology once quoted around 90 dollars. Based on a total of 404 million shares, this corresponds to a market cap of approximately 35.47 billion dollars, or about 239 billion yuan, nearly four times the 60.993 billion yuan issuance market cap.
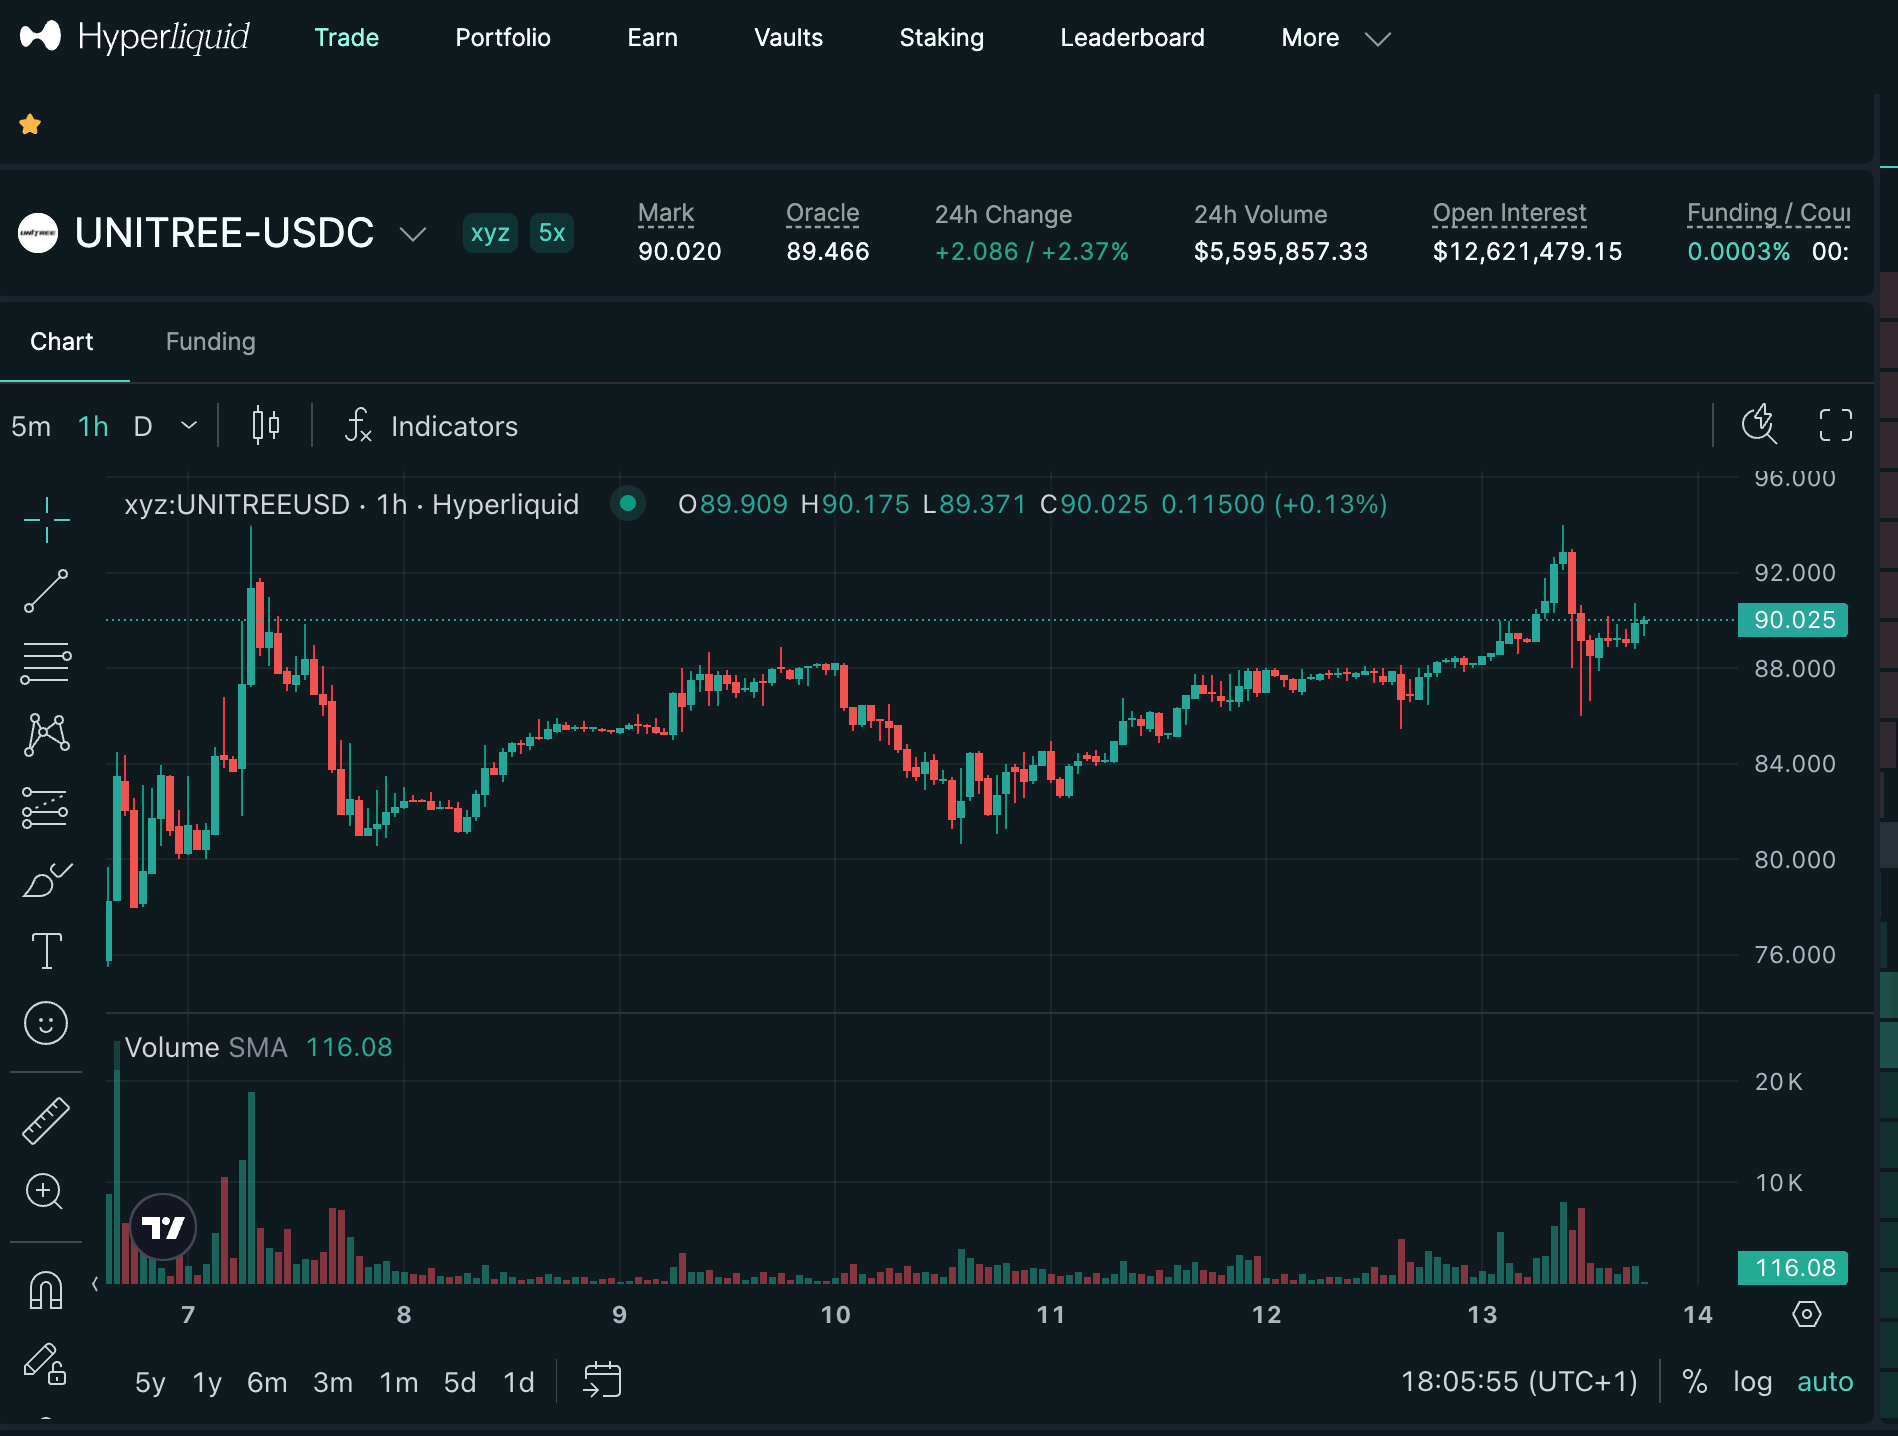
Unitree's pre-market quote on Hyperliquid. Source: Hyperliquid
But the sentiment it reflects is real: the market has priced an extreme amount of imagination into Unitree.
3. Only 3% of Robot Sales Are Actually for Industrialization
The narrative supporting this valuation is the story of humanoid robots entering factories on a large scale and replacing human labor. But opening Unitree's own prospectus reveals that this story is still just a story for now.
In the first nine months of 2025, 73.6% of Unitree's humanoid robot revenue came from scientific research and education scenarios, 17.4% from commercial exhibitions and performances. The revenue share from actual industrial application was only 9.01%. And within this 9%, revenue from actual work scenarios like manufacturing, inspection, and logistics was less than 3%, only 15.70 million yuan in the first nine months, with the majority of the remainder still being for corporate visit reception.
36Kr raised a pointed question in the article "Humanoid Robots: Not Yet 'Creating Prosperity,' But Already 'Creating Wealth'": "Does Unitree making money necessarily mean humanoid robots will definitely make money?" and provided specific data to support this doubt.
In the first nine months of 2025, scientific research and education accounted for 73.60% of humanoid robot business revenue, commercial consumption 17.39%, and industry application only 9.01%. And within this 9.01%, corporate tours accounted for 70%. Revenue actually used in defined industrial scenarios like intelligent manufacturing, intelligent inspection only amounted to 15.702 million yuan, accounting for 29.29% of industry application revenue.
The source of this data is actually Unitree's own written reply to the Shanghai Stock Exchange's second round of inquiry letter:
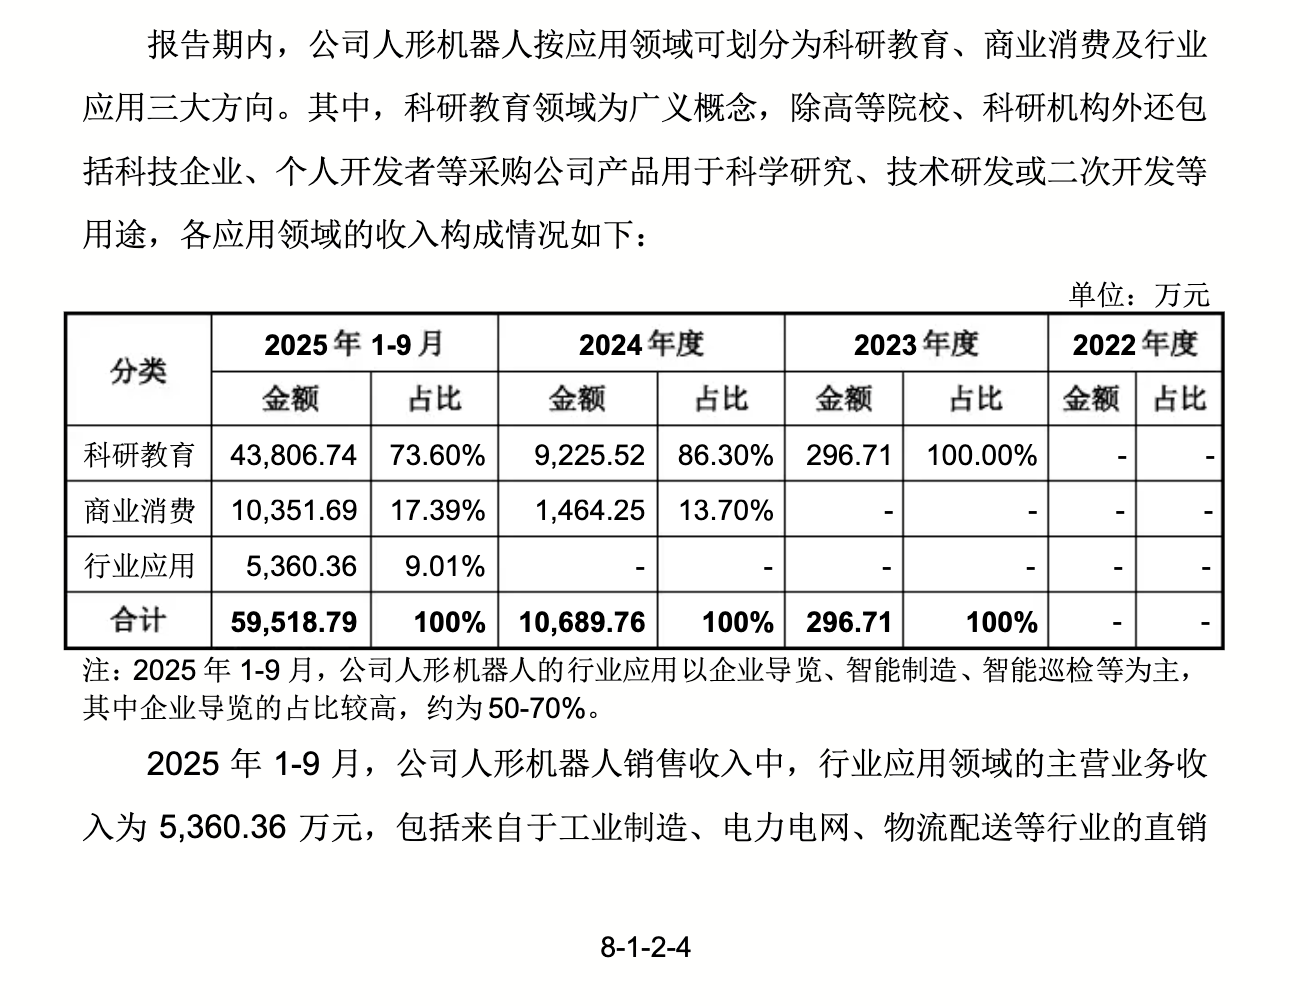
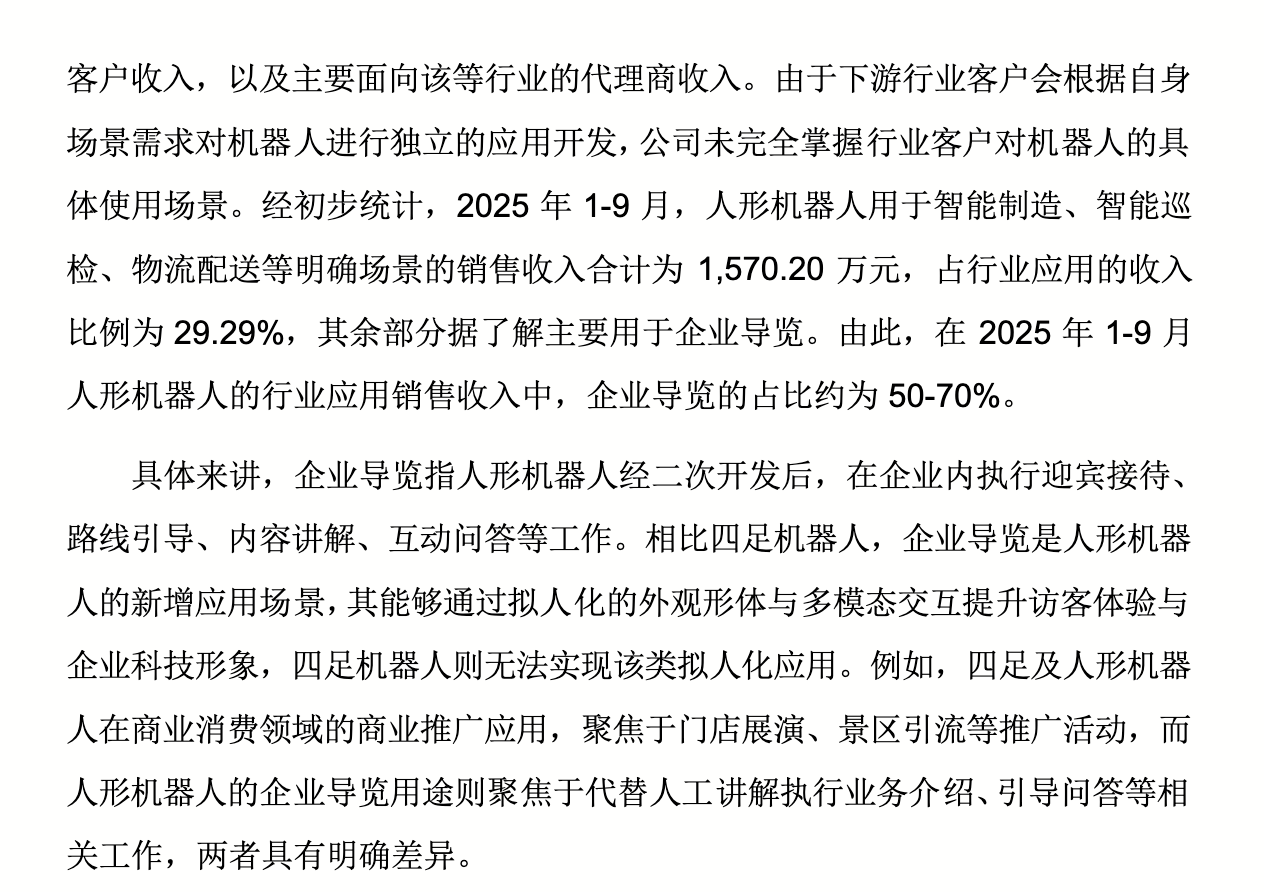
Unitree Technology's Reply Letter. Source: Shanghai Stock Exchange
In simple terms, the biggest buyers of humanoid robots currently are universities, research institutions, and tech companies, who buy robots for algorithm research, model training, teaching experiments. The demand in the research and education market is limited and could very quickly hit a ceiling.
And within this 9.01% industry application revenue, the portion corresponding to defined industrial scenarios like intelligent manufacturing, intelligent inspection, and logistics distribution is 15.702 million yuan, accounting for 29.29%. The remaining approximately 70%, according to the company's own statement, is "understood to be mainly used for corporate tours." So-called corporate tours refer to humanoid robots, after secondary development, performing tasks like reception, route guidance, content explanation, and interactive Q&A within companies, essentially being talking, walking exhibition pieces.
If you multiply the 9.01% industry application share by the roughly 70% corporate tours share, then a significant portion of revenue counted under the "industry application" statistic—which sounds like industrial deployment—is actually front desk reception and exhibition hall explanations, quite different from the imagined scenario of robots screwing screws or moving goods in factories.
Revenue that truly corresponds to intelligent manufacturing, intelligent inspection, and logistics distribution accounts for less than 3% of the company's total humanoid robot revenue.
The article also mentions that while competitor Ubtech's humanoid robots have frequently won large orders, its cumulative losses from 2020 to the first half of 2025 exceeded 5 billion yuan, and it has not yet turned a profit. For comparison, even with impressive orders, it doesn't mean the business is all set. Another analysis article on IPO subscriptions directly pointed out that scientific research and education is a good business, but it cannot support the premium in the 60.1 billion market cap related to "general-purpose robots entering every household." That part of the premium requires industrial scenarios and consumer markets to take over, and both are currently still in the pilot stage.
4. Slowing Profit Growth, Deteriorating Profit Quality
In the first quarter of this year, Unitree's revenue was 423 million yuan, a year-on-year increase of 68.49%, seemingly still strong. But compared to the 332.64% growth in Q1 2025, this is a cliff-like drop. Q1 non-GAAP net profit fell from 84.8365 million yuan in the same period last year to 40.2536 million yuan, a year-on-year decline of 52.55%, directly halved. The company's explanation is that R&D expenses increased year-on-year by a net 38.328 million yuan, mainly directed towards embodied AI large models, motion control algorithms, and body structure R&D, while intensive brand promotion on platforms like the CCTV Spring Festival Gala pushed up sales expenses.
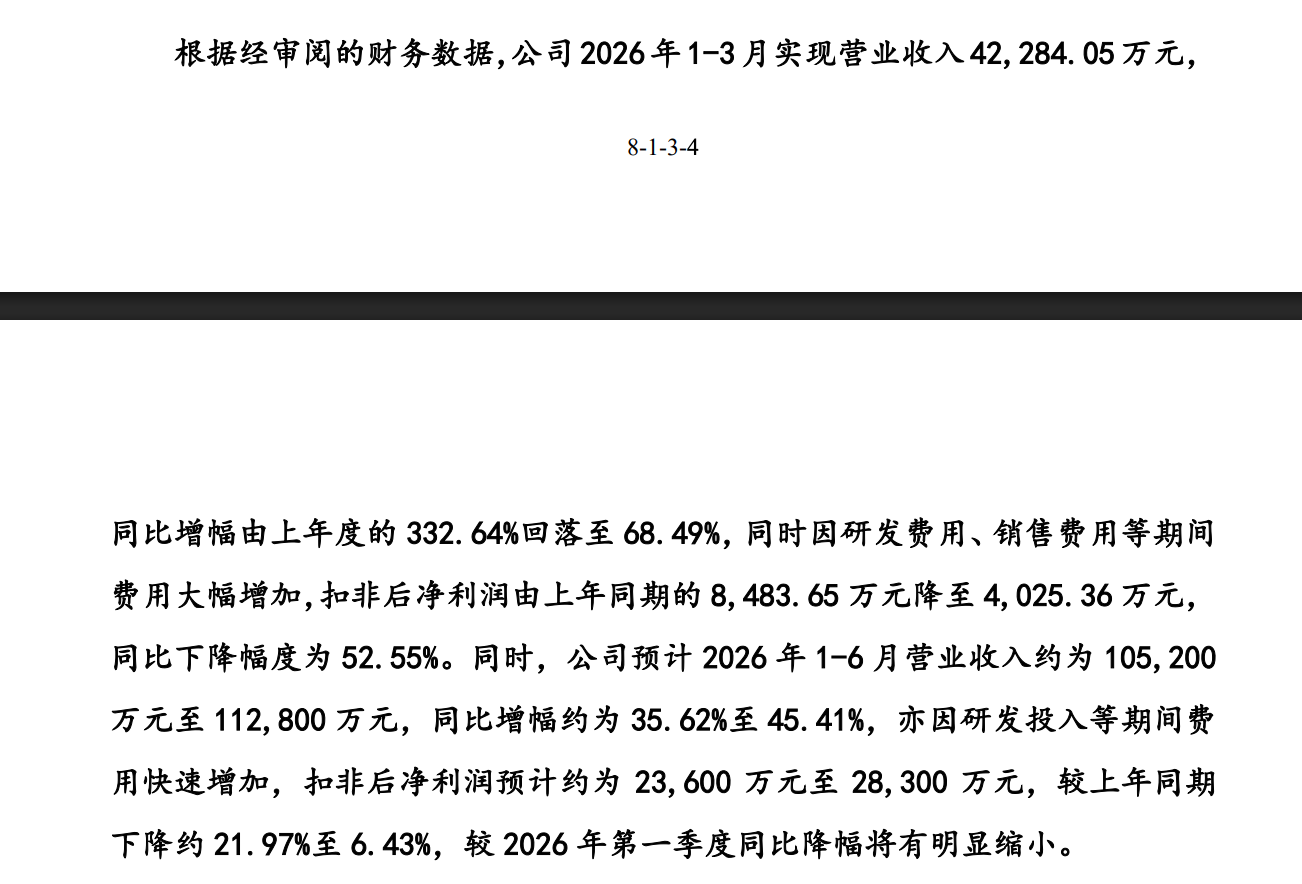
Unitree Technology Financial Reply Letter, Source: Shanghai Stock Exchange
Comparing the prospectus disclosed in March this year and the meeting draft disclosed in May, Unitree Technology made five modifications to its Special Risk Disclosure. The most critical one was adding a "Net Profit Year-on-Year Decrease Warning" and replacing the originally relatively broad "Risk of Technology Breakthrough and Product Innovation Falling Short of Expectations" with "Risk of Slowing Growth and Business Performance Fluctuations," placing it at the top of the seven special risk warnings. The prospectus also for the first time named Tesla as a threat, acknowledging that Tesla, leveraging mass production and supply chain integration capabilities, has started small-batch trial production of its humanoid robot Optimus Gen-3, with planned annual capacity reaching 1 million units. Once mass production is achieved, it will directly compete with Unitree.
Wang Feili, China Industrial Analyst at UBS Securities, mentioned that even if many manufacturers aim for shipments of ten thousand units this year, humanoid robots may not have truly reached a commercialization inflection point, because current industry orders are still mainly verification purchases, not expansion purchases based on productivity demand.
5. Institutions and Analysts' Bearish Views
Zhuo Wang, a partner at a Shanghai investment institution, told Reuters in an interview, "This IPO pricing is on the expensive side, the investment risk is already quite high," and pointed out that most of Unitree's sales revenue comes from research and exhibition scenarios, and true large-scale commercial application is still far away.
Even the relatively bullish Shenwan Hongyuan Research used cautious wording when commenting on this pricing, stating that the relatively high issuance valuation might draw market attention to the commercial value of the entire robot industry, thereby driving re-pricing of related stocks. Looking at this statement conversely, it can also be understood that Unitree's current commercial value itself still needs verification, and valuation has outpaced its business.
Research firm SemiAnalysis gave in its report that they estimate Unitree had only about 250 robots actually used in industrial scenarios in 2025, while annual shipments had already exceeded 5500 units, a relatively large discrepancy.
Conclusion: Valuation Ultimately Returns to Fundamentals
In the end, this round of pricing is largely the result of the combined push from the global humanoid robot frenzy and A-share retail investor sentiment. Since the beginning of this year, almost all companies tagged with "embodied intelligence," from Tesla Optimus to Zhiyuan, Dobot, and Yunsenchu, have been assigned far more imagination in the capital markets than their existing performance warrants.
For this bet to succeed, three assumptions need to materialize simultaneously: humanoid robot industry demand sees explosive growth in the short term, Unitree can defend its market share amid strong competitors like Zhiyuan Robot and Tesla Optimus, and it won't sacrifice its current high gross margin of around 60% due to price wars. All three conditions are indispensable, and each carries considerable uncertainty.
In the short term, constrained by structural factors like a small free float and index fund support, Unitree's stock price may not weaken immediately, and may even continue to rise in the initial post-listing period. But in the medium term, once these structural supporting forces fade over time, especially as the one-year post-listing lock-up period for institutional shares approaches, valuation will ultimately have to return to fundamentals for examination. If by then the revenue share from industrial scenarios has not significantly improved and profit growth continues to decline, this currently dream-based high valuation will likely experience a significant correction.
How similar this is to the trajectory of most crypto assets...