Strategy Counters MSCI's Plan to Exclude MSTR from Global Indices

cryptonews.ru2026-08-15 tarihinde yayınlandı2026-08-15 tarihinde güncellendi

Özet

Strategy Inc. (MSTR) has publicly challenged MSCI's proposal to exclude the largest corporate Bitcoin holder from its global equity indexes. The index provider's consultation introduces a two-step filter to identify "non-operating companies," where firms failing a primary operational assets test face further financial ratio screenings. MSTR, classified as such due to its Bitcoin treasury model, risks removal alongside firms like Yellow Cake and Metaplanet. MSCI estimates potential exclusion of three companies from its ACWI IMI index as of May, with MSTR being the only large-cap firm, facing an estimated $2.8 billion in passive fund outflows. The company argues that digital assets are legitimate and index providers should not dictate what assets companies hold. This new proposal replaces a previous, more crypto-specific rule that MSCI abandoned after criticism. With MSTR's stock trading close to the value of its Bitcoin reserves, its premium is minimal, and the availability of spot Bitcoin ETFs offers direct exposure without corporate risks. Feedback on the proposal closes September 30, with results announced by October 16 and any changes taking effect in November 2026.

On August 14, Strategy Inc. (Nasdaq: MSTR) issued a public rebuttal to MSCI's statement after the index provider this month initiated consultations on excluding the largest corporate Bitcoin holder from its global equity indices. Funds that track these indices adjust their portfolios accordingly, turning the selection rule into automatic portfolio changes.

"Digital assets are assets," the company wrote on X, arguing that index providers should measure markets, not define what assets companies can own. Strategy stated that MSCI's proposal does not align with the stance of regulators, markets, and clients, adding that neither Bitcoin nor the company itself is dependent on the index provider.
As part of the consultation, MSCI proposes a two-stage filter for so-called "non-operating companies"—firms whose value appreciates due to assets on their balance sheet rather than business income. An issuer passes the first stage if operating assets constitute more than half of total assets.

How MSCI's New Filter Identifies 'Bitcoin Treasuries'

Issuers failing this primary test are then screened against five financial ratios covering operating asset intensity, expense intensity, operating cash flow, fair value intensity, and capital dependency. Four "red flags" out of these five deem a company unsuitable for inclusion in Global Investable Market Indices.

The proposal applies more lenient thresholds to current index constituents than to external candidates: starting with an operating asset share of less than 10% of the balance sheet and operating expense share of less than 5% of assets. Negative operating cash flow, excessive non-operating fair value fluctuations affecting both assets and revenue, and financing cash flow exceeding 30% of assets, along with reporting confirming external financing was raised to purchase assets, complete this set of criteria.

Index constituents must fail the criteria for two consecutive years before being removed, while new entrants lose eligibility after just one reporting period. MSCI follows a cautious policy to limit turnover, so a single instance of non-compliance does not lead to loss of index membership.

Which Companies Are Slated for Exclusion

MSCI's simulation using the MSCI All Country World Investable Market Index (ACWI IMI) identified three companies for exclusion as of May. Strategy was the only large-cap company among them, with a free-float adjusted market value of $23.93 billion.

Following it is London-listed uranium mining company Yellow Cake with a market value of $1.81 billion, and Tokyo-listed Metaplanet—$654 million; both companies fall into the small-cap category. Additionally, as of the end of the second quarter, Metaplanet held approximately 43,000 $BTC and uses these reserves as collateral for loans.
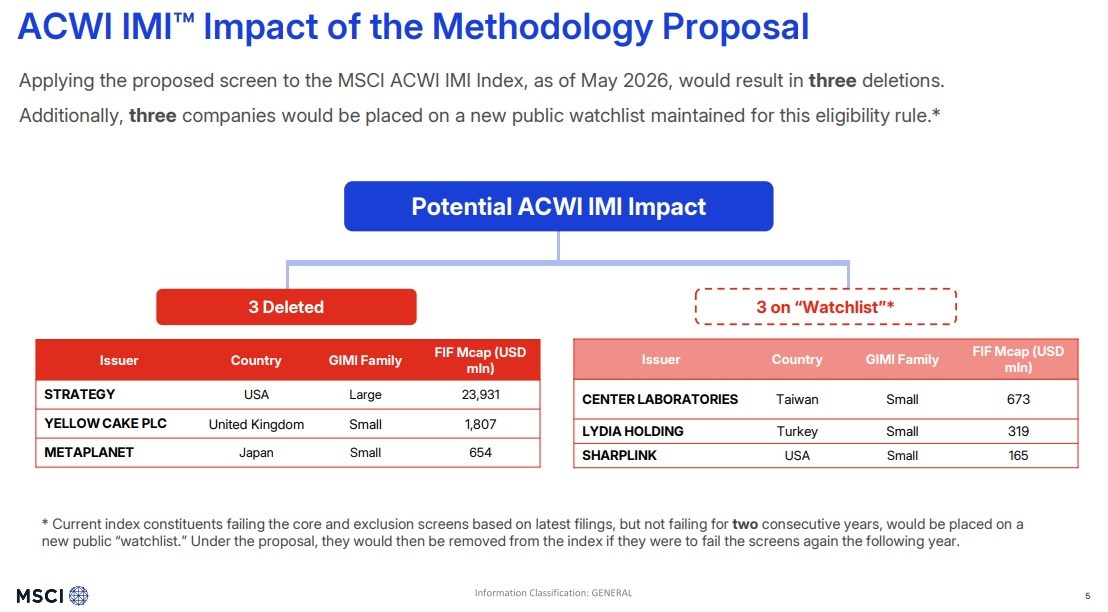
As a result of MSCI's simulation conducted in May 2026, Strategy was identified as the only large-cap company among three facing potential exclusion from the ACWI IMI index under the proposed selection criteria. Source: MSCI

Three more companies enter a new public watchlist: Taiwan's Center Laboratories with a market cap of $673 million, Turkey's Lydia Holding at $319 million, and SharpLink, managing ether reserves, at $165 million. Yellow Cake holds physical uranium, not tokens, indicating the selection criteria extend beyond digital assets.

A Rule MSCI Already Abandoned Once

In its previous attempt, MSCI singled out digital asset holding companies, defining them as issuers where half or more of total assets are cryptocurrency, and named 39 candidates. Executive Chairman Michael Saylor and CEO Phong Le signed a letter in December calling this threshold discriminatory, arbitrary, and unworkable.

That proposal was shelved on January 6, and MSCI promised a broader review of non-operating issuers. The new proposal contains no cryptocurrency threshold; however, it impacts Strategy through its treasury model mechanism, which raises equity and debt to accumulate Bitcoin.

According to the latest reporting, Strategy owns 840,447 $BTC, having bought roughly 175,000 coins this year and sold about 7,000. Le made it clear the company will resume purchases at the end of this year.

The Cost to Shareholders from an Index Exclusion

Passive investment funds follow index composition, so excluding a company from an index would force index funds to sell Strategy's shares or otherwise rebalance their position in the stock. JPMorgan analysts estimated outflows of around $2.8 billion if Strategy were removed from MSCI indices; this estimate was based on the withdrawn 2025 proposal, not the current one.

Strategy's shares trade close to the value of its Bitcoin portfolio: according to the company's dashboard, the mNAV ratio was about 1x on August 14. This ratio evaluates the company's market value relative to its own reserves. Such a small premium leaves shareholders with limited downside protection should index-tracking funds be forced to sell shares. It also indicates investors assign little additional value to Strategy's ability to raise debt, its capital-raising strategy, and corporate structure beyond its underlying Bitcoin assets.

Furthermore, spot Bitcoin ETFs provide exposure at near-par value without an intervening corporate balance sheet, weakening the argument for a stock premium. Investors can gain Bitcoin exposure without taking on Strategy-specific risks related to debt, convertible obligations, equity dilution, management decisions, or index eligibility. This alternative may cap the premium investors will pay for Strategy, especially when a potential benchmark exclusion creates an additional source of selling pressure.

The feedback period ends September 30, results will be announced by October 16, and any adopted changes will take effect during the index review in November 2026. MSCI notes consultations may or may not lead to changes, and watchlisted companies remain in the index until a second consecutive exclusion, meaning Center Laboratories, Lydia Holding, and SharpLink will face the same filter again next year.

İlgili Sorular

QWhy is MSCI proposing to exclude companies like Strategy Inc. from its global indexes, and what is the core argument made by Strategy against this proposal?

AMSCI is proposing a two-step filter to identify and potentially exclude 'non-operational companies,' defined as firms whose value is driven by assets on their balance sheet rather than business earnings. Strategy Inc. argues that index providers should measure markets, not dictate what assets companies can own, stating that digital assets are legitimate assets and that MSCI's proposal is inconsistent with regulators, markets, and clients.

QWhat are the specific financial ratio criteria in MSCI's proposed filter that could lead to a company's exclusion, and how many 'red flags' trigger ineligibility?

AThe proposed filter uses five financial ratios: operating asset intensity, expense intensity, operating cash flow, fair value intensity, and capital dependency. A company becomes ineligible for inclusion in MSCI's Global Investable Market Indexes if it raises four 'red flags' out of these five criteria.

QAccording to the article, which companies were identified for potential exclusion from the MSCI ACWI IMI index as of May, and what was their market capitalization?

AAs of May, the simulation identified three companies for potential exclusion: Strategy Inc. (large-cap, $23.93B market cap), Yellow Cake (small-cap, $1.81B), and Metaplanet (small-cap, $654M). Three more companies were placed on a watchlist: Center Laboratories ($673M), Lydia Holding ($319M), and SharpLink ($165M).

QWhat was the estimated financial impact on Strategy Inc.'s shareholders if the company were to be excluded from MSCI indexes, according to analysts mentioned in the article?

AAnalysts at JPMorgan estimated that exclusion from MSCI indexes could result in outflows of approximately $2.8 billion. This estimate was based on a withdrawn 2025 proposal, not the current one.

QWhat is the deadline for feedback on MSCI's consultation, and when would any adopted changes take effect?

AThe deadline for feedback on MSCI's consultation is September 30. Results will be announced by October 16, and any adopted changes would take effect at the index review in November 2026.

İlgili Okumalar

CFTC Finally Recognizes 'Private Keys as Ownership', How Will the 108-Page New Rule Reshape the Crypto Derivatives Landscape?

The CFTC has unveiled a 108-page Advance Notice of Proposed Rulemaking (ANPR) introducing Regulation CTX and Reg CAM, marking a significant regulatory shift for the crypto derivatives landscape. This move, led by Commissioner Michael Selig, provides the industry's first clear compliance framework following years of enforcement based on Dodd-Frank rules. A key breakthrough is the formal recognition of the "Not your keys, not your coins" principle. The rules clarify that "actual delivery" for crypto assets requires transferring possession of access credentials (like private keys), effectively exempting pure self-custodial, peer-to-peer transactions (e.g., on DEXs like Uniswap) from CFTC exchange registration requirements for day-to-day oversight. Furthermore, Reg CAM allows for a "Fully Integrated Crypto Asset Market" structure. This permits qualified platforms to combine exchange, broker (FCM), and clearinghouse (DCO) functions under one entity, aligning with the integrated model of major crypto exchanges like Coinbase. The CFTC defended this approach by contrasting the safety of customer funds in its registered entities during the FTX collapse with the losses in offshore affiliates. The ANPR also explores critical forward-looking areas: the regulatory treatment of front-end interfaces integrating DeFi yield vaults; potential mandates for smart contract audits and formal verification; the use of on-chain transparency for proof of reserves; and the possibility of compliant, fully on-chain order book exchanges. This regulatory "help" aims to provide certainty for on-chain finance to flourish under a new U.S. framework.

marsbit7 dk önce

CFTC Finally Recognizes 'Private Keys as Ownership', How Will the 108-Page New Rule Reshape the Crypto Derivatives Landscape?

marsbit7 dk önce

Exclusive Interview with Chicago Fed President Goolsbee: The Clash Between Hard Data and Sentiment, Consumer Disconnect, and Concerns Over AI Infrastructure Overheating

Chicago Fed President Austan Goolsbee discusses the growing divergence between strong macroeconomic data ("hard data") and widespread public pessimism ("vibes"). He explains that the Federal Reserve prioritizes hard data, like labor market ratios and retail sales, for policy decisions, as the traditional link between consumer sentiment and actual spending has nearly broken down. Goolsbee attributes the public's negative economic feelings to the "salience" of high absolute price levels for items like gas and groceries, political polarization influencing surveys, and the memory of past real wage declines. The labor market remains in an unusual "low-hire, low-fire" stalemate with high stability but low mobility. A key concern is the potential for a $1.5 trillion AI infrastructure spending boom to cause localized economic overheating. Goolsbee warns this could complicate inflation control if it spills over into broader demand and costs, risking a scenario reminiscent of past investment bubbles. Core insights include: sentiment is no longer a reliable spending indicator; cumulative price increases drive public pain more than inflation rates; strong spending by high-income groups masks stagnation at lower levels; and the Fed remains committed to returning inflation to 2% as the fundamental solution to cost-of-living anxieties.

marsbit18 dk önce

Exclusive Interview with Chicago Fed President Goolsbee: The Clash Between Hard Data and Sentiment, Consumer Disconnect, and Concerns Over AI Infrastructure Overheating

marsbit18 dk önce

U.S. Becomes Net Importer of Bitcoin in 2026, Institutions Accumulate as Retail Exits

In 2026, the U.S. became a net importer of Bitcoin for the first time since the 2022 market correction, according to a Chainalysis report. A deep divergence emerged between institutional and retail investors. Large institutions and professional capital, utilizing compliant channels like spot ETFs approved in 2024, have maintained a strong pace of accumulation, moving BTC into cold storage and trusts. In contrast, retail investors have largely been net sellers, reducing small transactions and active addresses, leading to a one-way transfer of coins from散户 to institutional vaults. Following the SEC's approval of spot Bitcoin ETFs in January 2024, the U.S. has seen its share of global Bitcoin activity increase consecutively. Despite market pullbacks, the U.S. crypto economy remained stable at $2.78 trillion in 2026, retaining 97.8% of its capital from the previous year's expansion. The report also highlights a broader global settlement pattern: the U.S. is exporting digital dollar stablecoins—accelerated by regulations like the 2025 GENIUS Act mandating full U.S. Treasury backing—to global trade networks, while simultaneously using its capital advantage to absorb the finite supply of Bitcoin as a strategic store-of-value asset for institutional balance sheets. This dual flow positions the U.S. to both provide dollar liquidity abroad and accumulate scarce digital assets domestically as the macro rate-cut cycle deepens.

marsbit21 dk önce

U.S. Becomes Net Importer of Bitcoin in 2026, Institutions Accumulate as Retail Exits

marsbit21 dk önce

Strategy Spent $16 Billion in Rescue Funds, Preferred Stock STRC Buyback Loop Faces Liquidity Test?

MicroStrategy (now Strategy) launched a high-yield preferred stock, STRC, with a 12% annual dividend, designed to raise funds by issuing shares at or above their $100 face value to finance continuous Bitcoin purchases. However, since mid-May, STRC's price fell below par, dropping as low as $74.57 in late June, halting new issuances. To restore the $100 benchmark and restart this funding channel, Strategy initiated an aggressive weekly buyback program in late July, spending a cumulative $1.6 billion to repurchase STRC. Last week's buyback hit a record $192.4 million—approximately nine times its Bitcoin purchases for the same period. This massive effort has pushed STRC's price back to $99.90. The funding for these repurchases primarily comes from selling MSTR common stock in the open market. At the current spending rate, the authorized buyback budget could be exhausted in about two weeks, though the board may increase it again. The company's available liquidity could also be depleted in just over three weeks at this pace. This situation represents a significant shift in Strategy's capital strategy. Instead of using raised funds to leverage Bitcoin acquisitions, a substantial portion is now being diverted to support STRC's price. The company even sold some Bitcoin this summer to fund the repurchases. While financially accretive if MSTR trades above ~$131, this activity effectively reduces MSTR's leverage to Bitcoin's price. Market data shows Strategy's buybacks accounted for 20-25% of STRC's trading volume in September, raising concerns about a lack of independent buy-side demand. The critical question remains: if Strategy stops its buyback support after reaching the $100 target, whether sufficient external demand exists to sustain the price, or if the costly cycle will need to restart.

marsbit22 dk önce

Strategy Spent $16 Billion in Rescue Funds, Preferred Stock STRC Buyback Loop Faces Liquidity Test?

marsbit22 dk önce

İşlemler

Spot
活动图片