Trump's Perplexing Fed Threat Might Be a Gift to Warsh

marsbitPublished on 2026-09-08Last updated on 2026-09-08

Abstract

Former President Donald Trump's puzzling call for Federal Reserve interest rate cuts and threats to halt trade with countries running U.S. deficits has drawn market confusion rather than movement. Reuters columnist Mike Dolan argues this rhetoric, lacking logical coherence, paradoxically presents new Fed Chair Kevin Warsh with an opportunity. By pushing for a rate hike at the upcoming September meeting, Warsh could credibly distance the central bank from White House pressure, reaffirm its commitment to the inflation target, and bolster his own credibility. With strong August jobs data, growth accelerating, and core inflation persistently above 2%, few economists see a case for cuts. A 25-basis-point hike, Dolan suggests, would be a strong public relations move to end speculation that Warsh is a White House "puppet" and could even help lower long-term borrowing rates by reinforcing the Fed's anti-inflation resolve. The article notes Trump's history of turning on his Fed appointees, implying Warsh faces a critical choice that may ultimately anger his patron.

Author: Mike Dolan

Compiled by: TechFlow

Deep Tide Digest: Last Friday, positive U.S. August employment data emerged, yet Trump suddenly pivoted to criticize the Federal Reserve, demanding "interest rate cuts, or else stop trading with countries with deficits." Reuters columnist Mike Dolan points out that this statement is logically incoherent and barely elicited a market reaction. However, it precisely presents an opportunity for Fed Chair Kevin Warsh, who took office this past May, to push for a rate hike this month. This move would reaffirm the Fed's commitment to its inflation target and demonstrate that he is not the White House's "puppet," thereby creating distance from the President and building his own credibility.

Trump's inexplicable linking of U.S. interest rate policy with trade relations with America's largest trading partners has generated more confusion than market volatility. But the President's outlandish statement has instead given Federal Reserve Chair Kevin Warsh an opportunity: to drive a Fed rate hike this month, convincingly creating distance from the White House and boosting his own credibility.

Last Friday should have been a reasonably good day economically for the President. After all, U.S. August job growth came in three times higher than expected, and a significant portion of the summer's weak job figures were revised upward. Diesel prices did hit a record high earlier that day, potentially adding upward pressure on inflation. However, the modest wage growth in the jobs report could also be interpreted as another reason for the Fed to stand pat ahead of this Friday's inflation data, coming just days before the Fed's next meeting.

Trump needed some good economic news. With only two months until the midterm Congressional elections, his overall approval rating remains at the low point of his two terms, and 71% of Americans (including four in ten Republicans) disapprove of his handling of the cost of living.

Yet, instead of focusing on the positive August jobs data, Trump quickly and somewhat inexplicably pivoted to attack the Fed, telling the central bank what it should do and threatening what he would do if it didn't comply.

"High interest rates put the U.S. at a very unfair disadvantage, I won't allow it!" Trump wrote on his Truth Social platform, while praising Warsh as "great." "We should have the lowest interest rates in the world... No rate cut, I'll stop trading with those countries where we have a deficit," Trump added.

The main problem with this argument is that it simply doesn't make sense. Even commentators typically supportive of the President either gave up trying to parse it or ignored it outright. Given the market's concerns over the past 18 months about the President's persistent political pressure on the central bank—including his willingness to force its hand through political appointments—this apparent disregard is noteworthy.

Trump has repeatedly called for significant rate cuts during his second term and has threatened multiple times to fire Warsh's predecessor, Jerome Powell, for not complying. He has also frequently questioned why America's economic strength shouldn't also grant it the world's lowest interest rates, even though most economists would struggle with the notion that a high-growth economy should have lower borrowing costs—considering the inflationary impact of overheating, the opposite is typically true.

More importantly, with core inflation running above the Fed's 2% target for 65 consecutive months, growth accelerating, financial conditions loose, and full employment effectively achieved, almost no one believes the Fed should be cutting rates now—not even those who think a September hike (currently priced by futures markets at over a 50% probability) might be slightly premature.
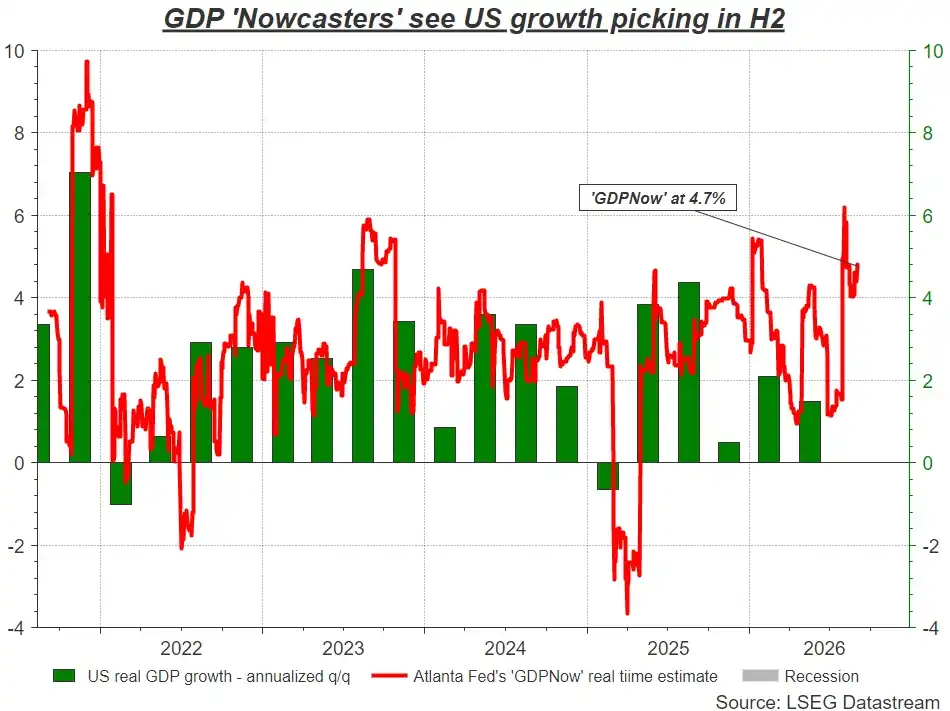
Even if one agreed with the call for rate cuts now, despite the cost-of-living issues, linking the Fed's hesitation to a threat to "stop trading with foreign countries" has left most commentators and investors questioning the President's grasp of basic economics.

"Clueless" or "Puppet"?

Perhaps Friday's post was just a hasty attempt to re-energize his latest offensive in the trade tariff war. But even then, deliberately weakening foreign economies by cutting off imports via tariffs or executive order could prompt those countries to cut rates while also potentially raising import prices at home. That wouldn't give the U.S. the world's lowest interest rates.

The market's lack of reaction to Trump's latest Fed comments might indicate investors are growing more skeptical and cautious about the President's increasingly outlandish posts. For example, Trump recently claimed to have "blown to pieces" Iran's Kharg Island oil hub, which turned out to be completely false.

So where does this leave Kevin Warsh? The Trump-appointed chair has struggled to establish his own credibility since taking office in May, with concerns about White House political pressure constantly looming over him.

However, Warsh seemed to lean noticeably hawkish in his recent keynote speech at Jackson Hole.

A rate hike now would not only highlight the Fed's commitment to its inflation target (regardless of how little consumer price inflation trends fluctuate this week) but also affirm Warsh's control over the central bank and help him create distance from the President.

"A 25bp hike is good PR. It ends the credibility narrative and months of speculation over whether Warsh is a puppet," wrote TS Lombard economist Dario Perkins. He noted that in the last 50 years, only Janet Yellen didn't raise rates within two months of becoming Fed chair.
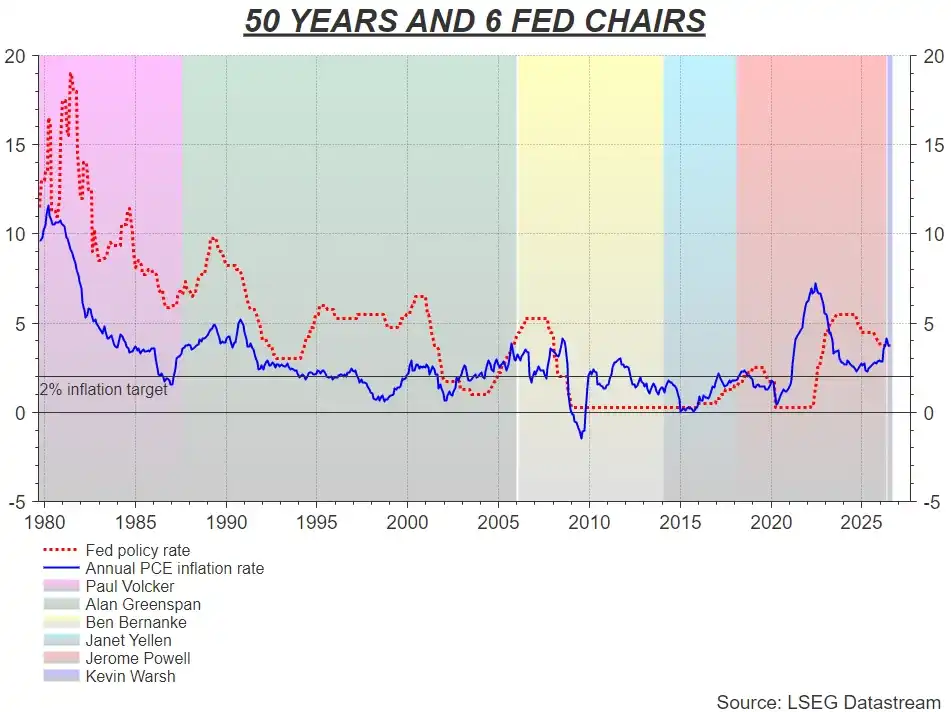
The perceived cost of the Fed and its current head being seen as cowed by a White House whose views are "hard to explain" outweighs any negative impact from a quarter-point hike. In fact, hiking now might even help lower long-term bond borrowing rates by reaffirming the Fed's inflation-fighting credibility, taking some pressure off Treasury Secretary Scott Bessent; and long-term rates arguably have a bigger impact on the economy than the policy rate.

"Warsh only gets credibility when Trump starts calling him an idiot!" Perkins added.

For now, Warsh still seems "great" in the President's eyes. But it took Trump only a year to go from praising Powell as "brilliant" to labeling him "clueless" as rates kept rising. Warsh faces significant choices, even if they risk angering the person who appointed him.

(These views are those of the author, Mike Dolan, a Reuters columnist.)

Related Questions

QWhat is the main point made by the author regarding President Trump's recent criticism of the Federal Reserve?

AThe author argues that President Trump's illogical criticism of the Federal Reserve and his demand for rate cuts paradoxically provides an opportunity for Fed Chairman Kevin Warsh to raise rates, which would help him establish credibility and distance himself from the White House.

QAccording to the article, why is President Trump's argument for lower interest rates considered illogical?

ATrump's argument is considered illogical because it suggests a high-growth economy like the U.S. should have the world's lowest interest rates, while most economists believe the opposite is typically true due to inflationary pressures from an overheating economy. Furthermore, his threat to stop trade with countries running a deficit with the U.S. has no logical connection to Fed rate policy.

QWhat opportunity does Trump's critique create for Fed Chairman Kevin Warsh, according to the analysis?

ATrump's critique creates an opportunity for Warsh to lead the Fed in raising interest rates. This move could demonstrate the Fed's commitment to its inflation target, confirm Warsh's control over the central bank, and help him build personal credibility by distancing himself from political pressure from the White House.

QHow did the market react to President Trump's latest comments on the Federal Reserve, and what does this reaction suggest?

AThe market showed little reaction to Trump's latest comments. This lack of reaction suggests investors are becoming increasingly skeptical and cautious towards the president's more outlandish posts, as seen with his earlier false claim about bombing an Iranian oil hub.

QWhat is the significance of a potential rate hike for Fed Chairman Kevin Warsh's reputation, as highlighted in the article?

AA potential rate hike is significant for Warsh's reputation because it would serve as a strong public relations move. It could end the narrative questioning his credibility and speculation that he is a 'puppet' of the White House, ultimately helping him establish his independence and authority as Fed Chair.

Related Reads

Changing Gas Metering Could Break Smart Contracts? Ethereum Urgently Halts Hoodi Fork to Investigate Eight Major Security Risks

Ethereum core developers have paused the Hoodi testnet upgrade after security auditors found that two upcoming Gas improvement proposals could invalidate long-standing assumptions underpinning many deployed smart contracts. The proposals, EIP-8037 and EIP-8038, part of the Glamsterdam upgrade, aim to reprice state storage by decoupling state creation from state access and setting dynamic weights for certain opcodes, in order to curb unchecked growth of Ethereum's state data. However, this overhaul disrupts static Gas constants that developers have relied on as fixed system parameters. ChainSecurity identified eight invariant risks. Many contracts and off-chain infrastructure depend on hardcoded Gas limits, for example to prevent reentrancy or bound execution scope; higher costs could cause cross-contract calls to run out of Gas and revert. Other risks lie in error-handling logic that relies on precise prediction of inner execution costs, and in proxy contracts that forward Gas based on fixed ratios, potentially distorting execution paths or locking funds in incomplete state-machine branches. To avoid systemic compatibility failures and cascading disruptions across multisig wallets, bridges, and lending protocols, developers agreed at an ACD meeting not to hard-fork Hoodi until the affected contracts are fully mapped and compatibility guidance is issued. Because much logic lives off-chain in proprietary routing, settlement scripts, and liquidation bots, the Ethereum Foundation acknowledged it cannot audit the entire ecosystem alone. It has published a public repository detailing the eight affected invariants, sample problem code, and prompt templates for audit and scanning tools, so teams can check their own logic. Findings will be reviewed at next week's ACD meeting, when Hoodi activation conditions will be reassessed.

marsbit1h ago

Changing Gas Metering Could Break Smart Contracts? Ethereum Urgently Halts Hoodi Fork to Investigate Eight Major Security Risks

marsbit1h ago

What Exactly Drives the Value of Layer 1?

This analysis by Marc Arjoon, CFA, examines what actually drives Layer 1 valuation through time-series regression on major L1 assets. Short-term, all L1 price movements remain dominated by Bitcoin beta. Over longer horizons, Ethereum's market cap has fully decoupled from its own protocol revenue—a deliberate policy outcome of Dencun and higher gas limits rather than a demand collapse—with its 2025 rally driven instead by spot ETF and corporate treasury demand. Solana, by contrast, shows revenue and market cap moving in tandem, both rising ~15x since January 2023 and peaking the same week. Active addresses and DEX volumes show weak weekly correlations and large divergences despite long-cycle drift. Testing Metcalfe's Law, the fitted elasticity of market cap to active addresses is only 0.56 for Ethereum and 0.62 for Solana and BNB—closer to the square root of addresses than the square. None of six valuation multiples reliably mean-reverts; Mcap/REV is the only one that predicts positive 13-week returns from low valuation quantiles on Ethereum and TRON. No L1 has Bitcoin's deep holder base: only 4% of Solana and 10% of Ethereum supply has been dormant over three years versus 42% for Bitcoin. Ethereum's pricing anchors to peer capital share—59% of L1 market cap, 70% of DeFi TVL, 75% of tokenized RWA—rather than on-chain activity, where it holds just 5% of active addresses. Across chains, market cap rank correlates strongly with TVL (Spearman 0.87) and stablecoin supply (0.63) but weakly with transactions (0.17). The core conclusion: L1s are valued less as fee-generating businesses and more as monetary assets competing for capital settlement and liquidity share.

marsbit1h ago

What Exactly Drives the Value of Layer 1?

marsbit1h ago

From 85% to 9%: The Dramatic Shift in Korean Exchange Listing Logic—Tokens Are Safer, but Is the Business Harder?

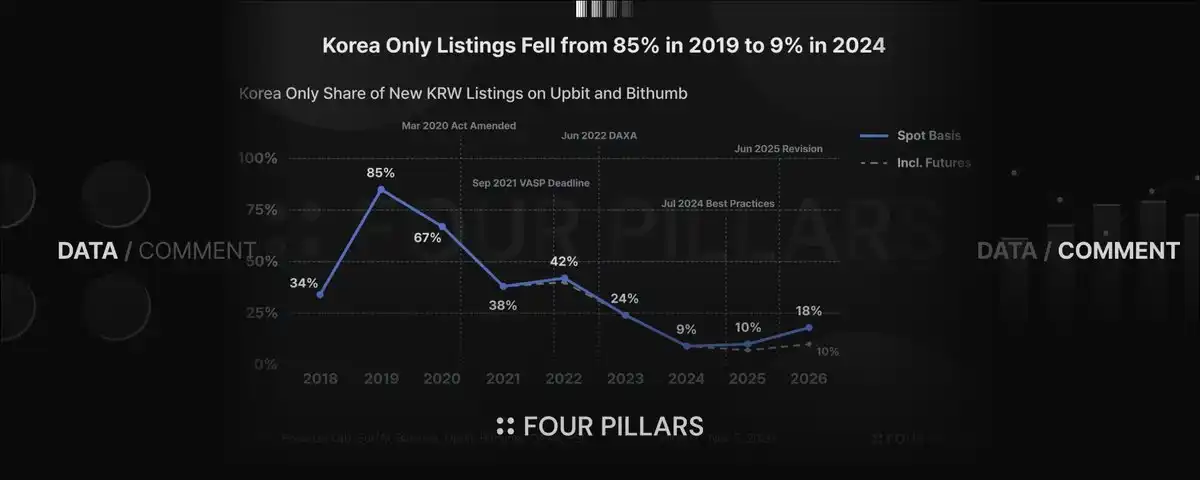
South Korea’s KRW crypto exchanges have fundamentally changed their listing logic. According to Bonanza Lab data across Upbit, Bithumb, Coinone, Korbit, and Gopax, the share of Korea-only token listings fell from 85% in 2019 to 9% in 2024, with a slight rebound to 18% in 2026 that drops back to about 10% when excluding assets first traded on overseas futures markets. The shift began with the 2021 Specific Financial Information Act, which required real-name bank accounts and traditional-finance-level AML compliance, and was reinforced by DAXA’s unified listing review guidelines effective July 2024, under which assets with two or more years of trading history on compliant overseas exchanges can automatically satisfy baseline disclosure and whitepaper requirements. Despite the collapse in local-first listings, total listings have grown: Upbit and Bithumb added 43 KRW-market tokens in 2022, 116 in 2023, 125 in 2024, and 238 in 2025. Listing timing remains cyclical—in the 2025 bitcoin high, 111 assets (47%) were brought to Korea within 30 days of overseas listing, while in 2026 mature assets with over a year of overseas trading became the mainstay (52 assets, 31%), including older tokens such as CRV and RSR. The consequences are clear. The share of assets hit by investment warnings or delisting within two years fell from 24% for the 2020 cohort to 10% for 2024. Among 2020–2024 listings, 44 of 148 Korea-only tokens (30%) faced warnings or delisting within two years, versus only 26 of 279 overseas-first tokens (9%). Overseas seasoning also reduces post-listing drawdowns: assets listed in Korea within 30 days of overseas launch saw a median 30-day price decline of 39%, compared with just 7% for assets with over a year of overseas trading history. The trade-off is revenue. Heavily traded overseas assets generate limited first-day speculative volume, and since Korean exchanges rely overwhelmingly on spot trading fees, weaker listing-day surges can hurt earnings. A renewed bull market could temporarily revive listings of newly launched overseas assets, but exchanges cannot build a durable, cycle-resistant business on listing structure alone. Their core challenge is to create new trading demand and diversify revenue beyond listing-driven fees.

marsbit1h ago

From 85% to 9%: The Dramatic Shift in Korean Exchange Listing Logic—Tokens Are Safer, but Is the Business Harder?

marsbit1h ago

Didn't We Agree on Decoupling? BTC Fell Along With US Stocks Again

Bitcoin's "decoupling" from tech stocks proved short-lived. On Nov 4, the Dow rose 3% and BTC rebounded to $81K; just 24 hours later, a massive AI-driven selloff sent Nasdaq down 5.5% and BTC back to $75.2K. The trigger had nothing to do with crypto: after Democrats won Congress, markets feared slower data-center buildout, and chip stocks cratered (Nvidia -9.26%, AMD -17.26%, semiconductor ETF -12%, worst since March 2020). All 11 S&P sectors fell. BTC followed: it dropped about 5.5% to $76K, with over $1B liquidated in 24 hours—nearly 90% longs, about 210,000 traders forced out. The transmission path was simple: tech panic → institutions sell BTC ETFs → ETF outflows trigger on-chain leverage liquidations → accelerated decline. From Oct 30 to Nov 5, BTC ETFs saw roughly $1.5B in net outflows. The decoupling narrative keeps flipping. In February, Grayscale's Zach Pandl said BTC was highly correlated with high-growth tech software stocks. By August, the same analyst said BTC's correlation with gold had risen above 50% while its correlation with Nasdaq 100 fell from over 60% to about 33%—prompting talk that BTC was finally shifting toward gold. Two months later, K33 Research found BTC-Nasdaq synchronicity rising again. On Nov 5, Nasdaq fell ~6.5%, BTC ~5.5%, while gold rose 0.9%—BTC tracked Nasdaq, not gold. This isn't new. In early 2022, Kaiko found BTC-Nasdaq correlation at its highest since July 2020, while BTC-gold correlation was negative—the first data-driven blow to the "digital gold" thesis. In April 2025's tariff shock, BTC briefly decoupled, rising 13% while Nasdaq was flat, but correlation soon returned. Nov 5 mirrored April 2025: two shocks of similar magnitude; BTC withstood the first but not the second. Different institutions use different windows—Grayscale looks at 90 days, K33 at two-week returns—so conclusions change with the window. Correlation isn't a fixed conclusion; it keeps flipping. Notably, BTC and gold are both among 2025's worst performers. Charlie Bilello's Oct 23 ranking of 21 assets showed BTC down 7.3% and gold down 7.5%—the two worst—while short-term Treasuries rose 2.9% and commodities 52.5%. By Nov 5, BTC's year-to-date loss widened to about 13%. Bilello noted that since 2011, no year had seen BTC and gold both at the bottom. Gold itself fell about 27% from its January high near $5,600 to about $4,095, hit by war-driven inflation, higher yields, a stronger dollar, and leveraged selling. Yet in March, during the Iran war, BTC didn't follow stocks down—Grayscale's April report was titled "Resilience in War," noting equities, bonds, and precious metals all fell while crypto rose slightly, aided by Strategy's purchase of ~44,400 BTC. Same year: BTC held up in March but fell with tech in November. "Digital gold" is less a fixed property than a switching state. Pandl framed it honestly in February: "Is BTC a store-of-value asset like gold, or a growth asset like tech stocks? Short answer: we think it's both." The risk-asset side is visible—post-ETF institutional inflows make BTC trade like a high-beta tech stock. The store-of-value side needs a longer view: since 2011, BTC's average annual return is 120.6% versus gold's 6.3%. Even JPMorgan now includes BTC in long-term capital market assumptions, projecting 10% annualized returns over the next decade (above US large caps' 7.5%), though it flags 55% volatility and unstable correlations and excludes BTC from main portfolio models. Pandl added: "If BTC succeeds as a monetary asset long term, its price behavior may eventually look more like gold." Note the "if"—BTC is only 17 years old. Three indicators to watch: whether BTC-Nasdaq 100 90-day correlation stays above 0.5; whether spot ETFs see net outflows for more than a week; and whether BTC follows or decouples from tech in the next big move. At 17, BTC hasn't yet grown into itself.

marsbit2h ago

Didn't We Agree on Decoupling? BTC Fell Along With US Stocks Again

marsbit2h ago

After the US Midterm Elections, South Koreans Are in Complete Panic

After the U.S. midterm elections, a "blue wave" swept Congress and key AI-data-center states, triggering a global selloff in AI and semiconductor stocks. While most markets absorbed the shock without emergency action, South Korea reacted with alarming urgency: the deputy prime minister and finance chief convened an emergency market meeting, the financial services commissioner and a Bank of Korea deputy governor attended, and authorities announced a three-month exemption from the 140% credit-financing collateral requirement for brokerages, while the exchange triggered a Sidecar circuit breaker to halt programmatic selling. The panic is rooted in structure. In the month before the crash, Korean retail investors—the famous "ant army"—piled into Samsung Electronics and SK Hynix, often using borrowed money and single-stock leveraged ETFs, which regulators had already been tightening since July as leverage grew dangerously large. Retail investors hold roughly 60% of these leveraged products, and earlier declines had already wiped out 41% of their assets. Beneath them, the National Pension Service, the world's third-largest sovereign wealth fund, was heavily concentrated in the same chip stocks and rode them down from June's peak, losing about $137 billion. Korea's stock market is also a amplifier of social mood and a political risk, and the won is not a safe-haven currency: risk-off outflows hit the currency, import-dependent inflation rises, and a stock-FX-inflation "triple kill" becomes lethal. Foreign investors hold nearly 38-39% of market capitalization and over 46-50% of Samsung and SK Hynix, and have been massive net sellers—about $131 billion withdrawn this year, the most in Asia. Ultimately, the U.S. election was only the match; Korea's dependence on semiconductors is the fuel. Chips are now approaching 47% of exports, and semiconductor-related production contributed about half of Q3 GDP growth. With demand tied to U.S. AI capital spending, Korea catches a heavy cold whenever America sneezes—so its response is less market rescue than firefighting.

marsbit2h ago

After the US Midterm Elections, South Koreans Are in Complete Panic

marsbit2h ago

Trading

Spot
活动图片