Bitcoin moves first, followed by altcoins.
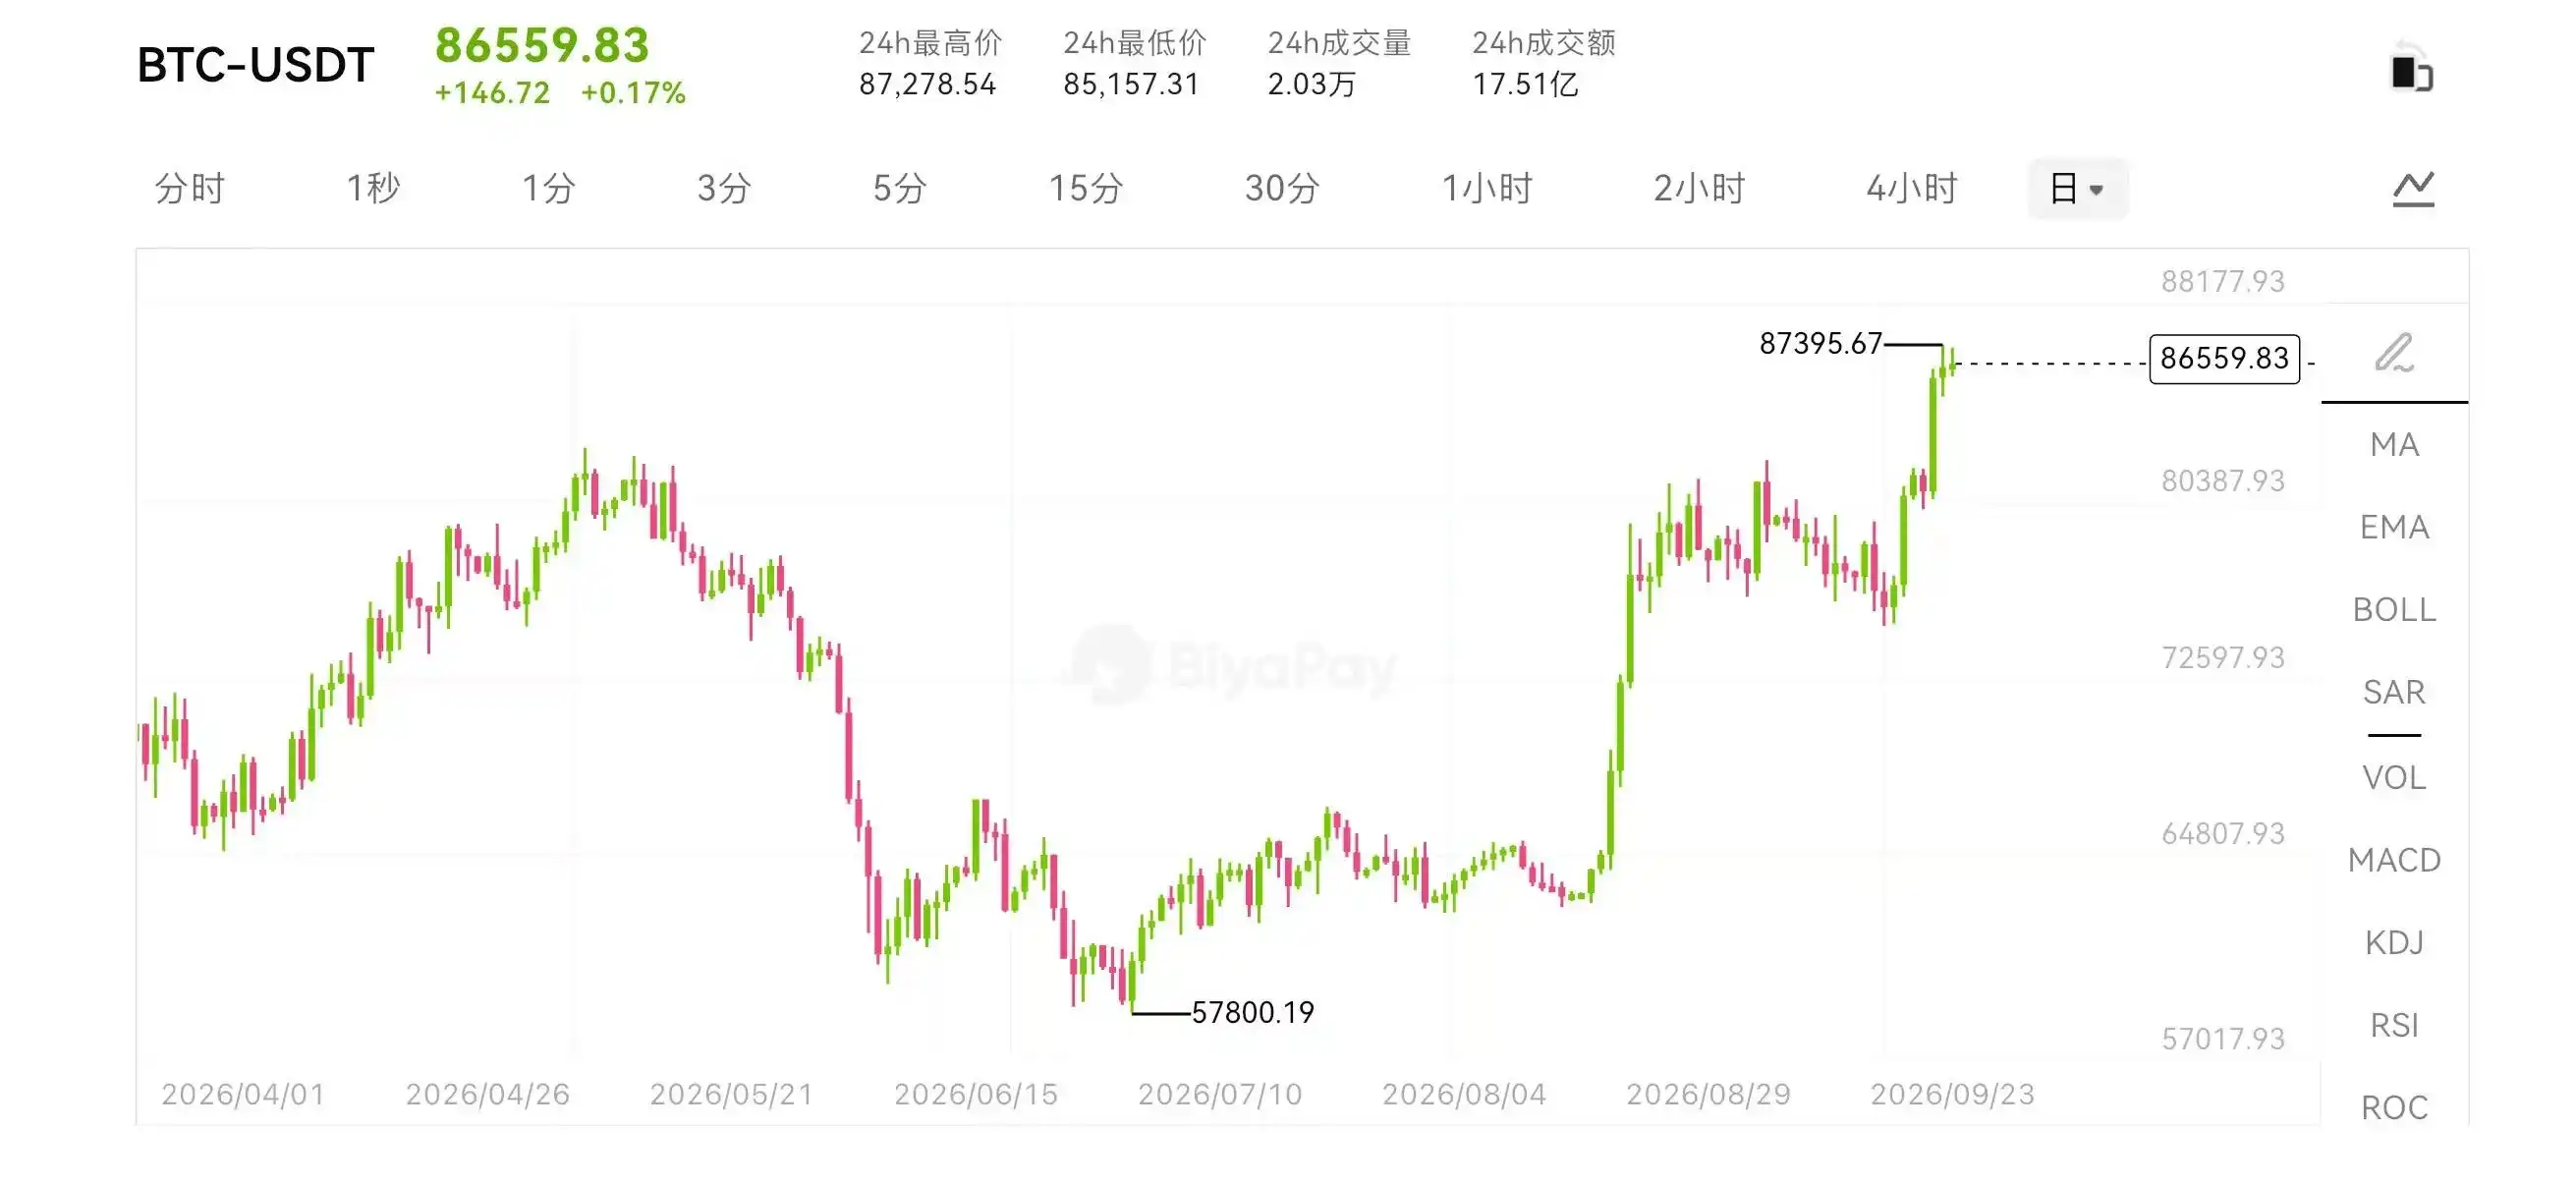
Market data from the global one-stop asset allocation platform BiyaPay shows that on September 21st, Bitcoin once broke above $87,000, reaching its highest level since the end of January this year. Subsequently, capital began flowing into assets with higher elasticity, with BCH showing significantly amplified gains and UNI also returning to around $10. By September 22nd, the CME announced plans to launch Bitcoin Cash (BCH) and Uniswap (UNI) futures contracts on October 19th, although final launch remains subject to regulatory review.
The convergence of these several factors quickly made BCH and UNI market focal points. Questions also arose: why were these two tokens favored by capital simultaneously? Does this signal the return of the altcoin season, or is it merely a short-term diffusion driven by BTC's breakout, derivatives news, and short covering?
What Signal Did CME Send to the Market?
What CME plans to launch this time are not spot products, but standard futures and Micro futures. Among them, the BCH standard contract corresponds to 250 BCH, and the Micro contract to 25 BCH. The UNI standard contract corresponds to 10,000 UNI, and the Micro contract to 1,000 UNI. CME stated that these products are mainly for price discovery, risk management, and providing market participants with a richer set of institutional-grade trading tools.
This means the market isn't actually trading on "how much BCH or UNI CME will buy," but rather that these two assets are entering a more standardized derivatives trading system. Futures allow institutions to participate through hedging, directional trading, and cross-market arbitrage, but they do not automatically generate equivalent spot buying demand.
From this perspective, CME's move is more like adding a new trading and risk management channel to the market. Past institutional derivatives in the crypto market were mainly concentrated on assets like BTC and ETH. Now, more high-liquidity altcoins are entering this system, indicating that institutional participation in the crypto market is still expanding.
However, a boundary needs to be noted here: a planned launch does not equal official launch, and futures launch does not guarantee an increase in spot demand. What is truly worth observing afterwards is whether the contracts can be launched as scheduled, and the subsequent trading volume, open interest, and spot market performance.
The sharper rise in BCH this time is also related to its own market structure. Compared to BTC, BCH has a smaller market size and trading depth, so under significant news catalysts, its price elasticity is often higher. After CME announced plans for BCH futures, the market refocused on the future availability of institutional trading and risk management tools for BCH, an expectation easily amplified in short-term price action.
But this does not mean BCH's fundamentals have fundamentally changed in a short time. Whether it can transform this gain into a sustained trend depends on the actual participation rate after the contract's final launch and whether the spot market can continue to absorb capital.
The logic for UNI is somewhat different. UNI is the governance token of the Uniswap ecosystem. Its price is influenced not only by the overall crypto market but also by factors like DeFi activity, on-chain liquidity, protocol development, and market expectations. CME's planned launch of UNI futures means the market gains a more mature price risk management tool and also increases market attention towards UNI's institutional trading and liquidity.
However, the futures product itself does not directly change Uniswap protocol fundamentals, nor does it automatically enhance UNI's governance value. Therefore, UNI's current rise is better understood within the context of two overlapping factors: on one hand, the news catalyst from CME's product, and on the other, the improvement in overall risk appetite following BTC's breakout.
After BTC's Breakout, Capital Begins Seeking Higher Elasticity
If we only look at BCH and UNI, it's easy to interpret this market movement as driven by a single news catalyst. In reality, before altcoins became active, BTC had already completed a significant rally.
On September 21st, Bitcoin broke above $87,000 intraday, reaching its highest level since the end of January this year. During the same period, flows into US spot Bitcoin ETFs also improved significantly, with net inflows on September 21st reaching approximately $999 million, one of the largest single-day net inflows since October 2025.
Institutional capital also showed new moves. Strategy disclosed that as of September 20th, the company added 950 BTC to its holdings, bringing its total to 846,000 BTC. Based on the announcement data, this purchase amounted to approximately $75.7 million.
Simultaneously, BTC's rapid rise was accompanied by massive short liquidations. Relevant market statistics show that the crypto market's short liquidation scale at that time was close to $920 million, with BTC short liquidations exceeding $550 million. Forced short covering creates additional buy-side pressure, which, when the market is already strong, can further amplify the speed of the rally.
Thus, this market movement shows a relatively clear transmission path: BTC led the rally, improving market risk appetite, prompting capital to seek assets with higher elasticity. BCH and UNI then coincidentally encountered the news catalyst of CME's planned futures products, further amplifying their price reactions.
This is also why the rise of BCH and UNI this time cannot be fully understood as the two projects themselves suddenly undergoing major changes. Macro liquidity, BTC's trend, market positioning, and specific news are all jointly influencing prices.
Is the Altcoin Season Back, or Just a Short-Term Diffusion?
For now, we cannot simply define this rally as "the comprehensive return of altcoins."
More accurately, what we are currently seeing are signs of capital diffusing into high-elasticity assets after BTC's breakout, with the news of CME launching BCH and UNI futures further increasing market attention. The combination of these two factors has led to significantly higher gains for some altcoins compared to BTC.
What is truly worth observing next is not how much further BCH and UNI can rise, but whether the prices can stabilize after the news hype subsides. If the rally primarily relies on short-term leverage and sentiment, then if BTC weakens again, altcoins typically experience greater volatility.
Whether the CME contracts launch on schedule is also a crucial observation point. The currently announced date is October 19th, but it still requires regulatory review. The real market impact needs to be verified after the product launches, through metrics like trading volume, open interest, and institutional participation.
Macro liquidity also cannot be ignored. The US dollar, US Treasury yields, US spot Bitcoin ETF flows, and risk appetite in US stocks all affect the valuation environment of the entire crypto market. If liquidity tightens again, altcoins are typically more prone to rapid pullbacks than BTC.
When observing such cross-market movements, I use BiyaPay to simultaneously view changes in BTC, ETH, US stocks, Hong Kong stocks, and fiat-related assets, then combine ETF flows, interest rates, and risk appetite to find explanations. The platform uses USDT as the core funding entry, connecting digital assets, US/HK stocks, and fiat currency exchange scenarios through a single account. It also supports converting digital currencies like BTC, USDT into fiat currencies such as USD and HKD for withdrawal to bank accounts. Placing different markets within the same observation framework makes it easier to judge whether capital is continuously diffusing into high-elasticity assets or if it's just a short-term rotation following BTC's breakout.
Especially when Bitcoin, the US dollar, US Treasury yields, and tech stocks are volatile simultaneously, looking at a single token in isolation makes it easy to misinterpret macro liquidity changes as independent project-specific movements. The recent rise of BCH and UNI is a typical example: driven by both the news catalyst from CME's derivative products and the combined influence of BTC's breakout, short covering, and overall improvement in risk appetite.
Finally
Therefore, instead of hastily concluding that "the altcoin season is back," it's better to first observe whether the capital diffusion can be sustained.
If institutional trading channels like CME gradually improve, BTC maintains relative strength, and spot capital continues willing to flow into high-elasticity assets, then the altcoin market might evolve from a rapid sentiment-driven diffusion into a more sustained market revaluation. Conversely, if BTC weakens again, macro liquidity tightens, or trading volume significantly declines after the news catalyst fades, this market movement might return to a BTC-dominated market structure.
From the current perspective, BCH and UNI are more like two representative samples in this round of market diffusion. What they tell the market is that after BTC's rise, capital has begun seeking higher-elasticity trading opportunities again, and the institutional derivatives market is gradually covering more altcoins.
As for whether this signifies a new, comprehensive altcoin season, it still requires time and capital flow data for verification.