South Korea's Debt Approaches 2,000 Trillion Won, Is the Market Overestimating Rate Hikes?

marsbitPublished on 2026-08-18Last updated on 2026-08-18

Abstract

South Korea's central bank raised its benchmark interest rate by 25 basis points to 2.75% on July 16, marking its first hike since January 2023. The move, driven by concerns over rising housing prices, household loan growth, and financial stability, comes as total household credit is nearing a critical threshold of 2,000 trillion won. While persistent high loan growth and inflation pressure the Bank of Korea (BOK) to maintain a hawkish stance, some market views, like that of M&G Investments, suggest expectations for further tightening may be overstated. They argue that improved corporate profits and tax revenues from the AI chip boom could reduce government bond issuance, potentially benefiting bond prices. The article highlights the tension between two forces: household debt and housing market risks pushing for continued policy tightening, and strong AI-driven exports offering macroeconomic support. The upcoming preliminary data on Q2 household credit and the BOK's future policy communications will be key in determining whether current market pricing for rate hikes is justified.

The Bank of Korea raised its benchmark interest rate by 25 basis points to 2.75% on July 16, citing housing prices, household loan growth, and financial stability pressures as policy considerations.

This marks the first rate hike in South Korea since January 2023. For investors, the question is not only about how high household debt is but also whether the central bank will be pushed back onto a tightening path by household leverage and housing prices.

The preliminary official figure for household credit in the second quarter will be released on August 19. As the balance reached 1,993 trillion won at the end of the first quarter, coupled with continued increases in household loans in May and June, the market is already pricing in a potential outcome: South Korea's household credit is approaching or exceeding 2,000 trillion won.
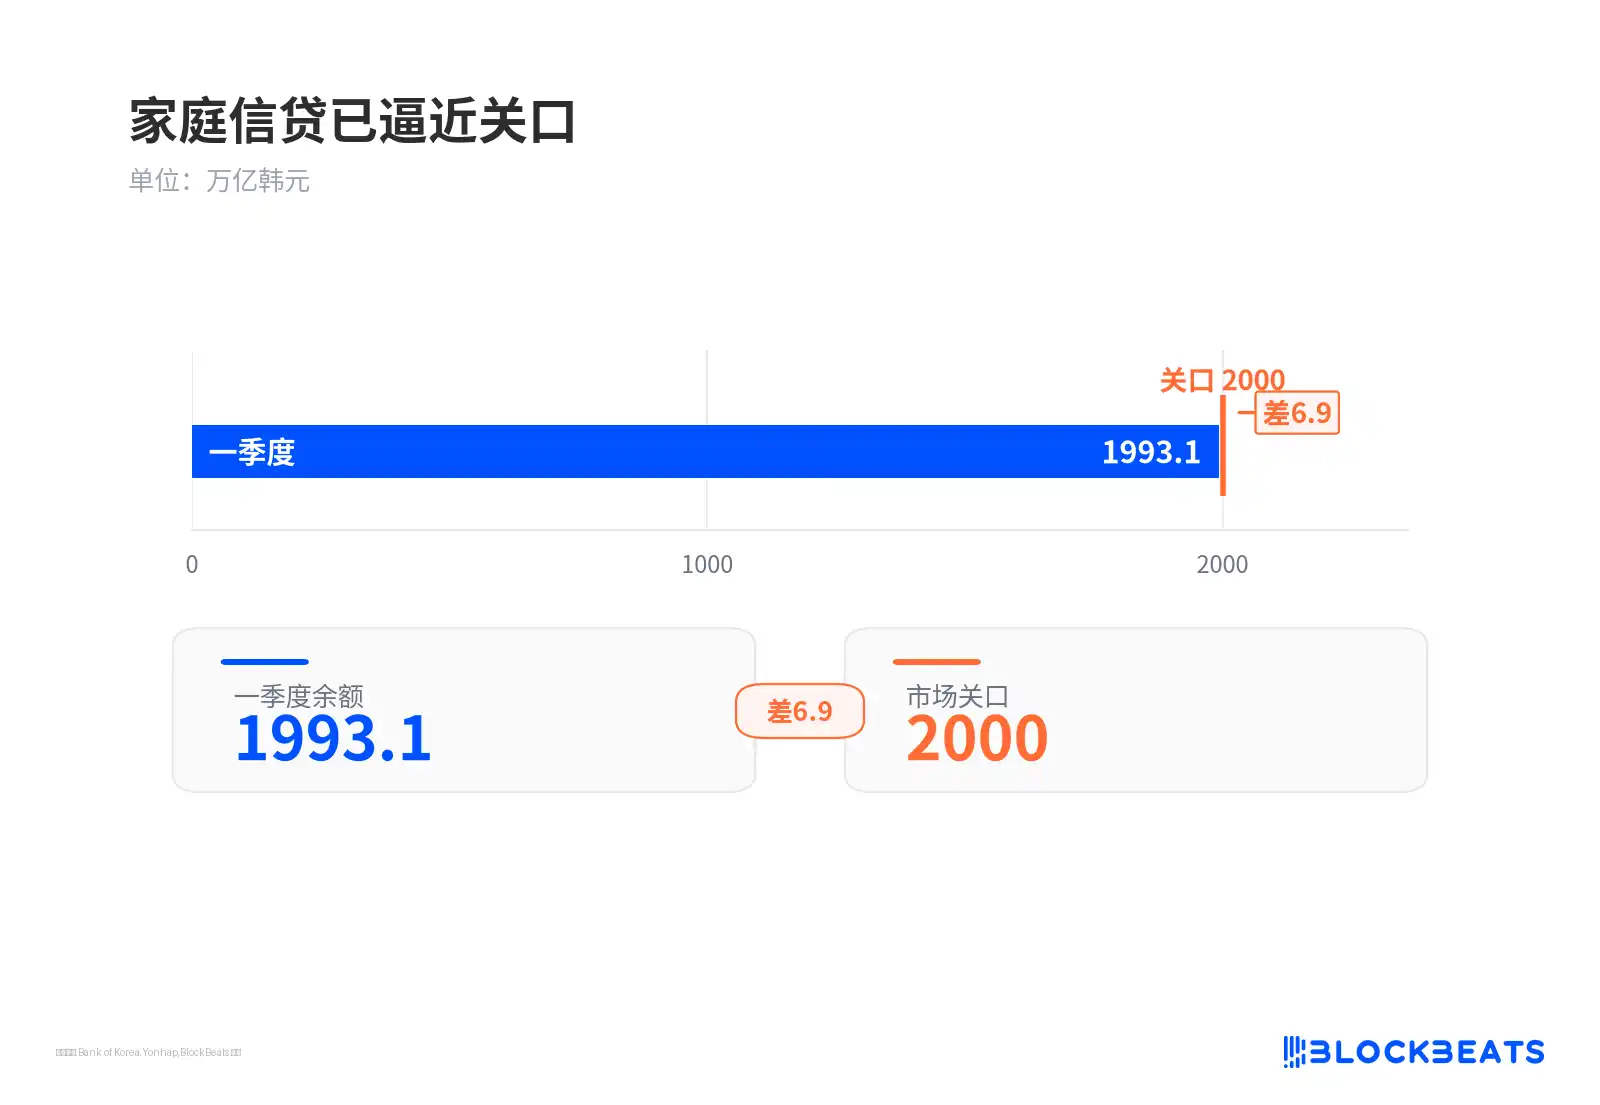
Household Credit is Approaching a Milestone

M&G Investments' Head of Asian Fixed Income, Low Guan Yi, holds a different view. According to media reports, his argument can be summarized as the market potentially overestimating the likelihood of further rate hikes by the Bank of Korea. Instead, improved corporate profits and tax revenue from the AI chip cycle could reduce government bond issuance needs.

This article does not focus on whether South Korea is entering a debt crisis. Rather, it examines which of the three forces—household leverage, inflation, and AI exports—will dominate interest rates and asset pricing in South Korea.

Household Loans Push the Central Bank Back into Hawkish Territory

The household credit balance refers to the total amount borrowed by households from financial institutions like banks and insurers, including mortgages, consumer loans, and stock financing loans. It is a stock burden, not a monthly flow.

The larger the stock, the more pronounced the cash flow amplification effect of an interest rate hike. For highly leveraged households, a 25-basis-point increase doesn't just alter monthly payments; it also affects home purchases, consumption, and risk asset allocation.

The Bank of Korea's July statement noted that housing prices are rising in the capital region and household loan growth is expanding. June CPI increased by 3.2% year-on-year, providing the central bank with an inflation-based justification for the hike.

More sensitive is the loan increment. Data from the Financial Services Commission shows household loans across the entire financial sector increased by 9.3 trillion won in May and 8.3 trillion won in June. Bank of Korea data also indicates that bank household loans increased by 7.6 trillion won in June, with mortgage loan balances reaching 945 trillion won.
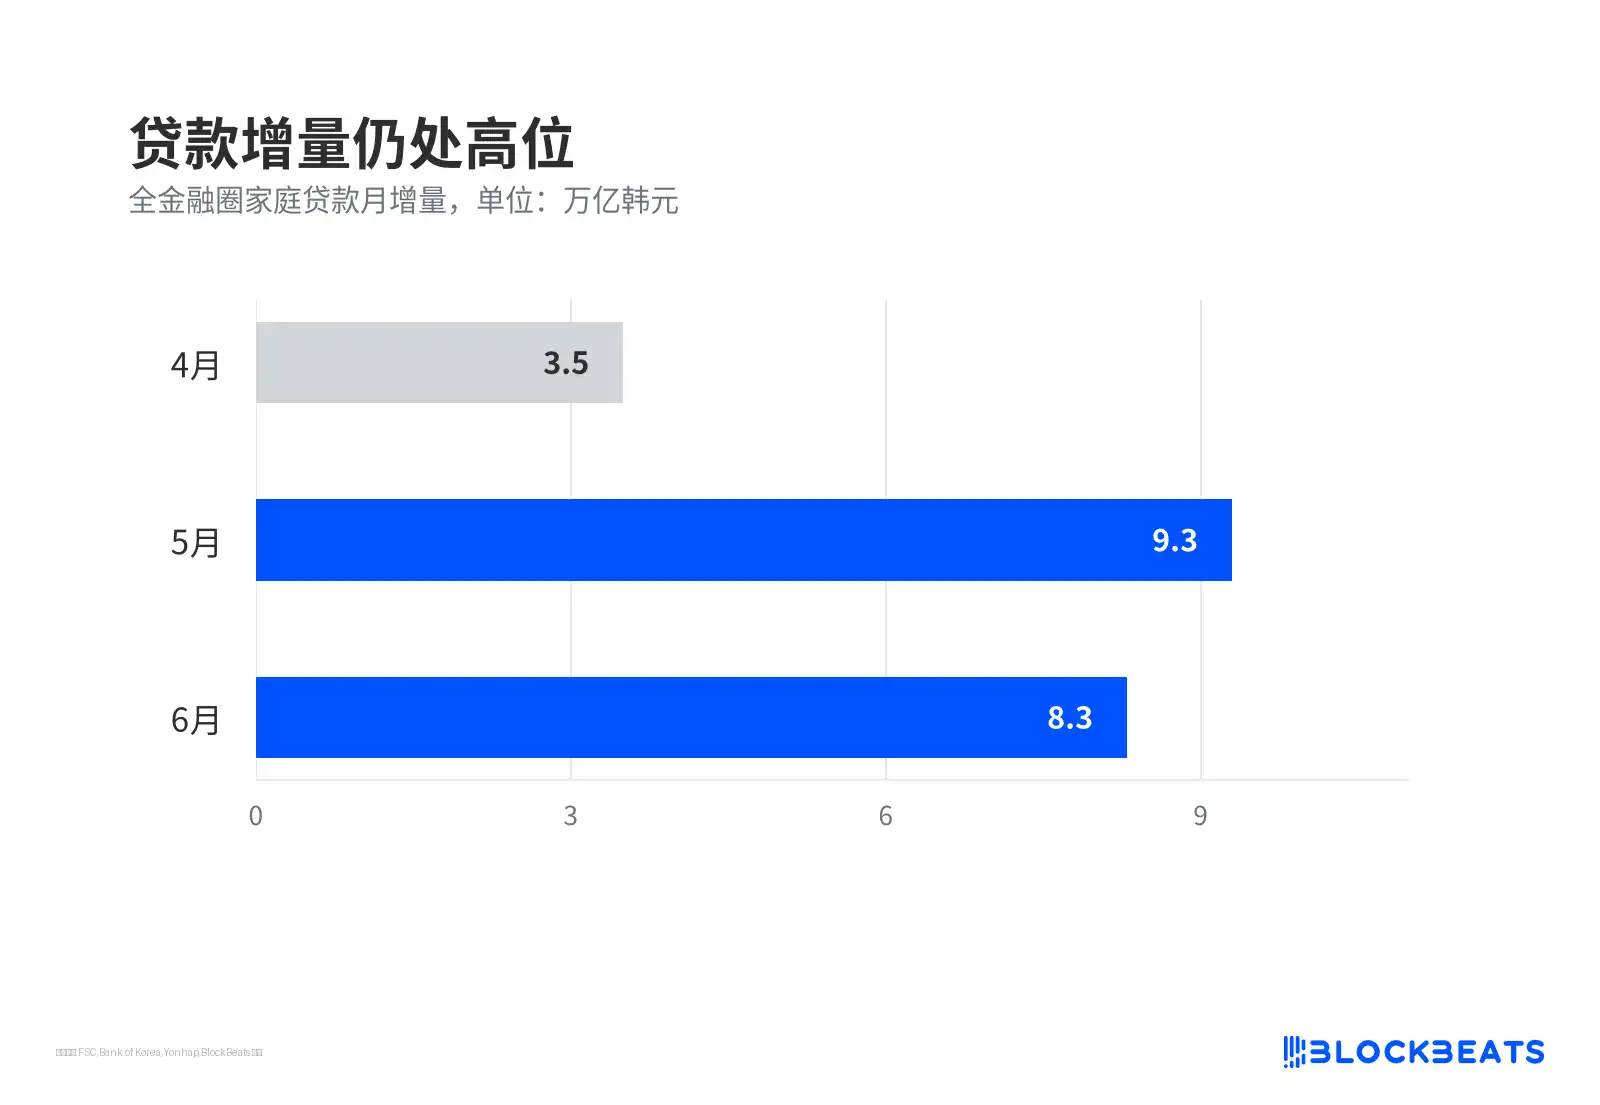
Loan Increment Remains Elevated

These numbers explain the central bank's constraint. As long as housing credit continues to expand, the central bank will find it difficult to pivot quickly toward easing, even as exports and corporate profits are improving.

M&G Bets Hawkish Rate Hike Expectations Are Excessive

M&G's contrarian logic does not deny debt pressure but questions whether pricing has run ahead of fundamentals.

Following this line of reasoning, if inflation is near a temporary peak, the necessity for additional rate hikes diminishes. If South Korea's semiconductor exports continue to benefit from AI demand, improved profits for companies like Samsung Electronics and SK Hynix will lead to a broader tax base.

Improved fiscal revenue could reduce government bond issuance needs. For bond investors, reduced supply pressure typically supports bond prices, potentially leading to a decline in South Korean government bond yields.

The appeal of this logic lies in its attempt to move South Korea beyond a simplistic high-debt narrative. The AI chip boom affects not only the stock market but may also impact bond supply through fiscal channels via taxes and government spending.

However, this remains a trading hypothesis yet to be verified. Low Guan Yi's view resembles an optimistic scenario more than market consensus. Whether AI exports translate into fiscal improvements depends on subsequent tax revenue and government bond issuance plans.

Property Market and Leveraged Positions Amplify Policy Difficulty

The complexity of South Korea's current pressures lies in the simultaneous occurrence of high household leverage and asset price rebounds. Increased mortgage loans indicate households are still using leverage to participate in the property market. Rising stock financing loans suggest the stock market rally is also attracting leveraged funds.

A rebound in capital region housing prices will make the central bank more cautious. While rising housing prices can temporarily support household balance sheets, they also stimulate further borrowing demand, creating new policy pressures.

If asset prices continue to rise, households can use paper wealth to buffer interest payment pressures, and banks' credit risks are less likely to surface. However, if rate hikes dampen transactions and both housing and stock prices weaken simultaneously, debt repayment pressures could transmit more quickly to consumption and bank asset quality.

This is also a variable that the Korean won and South Korean bank stocks need to monitor. The more hawkish the central bank, the more it may support the currency in the short term, but it also increases pressure on the household sector and bank asset quality. The earlier the central bank pivots dovish, the more bonds might benefit, but the won could then face pressure from interest rate differentials.

The stronger semiconductor exports are, the more growth and tax revenue are supported. The more willing the household sector is to increase leverage, the harder it is to ignore financial stability risks. South Korea is currently trading on the tug-of-war between these two forces.
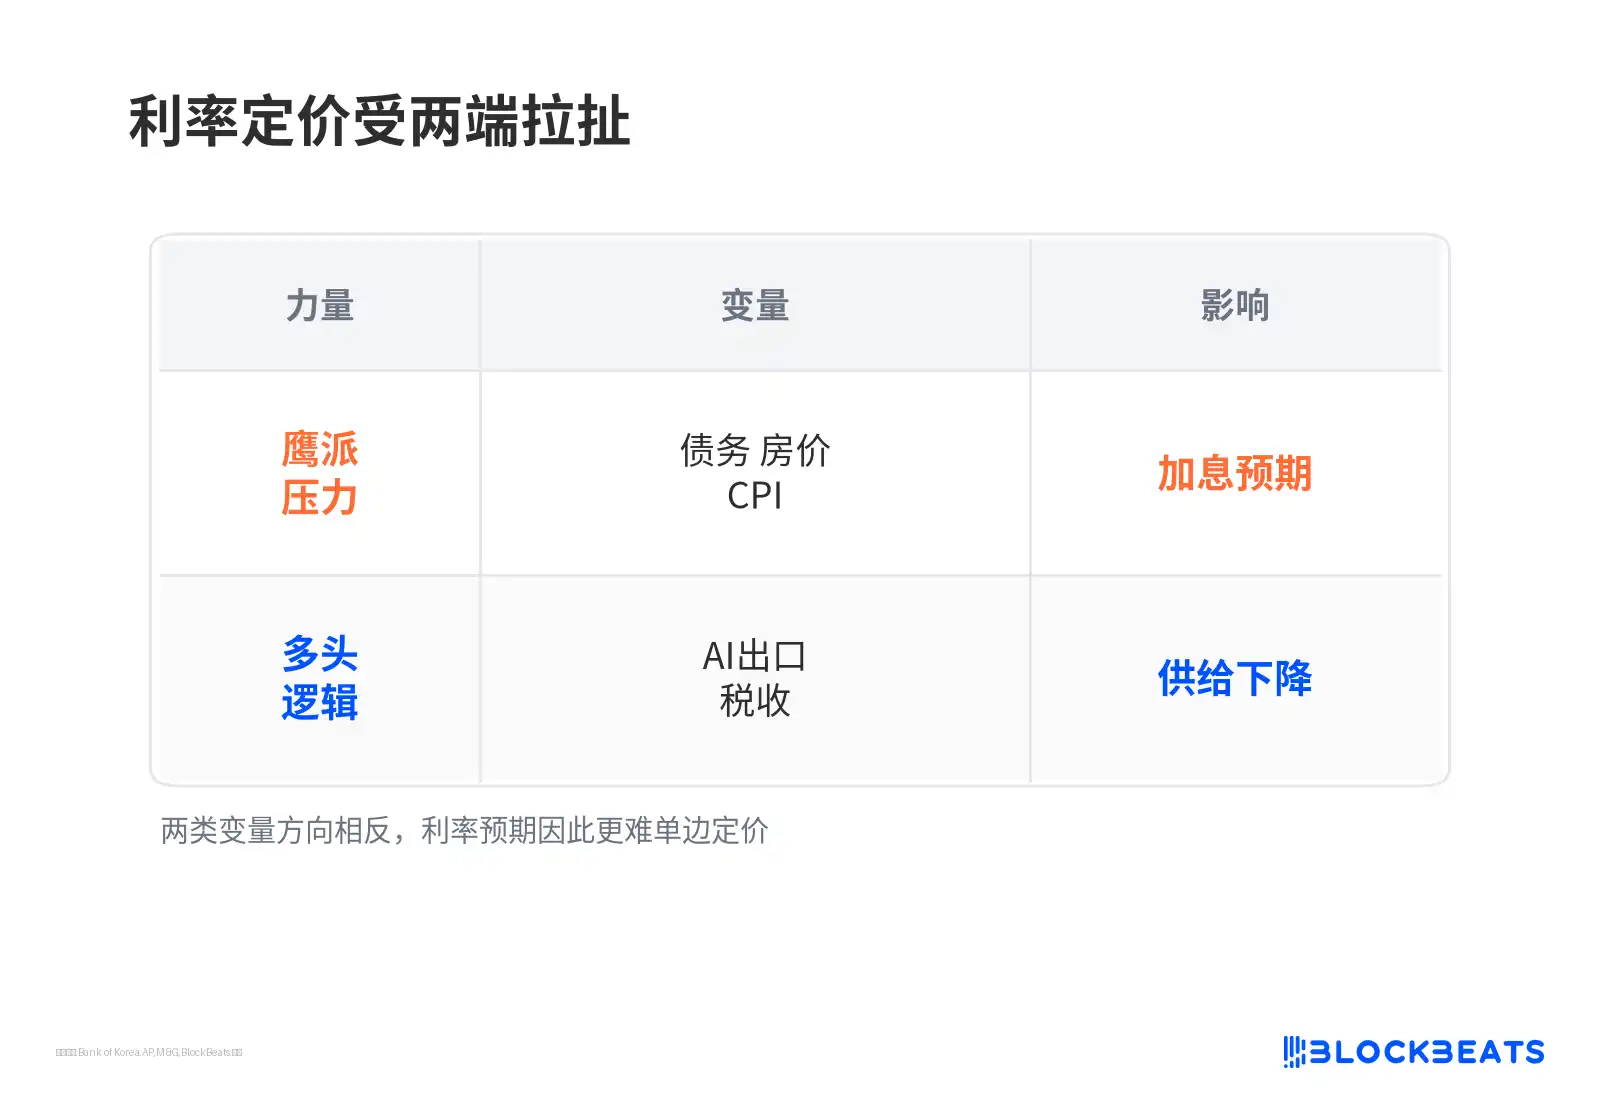
Interest Rate Pricing Pulled by Two Sides

Bond Bulls Await Cooling in Supply and Loans

The preliminary Q2 household credit figure on August 19 will first test the 2,000 trillion won milestone. If the balance is confirmed to have surpassed this level, the market will interpret it as a reason for the central bank to continue emphasizing financial stability.

The focus of the next monetary policy meeting may not solely be on whether to hike rates. More important is how the central bank describes inflation, household debt, and housing prices. If the statement continues to place significant weight on financial stability, subsequent hawkish pricing is unlikely to recede quickly.

Loan growth is a harder variable. As long as mortgage loan growth remains high, the household credit milestone will continue to constrain policy space. Only when new loan growth cools will the pressure on the central bank to hike further diminish.

The bond bull logic from M&G, however, awaits confirmation from the fiscal side. If the AI semiconductor boom is only reflected in stock prices and export data without significantly reducing government bond supply, the rationale for South Korean government bond appreciation weakens.

South Korea provides a clear case study: tech exports can improve the macro narrative but cannot immediately remove household leverage constraints. Investors must judge whether the market's pricing of the Bank of Korea's hawkish path has exceeded the level that subsequent data can support.

Trending Cryptos

Related Questions

QWhat are the two main forces that are creating tension and influencing market pricing for interest rates and assets in South Korea, according to the article?

AAccording to the article, the two main opposing forces creating tension are high household leverage, which pressures the central bank towards a hawkish policy to ensure financial stability, and the positive impact of the AI-driven semiconductor export boom, which could improve corporate profits and government tax revenues, potentially allowing for a less restrictive monetary policy.

QWhat key data point is the market anticipating on August 19th, and why is it significant for predicting the Bank of Korea's policy path?

AThe market is anticipating the preliminary official data for South Korea's second-quarter household credit. Its significance lies in the fact that the balance is expected to approach or even surpass 2,000 trillion won. A breach of this threshold would be interpreted as reinforcing the central bank's focus on financial stability and could justify maintaining a hawkish stance on interest rates.

QWhat is the core argument of M&G Investments' Low Guan Yi against the prevailing market expectation of continued rate hikes in South Korea?

ALow Guan Yi's core argument is that market expectations for further rate hikes may be too hawkish. He posits that the AI chip cycle could significantly boost corporate profits (e.g., for Samsung, SK Hynix) and consequently improve government tax revenues. Higher tax income might reduce the government's need to issue bonds, decreasing bond supply pressure and potentially lowering yields, which could change the calculus for monetary policy tightening.

QHow does the simultaneous increase in housing prices and household debt complicate the policy decision for the Bank of Korea?

AThe simultaneous increase complicates policy because rising housing prices can temporarily bolster household balance sheets, but they also stimulate further borrowing demand, creating a self-reinforcing cycle that increases financial stability risks. The central bank faces a dilemma: tightening policy (hiking rates) could cool the market and contain debt but risk triggering a downturn in asset prices that would worsen debt-servicing capacity. Maintaining looser policy supports growth but lets leverage build further.

QWhat specific indicator, beyond the overall household credit balance, does the article suggest is a crucial 'hard variable' for the Bank of Korea's future policy decisions?

AThe article suggests that the growth rate of new household loans, particularly housing mortgage loans, is a crucial 'hard variable'. As long as the growth in new mortgage lending remains high, it will continuously constrain the central bank's policy space. A noticeable cooling in the pace of new loan origination would be a key signal that the pressure for further rate hikes might be diminishing.

Related Reads

Google and Meta Called Out for Benchmark Gaming

Recently, analysis firm SemiAnalysis accused tech giants Google and Meta of "benchmark gaming" with their AI models Gemini 3.8 Flash and Muse Spark 1.3. The accusation stems from a dramatic performance drop between two versions of the Terminal-Bench evaluation for AI agents. On the older, public Terminal-Bench 2.1, Gemini 3.8 Flash scored 89.4, ranking second and beating GPT-6 Astra, while Muse Spark 1.3 scored 88.8. However, on the newly released, more secure Terminal-Bench 4.0, their scores plummeted to 19.1 and approximately 33.3 respectively, far behind competitors. SemiAnalysis argues this indicates "benchmark contamination," where companies train models not on the public test questions themselves, but on expensive, privately purchased training data specifically designed to mimic the benchmark's style. This has evolved into a lucrative industry, with specialized firms selling tailored training tasks for thousands to hundreds of thousands of dollars. The article specifically points to Datacurve, a company that both sells expert coding data and runs its own benchmark (DeepSWE), where the accused models also performed well. Meta's Chief AI Officer, Alexandr Wang, dismissed the claims as a "silly argument," pointing out similar performance drops for other models like GPT-5.6 Sol. He stated Meta never claimed Muse Spark 1.3 was as powerful as top-tier models, only that it offered better value. The report concludes that this is the inevitable fate of all high-quality public benchmarks—they become "gamed" over time. The proposed solution of private, high-quality benchmarks comes with a significant downside: it would erode public transparency, turning open rankings into marketing tools and leaving developers without a common, fair measure to compare AI models.

marsbit2h ago

Google and Meta Called Out for Benchmark Gaming

marsbit2h ago

Crypto's Nouveau Riche Strikes Gold in the Real World: Coinbase Co-founder's Venezuelan Oil Field Adventure

Coinbase co-founder Fred Ehrsam is venturing into the oil fields of Venezuela, a surprising shift for a prominent figure in the digital asset space. Through his company Primavera Infinita, he recently secured a production contract for the Budare-Elotes block with Venezuela's state oil firm PDVSA. This move into a politically volatile, sanction-scarred country highlights a bet on high returns from its reopening under new leadership and shifting U.S. foreign policy. Ehrsam’s investment reflects a venture capital-style appetite for risk, targeting assets deeply discounted by political uncertainty. He is not alone; smaller, politically connected U.S. firms like Aspect Holdings and Hunt Oil are also entering, while established giants like ExxonMobil remain cautious due to past expropriations. To manage the complex, capital-intensive nature of oil, Ehrsam is assembling a professional team. This trend extends beyond Ehrsam. Other crypto wealth, like BitMEX's Arthur Hayes and Tether, is diversifying into traditional hard assets—energy, metals, and agriculture—seeking physical scarcity as a long-term anchor. Tether, for instance, took a controlling stake in agricultural giant Adecoagro. These moves signify crypto capital's evolving interest: not just tokenizing real-world assets (RWA), but directly acquiring and operating them. Ultimately, Ehrsam's gamble is less on oil geology and more on the duration of Venezuela's current political window. It underscores a broader narrative where digital-era wealth seeks stability and scale in the physical world's most traditional, immovable resources.

marsbit2h ago

Crypto's Nouveau Riche Strikes Gold in the Real World: Coinbase Co-founder's Venezuelan Oil Field Adventure

marsbit2h ago

Refuting the Ethereum 'Abandoning' ETH Narrative: What Does It Really Mean to Pay Gas Without ETH?

Title: Refuting the "Ethereum Abandoning ETH" Argument: What Does Paying Gas Without ETH Really Mean? The debate sparked by Vitalik Buterin's discussion of EIP-8141 (Frame Transactions), which suggests users could pay transaction fees without holding ETH, has led to extreme claims that ETH will lose its value. However, this perspective misunderstands the proposal. Currently, an Ethereum user initiating a transaction must also pay the network's Gas fee in ETH. EIP-8141 aims to decouple these actions. It allows a transaction to be split into separate "frames." A user could sign a transaction to, for example, send USDC, while a separate Paymaster account pays the required ETH Gas fee on their behalf. The user would then settle the cost with the Paymaster using USDC or another token. From the user's perspective, they pay in a stablecoin without interacting with ETH. Crucially, from the Ethereum protocol's perspective, the Gas is still paid in ETH; only the settlement layer between the user and Paymaster changes. This concept isn't entirely new; ERC-4337's Account Abstraction already allows similar Gas sponsorship. EIP-8141 seeks to integrate this capability more natively. The core goal is to drastically improve user experience by abstracting away the complexity of Gas, similar to how one pays with a credit card abroad without handling the local currency. It also enables atomic operations, like bundling token approval with a swap, which would revert together if the swap fails. Regarding ETH's value, the argument that "no ETH is needed" is incorrect. While users may not hold ETH, Paymasters and services must still acquire and spend ETH to pay network fees on the backend. The demand for ETH shifts from being distributed across millions of user wallets to being concentrated in the balances of these service providers. The key variable is whether this improved usability attracts significant new users and increases overall network activity. If it does, total ETH burned in fees could rise substantially. If it doesn't, the change merely reshuffles who holds the ETH needed for Gas. In summary, EIP-8141 aims to lower the entry barrier by hiding Gas complexity, betting that this will drive broader adoption and increase the fundamental utility—and thus demand—for the Ethereum network and ETH itself.

marsbit2h ago

Refuting the Ethereum 'Abandoning' ETH Narrative: What Does It Really Mean to Pay Gas Without ETH?

marsbit2h ago

Trading

Spot

Hot Articles

What is $BANK

Bank AI: A Revolutionary Step in the Future of Banking Introduction In an era marked by rapid advancements in technology, Bank AI stands at the intersection of artificial intelligence (AI) and banking services. This innovative project seeks to redefine the financial landscape, enhancing operational efficiency, security measures, and customer experiences through the power of AI. As we embark on this exploration of Bank AI, we will delve into what the project entails, its operational dynamics, its historical context, and significant milestones. What is Bank AI? At its core, Bank AI represents a transformative initiative aimed at integrating artificial intelligence into various banking operations. This project harnesses the capabilities of AI to automate processes, improve risk management protocols, and enhance customer interaction through personalized services. The primary objectives of Bank AI include: Automation of Banking Functions: By leveraging AI technologies, Bank AI aims to automate routine tasks, reducing the burden on human resources and enhancing efficiency. Enhanced Risk Management: The project utilises AI algorithms to predict and identify risks, thereby fortifying security measures against fraud and other threats. Personalization of Banking Services: Bank AI focuses on offering tailored financial products and services by analysing customer data and behaviours. Improving Customer Experience: The implementation of AI-driven solutions, such as chatbots and virtual assistants, aims to provide users with more human-like interactions, revolutionising the way customers engage with banks. With these goals, Bank AI positions itself as a crucial player in rendering banking more efficient, secure, and user-centric. Who is the Creator of Bank AI? Details regarding the creator of Bank AI remain unknown. As such, no specific individual or organisation has been identified in the available information. The anonymity surrounding the project's inception raises questions but does not detract from its ambitious vision and objectives. Who are the Investors of Bank AI? Similar to the project's creator, specific information regarding the investors or supporting organisations of Bank AI has not been disclosed. Without this information, it is challenging to outline the financial backing and institutional support that might be propelling the project forward. Nevertheless, the importance of having a robust investment foundation is pivotal for sustaining development in such an innovative field. How Does Bank AI Work? Bank AI operates on several innovative fronts, focusing on unique factors that differentiate it from traditional banking frameworks. Below are key operational features: Automation: By applying machine learning algorithms, Bank AI automates various manual processes within banks. This results in reduced operational costs and allows human workers to redirect their efforts towards more strategic activities. Advanced Risk Management: The integration of AI into risk management practices equips banks with tools to accurately predict potential threats such as fraud, ensuring that customer information and assets remain secure. Tailored Financial Recommendations: Through continuous learning from customer interactions, the AI systems develop a nuanced understanding of user needs, enabling them to offer tailored advice on financial decisions. Enhanced Customer Interactions: Utilizing chatbots and virtual assistants powered by AI, Bank AI enables a more engaging customer experience, allowing users to have their queries resolved quickly, thus reducing wait times and improving satisfaction levels. Together, these operational features position Bank AI as a pioneer in the banking sector, establishing new benchmarks for service delivery and operational excellence. Timeline of Bank AI Understanding the trajectory of Bank AI requires a look at its historical context. Below is a timeline highlighting important milestones and developments: Early 2010s: The conceptualization of AI integration into banking services began to gain attention as banking institutions recognised the potential benefits. 2018: A marked increase in the implementation of AI technologies occurred when banks started using AI tools like chatbots for basic customer service and risk management systems for improved security handling. 2023: The sophistication of AI continued to advance, with generative AI being introduced for more complex tasks such as document processing and real-time investment analysis. This year marked a significant leap in the capabilities afforded to banks by AI technology. 2024-Current Status: As of this year, Bank AI is on an upward trajectory, with ongoing research and developments poised to further enhance capabilities in banking operations. Continued exploration of AI applications hints at exciting developments yet to come. Key Points About Bank AI Integration of AI in Banking: Bank AI focuses on adopting artificial intelligence to streamline banking processes and improve user experiences. Automation and Risk Management Focus: The project strongly emphasizes these areas, aiming to shift the burden of routine tasks while enhancing security frameworks through predictive analytics. Personalized Banking Solutions: By harnessing customer data, Bank AI enables tailored banking services that cater to individual user needs. Commitment to Development: Bank AI remains committed to ongoing research and development efforts, ensuring its adaptability and ongoing relevance as technology continues to evolve. Conclusion In summary, Bank AI exemplifies a crucial step forward in the banking industry, leveraging artificial intelligence to reshape operational paradigms, enhance security, and promote customer satisfaction. Despite gaps in information surrounding the creator and investors, the clear objectives and functional mechanisms of Bank AI provide a strong foundation for its ongoing evolution. As AI technology continues to advance and merge with the banking sector, Bank AI is well-positioned to significantly impact the future of financial services, enhancing the way we understand and interact with banking.

2.0k Total ViewsPublished 2024.04.05Updated 2024.12.03

What is $BANK

How to Buy BANK

Welcome to HTX.com! We've made purchasing Lorenzo Protocol (BANK) simple and convenient. Follow our step-by-step guide to embark on your crypto journey.Step 1: Create Your HTX AccountUse your email or phone number to sign up for a free account on HTX. Experience a hassle-free registration journey and unlock all features.Get My AccountStep 2: Go to Buy Crypto and Choose Your Payment MethodCredit/Debit Card: Use your Visa or Mastercard to buy Lorenzo Protocol (BANK) instantly.Balance: Use funds from your HTX account balance to trade seamlessly.Third Parties: We've added popular payment methods such as Google Pay and Apple Pay to enhance convenience.P2P: Trade directly with other users on HTX.Over-the-Counter (OTC): We offer tailor-made services and competitive exchange rates for traders.Step 3: Store Your Lorenzo Protocol (BANK)After purchasing your Lorenzo Protocol (BANK), store it in your HTX account. Alternatively, you can send it elsewhere via blockchain transfer or use it to trade other cryptocurrencies.Step 4: Trade Lorenzo Protocol (BANK)Easily trade Lorenzo Protocol (BANK) on HTX's spot market. Simply access your account, select your trading pair, execute your trades, and monitor in real-time. We offer a user-friendly experience for both beginners and seasoned traders.

7.6k Total ViewsPublished 2025.05.09Updated 2026.06.02

How to Buy BANK

Discussions

Welcome to the HTX Community. Here, you can stay informed about the latest platform developments and gain access to professional market insights. Users' opinions on the price of BANK (BANK) are presented below.

活动图片