Hyperliquid Trading Volume Soars, So Why Are Profits Falling?

marsbitPublished on 2026-08-11Last updated on 2026-08-11

Abstract

Hyperliquid, a leading decentralized perpetuals trading platform, has seen its open interest surge to a record high above $11 billion, capturing roughly 9% of the global market share. Trading volume remains robust, nearing $178 billion over 30 days, driven largely by the explosive growth of third-party markets offering tokenized real-world assets (RWAs) like stocks and commodities. Despite this growth, the platform's protocol revenue has declined for four consecutive quarters, falling 43% from its Q3 2025 peak of $357 million to approximately $202 million in Q2 2026. This divergence is primarily attributed to the HIP-3 governance proposal, which allows external developers to launch their own markets and keep up to half of the generated fees. These third-party markets now account for nearly 50% of total volume. Consequently, the share of revenue redistributed to developers, market makers, and the treasury has tripled from 6% to 18% in a year. This directly reduces the funds allocated to the platform's buyback-and-burn mechanism for its native HYPE token, weakening a key price support. HYPE's price has fallen 28% from its all-time high. The platform's growth is also heavily concentrated, with a single entity, Trade.xyz, responsible for over 90% of HIP-3 open interest, introducing systemic risk. Additionally, the ecosystem lacks diversity beyond HYPE, faces ongoing token unlocks adding sell pressure, and is encountering increased regulatory scrutiny and new competition from p...

Open interest on the Hyperliquid platform has reached a record high, but the platform's retained trading fee revenue continues to shrink.

On July 13th, the total size of leveraged positions held by traders on the platform, known as open interest, climbed above $11 billion, setting a new high for Hyperliquid in 2026. Over the past 30 days, Hyperliquid's perpetual contract trading volume neared $178 billion. Currently, among all centralized exchanges, Hyperliquid accounts for about 9% of the global perpetual contract open interest, up from less than 7% at the end of May.

But platform revenue is moving in the opposite direction. Data from DeFiLlama shows that Hyperliquid's protocol revenue peaked at approximately $357 million in Q3 2025, then declined quarter-over-quarter to $295 million, $217 million, and approximately $202 million in Q2 2026. Amidst a continuous rise in transaction counts, platform revenue has fallen 43% from its peak.
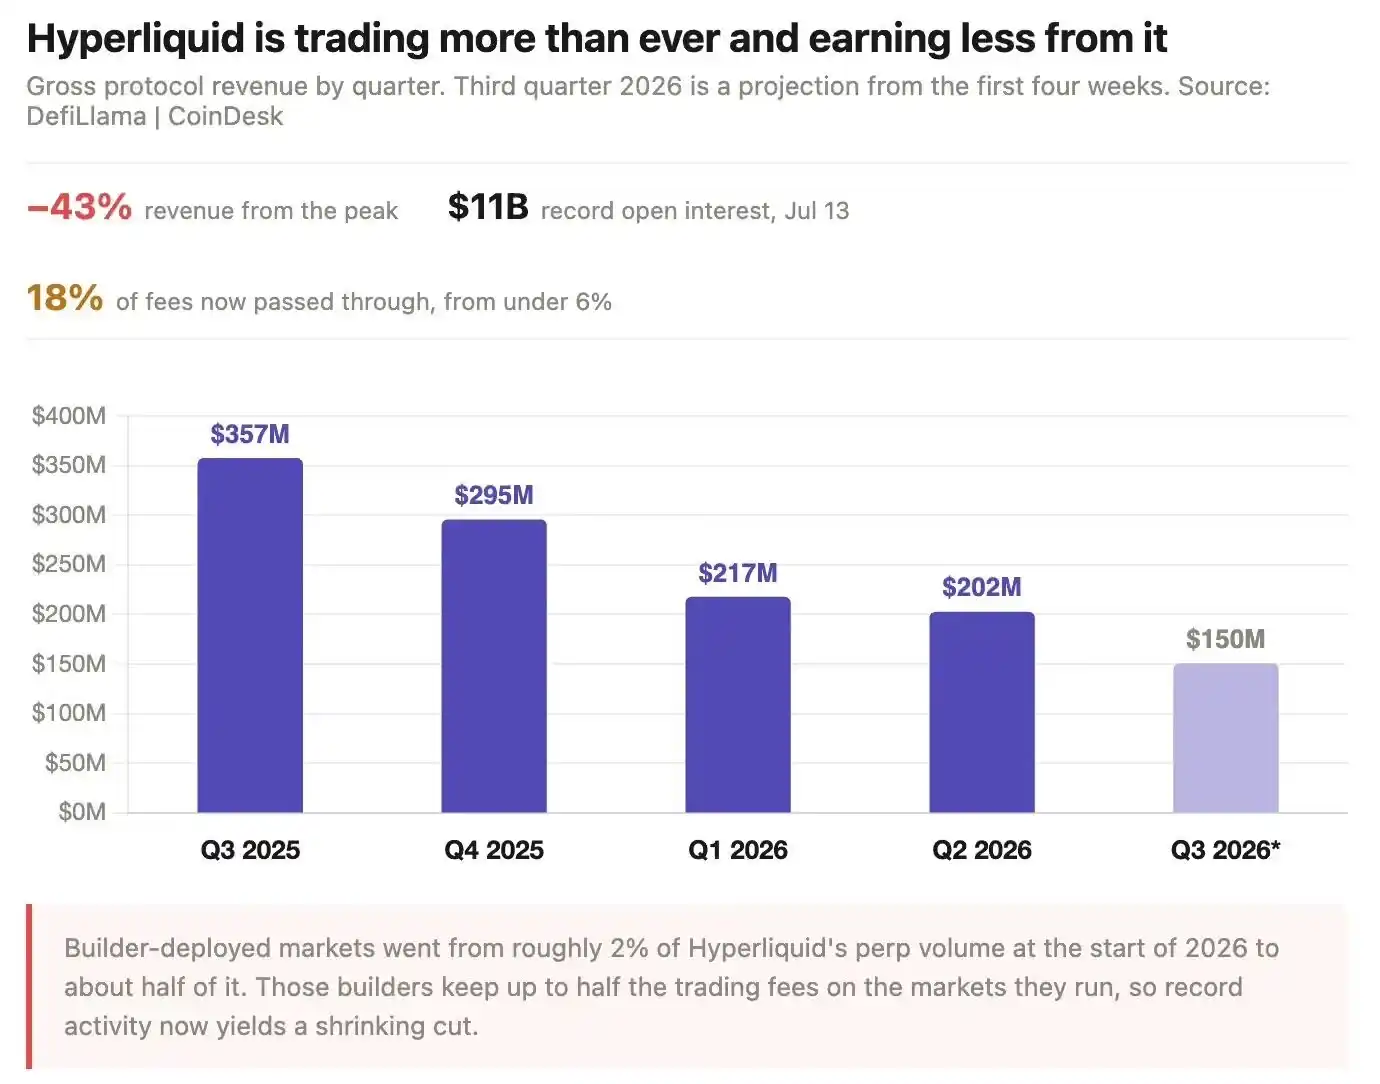
Hyperliquid's platform revenue has declined for four consecutive quarters

The Hyperliquid Improvement Proposal HIP‐3 explains why the platform cannot retain all the profits generated by its own business. Since October 2025, anyone staking 500,000 HYPE tokens (worth about $28 million at current prices) can deploy their own perpetual contract market on Hyperliquid's order book and claim up to half of the trading fees.

At the beginning of 2026, these externally deployed markets accounted for only 2% of Hyperliquid's perpetual contract trading volume; today, that share is close to 50%.

Revenue data clearly shows the impact of this revenue sharing. The portion of trading fees directly returned by Hyperliquid to developers, market makers, and the platform's liquidity treasury was just 6% of total revenue in Q2 2025; a year later, that proportion had reached 18%.

In Q2, developer fee revenue generated by front-end routers like Phantom amounted to about $16 million, and this entire amount flowed out as cost expenditure, representing pure pass-through revenue.
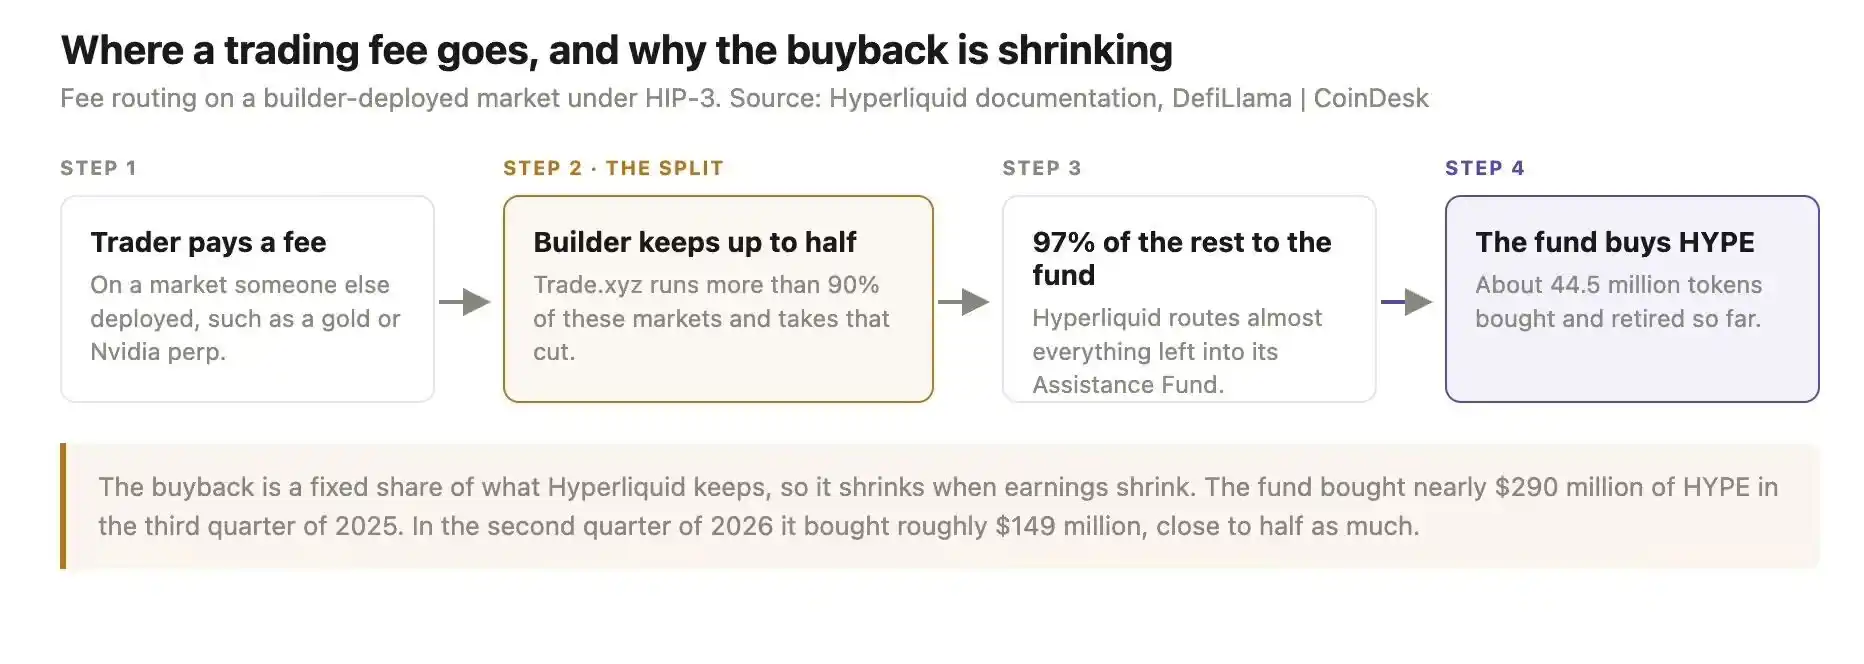
Flow of Trading Fees

The continuous influx of traders is driven by new product listings on these third-party markets: real-world asset (RWA) perpetual contracts. Contracts for crude oil, gold, Nvidia, Tesla, Nasdaq 100 tracking products, and even for unlisted companies like SpaceX, saw their open interest hit a new high of $3.6 billion this month, surpassing Bitcoin to become the platform's largest trading market by volume.

From July 13th to July 19th, trading volume for tokenized stock and commodity contracts reached $25 billion, accounting for 52% of the week's total volume and exceeding cryptocurrency perpetual contracts for the first time. Settled in stablecoins with no expiry date, these contracts can be traded even on weekends when the NYSE is closed. For those wanting to trade leveraged Nvidia contracts at 2 a.m. on a Sunday, there are almost no other similar options available.

However, this round of growth is highly dependent on a single entity. Trade.xyz accounts for over 90% of the open interest under the HIP‐3 mechanism. This means Hyperliquid's impressive records are highly dependent on this deployer's oracle choices, margin parameter settings, and risk management capabilities.

The risks inherent in this model were exposed last Monday: a large trade on a low-liquidity Korean pre-market exchange caused Trade.xyz's SK Hynix contract to plummet 19%, triggering a wave of liquidations. The firm later agreed to compensate affected users.

Hyperliquid allocates about 97% of its trading fees to a buyback fund, which repurchases and burns HYPE tokens on the open market. So far, approximately 44.5 million HYPE have been burned from the total supply. The buyback amount is directly linked to platform profits; as profits fall, so does the buyback scale. In Q3 2025, the fund bought back nearly $290 million worth of HYPE; in Q2 2026, the buyback was about $149 million, nearly halved.

CoinDesk data shows HYPE traded near $55 last Friday, down 5% for the week, and about 28% below its all-time high of around $77 on June 16th. Based on an annualized revenue of roughly $785 million, the token's corresponding P/E ratio for its circulating market cap is about 16x, and about 70x on a fully diluted basis.

Over the past month, institutional holders like Multicoin Capital and Bitwise have transferred large amounts of HYPE tokens to exchanges.

The Hyperliquid ecosystem is actually quite thin. Among the 48 Hyperliquid ecosystem tokens tracked by CoinGecko, almost all the market capitalization is concentrated in HYPE. The second and third largest are Ethena's USDe (~$4.5 billion) and USDT0 (~$4 billion), both externally issued, cross-chain bridged stablecoins. The largest natively issued token on the platform is PURR, with a market cap of just $53 million, less than 0.5% of HYPE's market cap. The market's valuation of HYPE primarily stems from Hyperliquid's own business model, not a rich native application ecosystem.
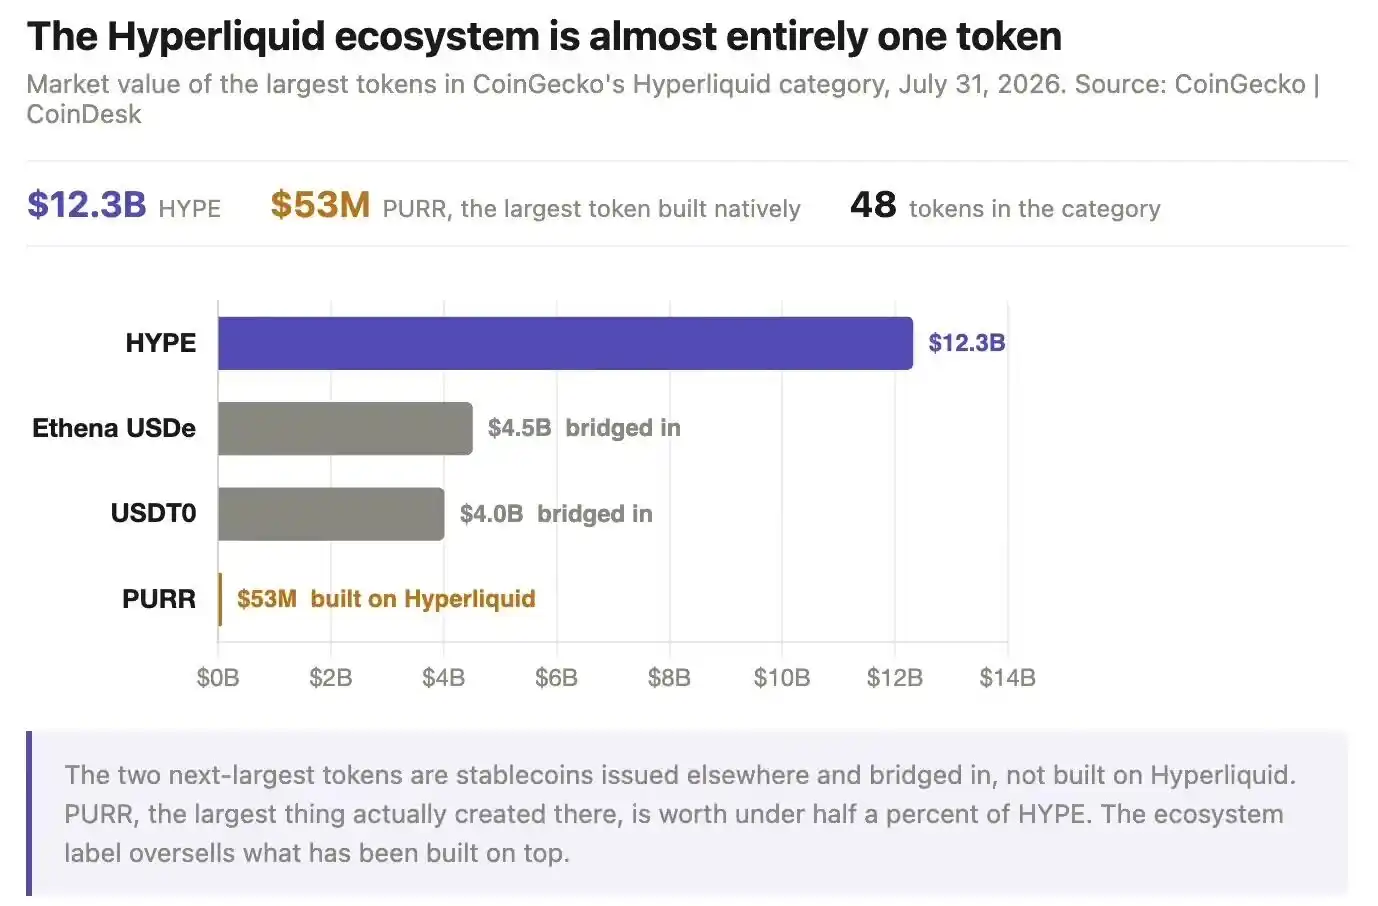
Hyperliquid ecosystem value is concentrated in HYPE

Token supply and regulators are applying simultaneous pressure. On August 6th, nearly 10 million HYPE were unlocked for core contributors, worth about $550 million at current prices; subsequent unlocks will continue monthly until 2027, while the total circulating supply of HYPE is only 222 million tokens.

For the week ending July 17th, the HYPE spot ETF saw its first weekly net outflow since inception, about $7 million, ending a nine-week streak of inflows. Singapore's MAS placed the platform on its investor alert list in late June, with the UK having issued a similar warning earlier; executives from CME and ICE have also urged the U.S. CFTC to review its commodity perpetual contract business.

Competition is also emerging from unexpected places. Just one month after brokerage Robinhood launched Robinhood Chain, daily settlement volume on its meme coin decentralized exchange has surpassed $600 million. By some measures, its daily speculative trading activity already exceeds that of Hyperliquid.

Of course, none of this necessarily means the platform is headed for failure. ARK research data shows that as of July 31st, Hyperliquid and Pump.fun together account for 67% of total crypto application revenue. Grayscale has also likened Hyperliquid to Amazon AWS: external developers build products on the platform, and the platform takes a cut from all transactions.

But this analogy precisely highlights the existing problem. In the first four weeks of Q3 2026, Hyperliquid's total revenue was approximately $45 million. If this pace continues, total revenue for the quarter would be close to $150 million, marking a fourth consecutive quarterly decline. The buy-side pressure supporting the HYPE token would then weaken further.

Related Questions

QDespite record trading volumes and open interest on Hyperliquid, why has the platform's revenue been declining for four consecutive quarters?

AHyperliquid's revenue is declining despite high trading activity primarily due to the HIP-3 proposal implemented in October 2025. This allows external developers to deploy their own perpetual markets on Hyperliquid's order book by staking 500,000 HYPE tokens. These developers can keep up to 50% of the trading fees generated on their markets. The share of trading volume from these third-party markets has grown from 2% in early 2026 to nearly 50%, significantly diverting fee revenue away from the core platform. Consequently, the portion of total revenue returned to developers, market makers, and the platform's liquidity vault has increased from 6% in Q2 2025 to 18% in Q2 2026, reducing the net revenue retained by Hyperliquid.

QWhat is the main driver behind the recent surge in trading activity and open interest on Hyperliquid?

AThe recent surge is primarily driven by the launch of new Real World Asset (RWA) perpetual contracts on third-party markets created under the HIP-3 mechanism. These contracts cover assets like crude oil, gold, stocks (e.g., NVIDIA, Tesla), the Nasdaq 100 index, and even private companies like SpaceX. They are settled in stablecoins, have no expiration, and can be traded 24/7, including on weekends when traditional exchanges are closed. This unique offering has attracted significant trading volume, with RWA contracts recently surpassing cryptocurrency perpetuals in weekly trading volume and becoming the platform's largest market by open interest.

QWhat are the key risks associated with Hyperliquid's current growth model?

AThe key risks are: 1. **Concentration Risk**: The growth is highly dependent on a single entity, Trade.xyz, which accounts for over 90% of the open interest in HIP-3 markets. Hyperliquid's performance is thus tied to this deployer's choices for oracles, margin parameters, and risk controls. 2. **Operational Risk**: An incident highlighted this vulnerability when a large trade on a illiquid Korean pre-market exchange caused Trade.xyz's SK Hynix contract to crash 19%, triggering mass liquidations. 3. **Revenue & Tokenomics Pressure**: The revenue-sharing model undercuts platform income, which directly reduces the amount of HYPE tokens bought back and burned from the Aid Fund, weakening a key value accrual mechanism for the HYPE token. 4. **Regulatory Scrutiny**: Authorities in Singapore, the UK, and the US (CFTC) have issued warnings or are reviewing the platform's commodity perpetuals business. 5. **Competition**: New competitors like Robinhood Chain are emerging, showing high daily settlement volumes in speculative trading.

QHow has the decline in Hyperliquid's revenue impacted the HYPE token?

AThe decline in revenue has negatively impacted the HYPE token in several ways: 1. **Reduced Buyback Pressure**: Approximately 97% of the platform's net trading fees go to an Aid Fund that buys back and burns HYPE tokens. As revenue falls, so does the buyback amount. For example, buybacks fell from ~$290 million in Q3 2025 to ~$149 million in Q2 2026. 2. **Price Decline**: The HYPE token price dropped about 28% from its all-time high in June 2026, with weekly declines reported. 3. **Valuation Metrics**: Based on annualized earnings of ~$785 million, the token's P/E ratio is about 16x for the circulating supply but 70x fully diluted, indicating high valuation pressure if earnings continue to fall. 4. **Selling Pressure**: Large institutional holders like Multicoin Capital and Bitwise have moved significant amounts of HYPE to exchanges recently. 5. **Unlock Schedule**: Ongoing monthly token unlocks for core contributors add further selling pressure to the market.

QAccording to the article, what is a major structural weakness in the Hyperliquid ecosystem beyond its core exchange business?

AA major structural weakness is the extreme lack of a diversified native application ecosystem. The Hyperliquid ecosystem is described as "extremely thin." Out of 48 tracked ecosystem tokens, almost all the value is concentrated in the HYPE token itself. The second and third largest tokens (USDe and USDT) are externally issued stable币 bridged from other chains. The largest natively issued token on the platform, PURR, has a market cap of only $53 million, which is less than 0.5% of HYPE's market cap. This indicates that the valuation of HYPE is almost entirely dependent on the trading platform's business model itself, rather than being supported by a rich and vibrant ecosystem of native applications built on top of it.

Related Reads

G7 Warning on Quantum Attacks Accelerates Transition to New Cryptographic Security System

The G7 cybersecurity working group urges countries and businesses to immediately begin transitioning to post-quantum cryptography, a warning directly relevant to crypto networks, exchanges, and custodians who must undertake costly system upgrades before quantum computers threaten modern encryption. Their report, while not mentioning cryptocurrencies specifically, highlights the risk quantum computing poses to public-key cryptography, which underpins crypto transactions. A key concern is the "harvest now, decrypt later" strategy, where encrypted data is collected for future decryption, a threat also applicable to blockchain's publicly visible keys. Europe has set concrete deadlines, mandating that all EU member states begin their transition by the end of 2026, with high-risk systems completing it by 2030. This shifts quantum readiness from a technical issue to a regulatory and competitive necessity. Bitcoin and Ethereum are pursuing different upgrade paths. Bitcoin's BIP-360 proposal aims to mitigate long-term quantum vulnerabilities, while Ethereum's broader roadmap targets upgrades to validator signatures, commitments, and zero-knowledge proofs by 2029. A major challenge is the increased data size of post-quantum signatures, which could raise storage, bandwidth, and transaction costs. The immediate market risk is not a quantum attack itself, but the complex preparation for it: governance debates, protocol development, infrastructure changes, and the vulnerability of old wallets with exposed keys. With entities like Google accelerating their migration timelines and NIST proposing phase-out dates for current standards, having a migration plan is becoming a competitive advantage.

cryptonews.ru7h ago

G7 Warning on Quantum Attacks Accelerates Transition to New Cryptographic Security System

cryptonews.ru7h ago

Trading

Spot
活动图片