Strategy Counters MSCI's Plan to Exclude MSTR from Global Indices

cryptonews.ruPublished on 2026-08-15Last updated on 2026-08-15

Abstract

Strategy Inc. (MSTR) has publicly challenged MSCI's proposal to exclude the largest corporate Bitcoin holder from its global equity indexes. The index provider's consultation introduces a two-step filter to identify "non-operating companies," where firms failing a primary operational assets test face further financial ratio screenings. MSTR, classified as such due to its Bitcoin treasury model, risks removal alongside firms like Yellow Cake and Metaplanet. MSCI estimates potential exclusion of three companies from its ACWI IMI index as of May, with MSTR being the only large-cap firm, facing an estimated $2.8 billion in passive fund outflows. The company argues that digital assets are legitimate and index providers should not dictate what assets companies hold. This new proposal replaces a previous, more crypto-specific rule that MSCI abandoned after criticism. With MSTR's stock trading close to the value of its Bitcoin reserves, its premium is minimal, and the availability of spot Bitcoin ETFs offers direct exposure without corporate risks. Feedback on the proposal closes September 30, with results announced by October 16 and any changes taking effect in November 2026.

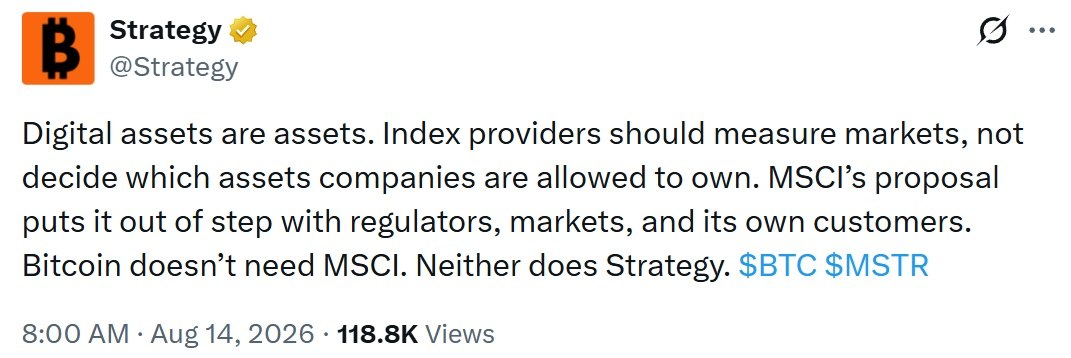
On August 14, Strategy Inc. (Nasdaq: MSTR) issued a public rebuttal to MSCI's statement after the index provider this month initiated consultations on excluding the largest corporate Bitcoin holder from its global equity indices. Funds that track these indices adjust their portfolios accordingly, turning the selection rule into automatic portfolio changes.

"Digital assets are assets," the company wrote on X, arguing that index providers should measure markets, not define what assets companies can own. Strategy stated that MSCI's proposal does not align with the stance of regulators, markets, and clients, adding that neither Bitcoin nor the company itself is dependent on the index provider.
As part of the consultation, MSCI proposes a two-stage filter for so-called "non-operating companies"—firms whose value appreciates due to assets on their balance sheet rather than business income. An issuer passes the first stage if operating assets constitute more than half of total assets.

How MSCI's New Filter Identifies 'Bitcoin Treasuries'

Issuers failing this primary test are then screened against five financial ratios covering operating asset intensity, expense intensity, operating cash flow, fair value intensity, and capital dependency. Four "red flags" out of these five deem a company unsuitable for inclusion in Global Investable Market Indices.

The proposal applies more lenient thresholds to current index constituents than to external candidates: starting with an operating asset share of less than 10% of the balance sheet and operating expense share of less than 5% of assets. Negative operating cash flow, excessive non-operating fair value fluctuations affecting both assets and revenue, and financing cash flow exceeding 30% of assets, along with reporting confirming external financing was raised to purchase assets, complete this set of criteria.

Index constituents must fail the criteria for two consecutive years before being removed, while new entrants lose eligibility after just one reporting period. MSCI follows a cautious policy to limit turnover, so a single instance of non-compliance does not lead to loss of index membership.

Which Companies Are Slated for Exclusion

MSCI's simulation using the MSCI All Country World Investable Market Index (ACWI IMI) identified three companies for exclusion as of May. Strategy was the only large-cap company among them, with a free-float adjusted market value of $23.93 billion.

Following it is London-listed uranium mining company Yellow Cake with a market value of $1.81 billion, and Tokyo-listed Metaplanet—$654 million; both companies fall into the small-cap category. Additionally, as of the end of the second quarter, Metaplanet held approximately 43,000 $BTC and uses these reserves as collateral for loans.
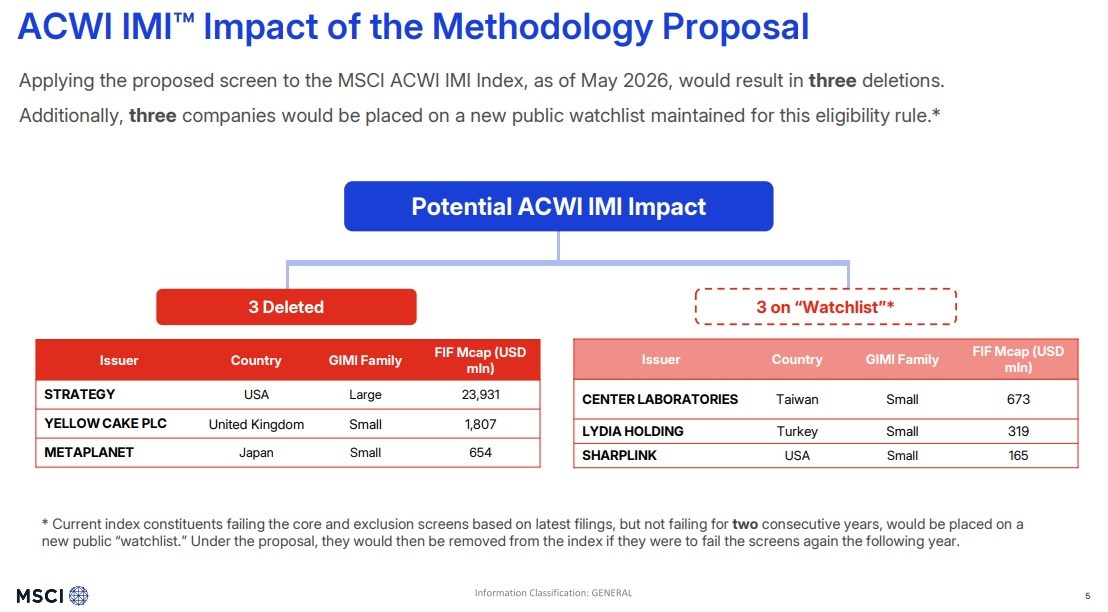
As a result of MSCI's simulation conducted in May 2026, Strategy was identified as the only large-cap company among three facing potential exclusion from the ACWI IMI index under the proposed selection criteria. Source: MSCI

Three more companies enter a new public watchlist: Taiwan's Center Laboratories with a market cap of $673 million, Turkey's Lydia Holding at $319 million, and SharpLink, managing ether reserves, at $165 million. Yellow Cake holds physical uranium, not tokens, indicating the selection criteria extend beyond digital assets.

A Rule MSCI Already Abandoned Once

In its previous attempt, MSCI singled out digital asset holding companies, defining them as issuers where half or more of total assets are cryptocurrency, and named 39 candidates. Executive Chairman Michael Saylor and CEO Phong Le signed a letter in December calling this threshold discriminatory, arbitrary, and unworkable.

That proposal was shelved on January 6, and MSCI promised a broader review of non-operating issuers. The new proposal contains no cryptocurrency threshold; however, it impacts Strategy through its treasury model mechanism, which raises equity and debt to accumulate Bitcoin.

According to the latest reporting, Strategy owns 840,447 $BTC, having bought roughly 175,000 coins this year and sold about 7,000. Le made it clear the company will resume purchases at the end of this year.

The Cost to Shareholders from an Index Exclusion

Passive investment funds follow index composition, so excluding a company from an index would force index funds to sell Strategy's shares or otherwise rebalance their position in the stock. JPMorgan analysts estimated outflows of around $2.8 billion if Strategy were removed from MSCI indices; this estimate was based on the withdrawn 2025 proposal, not the current one.

Strategy's shares trade close to the value of its Bitcoin portfolio: according to the company's dashboard, the mNAV ratio was about 1x on August 14. This ratio evaluates the company's market value relative to its own reserves. Such a small premium leaves shareholders with limited downside protection should index-tracking funds be forced to sell shares. It also indicates investors assign little additional value to Strategy's ability to raise debt, its capital-raising strategy, and corporate structure beyond its underlying Bitcoin assets.

Furthermore, spot Bitcoin ETFs provide exposure at near-par value without an intervening corporate balance sheet, weakening the argument for a stock premium. Investors can gain Bitcoin exposure without taking on Strategy-specific risks related to debt, convertible obligations, equity dilution, management decisions, or index eligibility. This alternative may cap the premium investors will pay for Strategy, especially when a potential benchmark exclusion creates an additional source of selling pressure.

The feedback period ends September 30, results will be announced by October 16, and any adopted changes will take effect during the index review in November 2026. MSCI notes consultations may or may not lead to changes, and watchlisted companies remain in the index until a second consecutive exclusion, meaning Center Laboratories, Lydia Holding, and SharpLink will face the same filter again next year.

Related Questions

QWhy is MSCI proposing to exclude companies like Strategy Inc. from its global indexes, and what is the core argument made by Strategy against this proposal?

AMSCI is proposing a two-step filter to identify and potentially exclude 'non-operational companies,' defined as firms whose value is driven by assets on their balance sheet rather than business earnings. Strategy Inc. argues that index providers should measure markets, not dictate what assets companies can own, stating that digital assets are legitimate assets and that MSCI's proposal is inconsistent with regulators, markets, and clients.

QWhat are the specific financial ratio criteria in MSCI's proposed filter that could lead to a company's exclusion, and how many 'red flags' trigger ineligibility?

AThe proposed filter uses five financial ratios: operating asset intensity, expense intensity, operating cash flow, fair value intensity, and capital dependency. A company becomes ineligible for inclusion in MSCI's Global Investable Market Indexes if it raises four 'red flags' out of these five criteria.

QAccording to the article, which companies were identified for potential exclusion from the MSCI ACWI IMI index as of May, and what was their market capitalization?

AAs of May, the simulation identified three companies for potential exclusion: Strategy Inc. (large-cap, $23.93B market cap), Yellow Cake (small-cap, $1.81B), and Metaplanet (small-cap, $654M). Three more companies were placed on a watchlist: Center Laboratories ($673M), Lydia Holding ($319M), and SharpLink ($165M).

QWhat was the estimated financial impact on Strategy Inc.'s shareholders if the company were to be excluded from MSCI indexes, according to analysts mentioned in the article?

AAnalysts at JPMorgan estimated that exclusion from MSCI indexes could result in outflows of approximately $2.8 billion. This estimate was based on a withdrawn 2025 proposal, not the current one.

QWhat is the deadline for feedback on MSCI's consultation, and when would any adopted changes take effect?

AThe deadline for feedback on MSCI's consultation is September 30. Results will be announced by October 16, and any adopted changes would take effect at the index review in November 2026.

Related Reads

Uniswap v4 Hook Ecosystem Heats Up: 8 Early Projects Lead the Race, Who Can Build Real Business?

The Uniswap v4 Hook ecosystem is heating up, with eight early-stage projects emerging to explore its potential for customizable trading pool rules. A Hook is an external smart contract attached to a Uniswap v4 liquidity pool, allowing developers to add custom logic before or after key actions like pool creation, liquidity provision, and trading. This enables features like dynamic fees, arbitrage profit redistribution, and complex token execution rules. The article highlights Hookr (a platform for easily composing and deploying Hooks), StonkBrokers (focusing on tokenized stocks and creating "Pair Tokens"), What The Hook (redistributing arbitrage profits), Programmable (a no-code/code launchpad for tokens with Hooks), Claus (an experimental, upgradeable Hook-based token), Fables Finance (a DEX combining Hooks with a ve(3,3) model), The Standard Reserve (a monetary policy experiment using Hooks), and Bordrless (a Solana-based project with a similar programmable token concept). However, the piece emphasizes significant risks for these early projects, including smart contract vulnerabilities, low liquidity and high volatility, and potential disconnects between a Hook's utility and its token's value. The key question remains: which projects can move beyond technical experimentation to build sustainable, real-world business models using Hooks? The ecosystem is growing, but true validation through user adoption and protocol revenue is still needed.

marsbit4m ago

Uniswap v4 Hook Ecosystem Heats Up: 8 Early Projects Lead the Race, Who Can Build Real Business?

marsbit4m ago

7 People, 5 Months: Anthropic Built a Git Replacement

In a surprising move, Anthropic replaced Git, the dominant version control system for two decades, with its own internally developed system named Scion. This migration was accomplished in just five months by a team of seven engineers, heavily assisted by their AI model, Claude. The primary driver was the explosive growth of AI-powered software development at Anthropic. By September, the company was handling over 30,000 code merges per day—a 12x increase in just four months—straining Git's decentralized, offline-friendly architecture which was not designed for such massive, centralized, and always-online agent-driven workflows. Scion was designed from the ground up for this new paradigm. Its core principles include: assuming clients (AI agents and automation) are always online; offloading complex computations (like blame, diff, merges) to scalable servers; providing a full API for source control queries to eliminate local repo needs for many tasks; and enabling highly efficient, sparse, and virtualized checkouts. Key to Scion's performance is its data structure. Instead of Git's commit-and-tree model, it uses a "Changeset" stored in a write-ahead log, which records only changed files. This allows for extremely high-throughput ingestion. Additional "derived data" structures are built on-demand for operations like blame and history queries. The new architecture employs a distributed, cache-heavy design with daemons (scion-daemon), regional caches (scion-cache), and authoritative servers (scion-server). This resulted in cache hit rates over 99%, a 200x reduction in CPU/memory usage compared to their previous Git mirror infrastructure, and code checkouts that are now seconds instead of minutes. Claude played a crucial role, not only in accelerating development but also in significantly improving code quality, performance, and test coverage. The project also led to innovations in security, access control, and system monitoring using AI "Superfans." Anthropic emphasizes that Scion is not a general-purpose Git replacement. It is tailored for massive monorepos driven by vast numbers of AI agents. However, they share their learnings in hopes that the broader ecosystem can adapt some of Scion's effective patterns—like server-side APIs and optimized protocols—to enhance Git for emerging large-scale, AI-augmented development environments.

marsbit41m ago

7 People, 5 Months: Anthropic Built a Git Replacement

marsbit41m ago

Trading

Spot
活动图片