Actually, the Largest Use Case for Stablecoin Payments Is Not Cross-Border

marsbitPublished on 2026-08-16Last updated on 2026-08-16

Abstract

Based on an analysis of $15.2 billion in identified on-chain stablecoin transfers, the data reveals that cross-border remittances represent only a portion of stablecoin demand. The dominant use case is domestic transfers, accounting for 62.6% ($9.5B) of the identified volume. Key markets include Turkey, South Korea, Mexico, Indonesia, and the US. This indicates stablecoins are widely used for domestic payments, transactions, and dollar-denominated savings within countries. Furthermore, 73.0% of all identified transaction volume (including domestic) stays within the sender's broader geographic region. The Asia-Pacific (APAC) region leads in stablecoin activity, contributing 41.0% of total sent volume and 41.6% of global domestic volume. It also shows a net inflow of funds, with Indonesia, Singapore, and South Korea being notable recipients. Major cross-border corridors already exist, such as Turkey-Indonesia and US-Mexico. Within APAC, corridors like Taiwan-Indonesia and Indonesia-South Korea show significant bilateral flows. For institutions, the key market opportunities currently lie in domestic settlement services and developing cross-border payment channels within the APAC region, which combines the largest transaction scale, high domestic usage, and positive net inflows.

Author: Heechang Kang, Four Pillars CSO

Compiled by: Jiahuan, ChainCatcher

This analysis is based on Allium's geographic payment data, covering $15.2 billion in identified on-chain transfers with known sending and receiving countries. As most on-chain transactions currently cannot be attributed to specific countries, the data in this article only reflects the identified sample.

Of this $15.2 billion in identifiable stablecoin transaction volume, 62.6% were domestic transfers. Of all identifiable transaction volume, 73.0% of funds ultimately flowed to the sender's region. Therefore, cross-border remittances are actually only one part of the current demand for stablecoins.

The Asia-Pacific (APAC) region is leading, accounting for 41.0% of total sent transaction volume and 41.6% of global domestic transaction volume, while also showing net inflows, with Indonesia, Singapore, and South Korea seeing particularly notable net inflows.

For institutions assessing stablecoin payment demand, domestic settlement services and cross-border payment channels in the Asia-Pacific region are currently the most noteworthy market opportunities.

1. Stablecoin Transactions Are Primarily a 'Domestic Business'
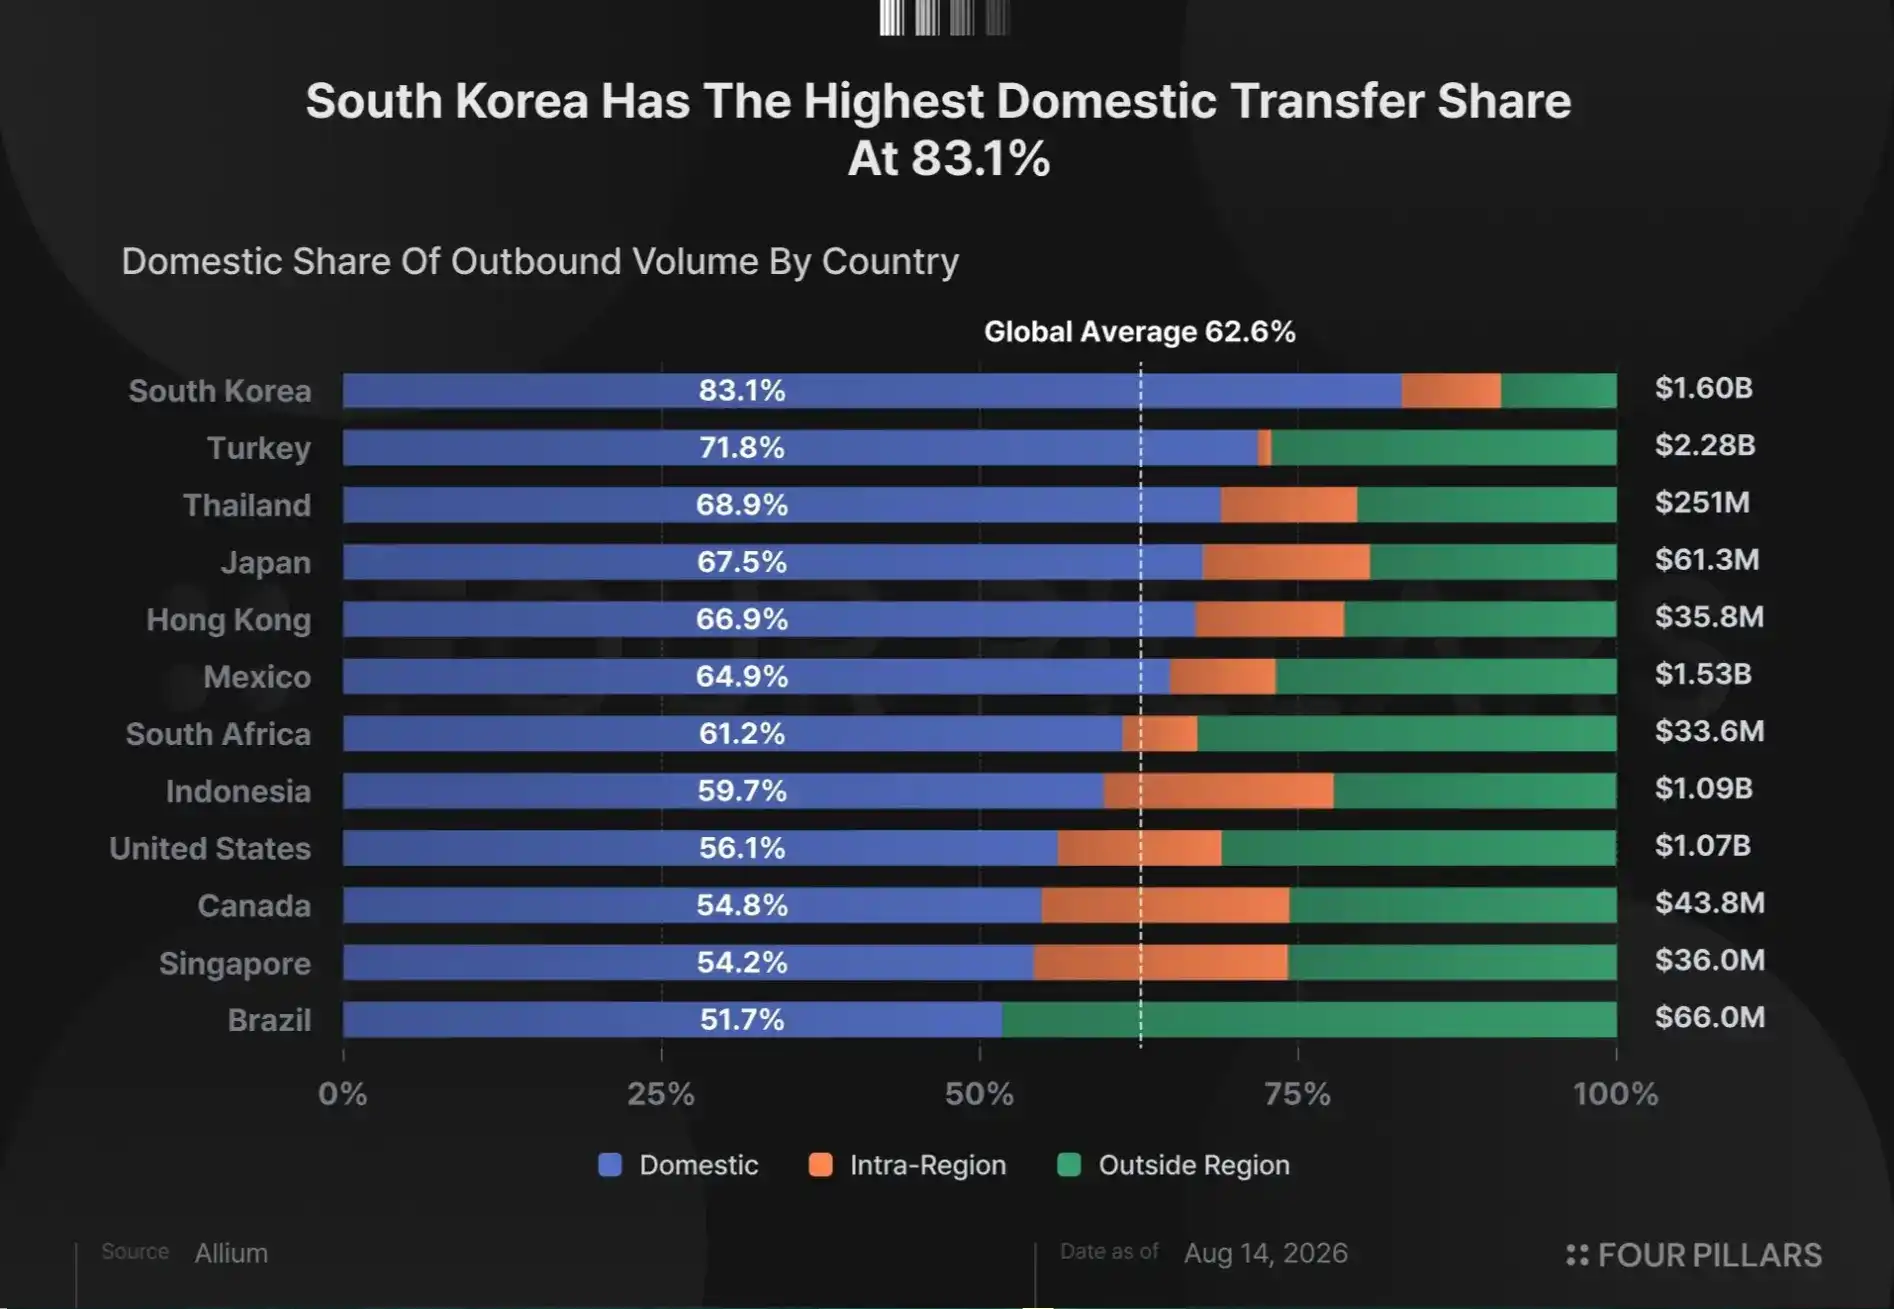
Domestic transfers, which occur between wallets located in the same country, amounted to $9.5 billion, constituting 62.6% of the $15.2 billion identifiable transaction volume.

Regardless of region or market size, domestic transfers represent the largest destination for funds in most markets with outflow activity.

Turkey ($2.28B), South Korea ($1.6B), Mexico ($1.53B), Indonesia ($1.09B), and the United States ($1.07B) together contributed 79.5% of global domestic stablecoin transaction volume.

These transactions are completed directly between public blockchain wallets, without the need to go through card networks or bank payment systems.

Such a large volume of domestic transactions indicates that users are employing stablecoins within their local markets for payments, trading, and US dollar-denominated savings. Therefore, cross-border remittances are just one part of the stablecoin use case.

For institutions designing stablecoin services, domestic payments and settlements currently correspond to a larger actual transaction volume compared to focusing solely on cross-border remittances.

2. After Crossing Borders, Funds Also Prefer to Stay Within the Region
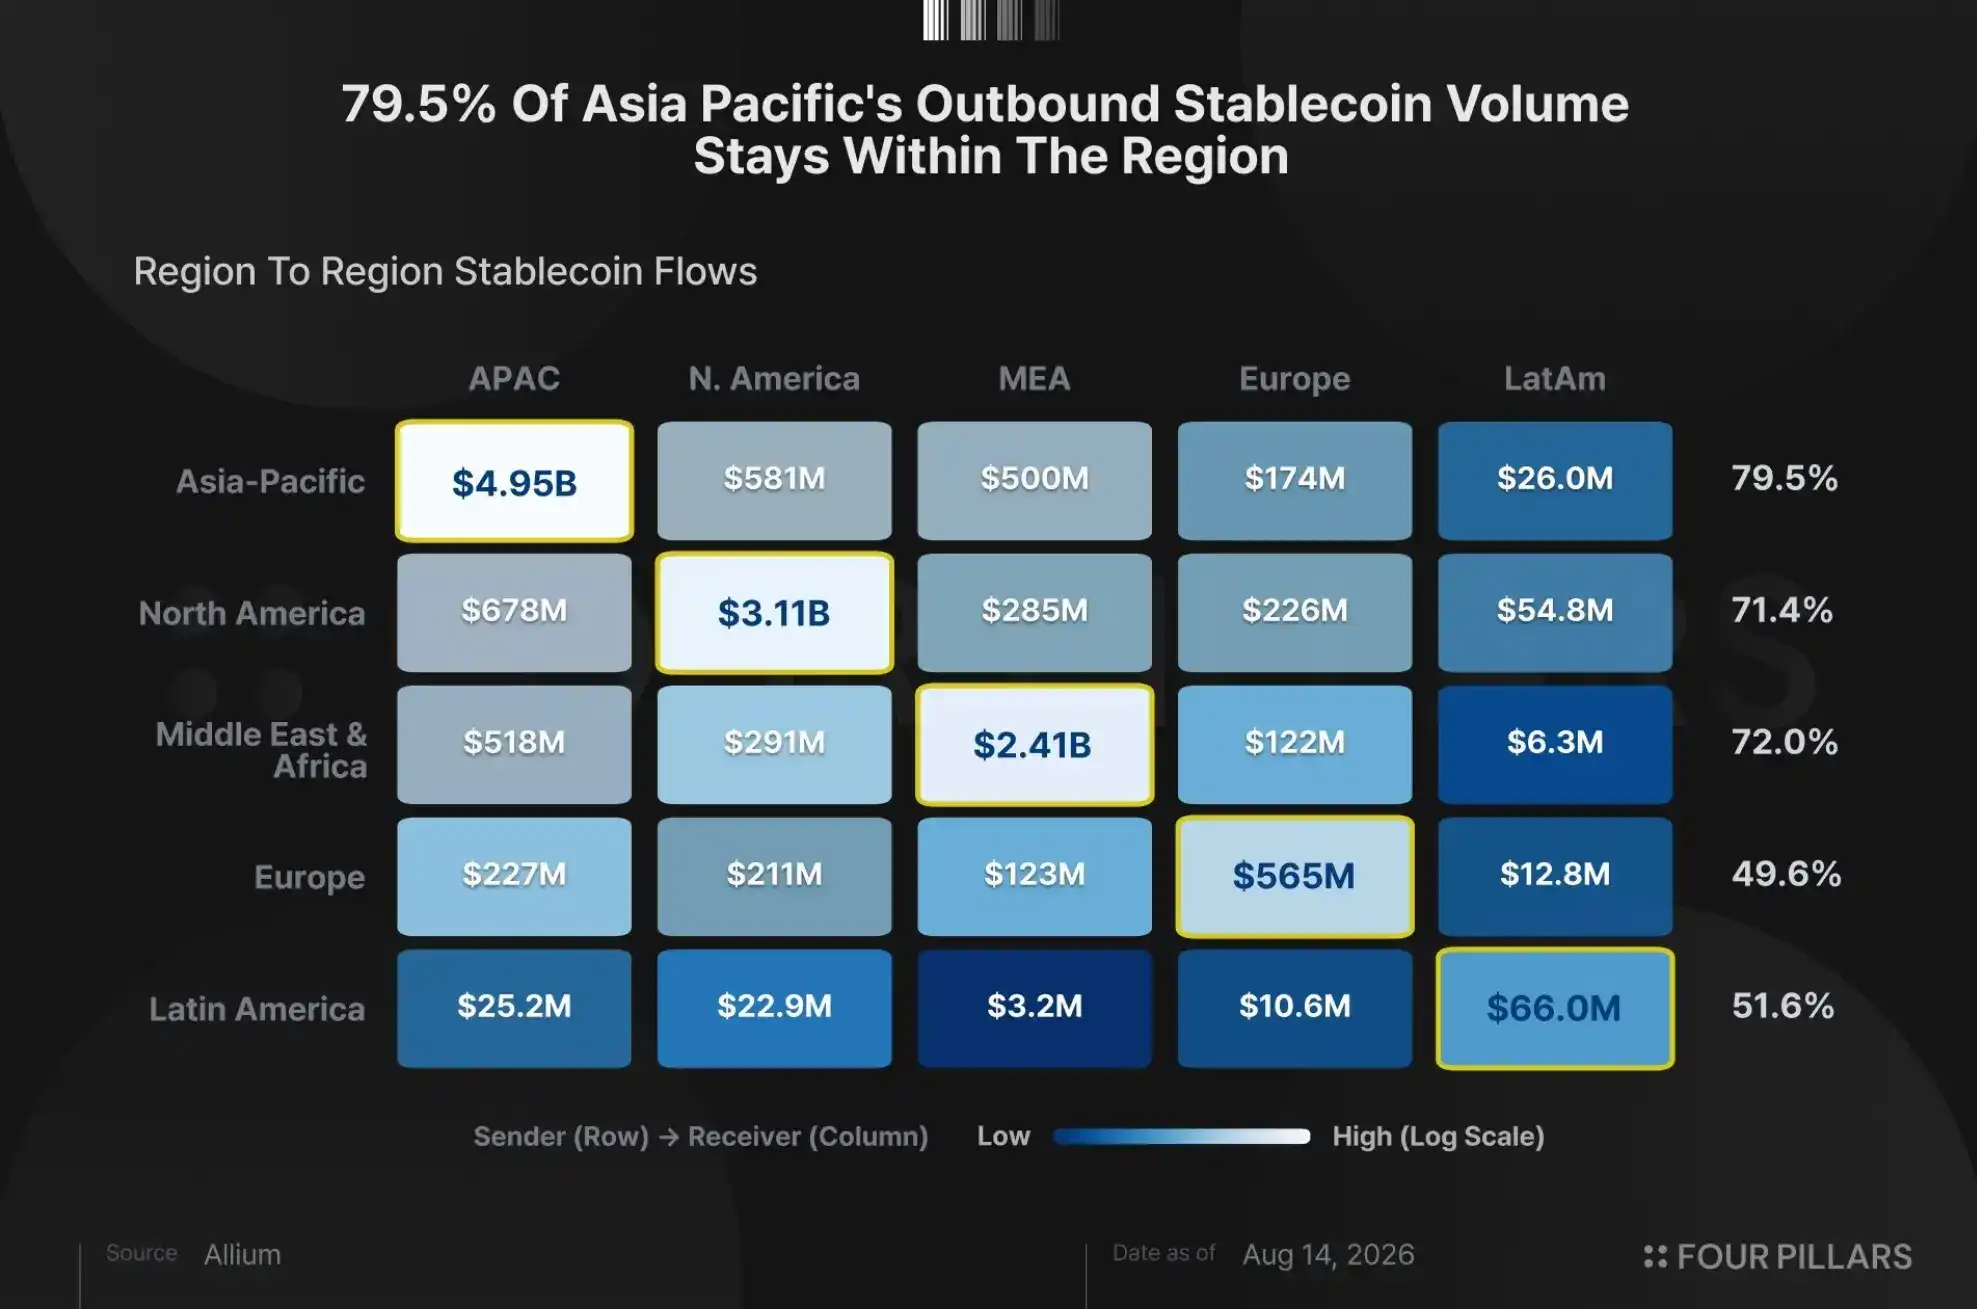
Including domestic transfers, 73.0% of transaction volume occurs within the sender's region, meaning within the same continent.

Specifically, 79.5% of funds from APAC remain within the region, followed by the Middle East and Africa at 72.0%, North America at 71.4%, and Europe at 49.6%.

Looking at fund flows between regions, transactions are clearly concentrated within regions, meaning most identifiable stablecoin transactions currently still occur within the sender's region.

Excluding domestic transfers, within the $5.68 billion cross-border transaction volume, the share of intra-regional transactions drops to 27.8%.

Here, APAC's intra-regional transaction share remains high at 43.7%, or $995 million out of $2.28 billion in cross-border transactions. In contrast, North America is at 27.0%, and the Middle East and Africa is only 6.3%.

As the largest market in the Middle East and Africa, most of Turkey's cross-border stablecoin funds flow to Asia and the Americas.

Within APAC, transaction volumes for Taiwan to Indonesia ($138 million), Indonesia to Taiwan ($124 million), and Indonesia to South Korea ($89 million) are already substantial.

The existing transaction volumes provide a foundation for building regional stablecoin payment infrastructure in APAC.

Indonesia, Taiwan, South Korea, Australia, and Thailand together participated in approximately $1 billion in intra-regional cross-border transactions, while also generating $3.96 billion in domestic transaction volume.

Institutions can use these existing liquidity flows and bilateral demands to determine which cross-border payment corridors are worth prioritizing.

For institutions planning to build regional payment infrastructure, cross-border corridors such as Taiwan to Indonesia and Indonesia to South Korea have already formed quantifiable bilateral demand, providing a market basis for early investment.

Currently, transactions where Allium can identify both sending and receiving countries account for only 2.9% of all observed transaction volume. As more transactions have their country information identified, the rankings of these current cross-border corridors may still change.

3. APAC Has Become the Largest Stablecoin Transaction Market
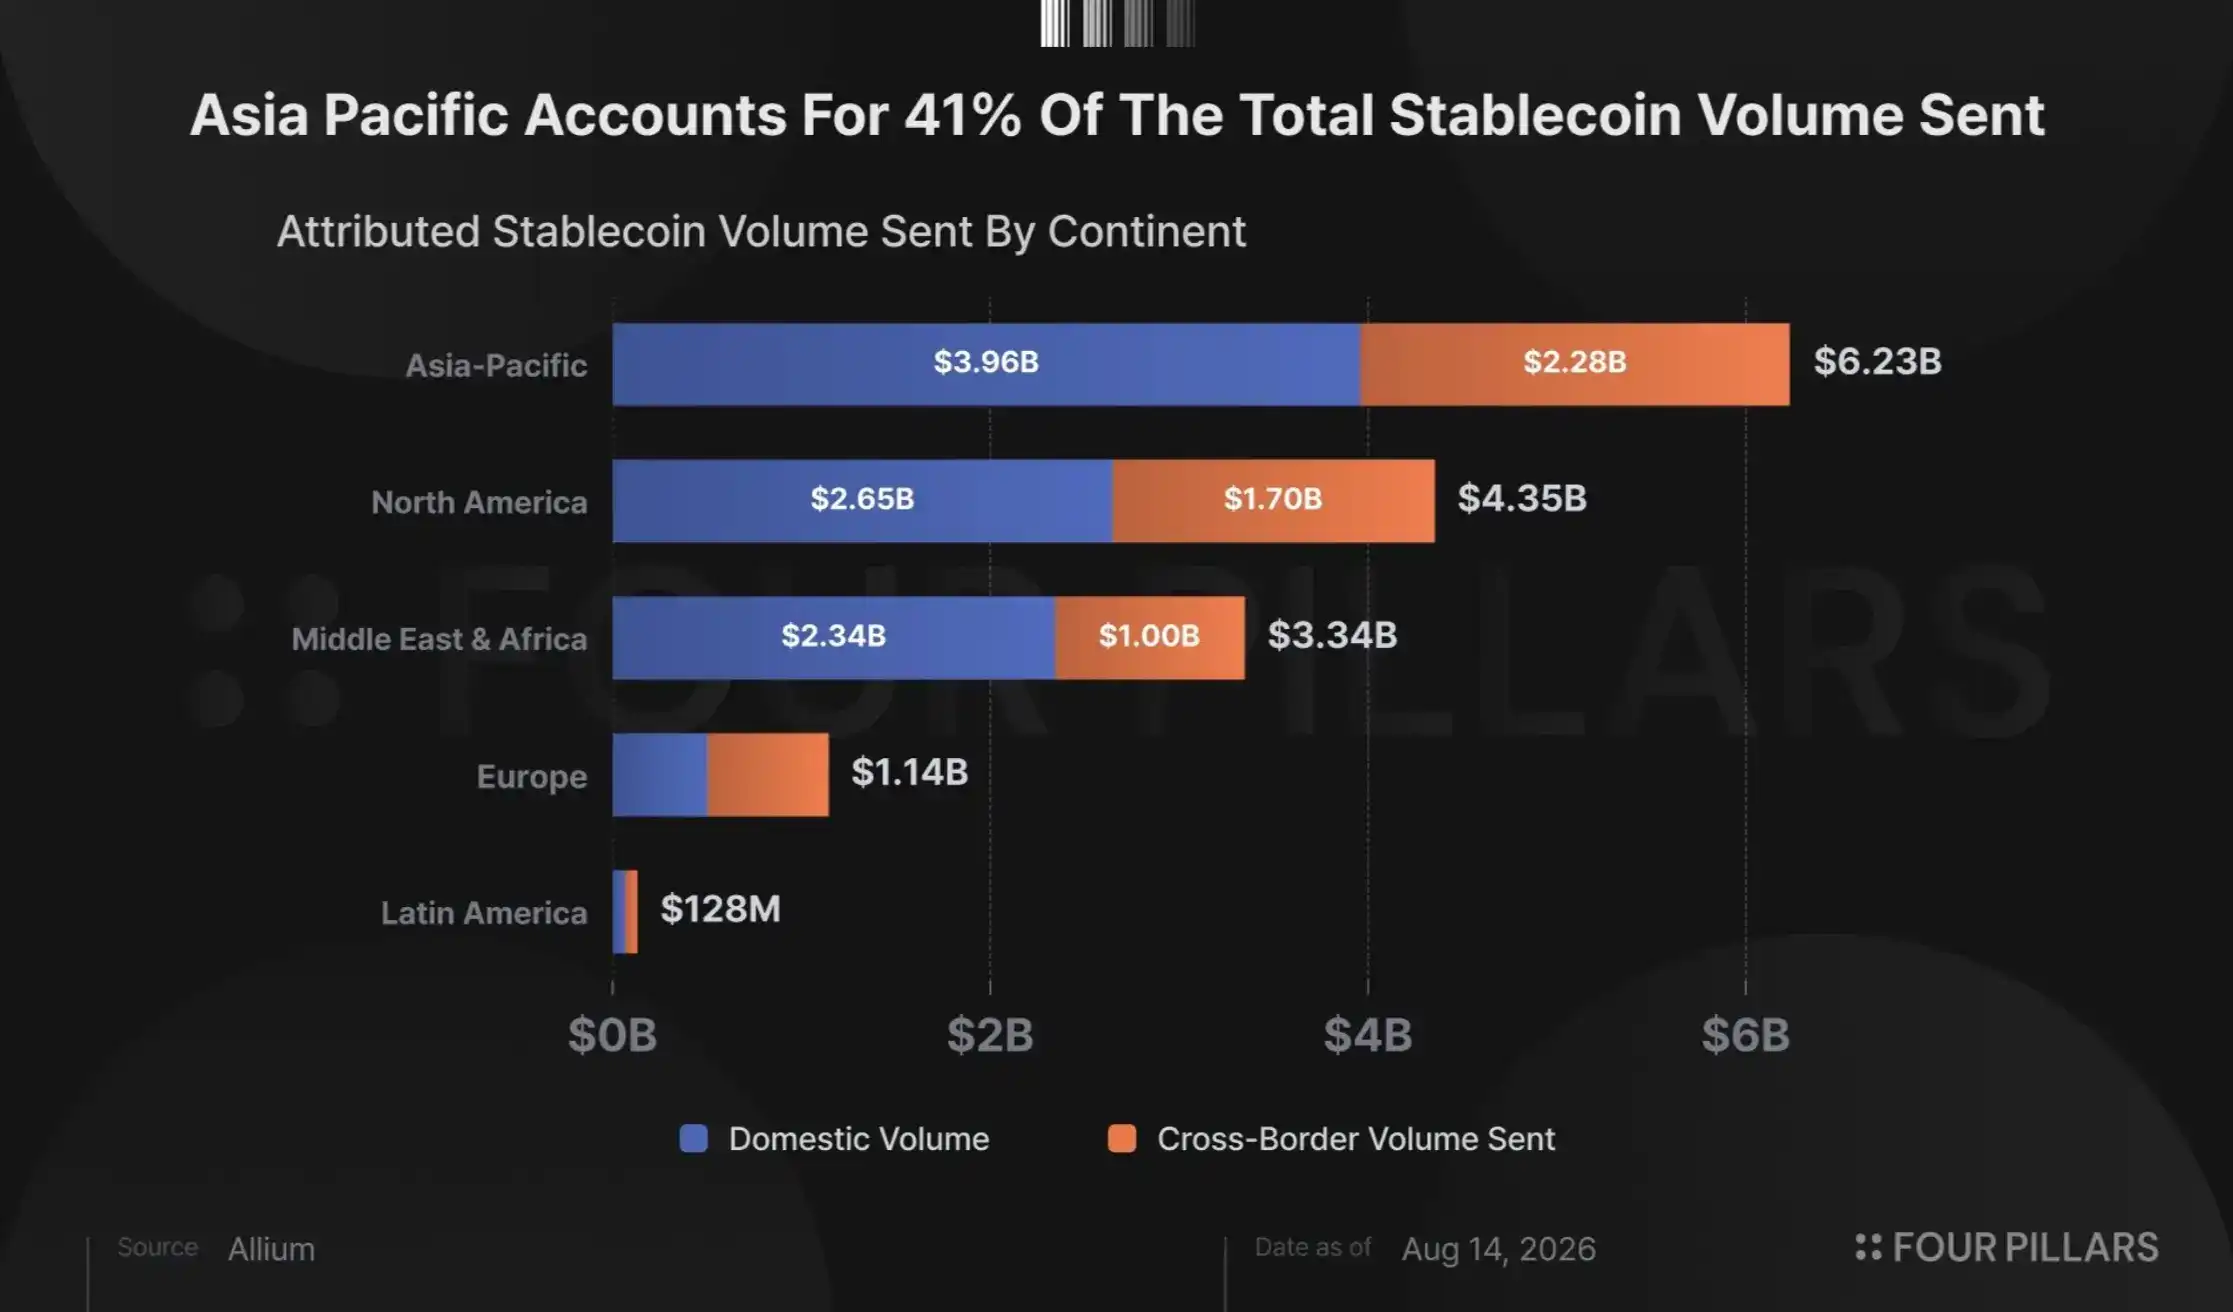
The APAC region is the largest in this dataset, sending $6.23 billion in stablecoins, accounting for 41.0% of identifiable volume; and receiving $6.4 billion, accounting for 42.1%.

In terms of sent volume, APAC is significantly higher than North America at 28.6%, the Middle East and Africa at 22.0%, Europe at 7.5%, and Latin America at 0.8%.

Simultaneously, APAC generated $3.96 billion in domestic transaction volume, equivalent to 41.6% of the global total domestic stablecoin transaction volume.

This concentration is also evident in major cross-border transactions. Of the world's 15 largest cross-border stablecoin payment corridors, 9 involve at least one APAC market, with Indonesia alone appearing in 6 of these corridors.

Turkey to Indonesia ($206 million)and United States to Mexico ($206 million) are the two largest unidirectional cross-border payment corridors.

Combining transaction volumes in both directions, bilateral trade volume between Indonesia and Turkey reaches $363 million, Indonesia and Taiwan reach $262 million, and South Korea and Turkey reach $190 million.

These figures indicate that substantial capital flows have already formed between Asian markets and markets outside Asia with high stablecoin adoption.

Net inflow data shows similar characteristics.

The APAC region received $167 million more than it sent, showing an overall net inflow; meanwhile, the United States recorded the largest net outflow in the sample.

Indonesia (+$111 million), Singapore (+$57.9 million), and South Korea (+$31.7 million) are among the markets with the largest net inflows in this sample.

Therefore, for institutions evaluating current stablecoin payment demand, the APAC region simultaneously possesses the largest identifiable transaction volume, the highest domestic transaction volume, and positive stablecoin net inflows.

Related Questions

QAccording to the article's data analysis, what is the proportion of domestic transfers within the total identified stablecoin transaction volume?

ADomestic transfers account for 62.6% of the identified $15.2 billion stablecoin transaction volume.

QWhich region is identified as the largest market for stablecoin transactions based on the data, and what is its share of the total identified sending volume?

AThe Asia-Pacific (APAC) region is the largest market, accounting for 41.0% of the total identified sending volume.

QWhat are the two largest one-way cross-border corridors for stablecoin payments mentioned in the article?

AThe two largest one-way cross-border payment corridors are Turkey to Indonesia ($206 million) and the United States to Mexico ($206 million).

QWhat specific opportunity does the article highlight for institutions assessing stablecoin payment demand, apart from cross-border remittances?

AThe article highlights that domestic payment and settlement services represent a larger actual transaction volume and are a more significant market opportunity compared to focusing solely on cross-border remittances.

QWhich three countries in the Asia-Pacific region are mentioned as having the largest net inflows of stablecoins in the sample data?

AIndonesia (+$111 million), Singapore (+$57.9 million), and South Korea (+$31.7 million) are mentioned as having the largest net inflows among APAC markets in the sample.

Related Reads

Google and Meta Called Out for Benchmark Gaming

Recently, analysis firm SemiAnalysis accused tech giants Google and Meta of "benchmark gaming" with their AI models Gemini 3.8 Flash and Muse Spark 1.3. The accusation stems from a dramatic performance drop between two versions of the Terminal-Bench evaluation for AI agents. On the older, public Terminal-Bench 2.1, Gemini 3.8 Flash scored 89.4, ranking second and beating GPT-6 Astra, while Muse Spark 1.3 scored 88.8. However, on the newly released, more secure Terminal-Bench 4.0, their scores plummeted to 19.1 and approximately 33.3 respectively, far behind competitors. SemiAnalysis argues this indicates "benchmark contamination," where companies train models not on the public test questions themselves, but on expensive, privately purchased training data specifically designed to mimic the benchmark's style. This has evolved into a lucrative industry, with specialized firms selling tailored training tasks for thousands to hundreds of thousands of dollars. The article specifically points to Datacurve, a company that both sells expert coding data and runs its own benchmark (DeepSWE), where the accused models also performed well. Meta's Chief AI Officer, Alexandr Wang, dismissed the claims as a "silly argument," pointing out similar performance drops for other models like GPT-5.6 Sol. He stated Meta never claimed Muse Spark 1.3 was as powerful as top-tier models, only that it offered better value. The report concludes that this is the inevitable fate of all high-quality public benchmarks—they become "gamed" over time. The proposed solution of private, high-quality benchmarks comes with a significant downside: it would erode public transparency, turning open rankings into marketing tools and leaving developers without a common, fair measure to compare AI models.

marsbit2h ago

Google and Meta Called Out for Benchmark Gaming

marsbit2h ago

Crypto's Nouveau Riche Strikes Gold in the Real World: Coinbase Co-founder's Venezuelan Oil Field Adventure

Coinbase co-founder Fred Ehrsam is venturing into the oil fields of Venezuela, a surprising shift for a prominent figure in the digital asset space. Through his company Primavera Infinita, he recently secured a production contract for the Budare-Elotes block with Venezuela's state oil firm PDVSA. This move into a politically volatile, sanction-scarred country highlights a bet on high returns from its reopening under new leadership and shifting U.S. foreign policy. Ehrsam’s investment reflects a venture capital-style appetite for risk, targeting assets deeply discounted by political uncertainty. He is not alone; smaller, politically connected U.S. firms like Aspect Holdings and Hunt Oil are also entering, while established giants like ExxonMobil remain cautious due to past expropriations. To manage the complex, capital-intensive nature of oil, Ehrsam is assembling a professional team. This trend extends beyond Ehrsam. Other crypto wealth, like BitMEX's Arthur Hayes and Tether, is diversifying into traditional hard assets—energy, metals, and agriculture—seeking physical scarcity as a long-term anchor. Tether, for instance, took a controlling stake in agricultural giant Adecoagro. These moves signify crypto capital's evolving interest: not just tokenizing real-world assets (RWA), but directly acquiring and operating them. Ultimately, Ehrsam's gamble is less on oil geology and more on the duration of Venezuela's current political window. It underscores a broader narrative where digital-era wealth seeks stability and scale in the physical world's most traditional, immovable resources.

marsbit3h ago

Crypto's Nouveau Riche Strikes Gold in the Real World: Coinbase Co-founder's Venezuelan Oil Field Adventure

marsbit3h ago

Refuting the Ethereum 'Abandoning' ETH Narrative: What Does It Really Mean to Pay Gas Without ETH?

Title: Refuting the "Ethereum Abandoning ETH" Argument: What Does Paying Gas Without ETH Really Mean? The debate sparked by Vitalik Buterin's discussion of EIP-8141 (Frame Transactions), which suggests users could pay transaction fees without holding ETH, has led to extreme claims that ETH will lose its value. However, this perspective misunderstands the proposal. Currently, an Ethereum user initiating a transaction must also pay the network's Gas fee in ETH. EIP-8141 aims to decouple these actions. It allows a transaction to be split into separate "frames." A user could sign a transaction to, for example, send USDC, while a separate Paymaster account pays the required ETH Gas fee on their behalf. The user would then settle the cost with the Paymaster using USDC or another token. From the user's perspective, they pay in a stablecoin without interacting with ETH. Crucially, from the Ethereum protocol's perspective, the Gas is still paid in ETH; only the settlement layer between the user and Paymaster changes. This concept isn't entirely new; ERC-4337's Account Abstraction already allows similar Gas sponsorship. EIP-8141 seeks to integrate this capability more natively. The core goal is to drastically improve user experience by abstracting away the complexity of Gas, similar to how one pays with a credit card abroad without handling the local currency. It also enables atomic operations, like bundling token approval with a swap, which would revert together if the swap fails. Regarding ETH's value, the argument that "no ETH is needed" is incorrect. While users may not hold ETH, Paymasters and services must still acquire and spend ETH to pay network fees on the backend. The demand for ETH shifts from being distributed across millions of user wallets to being concentrated in the balances of these service providers. The key variable is whether this improved usability attracts significant new users and increases overall network activity. If it does, total ETH burned in fees could rise substantially. If it doesn't, the change merely reshuffles who holds the ETH needed for Gas. In summary, EIP-8141 aims to lower the entry barrier by hiding Gas complexity, betting that this will drive broader adoption and increase the fundamental utility—and thus demand—for the Ethereum network and ETH itself.

marsbit3h ago

Refuting the Ethereum 'Abandoning' ETH Narrative: What Does It Really Mean to Pay Gas Without ETH?

marsbit3h ago

Trading

Spot
活动图片