Author: Deep Tide TechFlow
After becoming the world's most profitable and cash-rich "atypical financial institution" by issuing USDT, Tether has finally taken the most critical step from the virtual to the real economy.
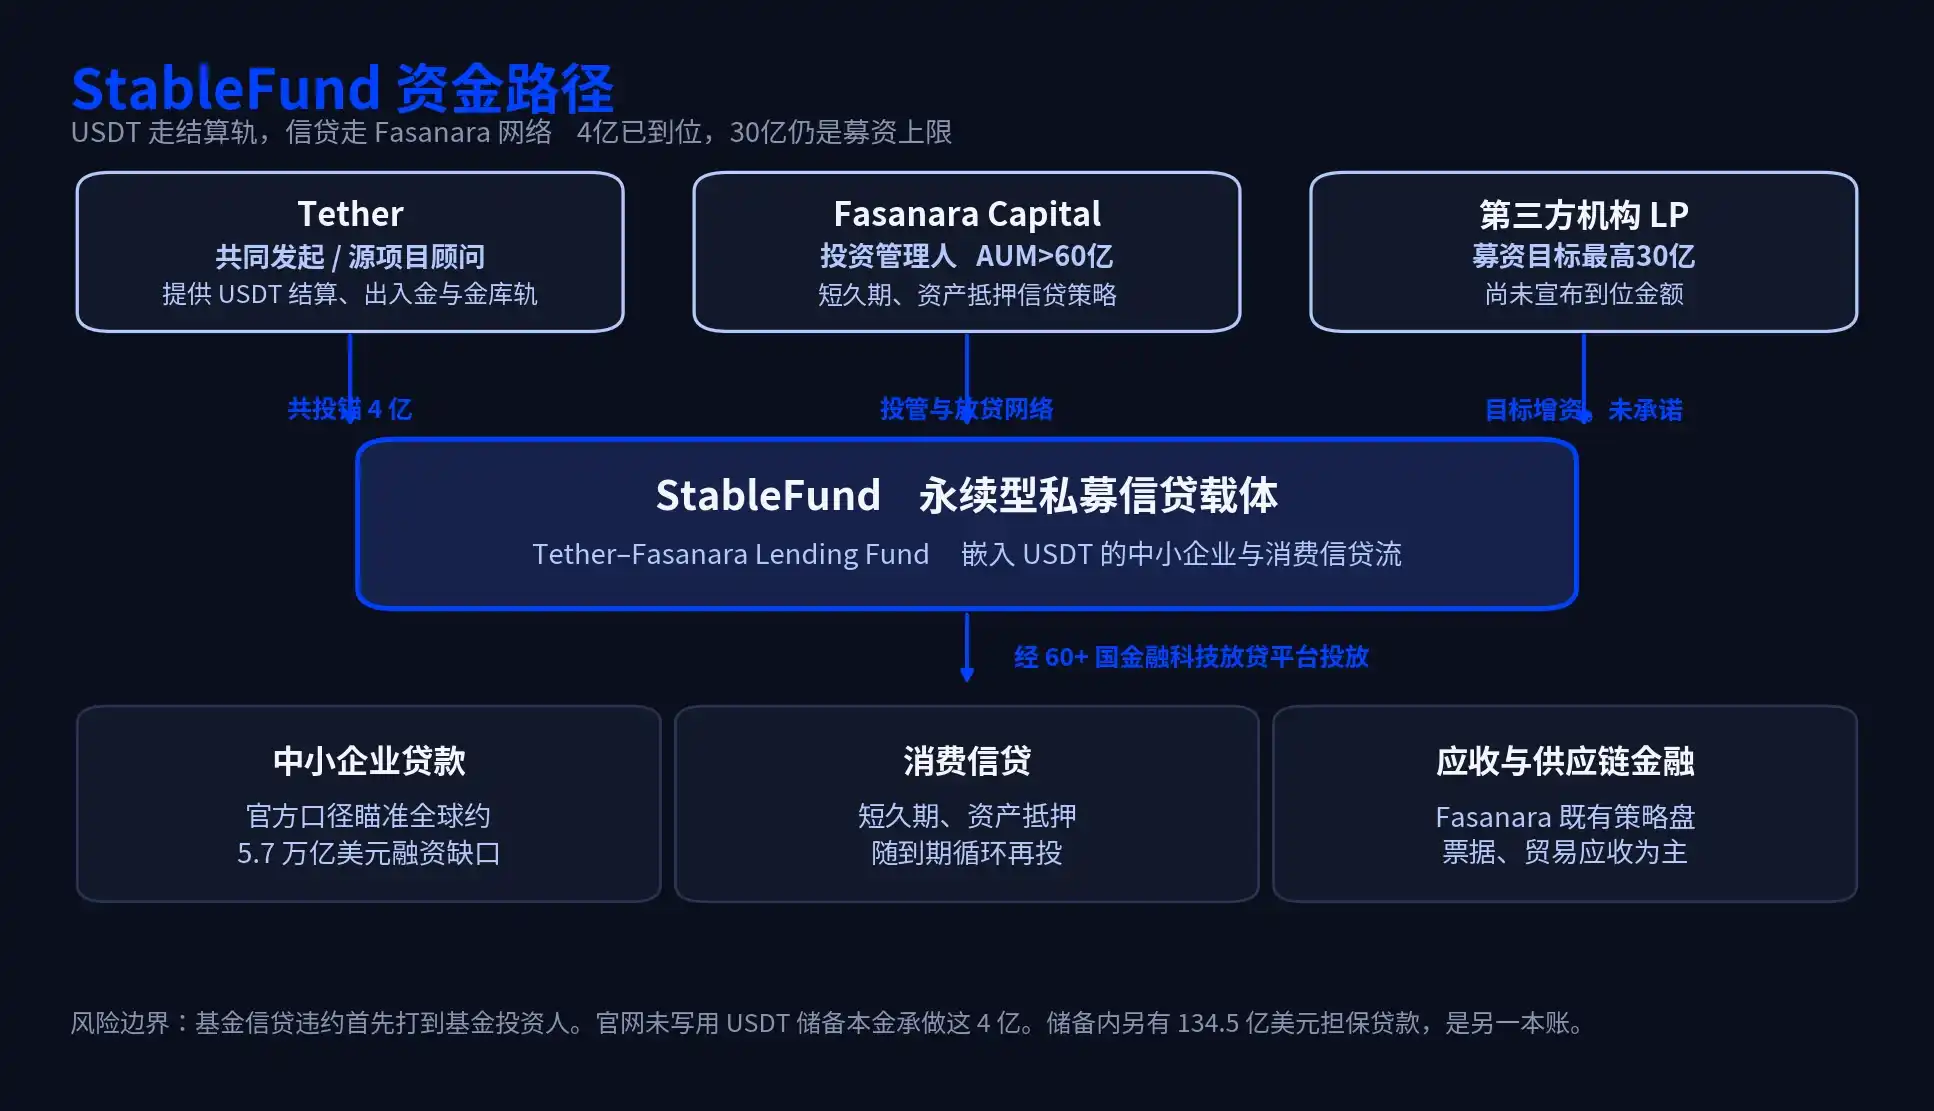
On September 9, Tether, in collaboration with London-based alternative asset manager Fasanara Capital, launched the StableFund, an evergreen private credit fund with a target size of up to $3 billion. The two parties contributed an initial $400 million in co-investment capital as the anchor, officially opening fundraising to external institutions.
This time, Tether is no longer targeting liquidity on crypto exchanges, but rather lending to physical small and medium-sized enterprises (SMEs) and consumer credit distributed across over 60 countries. While Silicon Valley is still debating the real-world use cases of cryptocurrencies, Tether, flush with massive US Treasury interest income, has quietly transformed into the most ambitious "on-chain shadow bank" in traditional finance.
Capital Flywheel: From Risk-Free Spread to a "Poacher" on Wall Street
Over the past two years, Tether's business logic has been remarkably simple: on one hand, meeting the demand for interest-free stablecoin issuance, and on the other, pouring its hundreds of billions in reserves into risk-free US Treasury assets.
This "money-printing machine" model, profiting from the interest spread, allowed Tether to easily record approximately $1.5 billion in operating profit in Q2 of this year.
However, as the global macroeconomic cycle of interest rate cuts approaches, the golden window for enjoying risk-free spreads is narrowing. Tether's enormous profit reserves must find the next reservoir capable of absorbing massive capital and offering higher potential returns.
Private Credit became the best landing point.
Against the backdrop of traditional Western banks contracting their balance sheets and a global SME financing gap reaching $5.7 trillion, Wall Street giants like Blackstone and Apollo have long deployed significant resources here. But unlike traditional Wall Street institutions, Tether wields a weapon for a dimensional strike: it not only provides capital but also the "road."
In this $3 billion venture, the funding pipeline has been completely restructured. Borrowers no longer receive wire transfer dollars that require multiple correspondent banks, take days to clear, and incur high fees. Instead, they receive USDT, settling in seconds.

Using USDT to Bypass the Traditional Banking Lending Track
Within this new vehicle named StableFund, the roles of Tether and Fasanara are clearly delineated, following a typical "storefront-backend" model.
London-based Fasanara plays the role of the "underwriter" and "risk controller." This specialized asset manager, overseeing over $6 billion in assets, has already established a lending network on fintech platforms across more than 60 countries. They are responsible for precisely channeling funds into short-duration, asset-backed SME and consumer credit strategies.
Tether, meanwhile, plays the most central role: the source of capital and the settlement rail. Tether CEO Paolo Ardoino maintains a sober and restrained view on this: Tether will not engage in direct debt collection but will provide the stablecoin infrastructure that enables cross-border lending to function.
At this point, the narrative of USDT undergoes a fundamental shift. It is no longer merely a "trading pair" used by crypto players to hedge volatility but has become a lending pipeline directly inserted into the real economies of emerging markets. Tether is transforming the liquidity once confined to crypto casinos into a dollar alternative that improves the financing efficiency of global physical businesses.
On-Balance-Sheet and Off-Balance-Sheet Gameplay: The Deep Waters of Shadow Banking Risk Control
Venturing into real-economy credit means Tether has officially stepped into the minefield of risk control that traditional banks fear most:
If borrowers can't repay, who bears the loss first?
According to the current structure, the newly established StableFund is an off-balance-sheet fund. Theoretically, its credit default losses will be contained within the fund's net asset value and its Limited Partners (LPs), thus isolated from the 1:1 redemption reserves backing USDT.
But scrutiny from the outside world never ceases. Because on Tether's own balance sheet, credit business is already a behemoth. As of Q2 this year, Tether's reserve assets still contain a staggering $13.45 billion in Secured Loans. In comparison, the initial $400 million anchor capital for the new fund is just a drop in the bucket for testing the waters.
What truly gives Wall Street and regulators pause is this: when a stablecoin giant lacking extreme transparency in audits holds tens of billions in on-balance-sheet secured loans while also starting to lend to micro, small, and medium-sized entities off-balance-sheet through fintech platforms in 60 countries, it has, in effect, become a super shadow bank that circumvents all capital adequacy constraints.
Before this $3 billion target is fully raised, StableFund is merely a reconnaissance mission. But once Tether, leveraging its extremely low cost of capital and the settlement advantages of USDT, truly carves out a niche in the global private credit market, any widespread cross-border collection failures or collateral depreciation could escalate into a stress test for the entire crypto liquidity foundation.
When that time comes, this "unlicensed global central bank" operating outside of regulation will undoubtedly face the harshest scrutiny from Washington.