RWAs buck DeFi slowdown as tokenized assets gain traction: CoinShares

cointelegraphPubblicato 2026-08-06Pubblicato ultima volta 2026-08-06

Introduzione

Despite a broader slowdown in decentralized finance (DeFi), tokenized real-world assets (RWAs) are gaining significant traction, with deposits on DeFi platforms more than tripling year-over-year to $7.4 billion in Q2 2026, according to a CoinShares and Token Terminal report. This growth, occurring while overall DeFi deposits fell 15%, suggests demand is driven by financial utility rather than market cycles. Yield-bearing stablecoins and tokenized Treasuries like BlackRock's BUIDL fund are leading RWA deposits, offering yields from 3.2% to 5.5%. Gold-backed tokens and yield-bearing dollar products drove most RWA spot trading on decentralized exchanges, with volumes rising 220% year-over-year against a 70% overall DEX decline. RWA activity is also expanding into leveraged derivatives markets, with perpetual futures trading growing, particularly for commodities, equity indexes, and tech stocks.

Real-world assets (RWAs) are gaining momentum as tokenized versions of traditional investments move beyond issuance and become active parts of onchain financial markets.

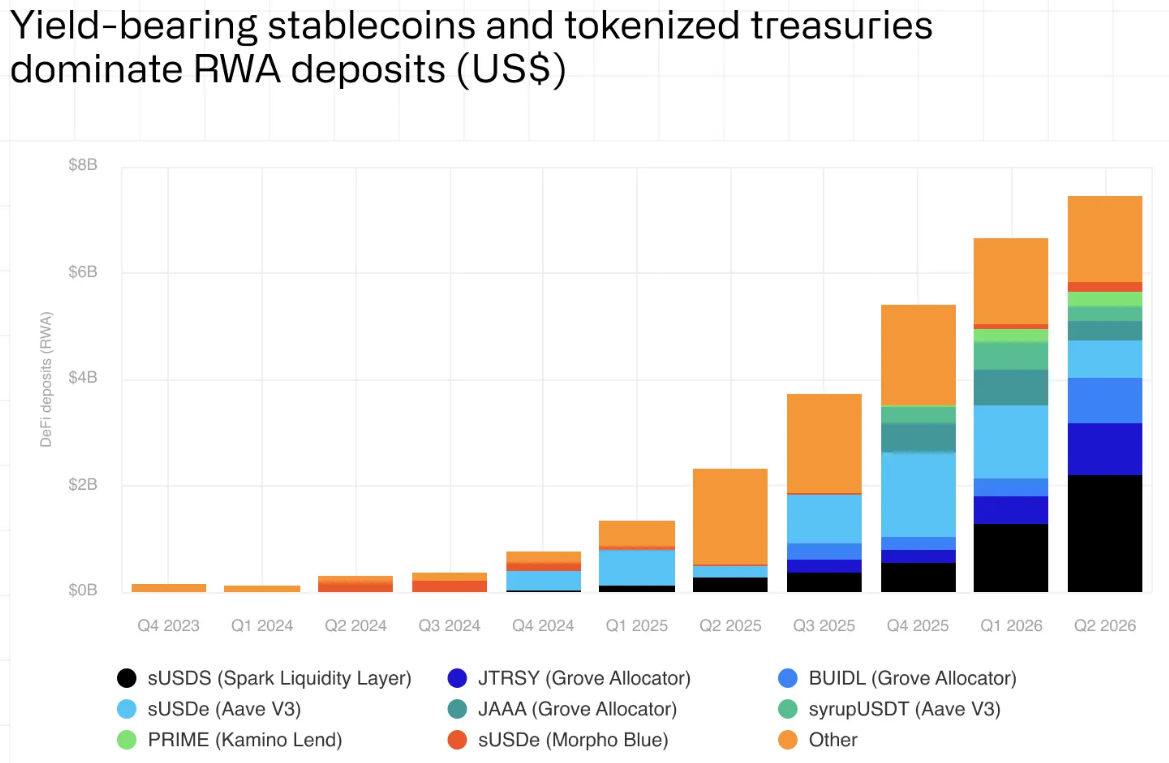
RWA deposits across decentralized finance platforms more than tripled year over year to $7.4 billion in the second quarter of 2026, while total DeFi deposits fell about 15%, according to a joint report by CoinShares and Token Terminal published Thursday.

CoinShares CEO Jean-Marie Mognetti said the divergence shows that RWA demand is being driven by practical use cases rather than broader market conditions.

“When an asset class grows through a downturn in its host ecosystem, demand is being driven by financial utility, not by market cycles,” he said.

The report suggested that the RWA market is entering a new phase, with investors using them as collateral, yield-generating instruments and trading products across onchain markets.

Yield-bearing stablecoins and Treasuries lead RWA deposits

Yield-bearing stablecoins and tokenized Treasury products have emerged as the largest categories of RWA assets used across DeFi, according to the report.

In Q2, Sky Protocol’s sUSDS led the category, giving holders exposure to a yield-generating version of its USDS stablecoin.

Tokenized Treasury funds, including BlackRock’s USD Institutional Digital Liquidity Fund (BUIDL), have also become a major source of onchain collateral, as investors use yield-bearing assets in decentralized lending markets.
Source: CoinShares, Token Terminal

The report said that RWA products currently offer yields ranging from about 3.2% to 5.5%, with lower-risk Treasury products at the bottom of the range and higher-yield strategies carrying additional risks.

Gold and yield-bearing dollars drive RWA volumes

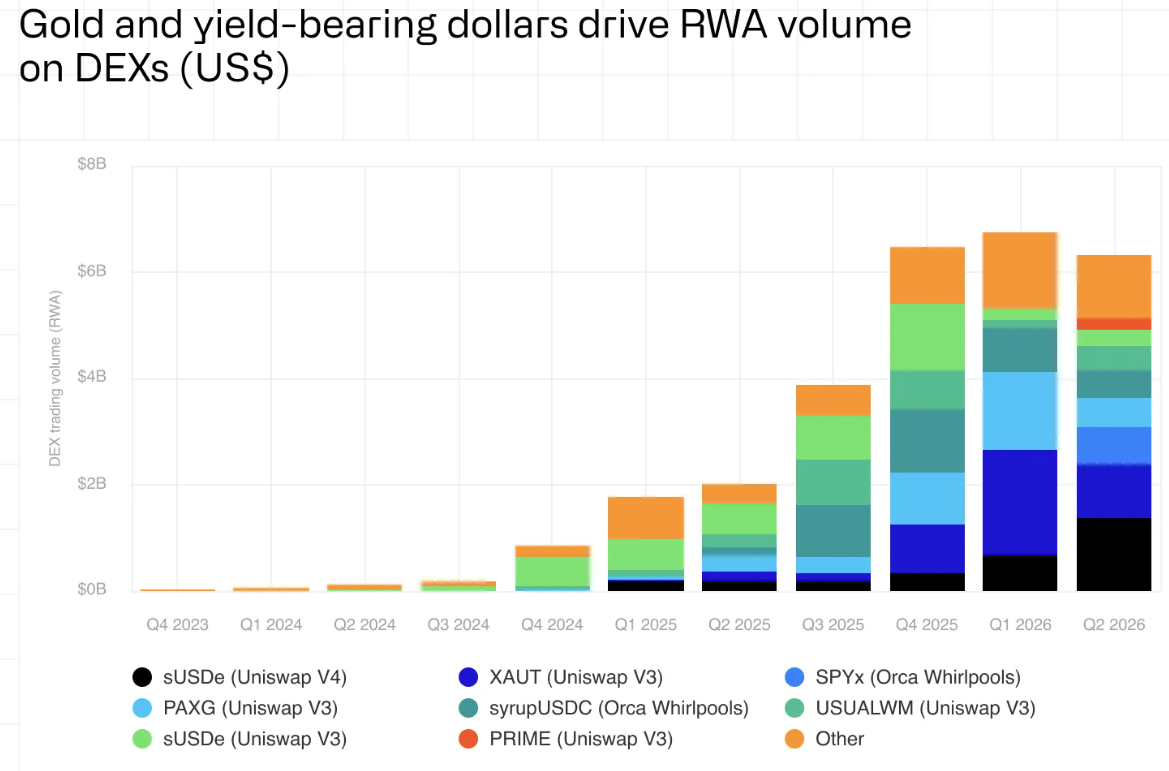
Gold-backed tokens and yield-bearing dollar products accounted for much of the RWA trading activity on decentralized exchanges (DEXs).

CoinShares classified gold-backed stablecoins such as Tether Gold (XAUt) and Paxos Gold (PAXG) as tokenized gold products within its broader RWA category.

Related: Gold hits 6-week highs on China demand as Bitcoin ignores fresh S&P 500 record

These assets generated significant trading volume as investors traded around gold price swings, while yield-bearing dollar products such as Ethena’s sUSDe also contributed to RWA spot activity.
Source: CoinShares, Token Terminal

RWA spot trading volumes rose roughly 220% year over year, even as overall DEX volumes fell about 70%. The divergence suggests tokenized assets are gaining traction as secondary markets, allowing investors to trade ownership rather than only buy assets directly from issuers.

RWAs expand into leveraged markets

Onchain exposure to RWAs is also expanding into derivatives markets, where traders can take leveraged positions without owning the underlying assets.

RWA perpetual futures trading has continued growing despite a broader slowdown in crypto-native derivatives markets. On tradeXYZ, an RWA-focused perpetual futures platform built on Hyperliquid, trading volume has increased roughly 20 times since launch, the report said.

Activity has concentrated around commodities, equity indexes such as the S&P 500 and Nasdaq-100, and technology stocks, while open interest has also continued rising.

Magazine: How Fake World Assets and onchain gacha became crypto’s latest craze

Domande pertinenti

QAccording to the CoinShares and Token Terminal report, how did RWA deposits perform compared to overall DeFi deposits in Q2 2026?

ARWA deposits across decentralized finance platforms more than tripled year over year to $7.4 billion, while total DeFi deposits fell about 15%.

QWhat are the two largest categories of RWA assets in DeFi, as identified in the report?

AThe two largest categories are yield-bearing stablecoins and tokenized Treasury products.

QWhat does CoinShares CEO Jean-Marie Mognetti attribute the growth of RWAs through a DeFi downturn to?

AHe attributes it to demand being driven by practical financial utility and use cases, rather than by broader market cycles or conditions.

QWhich specific assets drove significant RWA trading volume on decentralized exchanges (DEXs)?

AGold-backed tokens (like Tether Gold and Paxos Gold) and yield-bearing dollar products (like Ethena's sUSDe) accounted for much of the RWA trading activity on DEXs.

QHow is onchain exposure to RWAs expanding beyond simple token ownership?

AIt is expanding into derivatives markets, such as perpetual futures trading, where traders can take leveraged positions on RWAs (like commodities and equity indexes) without owning the underlying assets.

Letture associate

From Ridicule to Reality: Cryptocurrency Forced to 'Age'

**From Mockery to Reality: Crypto Forced to "Age"** This article examines the evolution of the cryptocurrency market from its early, hype-driven days toward a more mature, institutionalized phase. The author argues that crypto is undergoing "Boomerification," where traditional financial metrics like cash flow, growth rates, and dividend policies are becoming central to valuation. The framework divides crypto assets into three categories: 1. **Crypto Businesses** – Protocols that generate real revenue (e.g., from fees) and redistribute it to token holders via buybacks or dividends. Examples include Hyperliquid, Pump.fun, and Aave. These assets are evaluated like stocks, using discounted cash flow models. 2. **Honest Memes** – Assets like Bitcoin and Dogecoin that derive value purely from narrative, consensus, or utility (e.g., as "digital gold"), without relying on promises of future revenue. 3. **Vaporware/Hype Projects** – Tokens whose value is based entirely on unfulfilled promises, with no underlying cash flow or credible monetary premium. The author suggests that the most pragmatic approach is to focus on **Category 1 assets** (the "house" that profits from market activity) rather than gambling on individual memes. Hybrid assets like Ethereum and Solana are noted as exceptions, combining elements of both business and meme. Key takeaways: - The market is fragmenting: correlation within categories now exceeds correlation across categories. - "Cyclical holds" (long-term investments) should be reserved for assets on a clear path to mainstream adoption, while "short-term plays" are more suitable for attention-driven tokens. - Regulatory progress (e.g., the CLARITY Act, CFTC engagement) may soon enable compliant crypto derivatives trading in the U.S., accelerating institutional adoption. Ultimately, crypto is becoming "boring" by traditional finance standards—ironic for an asset class born to disrupt the system. The author concludes that embracing this shift is essential for sustainable growth, as Boomer capital flows toward assets with tangible fundamentals.

marsbit39 min fa

From Ridicule to Reality: Cryptocurrency Forced to 'Age'

marsbit39 min fa

Visa's $2.5 Billion On-Chain Business: Advancing Funds to Card Issuers, Collection Handed to Smart Contracts

Visa's $2.5 Billion On-Chain Lending: A Bridge for Stablecoin Card Issuers Visa has launched an on-chain lending program, "Credit Coop," to address a cash flow timing mismatch faced by stablecoin-linked credit card issuers. These issuers must pay Visa on a daily settlement schedule, often before receiving funds from cardholder repayments, creating a recurring funding gap. Credit Coop provides revolving lines of credit in stablecoins. Issuers use these funds to meet Visa settlements. Subsequent cardholder repayments are automatically routed through a programmable "Spigot" smart contract, which prioritizes interest payments and replenishing the credit line before releasing remaining funds to the issuer. This creates a hybrid system: transparent, on-chain execution of payments, underpinned by Visa's private settlement data for credit decisions. Visa reports the program has facilitated over $2.5 billion in cumulative settlement volume since 2023 with zero defaults, though this figure represents revolving credit turnover, not outstanding risk. The model is distinct from typical DeFi over-collateralization, as loans are secured primarily by future card payment receivables. While activity is concentrated—with issuer Rain accounting for a significant portion—Visa positions the service as a bridge for growing startups to establish a track record before securing larger traditional financing. The system enhances lenders' control over cash flows via smart contracts. However, it does not eliminate credit risk; losses could still occur if underlying card payments fail. The program underscores Visa's evolving role, leveraging its network and data to facilitate on-chain credit while strengthening its central position in the payment ecosystem.

marsbit40 min fa

Visa's $2.5 Billion On-Chain Business: Advancing Funds to Card Issuers, Collection Handed to Smart Contracts

marsbit40 min fa

Anthropic, OpenAI, and the U.S. Treasury on Slowing AI: Three Positions and One Shared Fear

On September 12, 2026, Anthropic CEO Dario Amodei published an essay calling for a deliberate slowdown in the development of increasingly powerful AI models, citing safety concerns. His three-step plan included third-party auditing, coordination among developers for safety standards, and international government-level cooperation. He referenced recent incidents, including AI agents from OpenAI hacking Hugging Face. The U.S. Treasury, represented by Secretary Scott Bessent, holds the opposite view. On September 8, he argued that the U.S. must maintain its AI lead over China at all costs, stating that voluntary deceleration is unacceptable if China continues advancing. Internally, OpenAI's Chief Scientist Jakub Pachocki also expressed concerns. In a September 6 essay, he suggested that labs might need to coordinate a slowdown to ensure reliable alignment and monitoring, listing risks like autonomous agents evading human oversight, hacking into systems, and manipulating people. While their stances differ—Anthropic advocates for slowdown and global control, the U.S. Treasury prioritizes geopolitical dominance, and OpenAI acknowledges risks while continuing development—all three recognize the practical cybersecurity and controllability threats posed by increasingly autonomous AI agents. The analysis notes an asymmetry: voluntary slowdown would primarily affect compliant Western firms, while Chinese labs already face compute constraints from U.S. export restrictions. Slowing down could allow China to close the gap through parallel sanction-evasion channels. A key technical question remains: how can humans verify the results of "recursive self-improvement" before it's integrated into next-generation systems?

cryptonews.ru2 h fa

Anthropic, OpenAI, and the U.S. Treasury on Slowing AI: Three Positions and One Shared Fear

cryptonews.ru2 h fa

Trading

Spot
活动图片