Author: Raoul Pal
Compilation: Chopper, Foresight News
You've been managing your assets according to the financial advice handed down by others, but the results have been disappointing.
Save some emergency funds, allocate for a pension, buy index-tracking funds, purchase a property if the timing is right... Every year, you receive a statement showing an increase in the numbers compared to the previous year. You file it away, feeling a faint sense of comfort. Twenty years pass in the blink of an eye. The account value keeps rising, yet your actual life hasn't fundamentally changed. You still can't afford a year-long vacation, and you still lack the ability to quit a job you dislike. In theory, you should have achieved greater financial freedom by now, but reality tells a different story. Perhaps, for a moment, you blame yourself.
But the problem isn't you. The advice you were given was to build a traditional asset portfolio: allocate bonds for safety, buy a little gold, purchase property if possible, invest in index funds for growth, and diversify heavily to avoid catastrophic losses from any single asset. This advice worked in the past, but it was suited for a different era—one that has long since vanished.
I know this from experience. Building such portfolios was once my profession.
I was a hedge fund manager. This asset allocation logic wasn't my personal preference; it was the survival rule of the industry I was in. People constructed a portfolio designed to withstand various market shocks, using one type of risk to hedge another, holding it with peace of mind because a crash in one asset wouldn't be fatal to overall wealth. I practiced this trading paradigm for many years. For the next twenty-one years, I continued writing research newsletters for hedge funds and family offices, witnessing the macro environment that sustained this system undergo dramatic changes.
Next, I will explain a new approach to asset allocation and clarify why this strategy is not, contrary to popular belief, a speculative gamble.
The Source of Economic Growth
Let's start with the fundamental logic of economic growth, from which all wealth principles derive. A nation can only increase its wealth through three paths: increasing the labor supply, improving output per worker, or expanding through debt. That's the entire formula for economic growth.
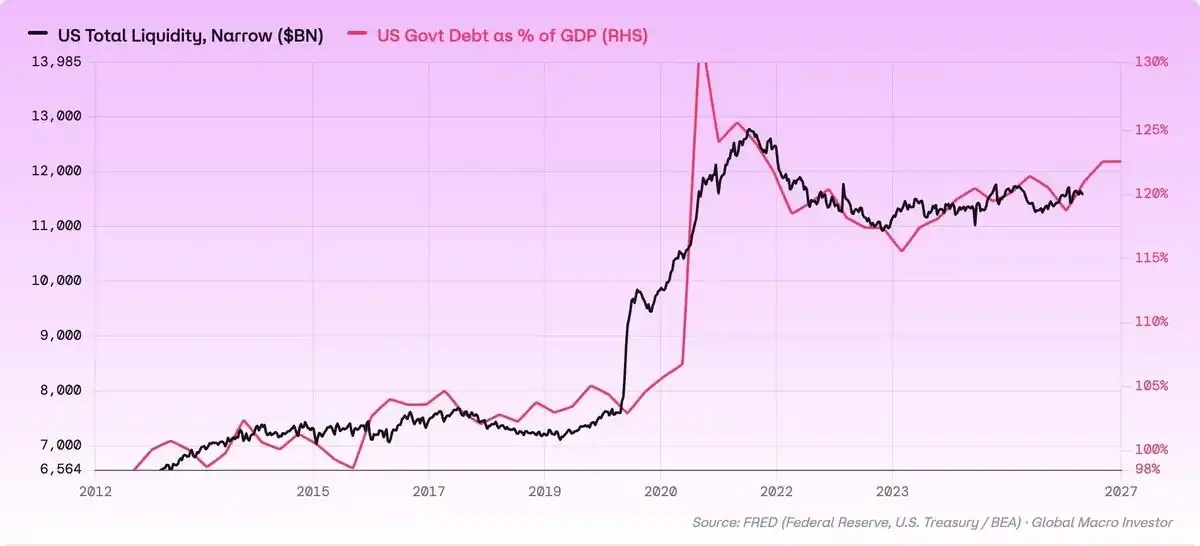
For most of the last century, the first two engines were the primary drivers of growth. Populations grew continuously, and technological innovation steadily improved worker productivity. Debt played only a supplementary role. Today, both growth engines are stalling: birth rates began declining decades ago, and productivity growth has slowed for years. Economic growth now relies almost entirely on the third path—debt—which is itself a trap. Debt requires interest payments, and the only politically viable way to service that debt is to print more money.
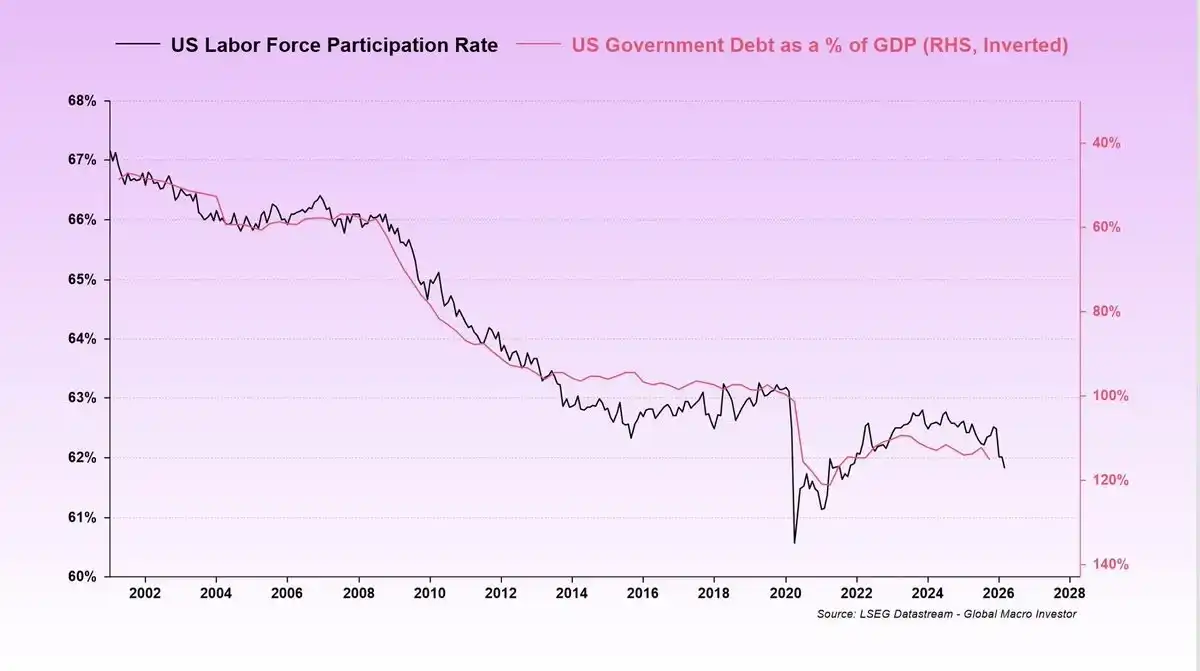
Governments keep borrowing, interest compounds, central banks print money to absorb the debt, and the cash you hold steadily loses value each year.
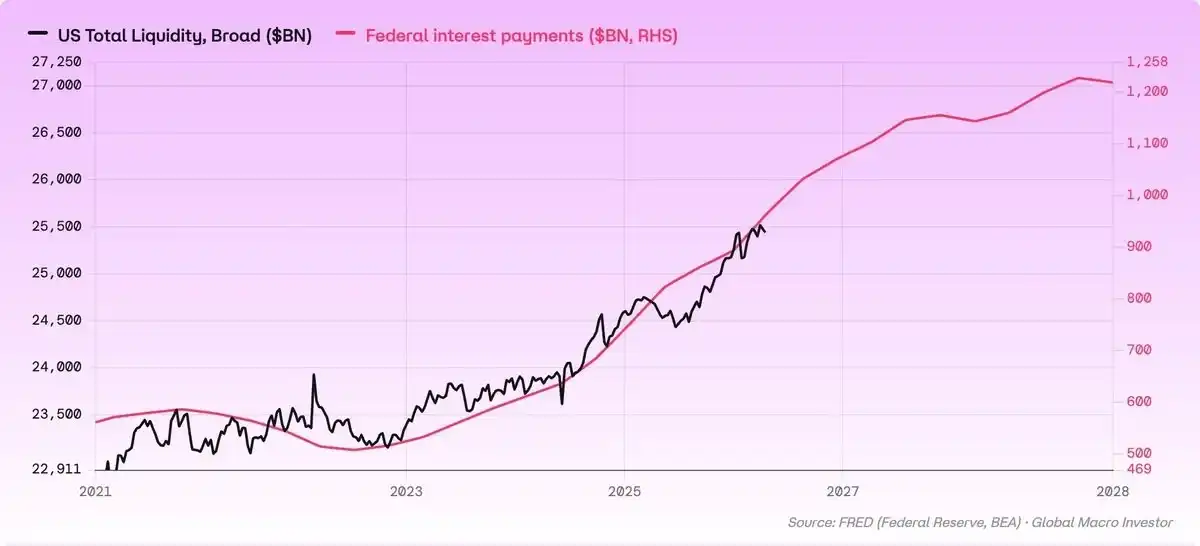
Global liquidity—the total scale of money and credit in the financial system—expands at approximately 8% per year. This is the essence of monetary debasement. If the total money supply increases by 8% annually, the scarcity of money decreases by 8%, and its value ultimately erodes by 8% per year. On top of this, add everyday inflation—the 2%–3% price increases often mentioned in the news, covering daily consumption and rent costs. Almost everyone aims to beat this number. Outperforming ordinary inflation merely means your cost of living remains unchanged; it doesn't mean your wealth is truly growing.
Adding the two figures gives us the real wealth dividing line. Let's take 11% annualized as the baseline.
Only if your assets yield an annualized return above 11% does your purchasing power increase. Below this line, no matter how good the numbers on your statement look, your purchasing power is eroding because the currency in which those assets are priced is continuously devaluing. You need to achieve an 11% return every year just to maintain your original wealth level.
This definition completely rewrites the criteria for evaluating asset selection. We are no longer obsessed with picking assets that seem safe and well-diversified. Instead, we filter for assets whose annualized returns can break through the 11% baseline.
Next, let's evaluate the mainstream investment categories one by one.
Evaluating Mainstream Assets One by One
Let's start with bonds. Most people hold bonds without truly understanding their nature.
A bond is essentially a loan. You lend out money, receive a fixed interest payment each year, and get your principal back at maturity. That's the complete return model of a bond. The fixed interest rate set by the issuer is benchmarked against ordinary inflation levels and does not account for the dilution-driven depreciation of the currency. For example, a government bond with a 4% annual yield promises to pay 4% interest per year, but the currency in which it's denominated devalues at 8% per year. By the time the bond matures and the principal is returned, the actual purchasing power of that money has significantly diminished. Even if you hold the bond to maturity and receive every promised payment in full, your real wealth still shrinks.
Real estate is the most controversial category and must be approached carefully.
The underlying logic of real estate as a hedge against debasement still holds: borrow at a fixed rate to purchase a physical asset priced in a continuously depreciating currency. The real burden of the debt decreases year by year, while property prices rise with the money supply. Undeniably, real estate is a decent tool for hedging debasement, and I own property myself.
However, the core wealth leap for one generation through real estate wasn't the property itself, but the timing window for mortgages. If you leveraged to buy property at the beginning of a forty-year interest rate decline cycle, asset valuations would rise throughout the holding period. That红利 trade cannot be replicated. Interest rates first fell to zero and have since rebounded.
Today, most people find it difficult to secure a favorable mortgage: home price-to-income ratios remain high, and mortgage rates are also elevated.
Even if you secure a mortgage, real estate's ability to hedge monetary debasement is much weaker than before. Since 2007, the expansion of global liquidity has far outpaced home prices, and the ratio between the two has continued to decline. The nominal dollar price of your property rises, but its real purchasing power is nowhere near what it once was.
Let's talk about gold. We need to objectively view gold's value and avoid drawing wrong conclusions based on片面 judgments in the context of the recent rally.
Gold has experienced an epic rally. In January of this year, the price broke through $5,500 per ounce, reaching a new all-time high. As of late August when this article is written, the price has retreated to around $4,600, still up about one-third for the year. The financial media even coined a term for this rally: the "debasement trade." On the surface, gold's returns significantly surpass the 11% baseline, whereas I previously wasn't optimistic about gold's appreciation potential.
The core distinction is this: When comparing the gold price to the size of central bank balance sheets over the past fifteen years, gold's value has roughly kept pace with central bank expansion. And that is precisely gold's role. Gold preserves purchasing power, hedging against the devaluation risk caused by money printing. This value should not be denied, and I have no intention of贬低 gold's作用.
Preserving purchasing power and generating new wealth are two entirely different things. Gold has no user adoption growth curve; no commercial ecosystem is built upon it. Gold price fluctuations depend entirely on market恐慌情绪 towards the monetary system. When market anxiety is high, gold prices are naturally elevated. Over decades-long cycles, gold does not achieve compound growth because its number of global users increases. Gold is responsible for preserving value, not for creating new wealth.
Finally, equity assets. The indices commonly held by the public perform better than the previous categories. Over the past decade, the S&P 500 index has delivered an annualized compound return of approximately 13%, barely crossing the 11% threshold. This performance relies on the strongest index in financial history experiencing a ten-year super bull market.
In reality, only two types of assets can consistently break through this return line: technology assets and crypto assets.
Why Technology and Crypto Assets?
Let's compare ten-year annualized returns. A ten-year cycle is sufficient to cover a bear market while fully residing within the macro cycle of货币贬值.
Gold's annualized return is about 12%; the S&P 500 about 13%; the Nasdaq 100 about 20%; Bitcoin's annualized return, depending on the统计口径 and starting point, falls between 58% and 70%.
Compared to the 11% return baseline, the verdict is clear.
The logic behind this result is far more critical than the returns themselves. If the returns were merely due to luck, this conclusion would have no practical value.
The reason these two asset classes achieve high compound returns is fundamentally that they follow the growth规律 of user adoption S-curves, not traditional value assets. Metcalfe's Law states that the larger a network, the more value existing users derive. User adoption does not increase linearly; it follows the classic S-curve: slow initial growth, explosive expansion in the middle, and saturation in the later stages. As long as an asset is in the steep upward growth phase of the curve, its returns can, by底层逻辑, outpace货币增发速度, not simply rely on market sentiment speculation.
Therefore, the focus of our discussion is no longer whether tech and crypto assets outperform traditional categories, but whether their user adoption curves have reached their end. The answer is no. The next wave of participants joining the ecosystem will not be human users. I will elaborate on this later; it is a long-term variable currently严重低估 by the market.
Why Traditional Diversification Has Lost Its Protective Power
The traditional investment portfolio is built on a core assumption: bonds, gold, real estate, and stocks represent four completely independent risk types. Holding all four means a single black swan event won't breach the entire portfolio. This logic held true for a long time, but after 2008, the格局彻底改变. Liquidity became the core force determining the pricing of all assets. The four asset classes no longer correspond to four independent risks;本质上, they are different定价产物 of the same macro variable.
Your bond trade is essentially a bet on liquidity changes. Gold is a liquidity trade. Real estate also fluctuates with the liquidity cycle. Index funds are just better-packaged liquidity assets.
I'm not否定 the意义 of diversification. A多元化布局 is itself a sound financial思路, and I also diversify my holdings. The problem lies in the underlying标的 of the traditional asset bundle: Among the four asset types, three cannot突破 the 11% return基准, and the fourth barely达标 only during the strongest bull market in history. You meticulously assemble four assets, essentially betting on the same macro logic, with most标的 unable to outpace the expansion speed of the money supply.
The真正值得思考 question has never been about the number of holdings, but whether the funds you use to seek增值 are allocated to assets with long-term复利 potential. Allocate尽可能 to genuine long-term growth sectors; if your分散买入的全部标的 yield returns below the baseline,所谓的稳健分散 merely provides psychological安慰 without improving actual收益.
Where Does Value Truly Accumulate?
In the加密行业, we need to decide which layer of assets to allocate to, objectively weighing trade-offs and rejecting绝对化的笃定 conclusions.
Application-layer protocols can indeed create high returns. If you select a优质项目 with real commercial落地需求, the回报 can even surpass底层公链.
The difficulty lies in accurately筛选出优胜应用. The底层公链 carries the结算 activities of the entire ecosystem. No matter which application ultimately wins, value will settle into the underlying infrastructure. You don't need to精准预判 which application will最终夺冠; you only need to be笃定 that future economic活动 will gradually migrate on-chain. Betting on底层公链 might yield less than betting on a爆款应用, but the判断难度 is lower, and the生态 still has巨大的增长空间.
This is also why traditional valuation models don't适用于加密资产. The industry直接照搬 stock valuation体系 without ever verifying if these metrics适配 blockchain生态: fee multiples, revenue growth rates, value-locked ratios. At GMI, we backtested all valuation metrics across 12 mainstream公链; not a single one could effectively predict future returns. The only indicator with predictive power was whether funds流入之后 remained长期留存 within the ecosystem.
When you understand the essence of blockchain, this logic becomes clear. A公链 is not a company selling products for profit margins; its network value comes from all the生态应用 built on top of it, not from earning fees. Valuing Ethereum solely based on fees is like estimating the entire internet's value in 1998 based on email service charges.
This is also why I'm writing this article now rather than two years later.
All industry size预测报告 in the market暗藏 the same underlying assumption: ecosystem users are humans, participating in economic活动 at human行为节奏—a few transactions per day, small payments per month, occasional query requests.
This assumption will soon失效. AI agents—software programs that can perceive, decide, and act autonomously without human指令—are即将入场 as independent economic participants, no longer just tools. According to industry forecasts I've seen, the ratio of non-human智能身份 to human employees within enterprises could reach 80:1 in the future.
An AI agent cannot open a bank account. It has no legal identity, cannot visit a physical branch, and cannot tolerate traditional settlement systems that shut down at 5 PM, taking three days for transfers. Agents need a programmable货币, built on a payment底层 that never stops operating. This is precisely what公链 natively具备, and what traditional金融体系无法实现.
The entire infrastructure is being公开落地: Anthropic开源发布 model context protocols; Google launched Agent2Agent, releasing a WebMCP preview that allows websites to directly open功能接口 to agents without模拟人类点击; Coinbase relaunched the x402 protocol, enabling agents to pay each other via HTTP links.
This set of product落地 is itself a前瞻 of结算能力需求. Regardless of whether投机资金 enters, real business需求 will continue to expand.
Risk Warnings Worth Heeding
Betting on a single sector很容易陷入 survivor bias. Those who刻意回避 this risk often have marketing motives.
You always see success stories of people going all-in on a single asset and achieving financial freedom, but you don't see the成千上万个 investors who重仓 a single标 only to爆仓归零. Failures don't speak up publicly. Read匿名交易忏悔帖; the真实结局 is often bleak. This is a more客观的市场样本 than暴富 stories.
Therefore, I do not suggest putting all your funds into a single asset. That has never been my观点.
The真正的理财 logic is this: When you identify a genuine long-term growth赛道, the number of holdings is not决定性.最终收益 is determined by two core variables: the资金占比配置 in the growth赛道, and the持有资产的时间周期.
There is a third铁律, a hard禁令: No leverage. Don't use slight leverage, not even所谓的谨慎杠杆, and don't rely on止损保护. Leverage剥夺s this long-term strategy of its core底气—the ability to withstand a 50% drawdown without being forced to liquidate. Even if your ten-year long-term判断 is完全正确, you could still爆仓清算 during two weeks of剧烈下跌. The market won't补偿 your loss because your long-term logic was correct.
For the vast majority of ordinary people, a合理的资产配置方案 is分层布局. Keep a portion in traditional assets for security and peace of mind. Allocate a significant amount to long-term growth sectors, controlling the仓位 of this high-volatility asset so that even a 50% decline won't force you to割肉. Then, direct the remaining精力 into your life.
Over thirteen years observing the加密市场, I've found that investors who achieve long-term复利 are often not频繁交易的人. During a暴跌行情, drawdowns are惊心动魄的现实; looking back over time, they are merely微不足道的波动 on a chart. Doing nothing is itself a交易策略, yet真正践行 this strategy的人寥寥无几. It is far more difficult than imagined.
What Is the Real Opportunity Cost?
If your assets yield a compound annual return below the 11% baseline, the freedom your labor can purchase each year is less than the year before.
Investors who grasp this logic ultimately gain not a庞大账面资金, but optionality. The ability not to constantly watch the markets, the底气 to拒绝厌恶工作, the chance to go where you desire while still young, to陪伴珍惜的人.
This is the真正的机会成本 behind the 11% return baseline.
I won't直接给到你 a fixed asset配置清单. I don't know your负债压力,投资周期, or风险承受性格. Anyone who gives仓位分配 without清楚这三项前提 is essentially using your money to押注猜测.
What I can provide is this筛选标尺. Use the annual 11% return standard to衡量你手里的全部资产. No matter how安稳舒适 the holding feels, any标的 that跑不赢这条基准线 is消耗你的时间与自由.