Robinhood is gradually upgrading its prediction market business from a rapidly growing brokerage operation into a set of trading infrastructure that it participates in and controls.
Goldman Sachs' latest report focuses on an analysis of Rothera. This is a prediction market exchange jointly owned by Robinhood, Susquehanna International Group (SIG), and MIAX, with equity stakes of 45%, 45%, and 10% respectively. Robinhood is the controlling entity, therefore, it consolidates 100% of Rothera's revenue and expenses into its financial statements, and then allocates 55% of the net profit to the other shareholders through non-controlling interests.
This means that all revenue created by Rothera is reflected in Robinhood's top line, but ultimately only 45% of the net profit belongs to Robinhood's shareholders. Understanding this accounting relationship is key to assessing Rothera's actual contribution.
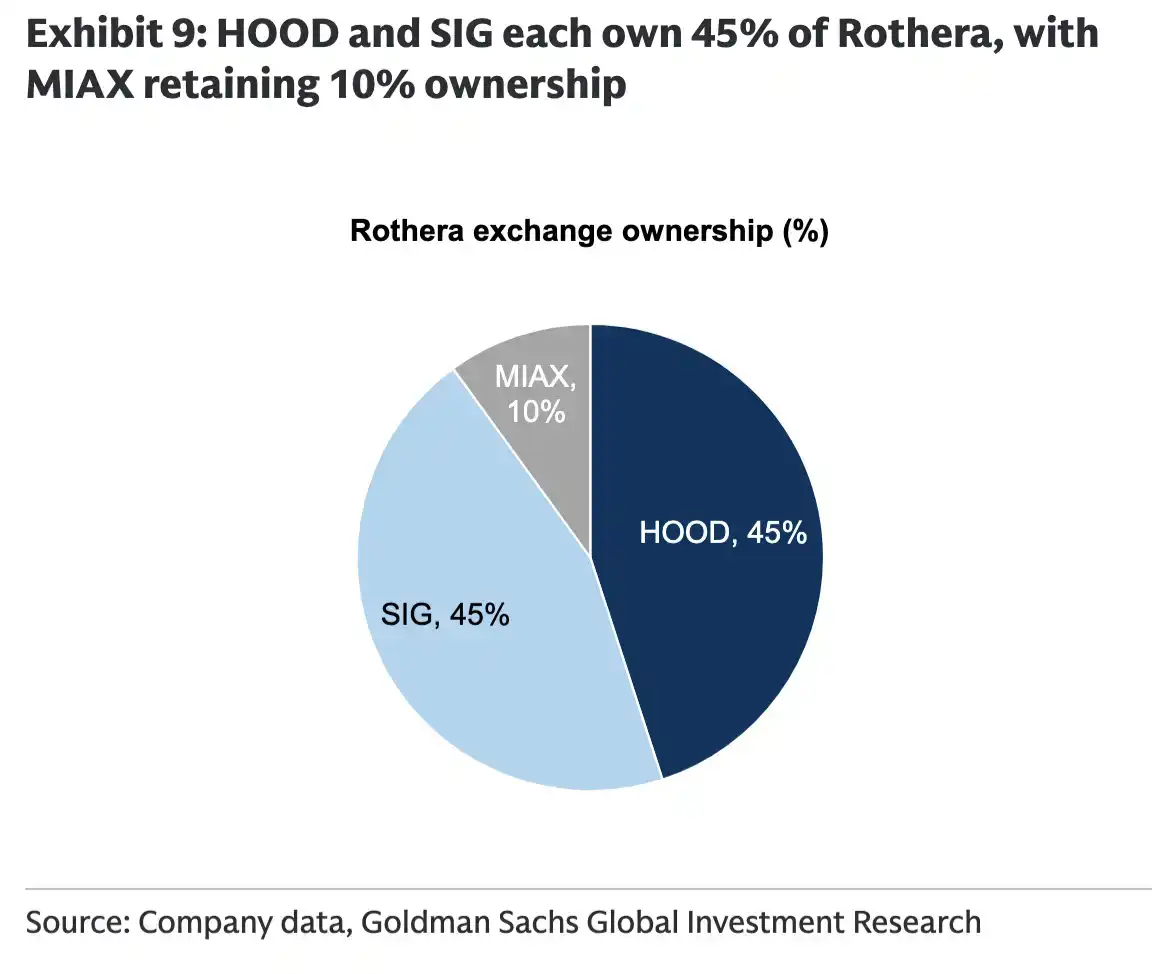
Caption: Robinhood consolidates 100% of Rothera's revenue and expenses, but only 45% of the net profit belongs to Robinhood.
Since its launch in late May 2026, Rothera has scaled rapidly. In its first 41 days of operation, Rothera generated approximately $17 million in revenue, translating to an annualized run rate of about $150 million. Goldman Sachs estimates its pre-tax margin has already reached 45%.
The growth in trading volume is even more striking. Rothera completed only about 2 million contract trades in May, which surged to 2.09 billion in June, was around 1.688 billion in July, and then fell back to 593 million in August.
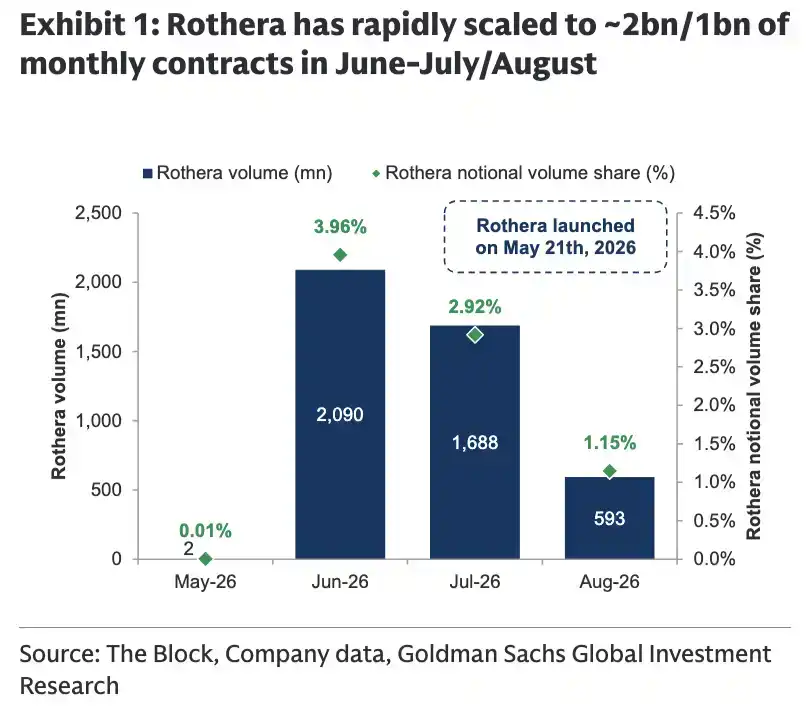
Rothera launched in May 2026, with contract trading volume exceeding 2 billion in June, before declining somewhat thereafter.
Measured by notional trading volume, Rothera became the world's third-largest prediction market Designated Contract Market (DCM) in July 2026 and ranked fifth in August, forming part of the leading group alongside platforms like Kalshi, Polymarket, Crypto.com, and Opinion.
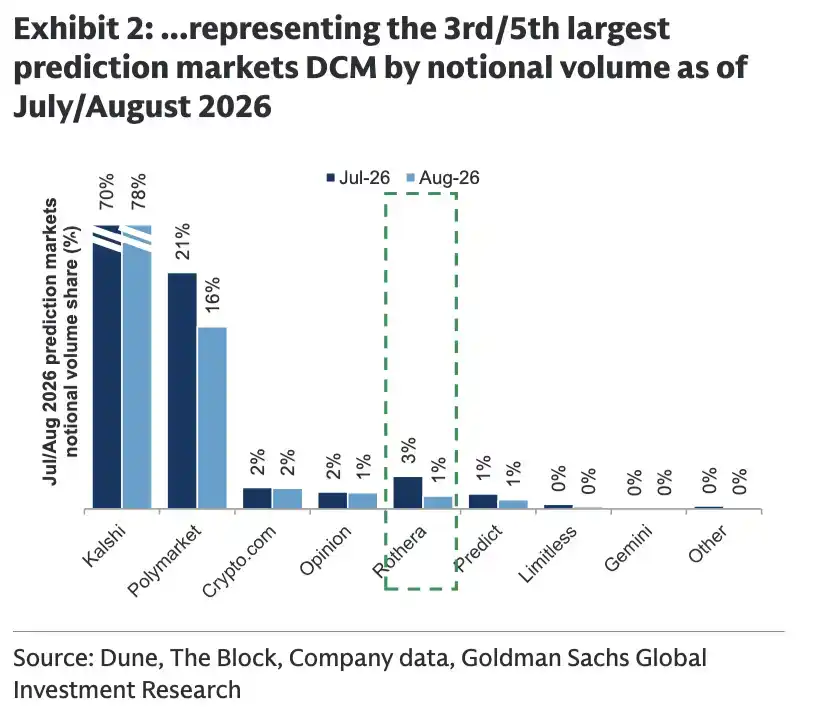
Based on notional trading volume, Rothera ranked as the world's third and fifth largest prediction market DCM in July and August 2026, respectively.
However, Rothera is still in the early stages of expansion. Its share of notional trading volume dropped from about 3% in July to about 1% in August. Both trading volume and rankings are susceptible to factors like sports event schedules, trending events, and market cycles. Its short-term entry into the global top five demonstrates Robinhood's ability to drive traffic, but it is not yet sufficient to confirm that it has established a stable market position.
Rothera initially offered almost exclusively sports event contracts, only beginning to add political and economic products in August 2026, which accounted for about 1% of trading volume each that month. This means Rothera's current activity remains highly dependent on the sports market, and product diversification has just begun.
For Robinhood, the significance of Rothera also lies in a change in its business model. Prior to this, Robinhood primarily acted as a Futures Commission Merchant (FCM), providing prediction market trading to its customers and then routing orders to external DCMs like Kalshi and ForecastEx. Robinhood collected brokerage fees, while the external exchanges collected matching and clearing fees.
With Rothera's launch, Robinhood can now participate in both the brokerage and exchange segments, keeping a portion of the revenue that previously flowed to external platforms within its own ecosystem. Thus, the prediction market is no longer just a trading product for retail customers but has also begun to serve as an entry point for Robinhood's expansion into trading infrastructure.
How Can Low Fees Mobilize Liquidity?
The key to scaling a prediction market lies in liquidity. Compared to the stock market, prediction markets have a vast number of contracts with different themes, outcomes, and maturities, making trading volume more easily fragmented. If there are insufficient buyers and sellers, bid-ask spreads widen, user experience deteriorates, further weakening market activity.
Goldman Sachs believes Rothera possesses two sources of liquidity that are difficult to replicate.
The first source is Robinhood's retail customer base. At the time of the report, Robinhood had approximately 14 million monthly active users. As more prediction market orders are directed to Rothera, these customers can continuously provide retail flow to the exchange.
The second source is SIG's market-making capabilities. SIG is not only a major global market maker but also holds a 45% equity stake in Rothera, giving it an incentive to continuously provide quotes and liquidity for the platform. Robinhood supplies retail orders, and SIG handles the provision and matching of liquidity; the combination of the two forms the foundation for Rothera's early expansion.
Low fees are another advantage Rothera uses to attract more orders.
Goldman Sachs estimates that the trading prices of most event contracts on Rothera are concentrated in the $0.25-$0.30 range, or symmetrically, the $0.70-$0.75 range. Based on its dynamic fee model calculations, the average fee paid by retail takers at the exchange level is approximately 0.38%-0.42% per $1 of notional contract value, significantly lower than the approximately 1.17%-1.31% level at other major prediction market exchanges.
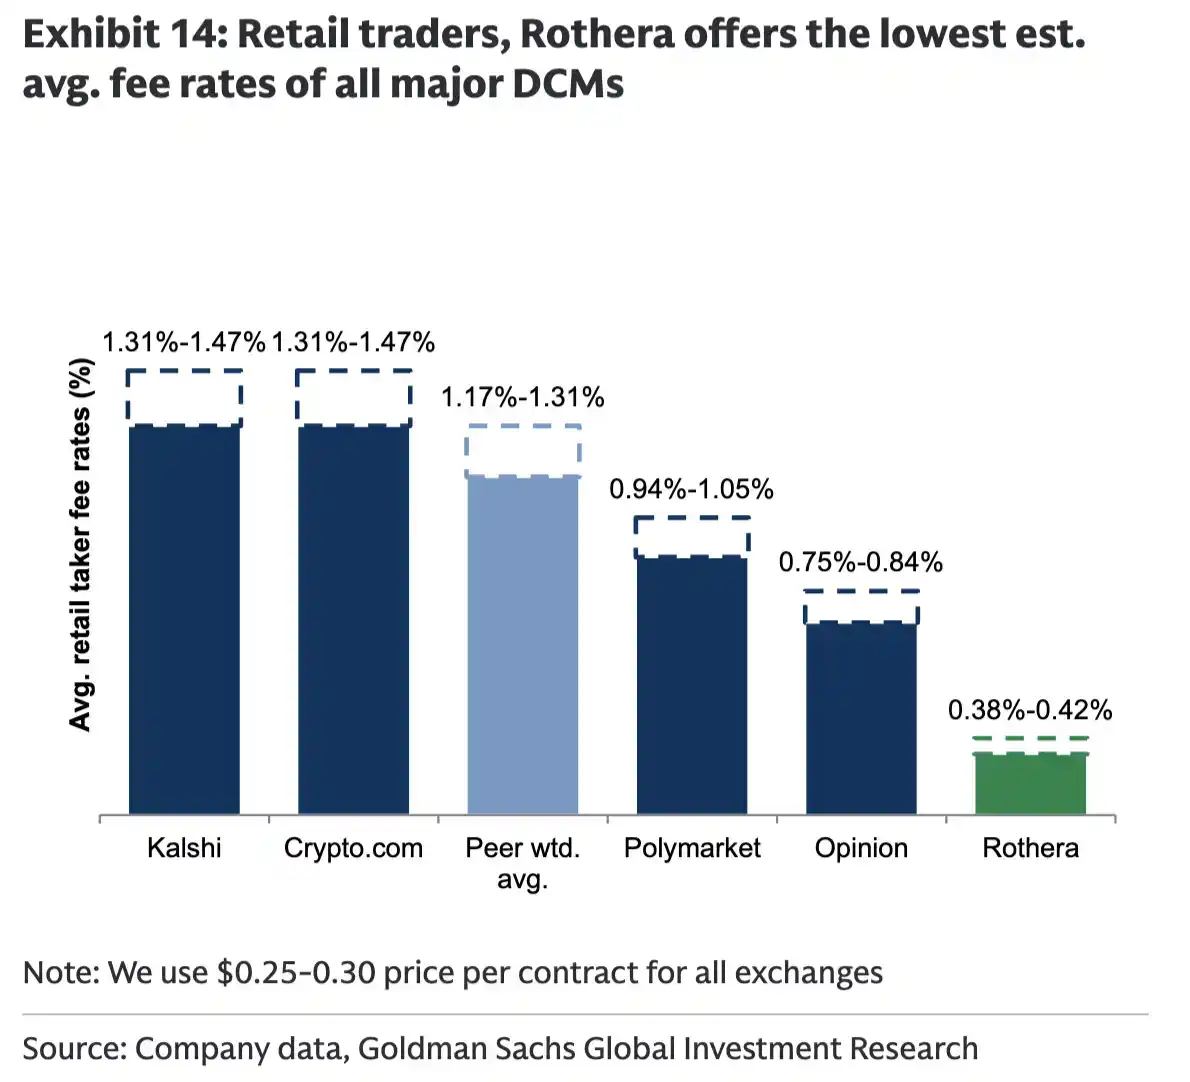
Goldman Sachs estimates that among major prediction market DCMs, Rothera offers the lowest average fees for retail traders.
Rothera employs not a uniform fee but a dynamic model linked to contract prices and trader types. The closer a contract price is to $0 or $1, the lower the trading fee; the closer it is to $0.50, the relatively higher the fee. Professional trading firms and market makers also pay higher fees than ordinary retail clients.
The purpose of this pricing strategy is to reduce participation costs for retail clients while charging higher fees to professional institutions to support platform liquidity.
Robinhood also adjusted its prediction market fee model following Rothera's launch. Previously, customers paid a fixed total fee of about 2%; after adopting floating pricing and routing some orders to Rothera, Goldman Sachs estimates the average total fee paid by customers has dropped to 1.31%-1.42%, equivalent to savings of about 29%-34%.
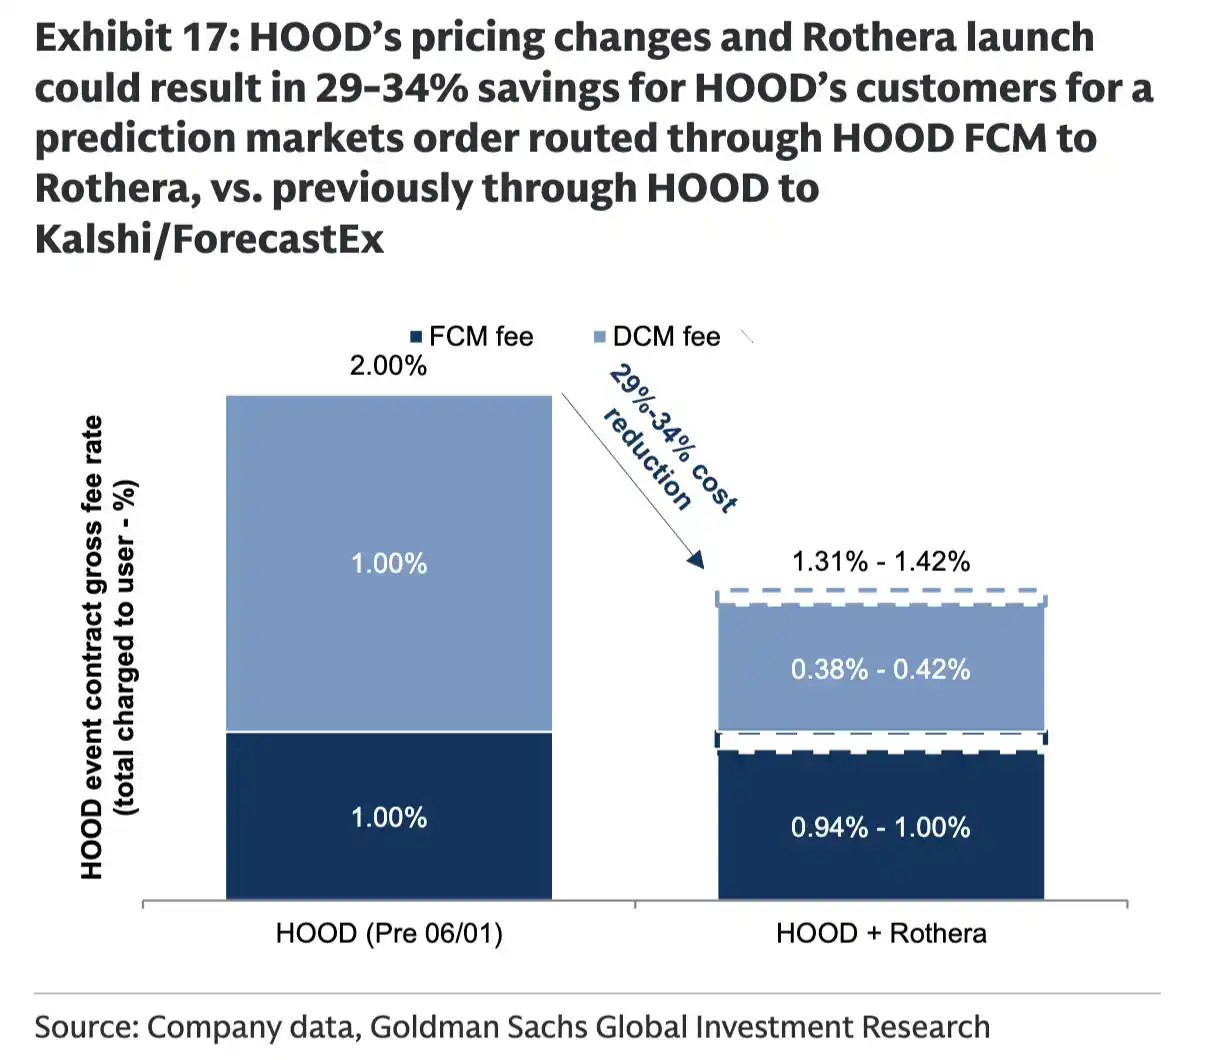
After adopting floating pricing and routing orders to Rothera, the total fee paid by Robinhood customers is estimated to decrease from 2% to 1.31%-1.42%.
For Robinhood, a decrease in customer fees does not necessarily mean platform revenue will decline proportionally. Since the company now earns both brokerage fees and Rothera's exchange fees, Goldman Sachs estimates that, before deducting non-controlling interests, Robinhood's notional total fee rate may have increased from the previous approximately 1.25% to 1.31%-1.42%.
However, only 45% of Rothera's net profit belongs to Robinhood. After accounting for non-controlling interests allocated to other shareholders, Goldman Sachs estimates Robinhood's effective prediction market fee rate is approximately 1.11%-1.19%, slightly lower than the previous level of about 1.25%.
Therefore, the value of this model stems primarily from long-term scale rather than an immediate increase in the effective fee rate. Robinhood is essentially trading a portion of short-term profits for lower customer costs, larger trading volume, and greater control over the trading infrastructure.
Currently, only Robinhood as an FCM is connected to Rothera. If low fees can attract other brokerages to join, the exchange could gain order flow from outside the Robinhood ecosystem and create a 'low fees - more flow - deeper liquidity' cycle. However, until external brokerages join on a large scale, Rothera remains highly dependent on internal traffic from Robinhood.
How Much Revenue Can Prediction Markets Contribute to Robinhood?
Goldman Sachs expects Rothera's revenue to grow from $87 million in 2026 to $307 million in 2027 and further to $444 million in 2028, accounting for 2%, 5%, and 6% of Robinhood's total revenue in those respective years.
During the same period, the net profit attributable to Robinhood from Rothera is projected to be $14 million, $58 million, and $94 million respectively. As early-stage investments decrease and revenue scale expands, the fixed-cost leverage of the exchange business is expected to be unlocked. Goldman Sachs believes its profit margins may trend towards the 55%-70% level of mature derivatives exchanges over the long term.
Rothera is only one part of Robinhood's prediction market business. Besides exchange revenue, the company also earns prediction market revenue from its brokerage side. Goldman Sachs forecasts that Robinhood's total net prediction market revenue will reach $657 million in 2026, increase to $943 million in 2027, and reach $1.15 billion in 2028, accounting for 12%, 14%, and 15% of the company's total revenue, respectively.
Within this, Rothera's share of Robinhood's prediction market revenue is expected to rise from about 13% in 2026 to 33% in 2027 and further to 39% in 2028. This indicates that Rothera will gradually evolve from a supplementary revenue source within the prediction market business to a significant component of it.
Prediction markets are also the main reason Goldman Sachs' revenue expectations for Robinhood are higher than market consensus. Its forecasts for prediction market revenue from 2026 to 2028 are 4%, 10%, and 14% above consensus, respectively, while total revenue forecasts are 2%, 3%, and 3% higher than consensus for those years.
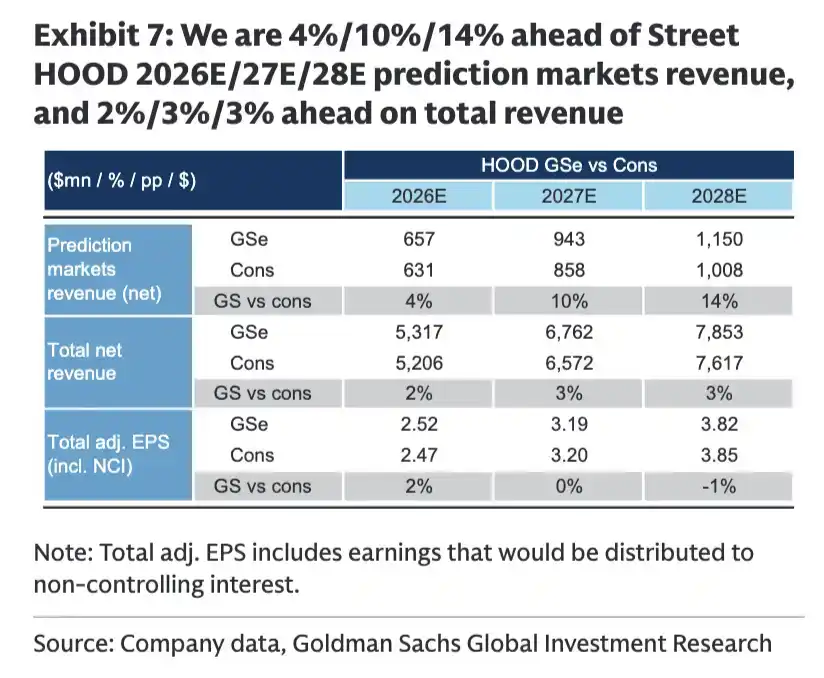
Goldman Sachs expects Robinhood's 2027 and 2028 prediction market net revenue to be 10% and 14% above market consensus, respectively, but the revenue advantage does not fully translate into an EPS advantage.
However, the upward revision in prediction market revenue has not been fully transmitted to earnings per share. Goldman Sachs' forecast for Robinhood's adjusted EPS in 2027 is essentially in line with consensus and is even about 1% below consensus for 2028. This suggests that besides revenue growth, factors like non-controlling interest allocation, product investments, and cost structure will still impact the ultimate shareholder returns.
Rothera may potentially enter other exchange-traded products in the future. Goldman Sachs specifically mentioned perpetual futures, suggesting its exchange license may provide room for product diversification. However, this is currently closer to a potential option and is not yet suitable for direct inclusion in definitive revenue projections. The launch of related products will still depend on regulatory approval, market demand, and specific execution progress.
Valuation Up to $19.5 Billion: What's Needed for the Optimistic Scenario?
Goldman Sachs conducted a sensitivity analysis on Rothera's potential 2027 revenue, profit, and value using three scenarios: base case, optimistic, and pessimistic.
In the base case scenario, Goldman Sachs expects Rothera's 2027 revenue to reach $307 million, with net profit of about $129 million, of which approximately $58 million is attributable to Robinhood. This corresponds to Rothera's total equity value of approximately $5.1 billion to $5.4 billion, with a value attributable to Robinhood of about $2.3 billion to $2.5 billion, equivalent to $2.50 to $2.69 per share.
In the optimistic scenario, Rothera's 2027 revenue could reach $359 million to $906 million, with net profit attributable to Robinhood ranging from $71 million to $195 million. This corresponds to a total equity value of $6.7 billion to $19.5 billion, with a value attributable to Robinhood of about $3.0 billion to $8.8 billion, equivalent to $3.30 to $9.64 per share.
In the pessimistic scenario, Rothera's 2027 revenue could be only $91 million to $242 million, with net profit attributable to Robinhood ranging from $15 million to $44 million. This corresponds to a total equity value of $1.0 billion to $3.6 billion, with a value attributable to Robinhood of about $0.5 billion to $1.6 billion, equivalent to $0.52 to $1.76 per share.
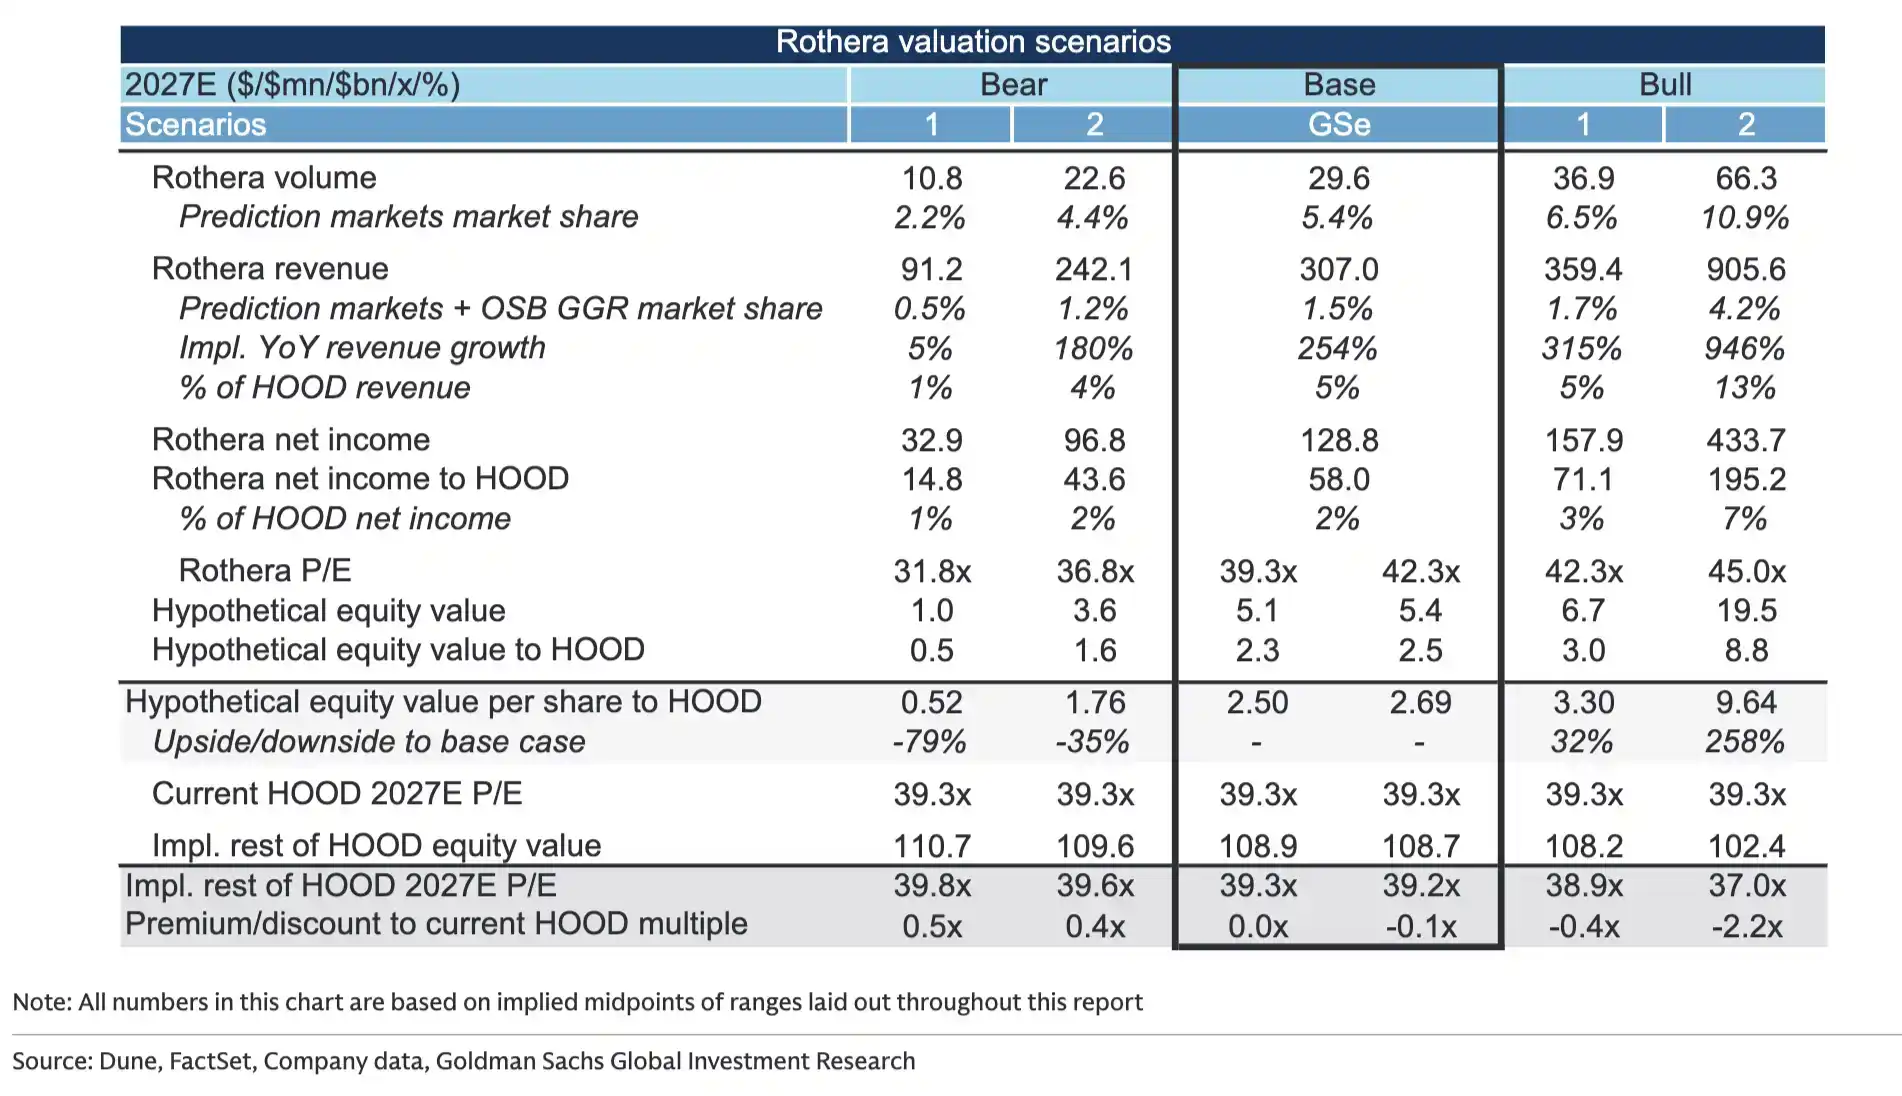
Under different growth scenarios, Goldman Sachs estimates Rothera's total equity value ranges from $1.0 billion to $19.5 billion; the value attributable to Robinhood ranges from $0.5 billion to $8.8 billion.
Goldman Sachs combined the total wagering revenue from prediction markets and online sports betting as the potential market, citing high overlap between the two products. Its estimates show that their combined annualized revenue pool for 2026 is approximately $18 billion and could grow to $20-$21 billion in 2027.
Within this market scope, Rothera's base case corresponds to about a 1.5% revenue share; the optimistic scenario is about 1.7%-4.2%; and the pessimistic scenario is 0.5%-1.2%.
The highest valuation of $19.5 billion implies fairly aggressive growth assumptions: Rothera's 2027 revenue would need to reach $906 million, representing year-over-year growth of 946%; Robinhood would need to continue directing a significant volume of orders to the platform; SIG would need to maintain its market-making support; more external FCMs would need to join; and the product scope would also need to expand from sports contracts to political, economic, and even other derivative products.
This also explains why Goldman Sachs' valuation range is so wide. Rothera's value depends not only on the overall growth of the prediction market but also on its ability to transform from an internal trading venue for Robinhood into an independent infrastructure capable of attracting other brokerages and traders.
Rothera can also partly explain Robinhood's currently high valuation. Robinhood currently trades at an FY+2 Goldman Sachs forecasted P/E multiple of approximately 39.3x, which is at the 87th percentile of the company's valuation range over the past five years, indicating the market has already priced in high growth expectations.
After excluding the value attributable to Robinhood from Rothera, the remaining businesses in the base case scenario correspond to an FY+2 P/E multiple of about 39.2-39.3x; this figure declines to 37.0-38.9x in the optimistic scenario; and is around 39.6-39.8x in the pessimistic scenario.
This does not mean Robinhood's remaining businesses are cheap. Even under the base case calculation, the valuation of the residual businesses remains at the historical 87th percentile and is significantly higher than the average for brokerages and crypto-asset related companies. Goldman Sachs is willing to accept this premium, primarily based on Robinhood's projected 22% revenue growth from 2026 to 2028 and the company's rapid pace of product launches.
Rothera provides a new pillar of support for Robinhood's valuation, but its investment thesis remains built on the basis of continued high-growth delivery. Whether trading volumes can be sustained, whether external brokerages will join, whether non-sports contracts can scale, and whether regulations will permit further product expansion will all determine where Rothera ultimately lands within the $1.0 billion to $19.5 billion valuation spectrum.
What can be confirmed for now is that prediction markets have gradually evolved from a new product for Robinhood into an important variable affecting its revenue expectations and valuation framework. Whether Rothera can translate short-term trading momentum into a stable liquidity network will be key to the credibility of Robinhood's next phase of growth narrative.