Author: Alea Research
Compiled by: TechFlow DeepTide
TechFlow DeepTide Introduction: While traditional settlement systems like Fedwire, T2, and CHAPS shut down for 44 to 60 hours every weekend, dollar stablecoins from the crypto world are filling the void. The Open USD, launched by Coinbase, Stripe, and Visa, saw $447 million running on Tempo the day after its launch. This tokenless settlement network is eating into the most expensive part of cross-border payments. For practitioners, this isn't just another stablecoin news—it's an early signal of a direct collision between traditional finance and crypto infrastructure.
The Markets Never Close, But the Dollar Does
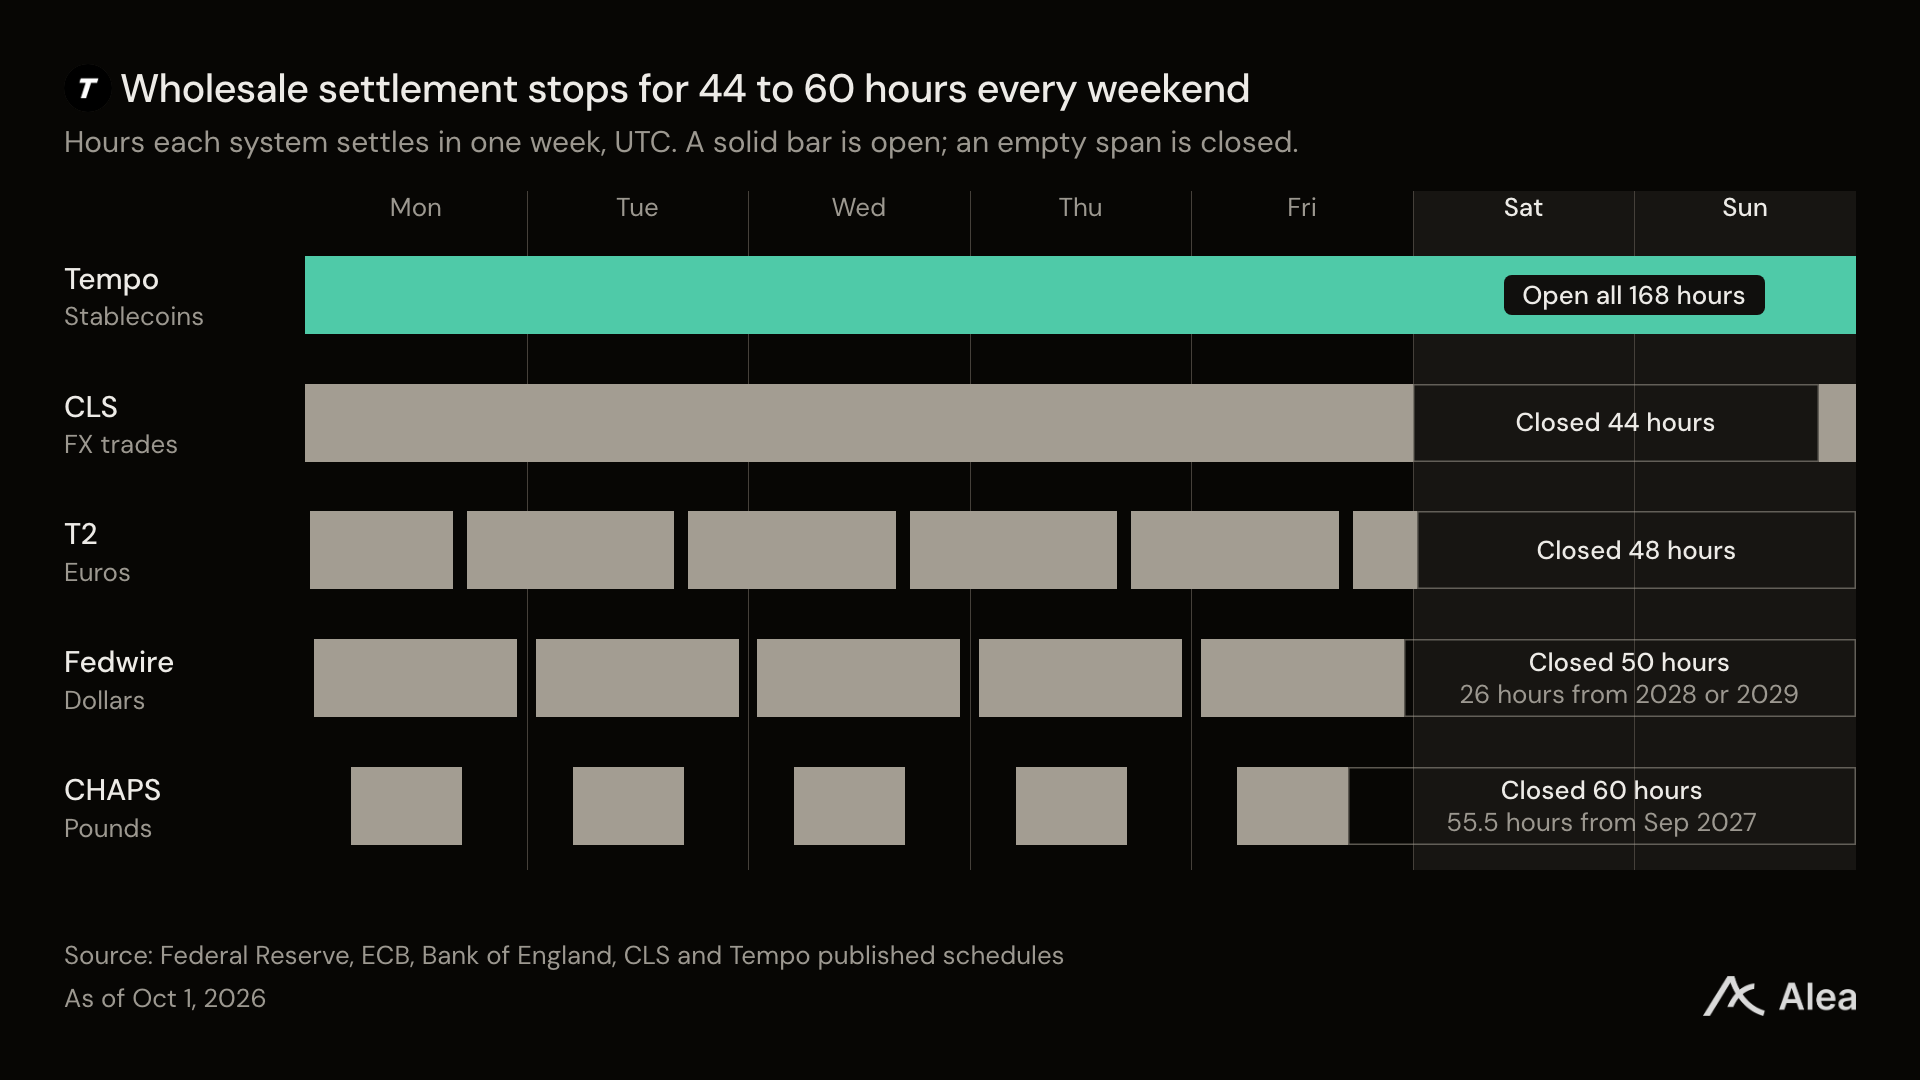
Fedwire, T2, CHAPS, and CLS cease settlement for 44 to 60 hours every weekend. Tempo settles hourly, and Open USD had $447 million running on it one day after launch.
Markets now trade over weekends, but the dollars to settle those trades still adhere to banking hours. Fedwire settled $1.15 quadrillion in 2025, with not a single dollar moving on a Saturday. On September 30th, Open USD launched—a dollar created by a consortium including Coinbase, Mastercard, Shopify, Stripe, and Visa. One day later, $447 million out of its initial $490 million was already running on Tempo. Tempo is indeed targeting the three places where the dollar gets stuck: weekends, borders, and bank ledgers that can't pay forward.
Weekend settlement will remain closed for many years. Fedwire will add Sunday service in 2028 or 2029, with Saturday remaining closed. Bank weekend stablecoin pools on Tempo break even at 1.5 basis points, while tri-party collateral mobilization costs range from 1 to 3 basis points.
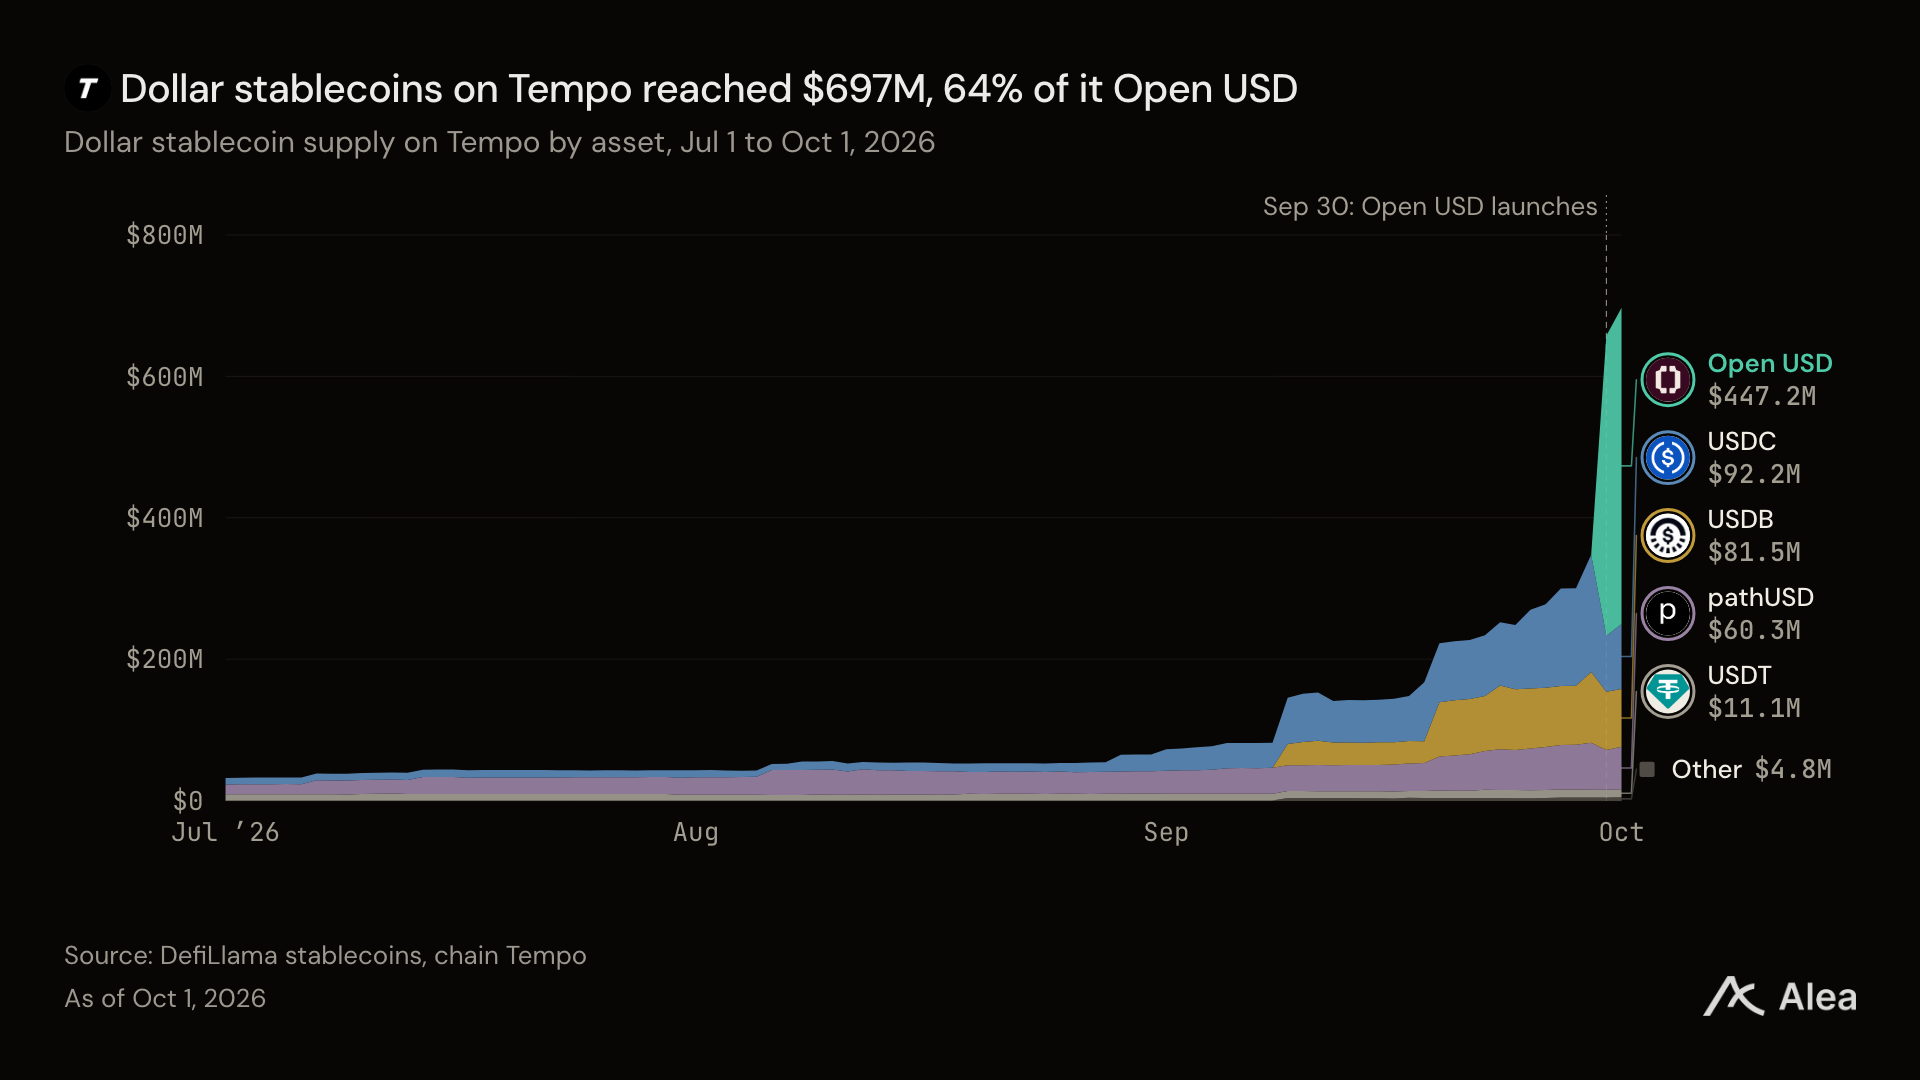
Open USD placed the majority of its initial dollars on Tempo. On October 1st, its first full operational day, $447 million out of the $490 million in circulation was on Tempo, bringing the network's dollar supply to $697 million, double the level on September 29th.
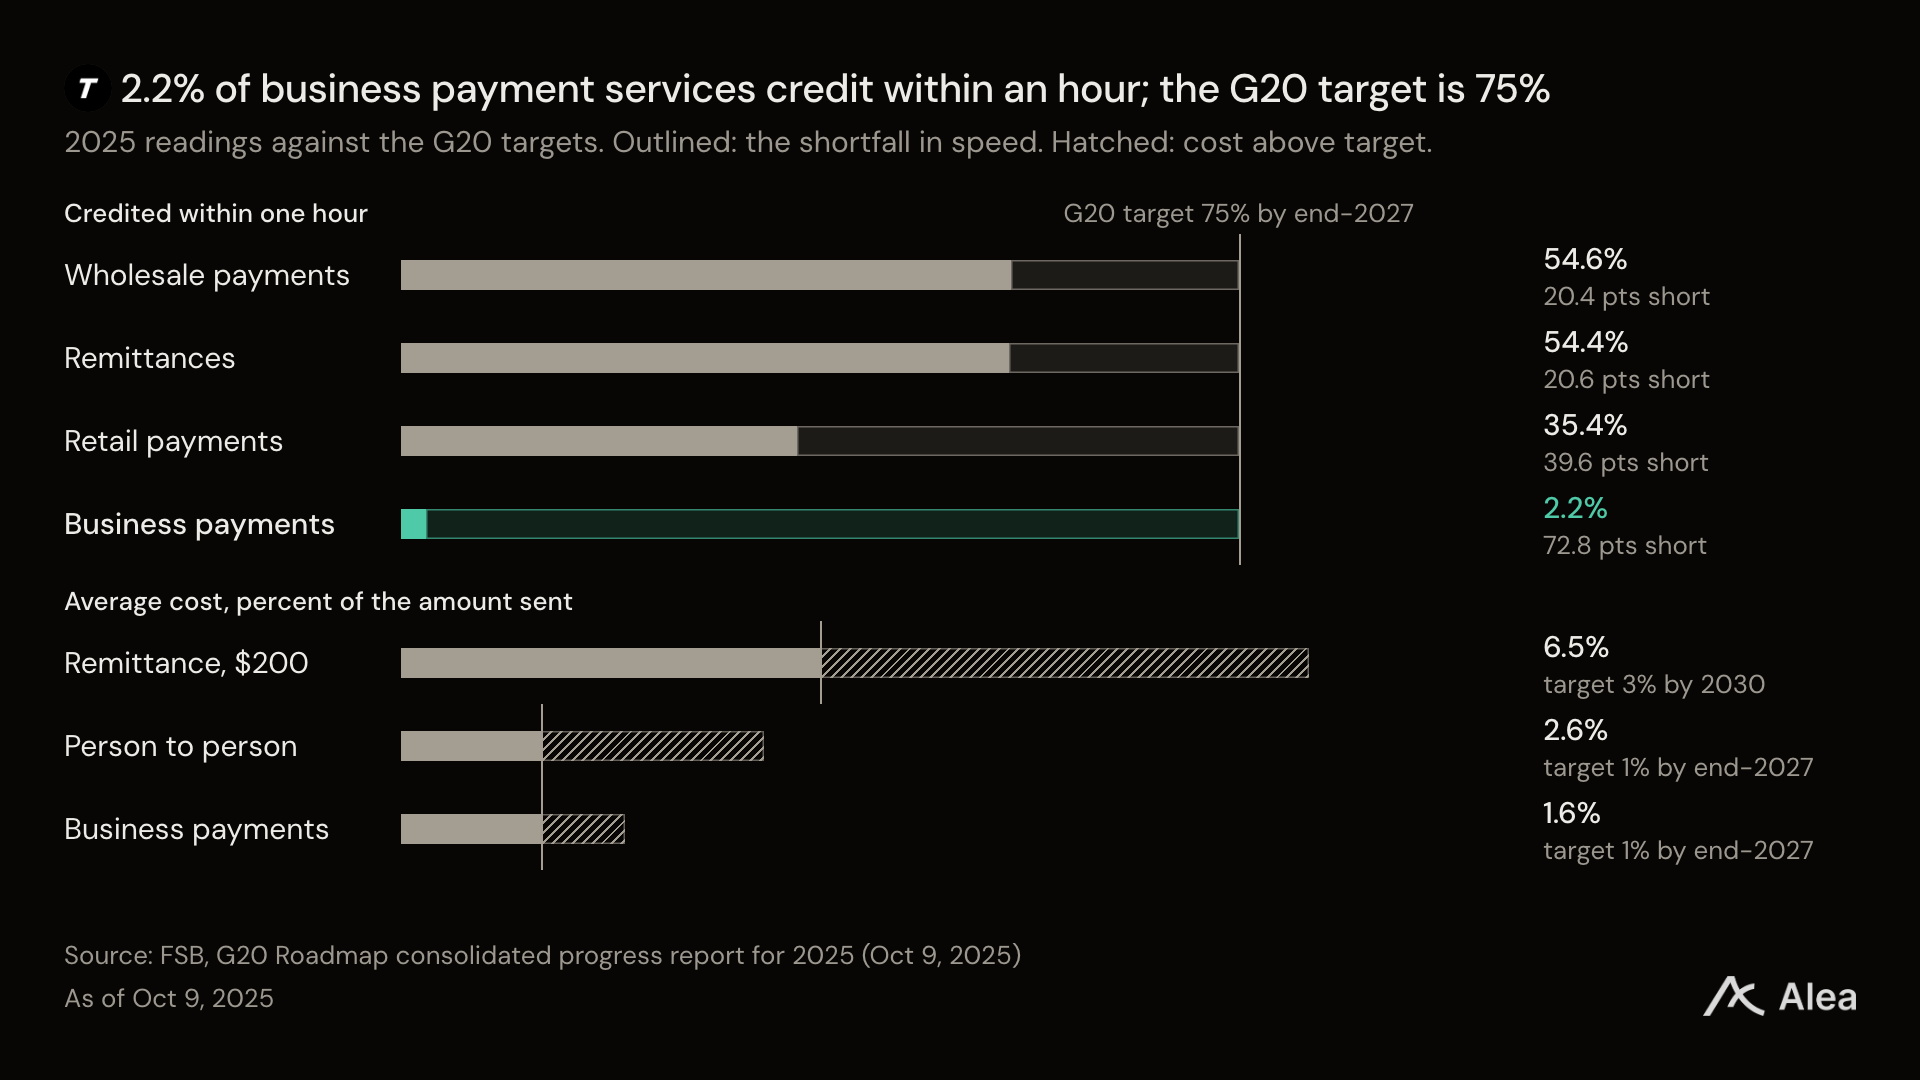
Cross-border payments aren't even meeting their own targets. In 2025, only 2.2% of business-to-business payment services were credited within one hour, while the G20 target is 75% by the end of 2027.
Tempo pushes transfer pricing close to zero. From the fee reduction on July 10th to October 1st, the median fee per transaction averaged $0.00003, with the payer using stablecoins they already hold.
Money is in float, and in the services around each payment. Reserve earnings go to the issuer, and for Open USD, to the partners bringing the supply. Tempo makes money by selling API access and consulting services, and it has no token.
A Dollar That Can Settle on Saturdays
Over a weekend in April, trade.xyz settled $15 billion in oil and stock index contracts using stablecoins, while systems for settling large payments were closed. These systems operate on business-day clocks. Fedwire opens at 9 p.m. New York time the night before each business day, closes at 7 p.m., and is offline for 50 hours every weekend. The euro system T2 closes for 48 hours, the pound system CHAPS for 60 hours, and CLS, which settles forex trades, closes for 44 hours.
These schedules change slowly. The Federal Reserve will add Sunday to Fedwire in 2028 or 2029, with Saturday remaining closed. The Bank of England will move CHAPS opening time forward to 1:30 a.m. starting September 2027. Instant systems like FedNow already run hourly but have a $10 million per-payment cap.
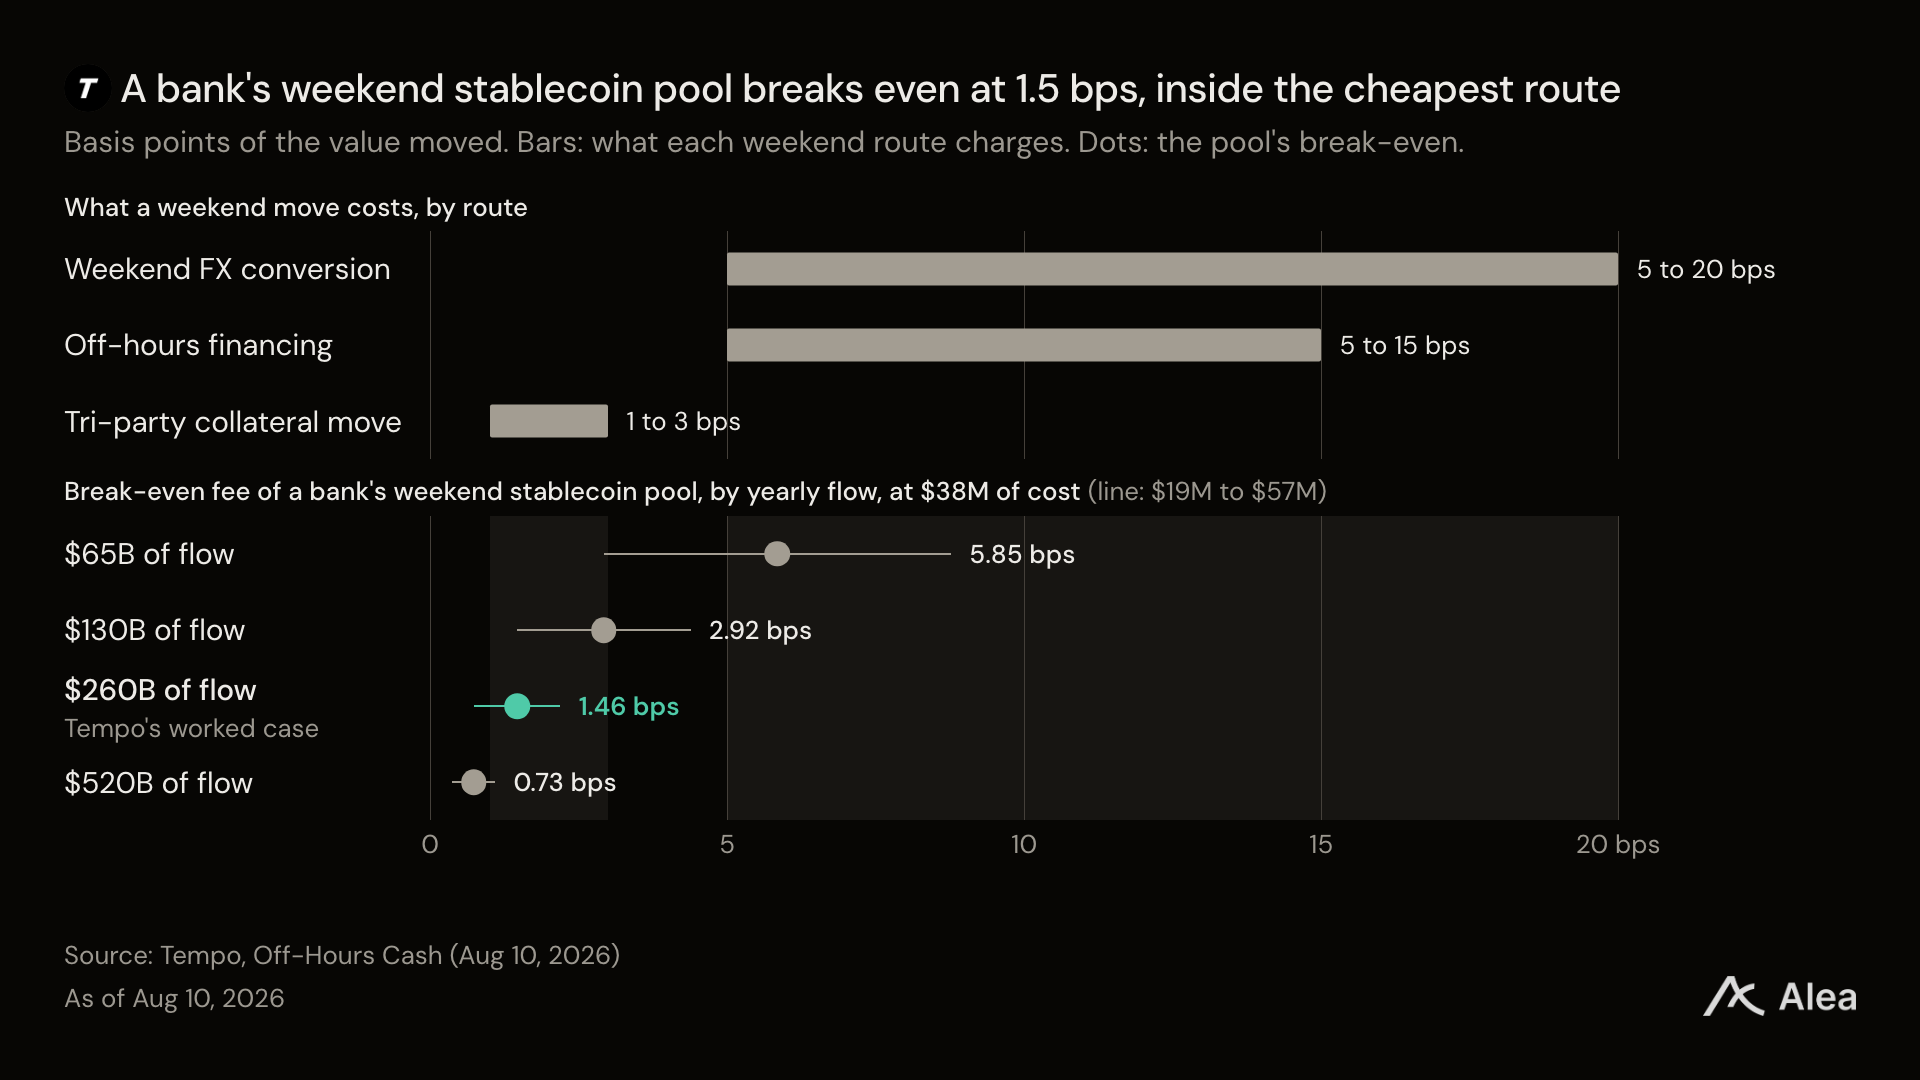
The Tempo team built its banking narrative around this weekend closure. Its "After-Hours Cash" paper models a scenario where a bank converts wholesale deposits into its own stablecoin at 4:30 p.m. on Friday. Clients use it for margin calls or to settle trades over the weekend, with unused balances automatically converted back to deposits on Monday. A bank with $500 billion in assets, holding a $5 billion peak pool, would incur an annual cost of about $38 million, serving approximately $260 billion in flow, breaking even at a fee of 1.5 basis points.
This figure is lower than or on par with the cost of every weekend alternative. Tri-party collateral mobilization costs 1 to 3 bps, weekend FX conversion 5 to 20 bps, and after-hours prime broker financing spreads 5 to 15 bps.
Cash No Longer Waiting at Every Border
Cross-border payments take time because each corridor requires pre-funding cash at the other end before a payment can be made. Businesses move about $23.5 trillion cross-border annually, paying about $120 billion in transaction fees. FX spreads and the cost of pre-funding are not included.
The G20 set a target for the end of 2027: 75% of cross-border payments to be credited within one hour, with an average retail payment cost of 1%. The Financial Stability Board's 2025 monitoring found 54.6% of wholesale and 35.4% of retail payment services were credited within an hour. But for business-to-business services, it was only 2.2%. Sending $200 overseas costs an average of 6.5%, while the 2030 target is 3%. The FSB expects unsatisfactory global progress by 2027.
The pain is felt first by companies that make external payments daily, several of which already run on Tempo. MoneyGram joined as Tempo's first remittance validator node and settlement partner, Felix settles remittances on Tempo. Deel launched DLUSD, a stablecoin wallet for contractors, with Tempo as its only chain. Coastal Bank built a corridor where messaging, screening, and bank confirmations remain the same, only the value leg moved to Tempo.
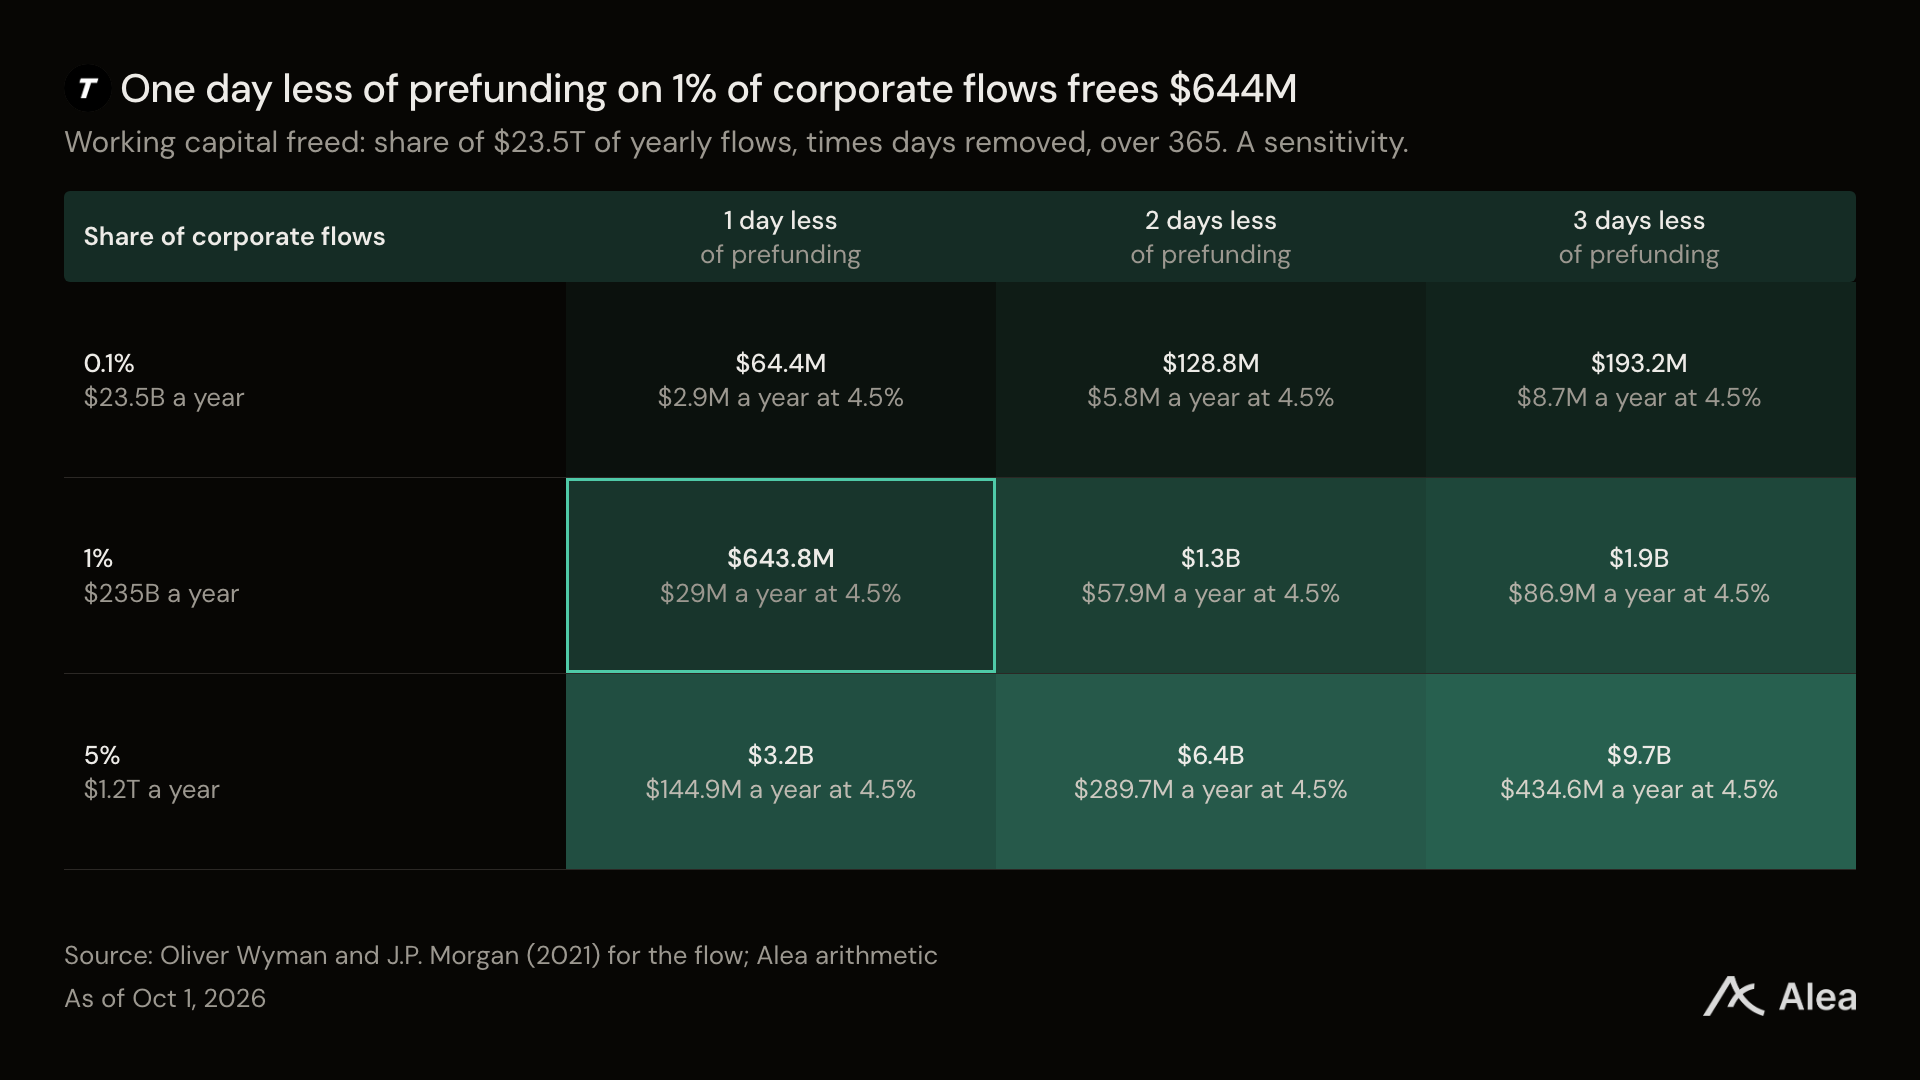
Each day less of pre-funding releases cash. If 1% of corporate cross-border flow reduces pre-funding by one day, about $644 million in working capital is freed. Assuming a 4.5% cost of capital, holding this balance costs roughly $29 million annually.
One Pool of Cash, Multiple Markets
Tempo's own research suggests speed is no longer the differentiator between settlement networks. Its July paper identifies the true differentiating attribute as liquidity mobility, meaning "the same cash can settle a repo trade, fund a cross-border payment, post margin at a derivatives venue, and settle a tokenized securities transaction." None of these steps require re-issuing cash. In Alea's Market Cap show, co-author Borja Neira said each generation of market infrastructure frees trapped cash, only to trap it again in new places.
Existing networks force a choice between privacy and liquidity. Public chains fragment about $40 billion in liquidity across twenty-plus rollups, while the largest private bank ledgers clear nearly $400 billion in repo daily—cash that serves only that one market. Tempo separates private execution from shared settlement. Tempo Zones run private transactions on parallel chains, while balances remain on a shared network. The first Zone goes live for a client in October.
Open USD now gives companies moving funds their own dollar. The Open Standard, founded by Coinbase, Mastercard, Shopify, Stripe, and Visa, launched it on Base, Ethereum, Solana, and Tempo on September 30. Stripe-owned Bridge handles issuance, with BlackRock, Lead Bank, and BNY holding reserves. As of October 2, 88.3% of these reserves were in Treasuries, 11.7% in cash.
The bulk of new dollars flowed to Tempo. October 1st, the first full trading day, saw 91% of circulating Open USD on Tempo, making up 64% of the network's dollar stablecoin total. Launch day added $424.3 million in Open USD, while USDC, USDB, and pathUSD on Tempo decreased by $114.5 million, resulting in a net increase of $309.8 million network-wide. Businesses can mint and redeem Open USD on Tempo for free via Coinbase, Stripe, and Visa.
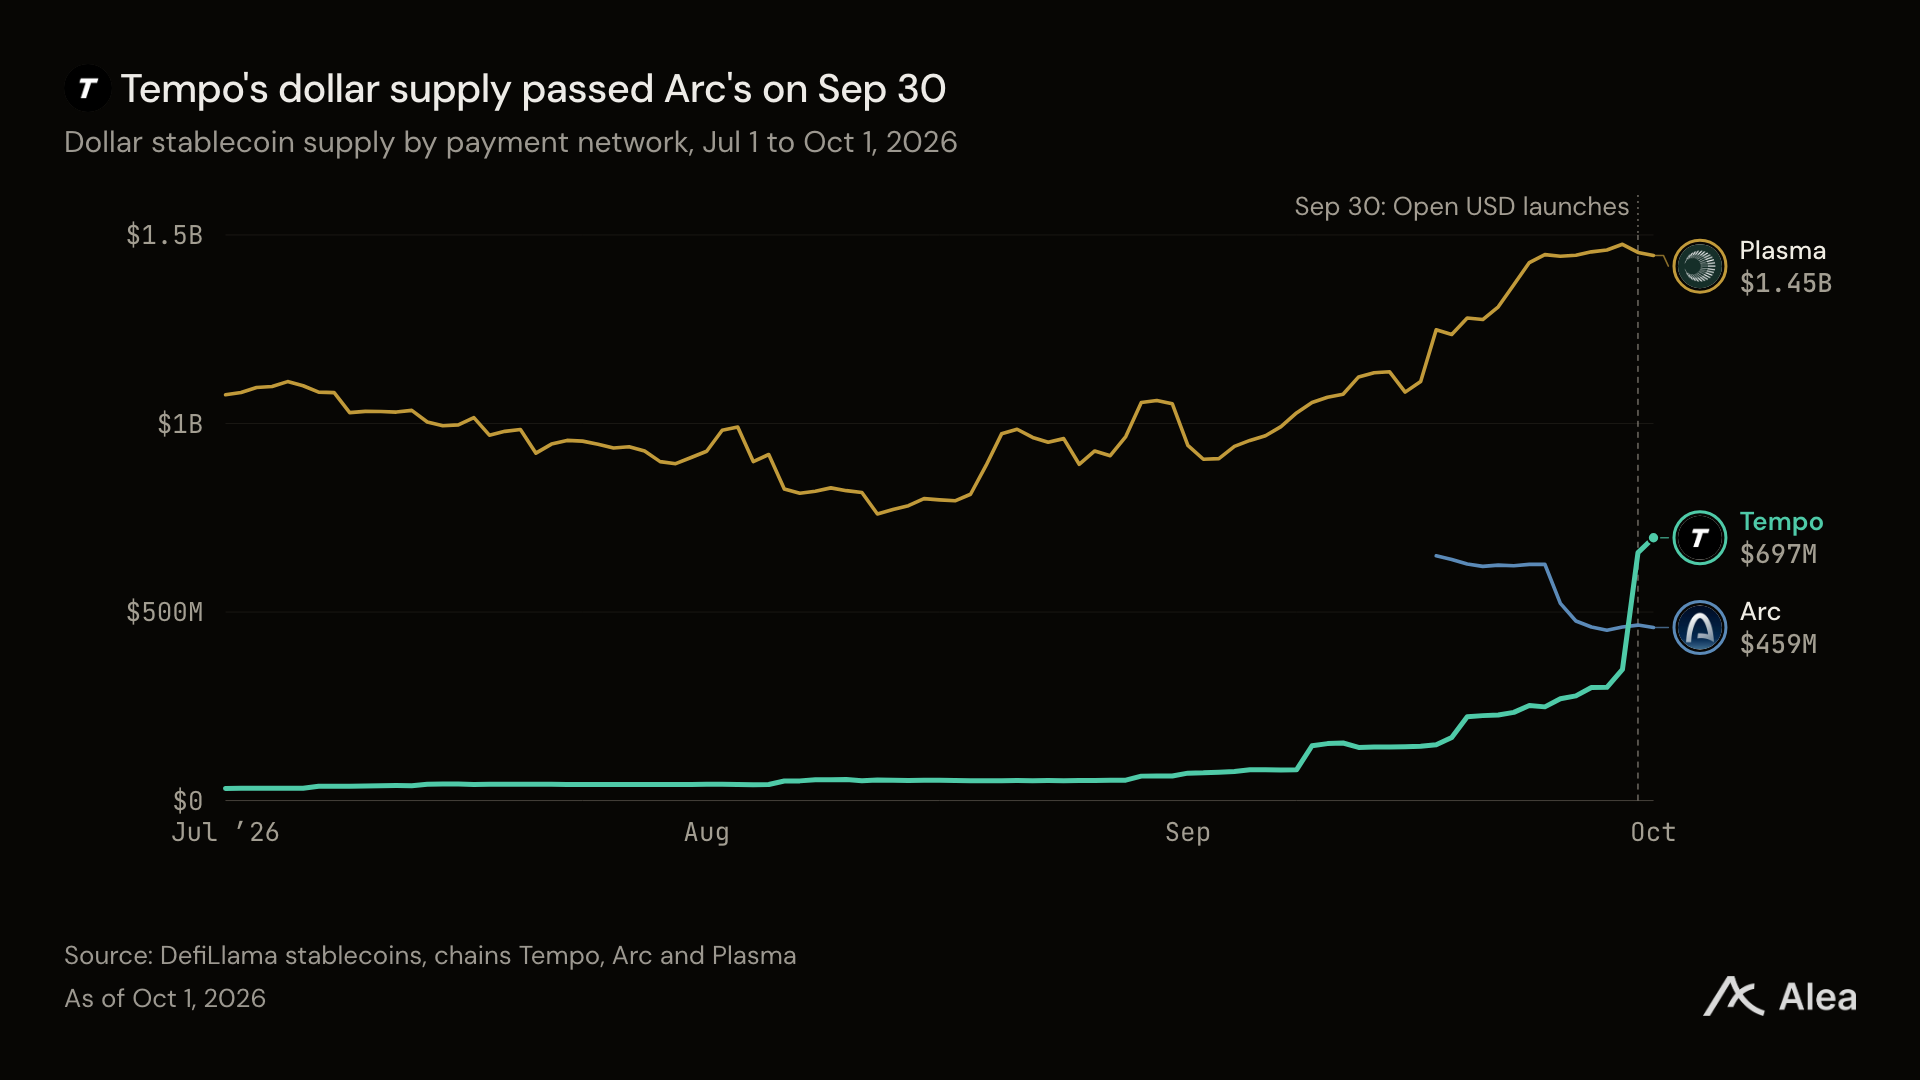
This supply places Tempo between Arc and Plasma. It surpassed Arc on September 30, two weeks after Arc's mainnet launch; by October 1, its size was about half of Plasma's $1.45 billion.
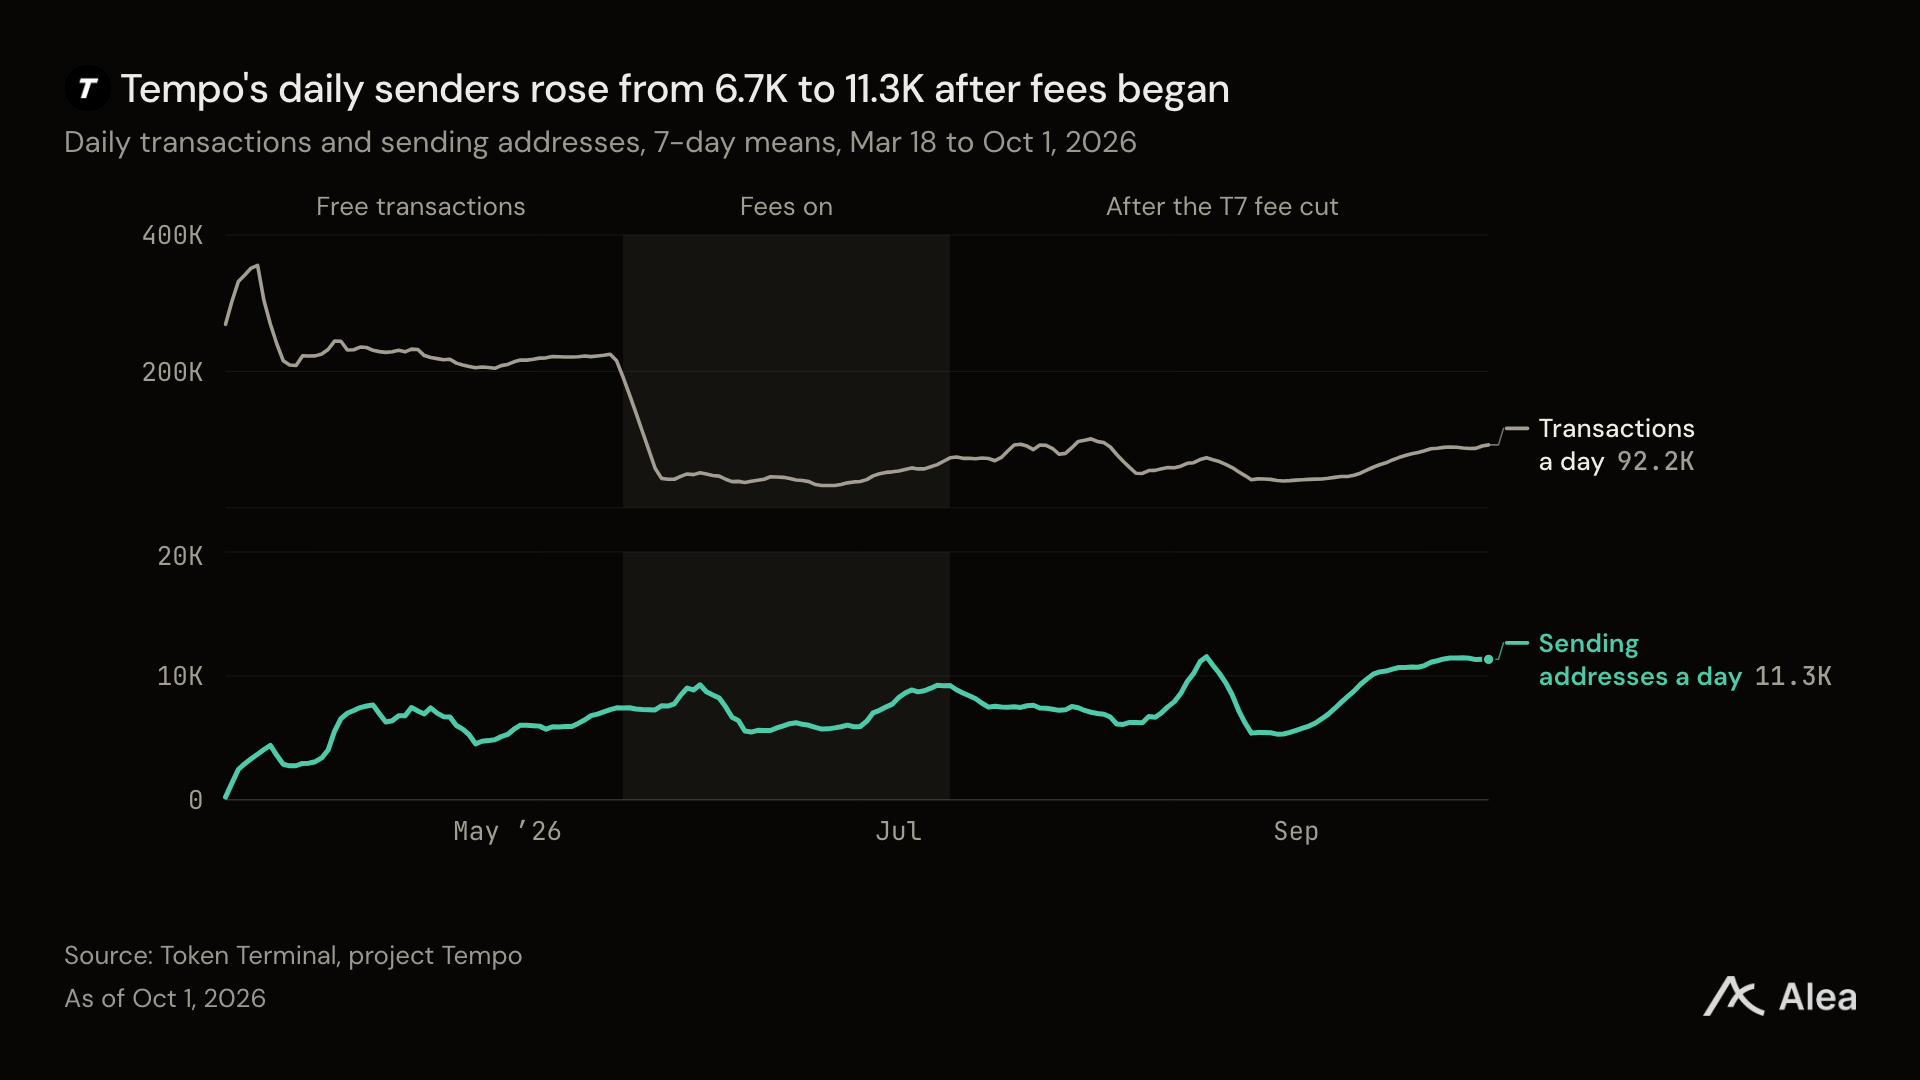
After the free flow period ended, the number of sending addresses continued to grow. During free transactions, the network processed about 230,000 daily transactions. After fees began on May 19, daily volume dropped to about 42,000 over the next month, while daily sending addresses remained around 6,700. By October 1, the seven-day average reached 11,338 sending addresses and 92,228 transactions.
Built for Finance Teams
Tempo starts from the work finance teams do after funds arrive. Senders can pay fees with any supported dollar stablecoin, and apps can cover fees for users. Each transfer includes a memo for invoice correlation; issuers can set roles and transfer policies on their tokens. Tempo reserves about 94% of each block for payment transactions, leaving 6% for general computation.
Competing stablecoin networks differ in what asset payers must hold for fees. Circle's Arc, launched September 16, charges fees in USDC. Plasma charges fees in its own XPL token, with USD₮ transfers being free. On Tempo, every supported dollar stablecoin pays fees with its own token, whether the issuer is a bank, a fintech, or if it's USDC.
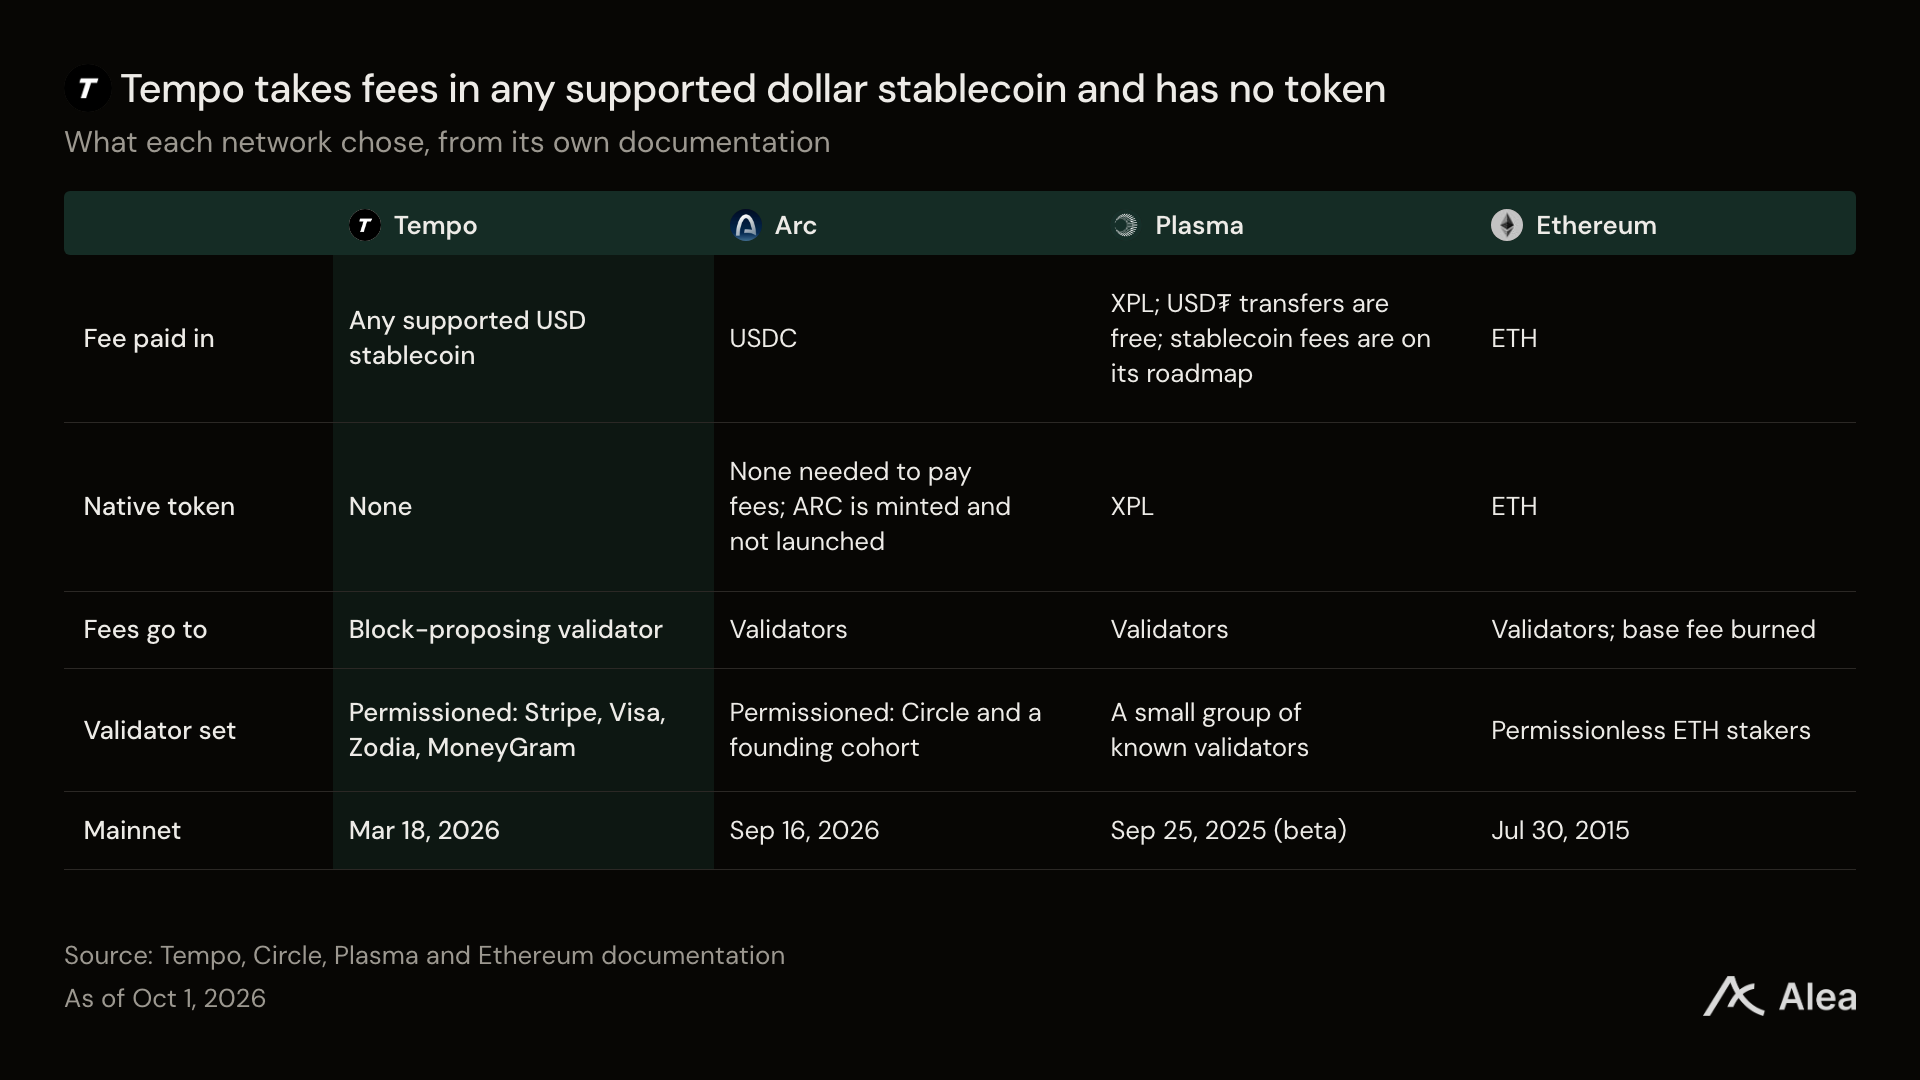
Tempo also launched with ready-made distribution channels. Stripe, Visa, and Zodia run validator nodes alongside MoneyGram. The validator set is permissioned; Tempo has outlined a path to permissionless validation but hasn't set a date. Businesses on Stripe processed $1.9 trillion in 2025, up 34% year-over-year, about 1.6% of global GDP. Stripe runs its own treasury management on Tempo across 100+ countries, and as of September 30, offers Open USD to its businesses, which can fund Stripe Treasury accounts from wallets on Tempo.
Who Earns What When a Dollar Moves
Money from a payment flows to four parties.
Validators get all network fees, which are designed to be low. From the fee cut on July 10 to October 1, the network collected $1,185 from 5.8 million transactions over 84 days.
Liquidity providers keep 0.3% of the fee when converting it in the Fee AMM to a stablecoin acceptable to validators.
Issuers and their partners earn the yield on reserve assets backing each stablecoin. Open USD distributes reserve earnings to partners, deducting only a small management fee. Tempo Earn, launched August 12, lets platforms put idle balances into tokenized money market funds, on-chain lending, and institutional credit, setting their own reward-sharing split with users.
Tempo sells services around the network: a usage-based custody API, including fee sponsorship, and a stablecoin consulting team working with banks. Tempo does not disclose its take rate.
Business Model: Senders or sponsors pay network fees with stablecoins; each fee goes to the validator proposing the block. The Fee AMM pays liquidity providers 0.3% for fee conversion. Issuers keep reserve earnings, or like Open USD, distribute them to partners, with Earn platforms choosing their reward split. Tempo's revenue comes from API usage and consulting work; take rate undisclosed. No token, no buybacks, no holder claim on network cash flow.
For businesses, no token means one less volatile asset in each payment. For Tempo, revenue comes from services it sells, demand for which grows as funds on the network increase.
How Much Money Can Flow This Way
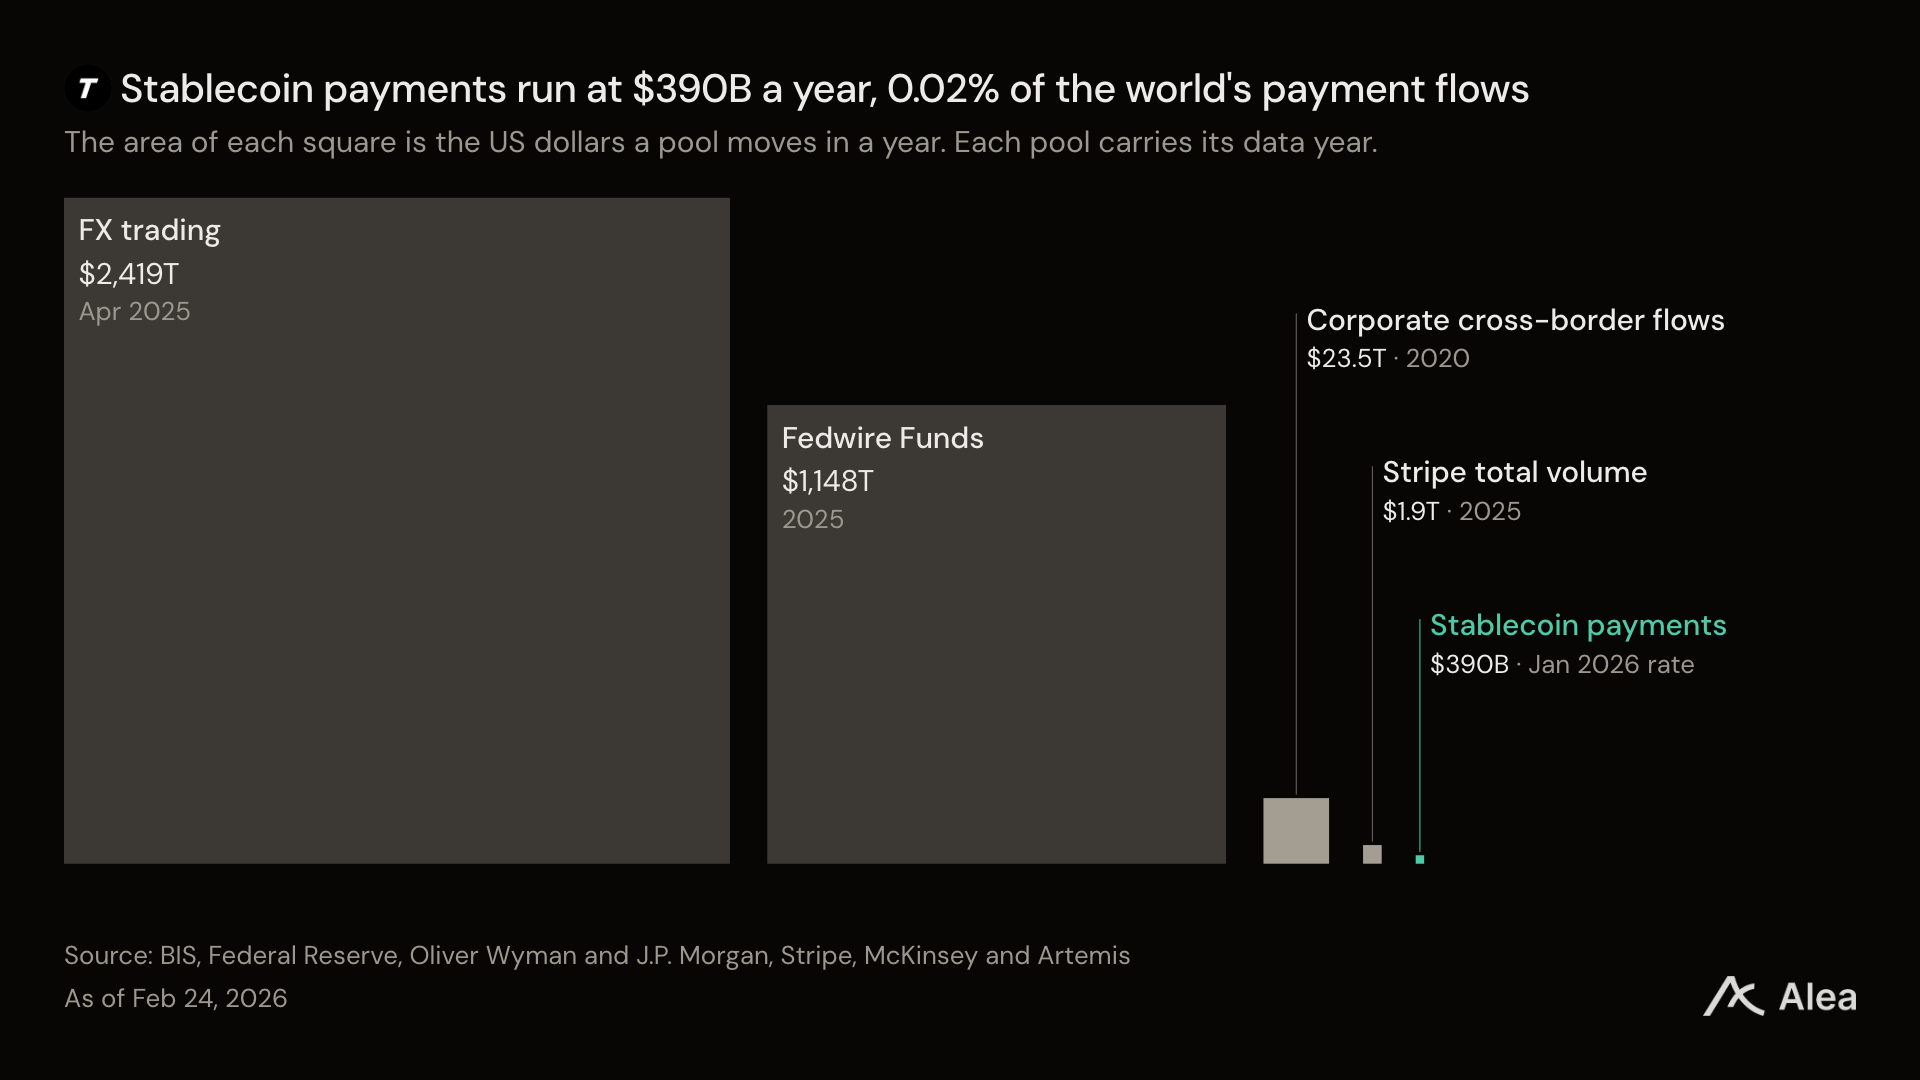
Stablecoin payments run at about $390 billion annually, accounting for 0.02% of global annual fund flows exceeding $2,000 quadrillion. This figure covers payroll, vendor, and remittance payments. Stablecoin transfer volume reaches $35 trillion annually, most of which is trading and internal transfers.
The pools around this number are much larger. Fedwire's 2025 settlement volume alone is about 2,900 times that, while forex markets trade $9.6 trillion daily. Corporate cross-border flows are $23.5 trillion, 60 times the stablecoin figure.
What Launches Before January
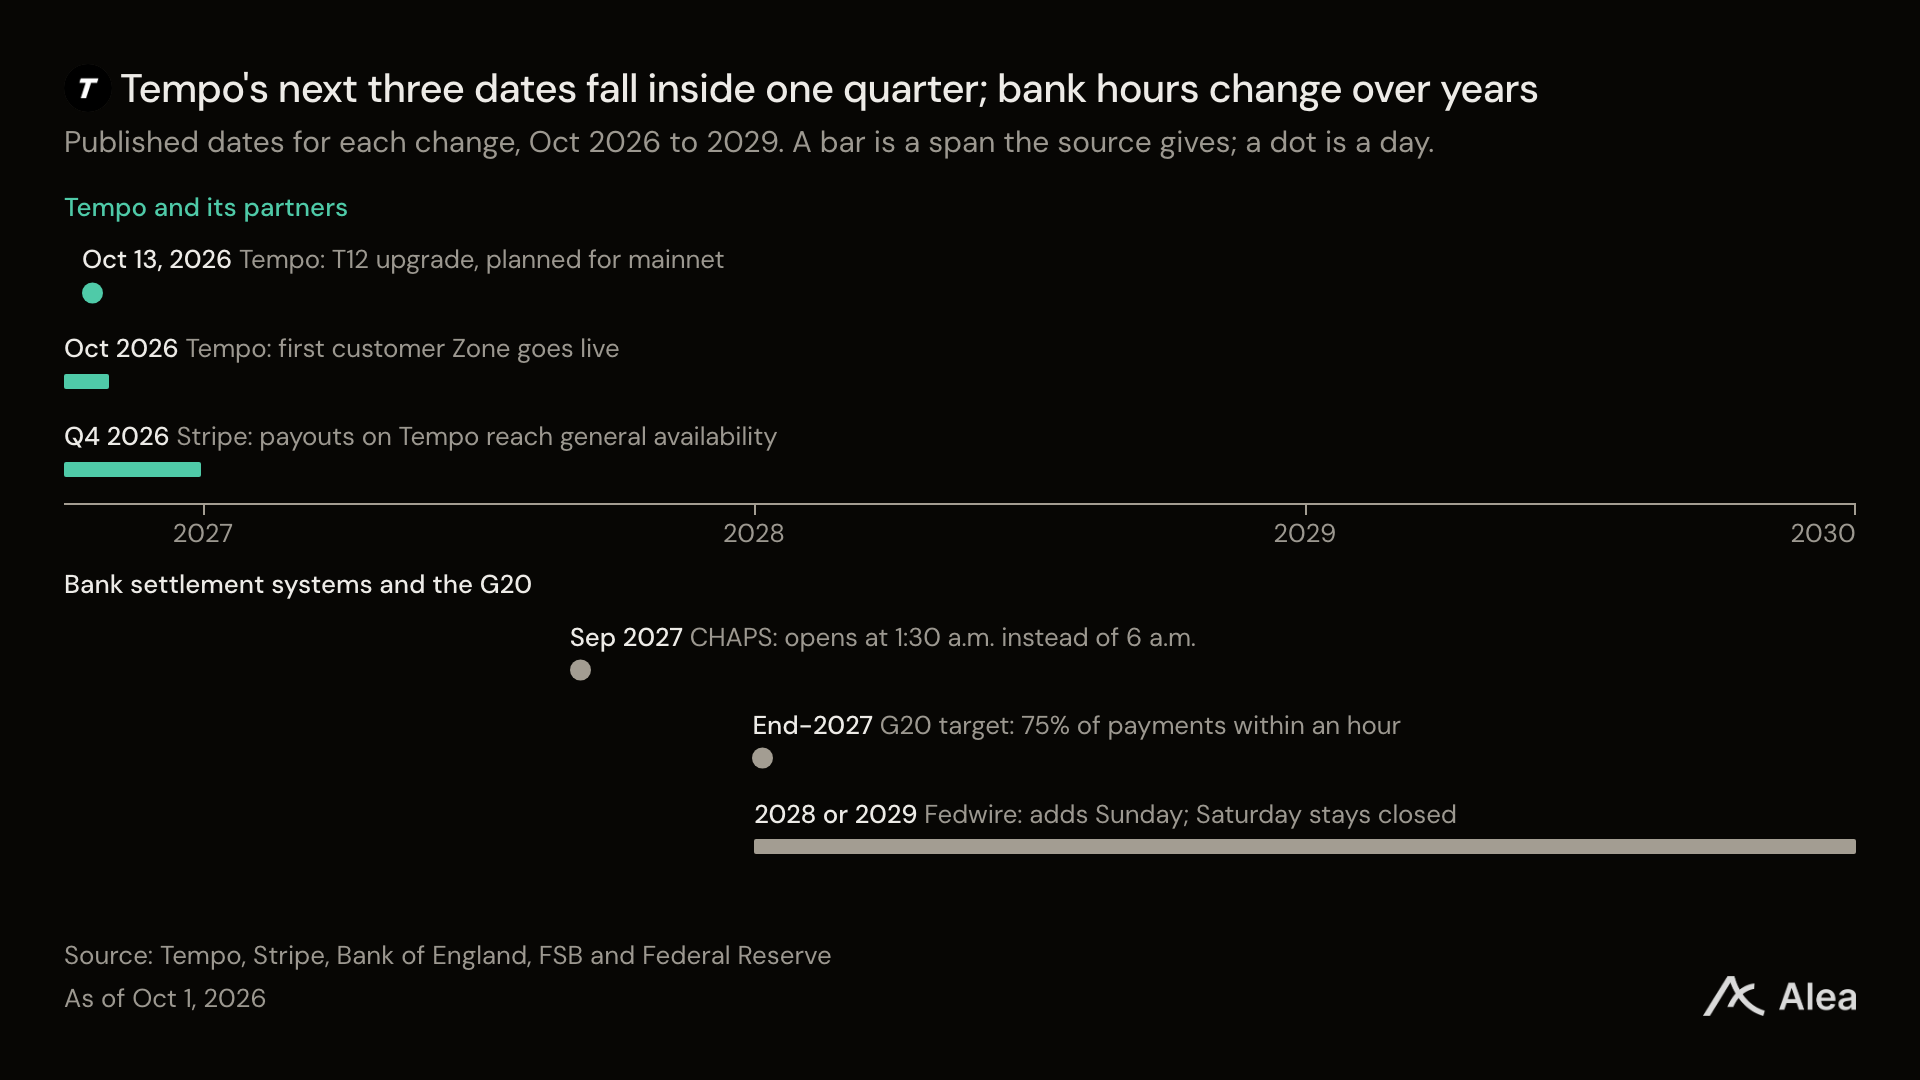
Tempo's next three milestones fall in Q4. The T12 upgrade is scheduled for mainnet on October 13. It adds payment sessions for closed-loop stablecoins, allowing issuers to move tokens across chains via burn-and-mint without separate user approval. The first Zone goes live in October, with Stripe planning full payment functionality on Tempo in Q4. Tempo also lists two upcoming Open USD additions: access via Mastercard, and support in Tempo Earn.
Adjustments to bank settlement times follow longer schedules. CHAPS starts running at 1:30 a.m. from September 2027, Fedwire adds Sunday settlement in 2028 or 2029, and the Bank of England proposed Sunday settlement no earlier than 2029.
Containers Didn't Make Ships Faster
Containers worked by eliminating the need to unload and unpack at every port; trade grew around this box. Tempo does the same for cash: funds move between different markets on one network without re-issuance at each stop. Stripe's treasury management already runs on it, and it held $447 million of Open USD on its first full trading day. Fedwire won't settle on Sundays until 2028, while Tempo already settles every hour of every week.