Author: shaunda devens
Compilation: Baihua Blockchain
Disclaimer: This article is reproduced content. Readers can obtain more information through the original link. If the author has any objections to the reproduction form, please contact us, and we will make modifications as requested by the author. Reproduction is for information sharing only and does not constitute any investment advice, nor does it represent the views or positions of Wu Shuo.
Full text as follows:
Hyperliquid continues to implement geographic blocking (geoblocked) for the U.S. market because its permissionless on-chain infrastructure conflicts with U.S. market structure laws—which strictly limit futures trading to registered trading platforms, clearinghouses, and brokers. The Hyperliquid Policy Center has urged the CFTC and SEC to modernize these regulatory frameworks, advocating that regulated entities should be allowed to build products on HyperCore through builder and deployer seats, as long as they undertake corresponding compliance obligations. Now, corroborated by Trump's statement, the most likely path for Hyperliquid's onshoring is through a permissioned HIP-3 DEX.
I. Core Details
Over the past year, much of our work on Hyperliquid has been to reposition it from a "decentralized perpetual contract trading platform" to "modern market infrastructure": a globally accessible, composable platform for financial instruments encompassing perpetual contracts, spot, and prediction markets.
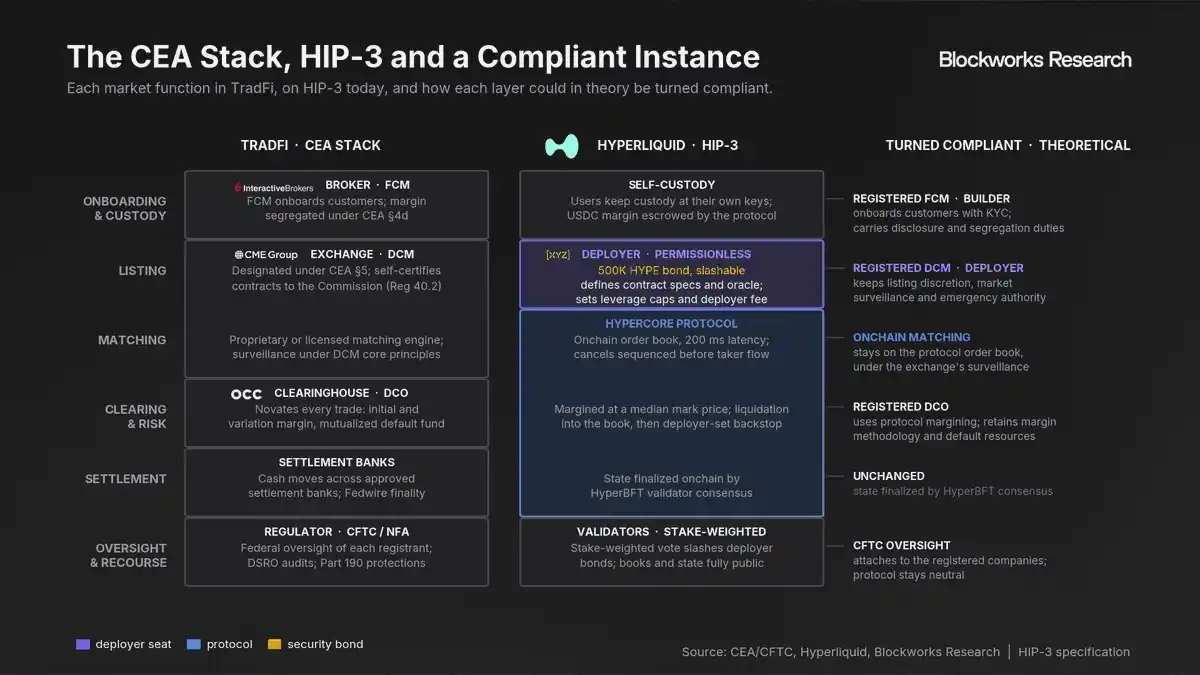
Unlike monolithic crypto platforms like Coinbase and Binance that handle the entire process themselves (from user onboarding, custody to trade execution), Hyperliquid's infrastructure layer is more akin to the separation of duties across entities in traditional finance (TradFi): the trading platform (DCM) is responsible for listing contracts and matching trades; the clearinghouse (DCO) is responsible for providing margin and ensuring settlement; the broker (FCM) is responsible for user onboarding and routing trading access.
Similarly, Hyperliquid's modular technology stack embodies this exact same separation of duties. HyperCore (the trading platform and clearing layer) runs matching, margin calculation, and settlement as underlying protocol logic, marking positions to market based on validator oracles, and executing liquidations through a deterministic waterfall mechanism. Deployers must stake 500,000 HYPE as slashable margin, responsible for token listing, setting contract specifications, leverage limits and oracle configurations, and can retain up to 50% of the fees generated by their markets. Builders act as brokers, responsible for guiding user onboarding and routing trading flow to HyperCore, receiving a share of transaction fees.
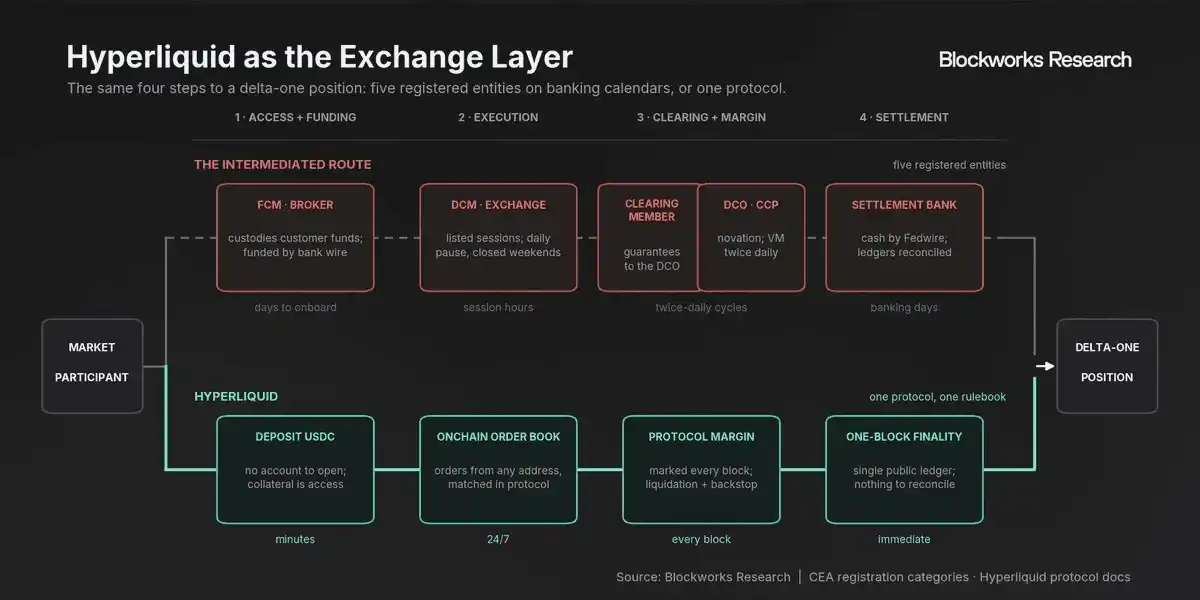
However, Hyperliquid reconstructs these layers on-chain and enforces them through programmed code: onboarding and market creation are permissionless, assets are fully self-custodied by users, other applications can be built on top of it, and all assets are traded 24/7 on a single global platform, eliminating the geographical and legal fragmentation of traditional finance.
II. Hyperliquid's Regulatory Dilemma
In this context, Hyperliquid's biggest challenge is regulation: U.S. market structure laws are tailored for traditional architecture, and each of its legally defined registered roles structurally conflicts with Hyperliquid's underlying design. For example:
• A Designated Contract Market (DCM) must adhere to 23 core principles under Section 5(d) of the Commodity Exchange Act (CEA), including market surveillance and customer identification. Yet anyone with a wallet can access HyperCore.
• A Derivatives Clearing Organization (DCO) must calculate margin using models approved by its board with 99% confidence levels and settle through approved settlement banks (17 CFR §§39.13–39.14). HyperCore relies on protocol logic for margin calculation and settles at the consensus layer.
• A Futures Commission Merchant (FCM) must segregate customer funds under CEA Section 4d. Hyperliquid users self-custody, which is fundamentally different from the custodial FCM model.
It is these stringent requirements that have forced even centralized KYC-enforcing platforms like Coinbase to register as FCMs and acquire existing DCM companies for their U.S. operations. Hyperliquid cannot replicate this model because acquiring a DCM and conforming to existing regulation would contradict its goal of "revolutionizing underlying infrastructure"; therefore, it chose to self-impose geographic blocking, withdrawing from the world's largest capital market.
Nonetheless, Hyperliquid's goal is not to remain offshore permanently: In February 2026, it announced the establishment of the Hyperliquid Policy Center (HPC), funded with 1 million HYPE (approximately $72.5 million at current prices), dedicated to bringing this new market structure within the U.S. legal framework.
In July, HPC, alongside Phantom, petitioned the CFTC to confirm that releasing on-chain software itself does not trigger licensing requirements, allowing existing licensed institutions to run matching, settlement, and margin calculation on on-chain infrastructure, and establishing exemptions that permit non-custodial wallets to route users to regulated derivatives. In August, HPC and TradeXYZ brought the same logic to the SEC, proposing a regulatory framework for Pre-IPO perpetual contracts (such as SpaceX and Cerebras, already trading on Hyperliquid), accompanied by disclosure and qualification rules necessary for opening them to U.S. investors. Early signs indicate the strategy is working and U.S. regulators are receptive, the most visible signal being Trump's announcement that Chairman Selig plans to push for Hyperliquid's onshoring.
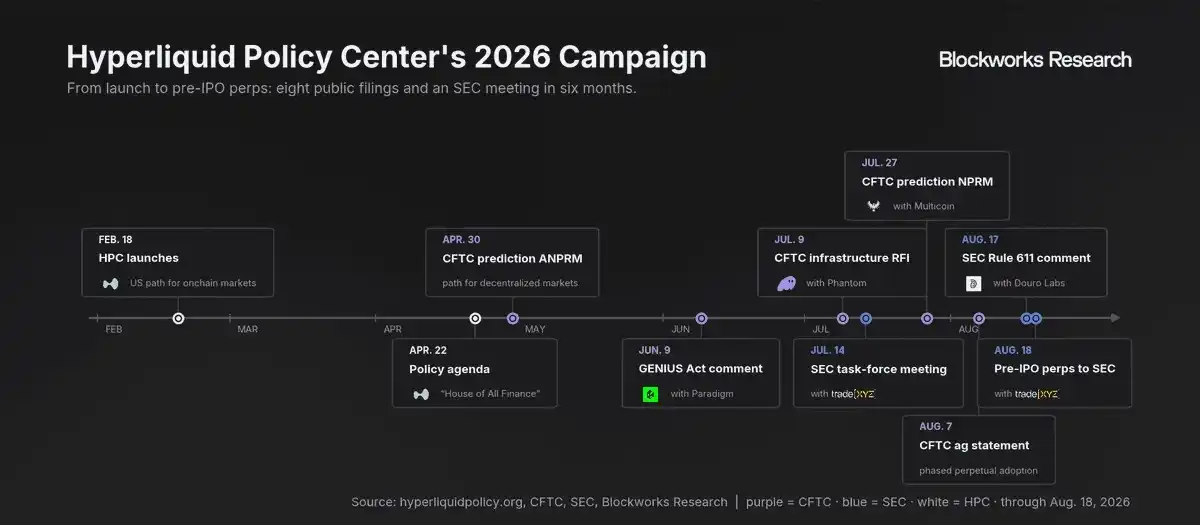
HPC's strategy is not to request opening Hyperliquid directly to U.S. investors without KYC, but to advocate for it as neutral infrastructure: if U.S. companies can use it while fulfilling their regulatory duties under current law, then it should be an option alongside traditional DCMs. For instance, brokers could route client trading flow to HyperCore as long as they fulfill KYC obligations; or deployers could take on the role of registered trading platforms, retaining listing discretion, market surveillance, and emergency intervention powers.
III. Hyperliquid's Compliance Examples
As policy advocacy progresses in Washington, Hyperliquid Labs has already rolled out updates on testnet, theoretically enabling such compliant access. The most typical example is the permissioned HIP-3 deployer: unlike Hyperliquid's native markets and existing HIP-3 deployments which are completely open, these new deployments are only accessible to whitelisted users. Such deployments provide a clear path for regulated entities to list markets, enforce KYC, and whitelist compliant users for trading.
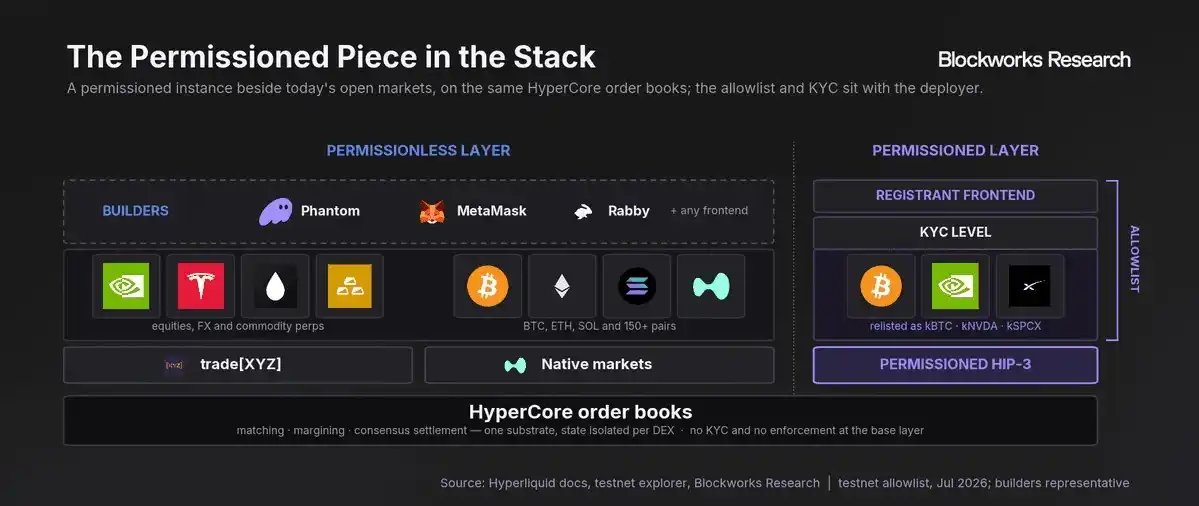
These compliance instances will manifest as fragmented order books, as all markets (e.g., BTC and RWA markets) need to be re-listed. However, whitelisted market makers will bridge liquidity between the two order books, thereby eliminating liquidity fragmentation, allowing the new deployments to inherit Hyperliquid's deep liquidity while maintaining independent order books. This independent order book model has precedents (e.g., early Binance US and Lighter's deployment on Robinhood Chain today), but the difference is that because both markets on Hyperliquid run on the same L1, sharing collateral and margin without the need for cross-chain or cross-exchange transfers, liquidity can flow seamlessly between order books rather than being isolated.
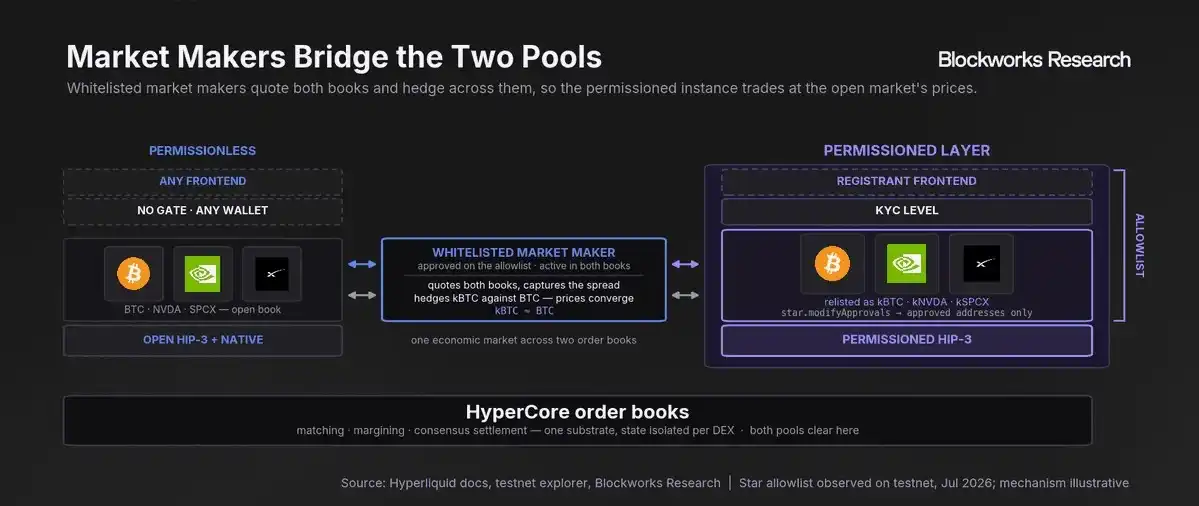
These trading platforms also include other parameters, such as the "PA" account operation permission in the payload, which allows the DEX to directly execute operations on user accounts: submitting reduce-only orders, canceling orders, and transferring USDC internally within the DEX, similar to the close-out authority an FCM has over client accounts. These elements collectively outline the future evolutionary path: U.S. brokers and institutions now have the tools to build compliant Hyperliquid products on HyperCore. This choice is additive—Hyperliquid's native markets remain permissionless, and its position as neutral infrastructure remains unchanged.
IV. Research View
Hyperliquid's recent moves in Washington indicate that gaining compliant entry into the U.S. domestic market is a current core priority; yet it is equally clear that operating directly through its native, KYC-free frontend is not compliant under current U.S. law. We believe HPC's efforts point to a path for achieving KYC-compliant access: allowing the use of Hyperliquid's underlying infrastructure, provided the enterprises offering access fully adhere to regulations. With enabling tools now live on testnet (permissioned HIP-3 deployers, PA account control), we expect this implementation method will provide a compliant channel for U.S. investors to participate in Hyperliquid's markets, while preserving the protocol's nature as neutral infrastructure.