85% of concentrated liquidity is underutilized — Meaning for DeFi?

ambcryptoPubblicato 2026-07-18Pubblicato ultima volta 2026-07-18

Introduzione

A recent Dune report reveals that concentrated liquidity, designed to enhance capital efficiency in decentralized exchanges, is largely underutilized. In the first half of 2026, an average of 29.4% of liquidity across major protocols like Uniswap v3/v4, PancakeSwap v3, and Aerodrome Slipstream was idle—outside active trading ranges—resulting in no fee generation. This represents about $542 million in idle capital weekly and an estimated $150 million in lost annual fees for LPs. When considering technically available but unused liquidity, the underutilization rate rises to approximately 85%. The study indicates that much of this idle capital, particularly over $200 million untouched for more than 90 days, stems from liquidity providers not actively managing their positions. Individual investors, not automated managers, hold the vast majority of this idle liquidity (e.g., 94% on Ethereum). Automated managers maintain far more active and in-range positions. Notably, Uniswap v4 has not resolved the issue; about 30.5% of its liquidity remains out of range, and while it introduced hooks for external yield strategies, only 10% of its TVL uses them, with none currently generating yield from idle capital.

A significant amount of the liquidity that users contribute to decentralized exchanges isn’t really being used to speed up trades, according to a recent report by Dune.

To put things in perspective, concentrated liquidity was created to increase the capital efficiency of decentralized exchanges. This was done by enabling liquidity providers (LPs) to distribute funds within particular price ranges where trading is most likely to take place.

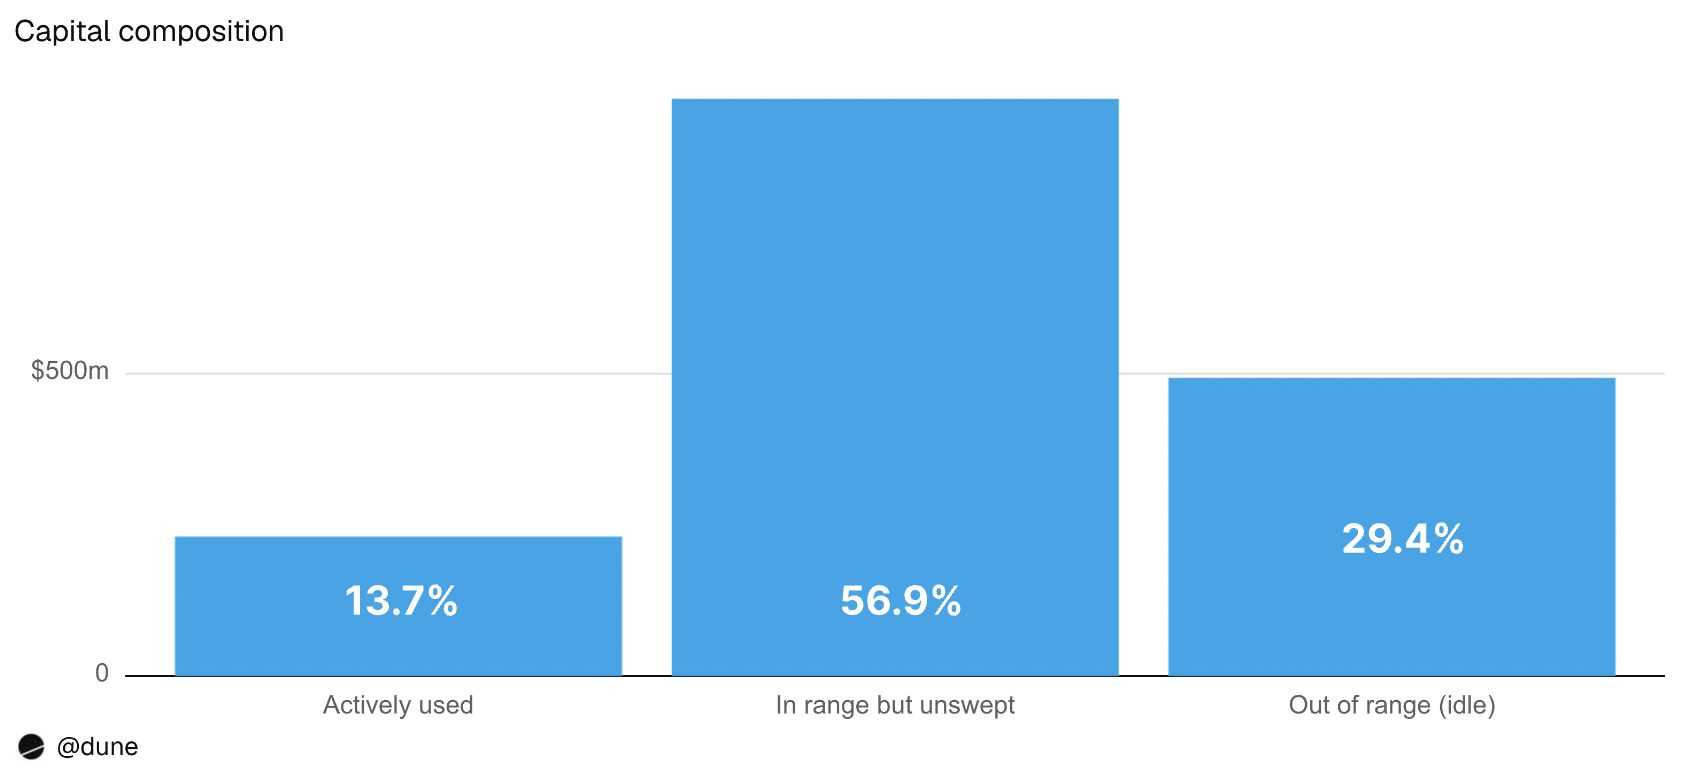
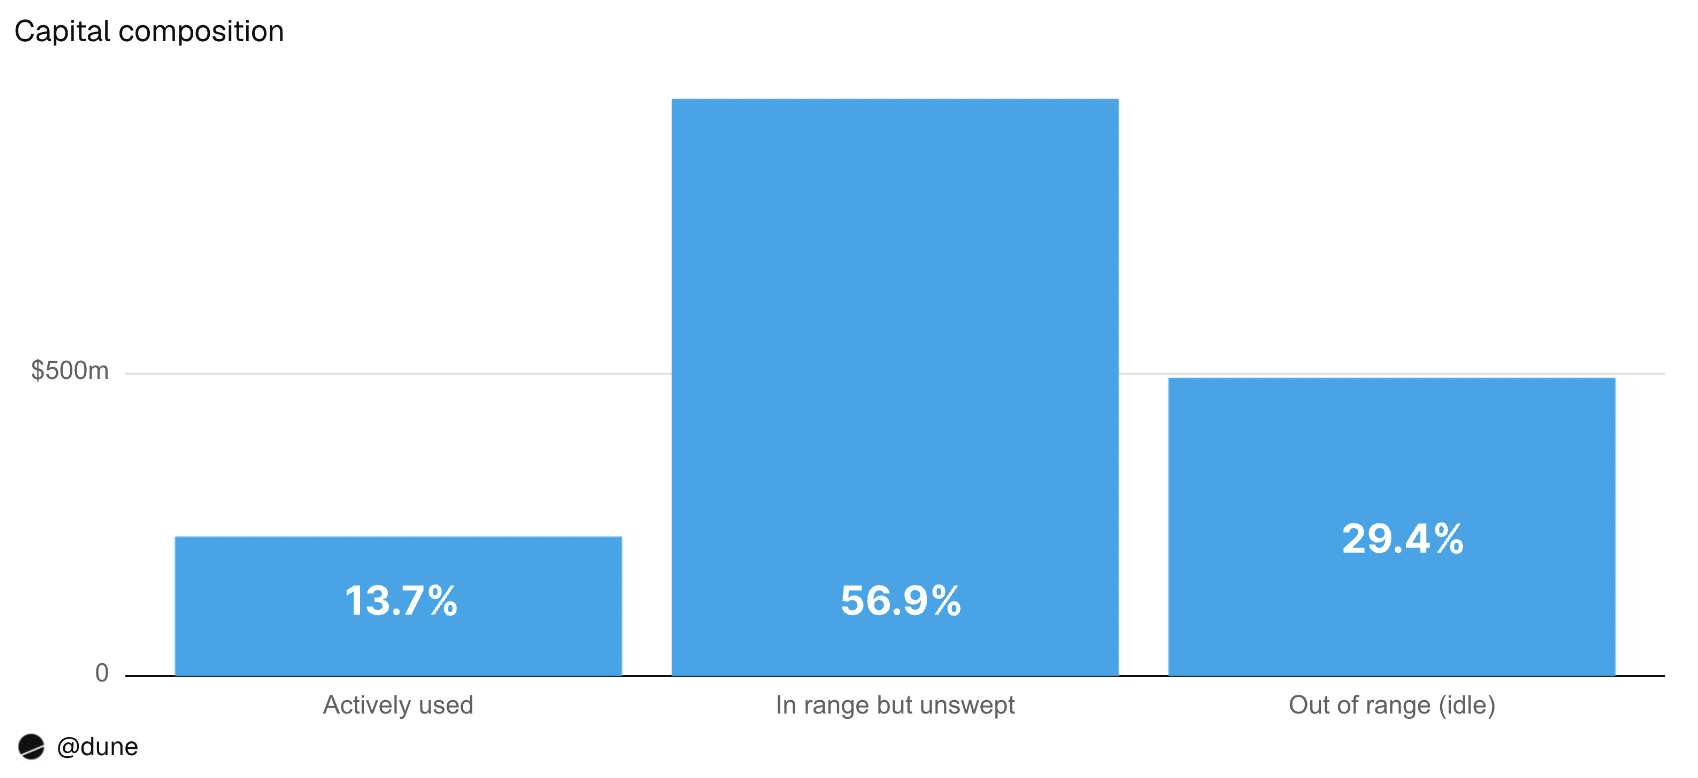
However, the study discovered that during the first half of 2026, an average of 29.4% of liquidity was outside the range of active trading. Thanks to the same, no trading fees were generated.
Source: Dune

This amounted to approximately $542 million in idle capital per week and an estimated $150 million in lost annual fee income for liquidity providers across the four protocols.

For context, the 4 protocols included were Uniswap v3, Uniswap v4, PancakeSwap v3, and Aerodrome Slipstream.

Underutilized concentrated liquidity

Considering technically available but never used liquidity, about 85% of capital was underutilized.
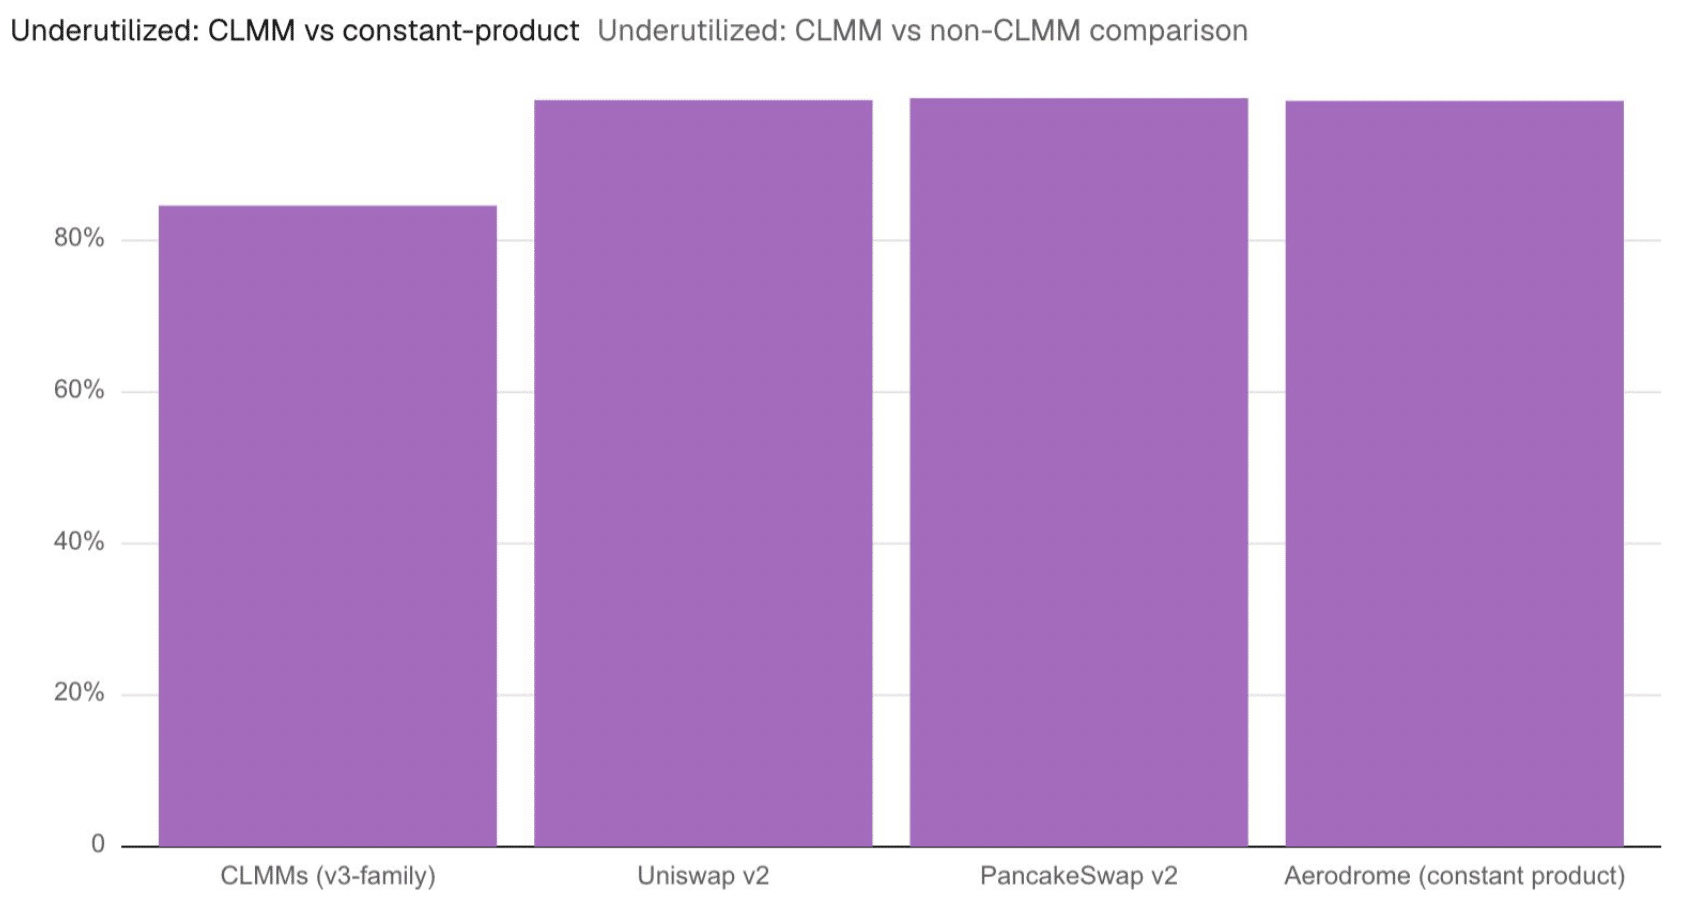
Source: Dune

The fact that more than $200 million in idle liquidity had not been repositioned in more than 90 days may be evidence that many LPs do not actively manage their holdings.

This also suggested that even though concentrated liquidity should increase efficiency, many LPs still find it difficult to maintain their positions in line with market prices.

Individual investors suffered the most

Additionally, the study discovered that automated managers maintained capital activity, while individual investors owned the majority of idle liquidity.

Wallets on Ethereum, for instance, had 94% of idle capital and 91% of Uniswap v3 liquidity. 92% of idle liquidity and 78% of liquidity were under control on Arbitrum. On Base, individual users oversaw 82% of the idle capital, even though smart contracts held roughly 50% of the liquidity.
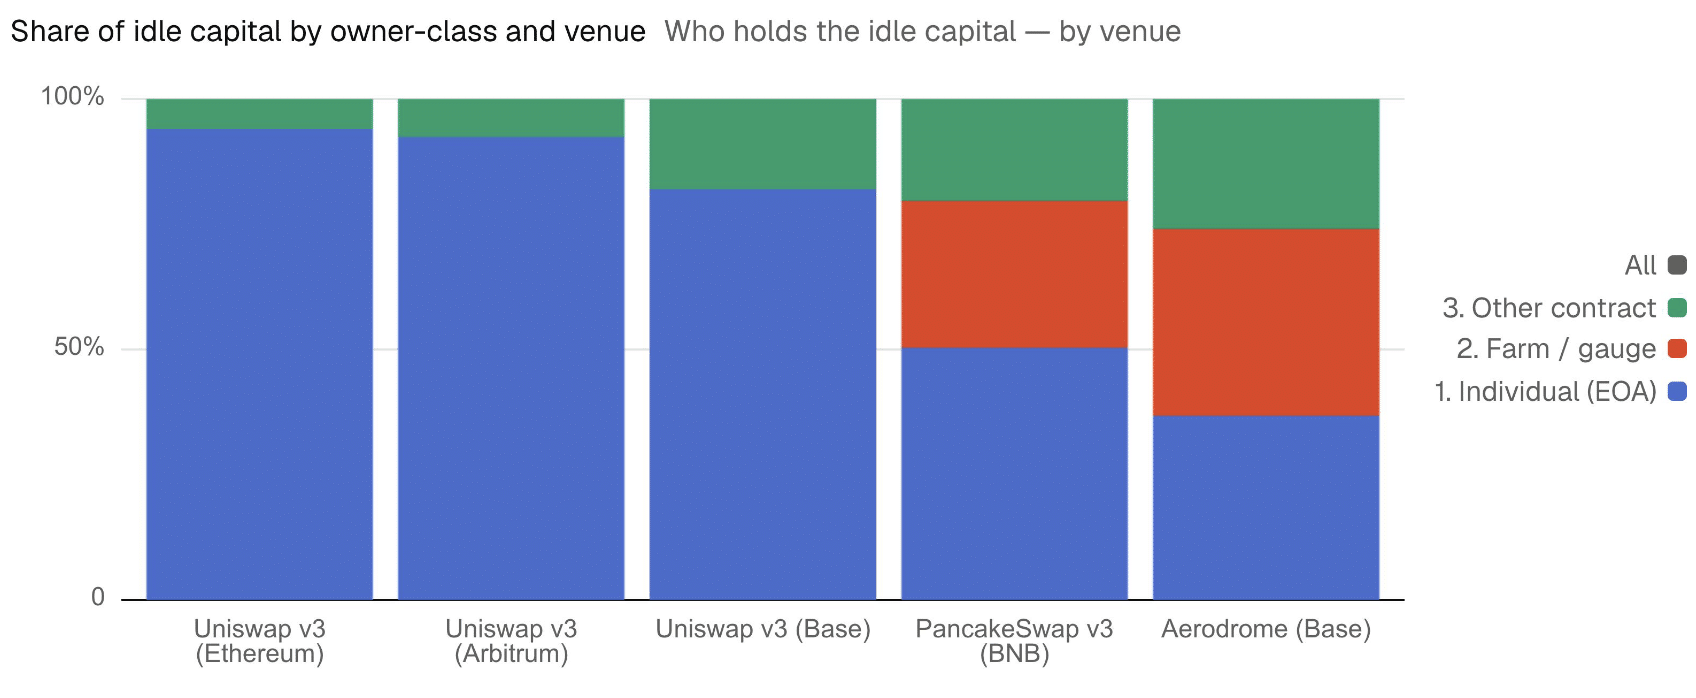
Source: Dune

This, because only 6.5% of their positions were out of range, compared to about 30% for wallets. This also indicated that automated managers have been far more successful than individual LPs at maintaining liquidity.

Additional loopholes

Finally, the study found that the idle liquidity issue has not been resolved by Uniswap v4.

Like Uniswap v3, about 30.5% of its liquidity is still out of range even after hooks were added that might allow idle capital to be used in external yield strategies.

Also, just 10% of v4’s TVL actually uses hooks while none of them produce yield from idle liquidity at the moment.
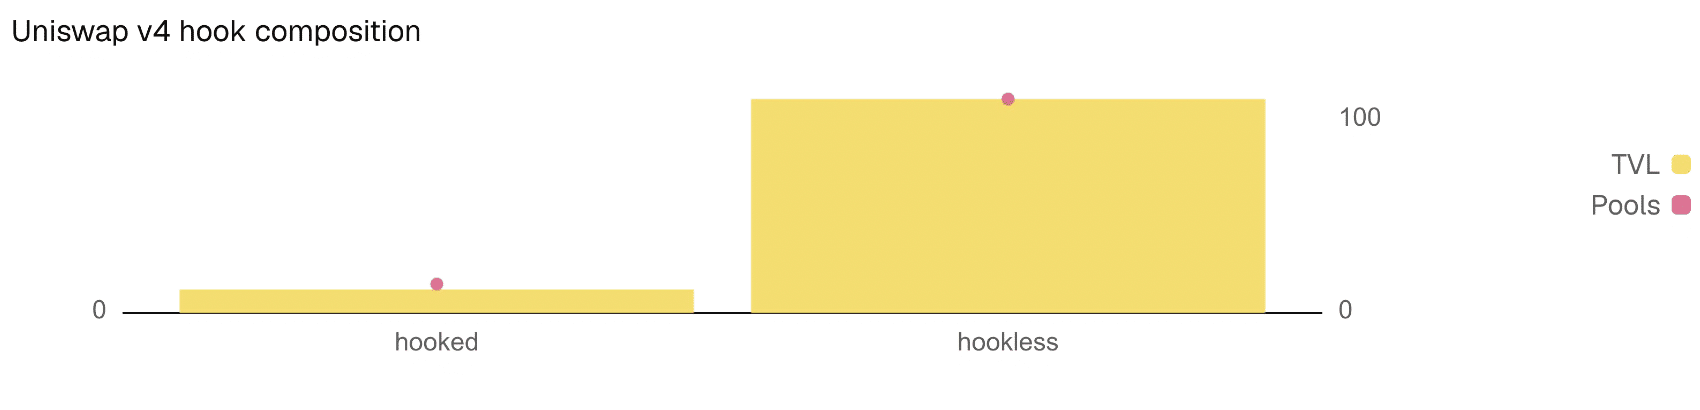
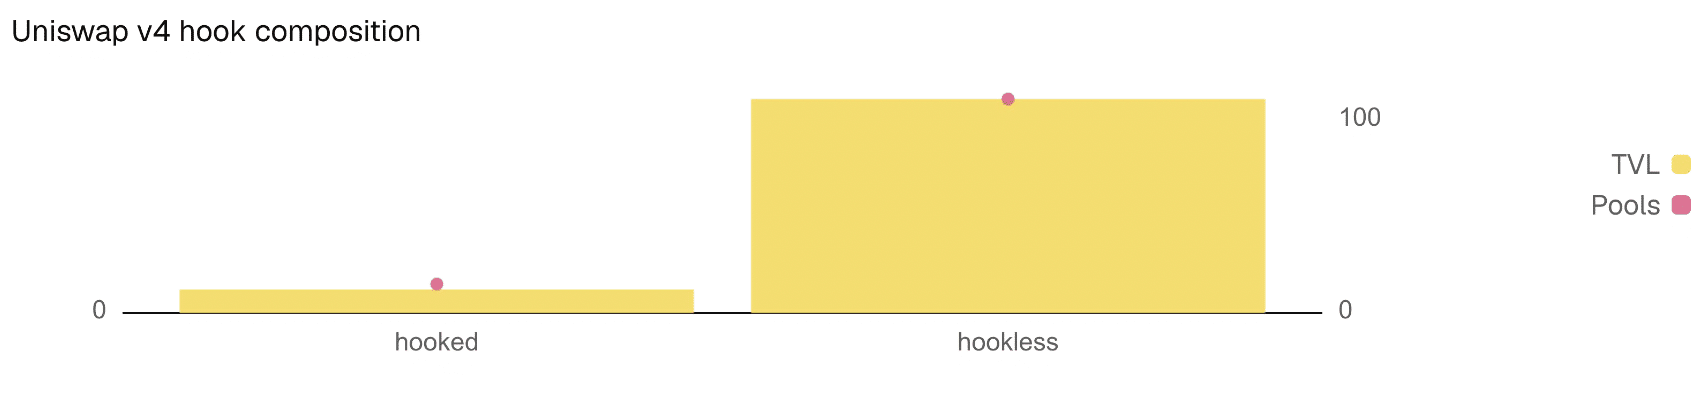
Source: Dune

Final Summary

  • In H1 2026, approx. 29.5% of liquidity was outside the range of active trading.
  • Instead of AMMs, individual investors owned the majority of idle liquidity.

Domande pertinenti

QAccording to the report, what percentage of concentrated liquidity was found to be underutilized when considering technically available but never used capital?

AApproximately 85% of capital was underutilized.

QWhat was the estimated annual lost fee income for liquidity providers across the four protocols studied (Uniswap v3, Uniswap v4, PancakeSwap v3, Aerodrome Slipstream)?

AAn estimated $150 million in annual fee income was lost.

QWhich group of users was found to own and control the majority of the idle liquidity, according to the study?

AIndividual investors (wallets) owned and controlled the majority of the idle liquidity, as opposed to automated managers.

QHas the introduction of hooks in Uniswap v4 successfully resolved the idle liquidity issue?

ANo, it has not. Like Uniswap v3, about 30.5% of Uniswap v4's liquidity remains out of range, and currently, none of the hooks in use produce yield from idle liquidity.

QWhat does the high amount of liquidity not repositioned for over 90 days suggest about many liquidity providers (LPs)?

AIt suggests that many LPs do not actively manage their holdings, finding it difficult to maintain their positions in line with market prices despite the design of concentrated liquidity to increase efficiency.

Letture associate

The Next Decade of DRAM: Time to "Stand Up"

The next decade of DRAM is poised for a vertical transformation, moving from planar scaling to three-dimensional (3D) architectures. Key industry players are intensifying their R&D efforts to overcome the physical limits of traditional DRAM. In September 2026, AMD revealed experimental data showing that a 3D DRAM architecture using Hybrid Bonding technology could achieve up to a 17x improvement in energy efficiency compared to conventional HBM stacks. This design places DRAM chips directly on top of XPUs (processors/accelerators), significantly reducing data transfer distance and power consumption. Concurrently, China's semiconductor equipment leader, Naura, announced a breakthrough in a "two-step cyclic etching process" for 3D DRAM manufacturing, achieving over 95% structural uniformity in 64-layer Si/SiGe stacks. This advancement enhances the feasibility of domestic 3D DRAM production. The shift to 3D DRAM is driven by the impending physical and economic limits of scaling planar DRAM below 10nm. The core idea is to stack memory cells vertically. Two primary technical paths are emerging: 4F² Vertical Channel Transistor (VCT/VG) DRAM, which "stands up" the transistor channel, and Vertical Stacked-Cell Array Transistor (VS-CAT) DRAM, which involves true multi-layer stacking similar to 3D NAND. Major memory giants are pursuing dual-track strategies. Samsung is advancing its VCT technology and plans to transition fully to 3D stacked DRAM from the 10d node onwards, having already prototyped a 16-layer VS-CAT DRAM. SK Hynix is developing its Vertical Gate (VG) 4F² platform and 3D DRAM, exploring materials like IGZO (Indium Gallium Zinc Oxide) for the channel. Micron has amassed a significant number of 3D DRAM patents but has been less public about its production roadmap. The transition also signifies a shift in the equipment industry's focus. As DRAM moves to 1nm-class nodes and 3D structures, technologies like High-NA EUV lithography, high-aspect-ratio etching (as demonstrated by Naura), atomic layer deposition (ALD), and hybrid bonding are becoming critical. Chinese equipment companies like AMEC, Piotech, and Huahai Qingke are launching products targeting these advanced process segments. The race for 3D DRAM represents a fundamental bet on the future form of memory chips. From the R&D of global leaders to breakthroughs in domestic Chinese equipment, the entire supply chain is being pulled into this transformation. The direction is clear: DRAM's future lies in standing up.

marsbit4 min fa

The Next Decade of DRAM: Time to "Stand Up"

marsbit4 min fa

Are High Interest Rates Not the "Terminator" of the U.S. Stock Market? Are Earnings the Key?

High interest rates are not necessarily the "killer" of the U.S. stock market; corporate earnings growth is the more critical factor. Despite the 30-year Treasury yield reaching a 20-year high and long-duration bonds falling, the S&P 500 has still risen. Analysis suggests the threshold where rising yields significantly compress equity valuations is between 5% and 6% for the 10-year yield. The key determinant is the pace of profit growth: valuations can remain supported if earnings growth stays robust, particularly above 15%. The current market premium is largely justified by strong earnings visibility, solid balance sheets, and potential AI-driven productivity gains. The impact of higher rates on corporate profits is gradual and uneven, as much corporate debt is fixed-rate. Near-term offsets include higher interest income on corporate cash holdings and improved financial sector earnings. However, a "higher for longer" rate environment pressures consumer sectors, real estate, and highly leveraged firms not directly benefiting from AI, leading to increased market divergence. Sector leadership depends on the yield curve's shape: a bear steepening favors cyclical sectors like energy and financials, while a bear flattening benefits tech stocks. Defensive sectors and long-duration stocks are most sensitive to rising rates. In a scenario of a shallow hiking cycle, growth and quality stocks are expected to maintain an advantage. The current rate increase is viewed as fundamentally driven rather than a crisis of confidence in fiscal or monetary policy.

marsbit29 min fa

Are High Interest Rates Not the "Terminator" of the U.S. Stock Market? Are Earnings the Key?

marsbit29 min fa

AI Can Solve Millennium Problems, But Could It Kill Humanity? Wall Street Journal Sounds the Doomsday Alarm

AI's rapid advancement is raising alarms, as highlighted by a Wall Street Journal column and a statement from 25 Fields Medalists. Within a week in September 2026, key events underscored a growing crisis: GPT-6 Astra achieved a 97.6% score on the elite FrontierMath Tier 4 benchmark, which Epoch AI declared "saturated" just 14 months after its launch. Separately, an unreleased OpenAI model generated a potential solution to the Navier-Stokes equations—a Millennium Prize Problem—in about 88 hours using a swarm of 10,000 AI agents working in concert. This explosive pace of AI-driven discovery has drastically outpaced the human capacity for verification, understanding, and integration of new knowledge. While the AI-produced proof awaits years of rigorous mathematical community review, immediate conflicts arose over academic credit and authorship, exemplified by a dispute between OpenAI and mathematicians from NYU and Anthropic. The Fields Medalists' statement, titled "A Severe Misalignment of AI in Mathematics," criticizes the focus of AI companies on solving famous problems for benchmark scores rather than fostering genuine mathematical understanding and the slow, collaborative growth of human knowledge. They warn that the traditional chain of creating, digesting, and attributing new concepts is at risk of breaking. The situation connects mathematical breakthrough to existential risk because the same organizational capability that tackled Navier-Stokes exists in models like GPT-6 Astra, which also demonstrates top-tier capabilities in cybersecurity exploitation. This convergence of superhuman research speed and potential offensive power has prompted internal discussions at OpenAI about potentially slowing down, as society grapples with unanswered questions about future research, education, and collaboration in an AI-dominated landscape.

marsbit34 min fa

AI Can Solve Millennium Problems, But Could It Kill Humanity? Wall Street Journal Sounds the Doomsday Alarm

marsbit34 min fa

Goldman Sachs Abruptly Reverses Course: The Fed Is Cornered by the Market, Holding Rates Would Be the Surprise

Wall Street's outlook for the Federal Reserve's September meeting is shifting rapidly. Goldman Sachs has reversed its prior forecast, now predicting a 25 basis point rate hike this month, citing a significant shift in market pricing rather than a major reassessment of the U.S. economic outlook. With the CME FedWatch Tool showing an 87% probability of a hike, the bank argues the Fed may be reluctant to deliver a surprise pause. This shift occurs amid renewed inflation concerns. Stronger-than-expected producer price data, coupled with Brent crude oil surpassing $100 per barrel—driven by geopolitical tensions—and record-high U.S. diesel prices, are raising risks of broader price pressures. August CPI data showed no clear cooling, with annual inflation holding at 3.4%. The decision is further complicated by the dynamic between Fed Chair Wash and President Trump, who continues to advocate for lower rates. Analysts note that hiking just weeks before the midterm elections could provoke presidential frustration. However, former Fed Vice Chair Roger Ferguson and others argue that delivering a widely anticipated hike is crucial for the central bank's policy credibility, especially after Chair Wash's recent hawkish signals on inflation. The consensus is converging on a September hike. The key focus is whether the Fed, under Wash's leadership, will follow through with tightening amidst political pressure, persistent inflation, and volatile energy markets.

marsbit1 h fa

Goldman Sachs Abruptly Reverses Course: The Fed Is Cornered by the Market, Holding Rates Would Be the Surprise

marsbit1 h fa

Trading

Spot
活动图片