U.S. Treasury Yield at 5% Frightens AI Investors

marsbitPubblicato 2026-08-19Pubblicato ultima volta 2026-08-19

Introduzione

U.S. Treasury Yields Surpass 5%, Spooking AI Investors Recent weeks have seen a sharp rise in long-term U.S. Treasury yields, with the 10-year and 30-year rates climbing 34 and 45 basis points, respectively. The 30-year yield has exceeded 5%, reaching its highest level since 2004. This surge in the global risk-free rate anchor has triggered a broad re-pricing of assets, impacting equities, currencies, and commodities, including the volatile AI sector. The primary driver is a fundamental imbalance in bond market supply and demand. Persistent U.S. fiscal expansion and massive Treasury issuance are the root cause. Concurrently, demand from traditional large buyers—foreign central banks and the Federal Reserve—has waned, shifting the burden to commercial financial institutions whose investment strategies increase market volatility. A significant marginal factor is the AI-driven corporate debt boom. Tech giants like Amazon, Alphabet, and Microsoft have issued over $1200 billion in bonds recently to fund capital expenditures, creating competition for investor capital and putting upward pressure on Treasury yields. Furthermore, resilient inflation data and expectations of a more hawkish Federal Reserve under Chair Wash have pushed up long-term inflation risk premiums. For the AI investment theme, higher yields pose a serious valuation challenge. They systematically raise the discount rate for future earnings, pressuring highly-valued tech stocks. This is a key factor behind the ...

Author | Yida Huang

Editor | Zhang Fan

Recently, the long-term U.S. Treasury yields have risen significantly, driving the yield curve to exhibit a typical steepening characteristic. Reflected in the data, from June 29th to August 17th, the yields on 10-year and 30-year U.S. Treasuries surged by 34 and 45 basis points (bps) respectively, while the 2-year U.S. Treasury yield increased by only 9 bps during the same period, causing the term spread to widen rapidly.

More notably, following this rapid surge, the 30-year U.S. Treasury yield has already risen above 5%, surpassing the peak of the post-pandemic rate hike cycle and reaching its highest level since 2004. The 10-year U.S. Treasury yield is not only approaching its previous high but is also close to the level seen during the 2007 subprime mortgage crisis.

As the anchor for the global risk-free rate, the rapid rise in U.S. Treasury yields has triggered a repricing of major asset classes including equities, foreign exchange, and commodities. The recent sharp fluctuations in the AI industry chain also reflect the influence of this transmission logic. Meanwhile, the pricing of the 10-year U.S. Treasury yield itself mirrors the global macroeconomic situation, and its current level has also reawakened painful memories for investors of the 2007 subprime mortgage crisis.
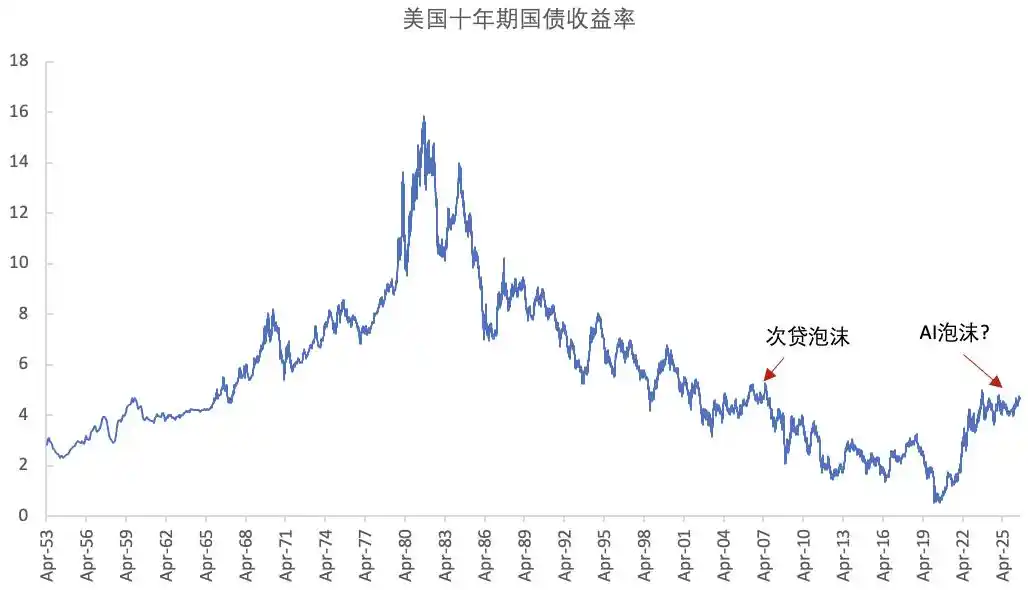
Chart: 10-Year U.S. Treasury Yield Trend; Source: wind, 36Kr

So, what are the core factors driving the rise in U.S. Treasury yields? How does the rising U.S. Treasury yield affect the AI chain market?

01 Multiple Factors Drive the Rise in Long-Term U.S. Treasury Yields

For investors unfamiliar with bonds, it's essential to first understand a basic principle: bond yields have an inverse relationship with asset prices. Therefore, a significant rise in U.S. Treasury yields indicates a substantial decline in U.S. Treasury prices. From a fundamental perspective, this round of rising U.S. Treasury yields is primarily driven by supply-demand dynamics in the capital markets. Simultaneously, factors such as resurgent inflation and expectations of tighter monetary policy have also played significant roles.

Firstly, the U.S. government's fiscal expansion and the resulting surge in Treasury issuance are the fundamental reasons for the rise in long-term U.S. Treasury yields. Over the past 20 years, the total U.S. debt has continued to swell, reaching $37.6 trillion by the end of 2025, 6.6 times the $5.7 trillion in 2000. Although the annual increase in U.S. debt supply retreated to around the median level of the past two decades after the 2020 pandemic issuance peak, the actual scale expansion remains very rapid due to the high base.
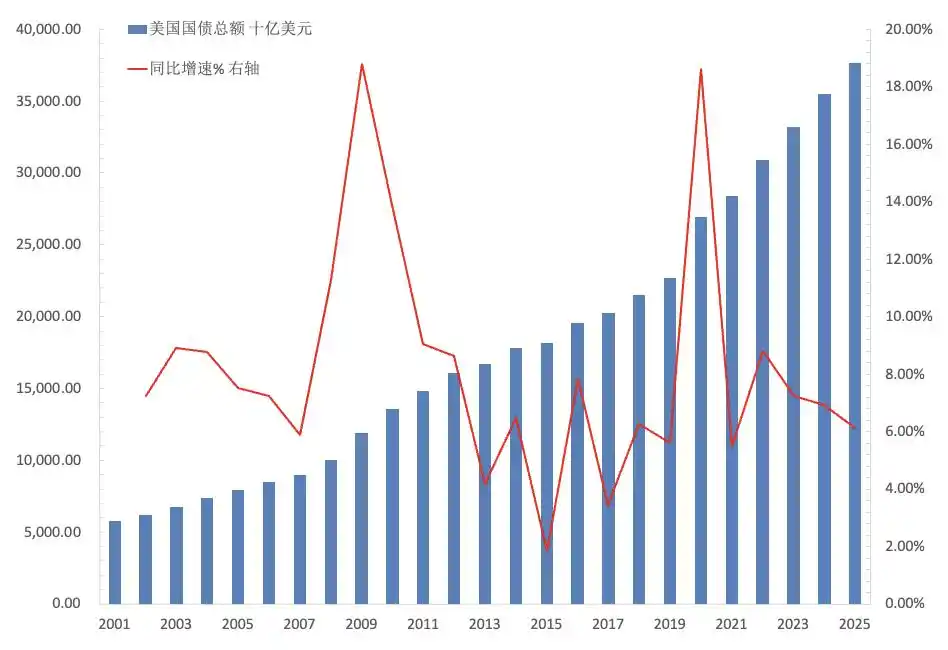
Chart: Total U.S. Debt Scale and Year-over-Year Growth Rate; Source: wind, 36Kr

At the same time, factors such as tax cuts and a high proportion of rigid expenditures in the U.S. fiscal budget have led to persistent expectations of robust Treasury supply, which to some extent has also pushed up U.S. Treasury yields. From an asset pricing logic perspective, the continuous growth in U.S. Treasury supply has a significant dilutive effect on market liquidity. Rising expectations for future supply further exacerbate pressure from supply-demand imbalances in the Treasury market.

Looking at the demand side, the main buyers of U.S. Treasuries have traditionally been foreign official institutions and the Federal Reserve. However, significant changes in the buyer structure in recent years have amplified U.S. Treasury price volatility. For foreign official institutions, against the backdrop of weakening U.S. sovereign credit, part of the asset allocation demand has shifted from U.S. Treasuries to assets like gold and non-U.S. sovereign bonds. Meanwhile, the Federal Reserve significantly reduced its holdings of U.S. Treasuries after continuous balance sheet reduction (quantitative tightening) during the previous rate hike cycle. If the Fed under Chair Wash continues to reduce its balance sheet, further selling of Treasuries is expected.

As the holdings of these two traditional major buyers have declined significantly, the demand to absorb new U.S. debt has had to shift substantially towards financial institutions in the capital market, such as banks, pension funds, hedge funds, and insurance companies. Given that different types of institutions have varying preferences and tolerances for factors like investment returns, risk control metrics, exchange costs, and speculative opportunities, the trend towards diversified investment strategies as commercial entities become key buyers of U.S. debt has predictably led to increased volatility in U.S. Treasury yields.

Notably, the bond issuance wave triggered by the expansion of capital expenditures in the AI chain constitutes a significant marginal force driving up U.S. Treasury yields. Public data shows that five tech giants—Amazon, Alphabet, Meta, Microsoft, and Oracle—issued over $120 billion in credit bonds in 2025. By October 2025, the scale of AI-related bonds had reached as high as $1.2 trillion.
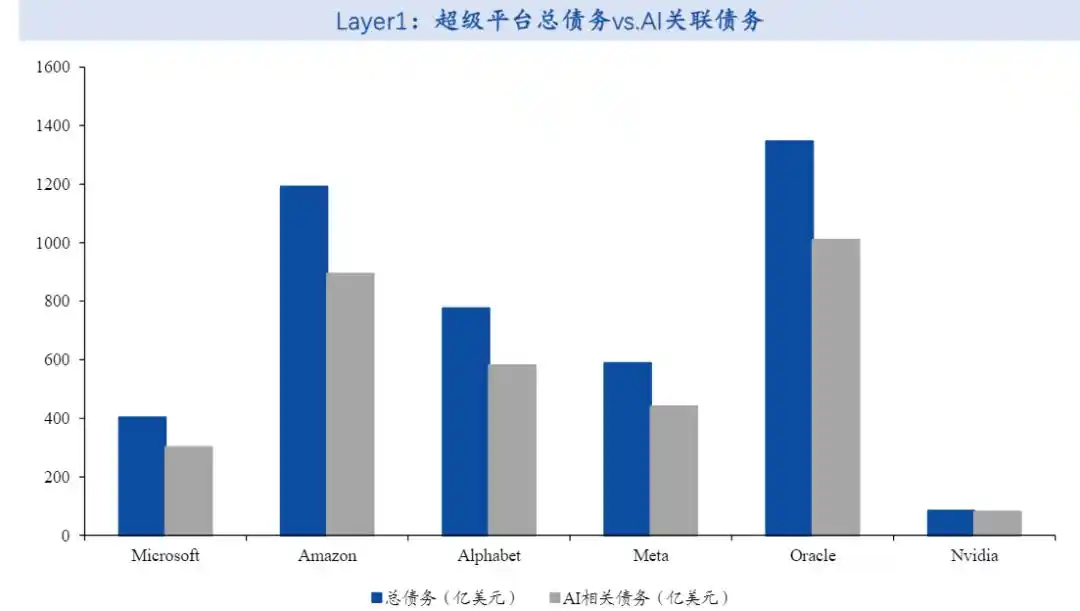
Chart: AI-Related Debt Scale of Major Companies; Source: Huafu Securities, 36Kr

In the current U.S. Treasury holder structure, financial institutions occupy an important position. Compared to traditional buyers like foreign official institutions and the Fed, institutional investors have a greater preference for investment returns and speculation in their allocation demands. Therefore, influenced by the AI bond issuance wave, a large influx of high-quality, high-yield credit bonds into the bond market has created a certain degree of competition with U.S. Treasuries. This has resulted in a crowding-out effect on Treasuries within a limited scope, marginally pushing U.S. Treasury yields higher.

At the macro and policy levels, the elevated long-term U.S. Treasury yields essentially reflect resurgent inflation and expectations of monetary policy tightening. Current U.S. inflation remains some distance from the policy target. Moreover, the resilience shown by repeated inflation flare-ups this year has increased the inflation risk premium embedded in long-term yields. The Federal Reserve's dual mandate focusing on inflation and employment, coupled with Chair Wash's relatively hawkish policy inclination, suggests the market is re-pricing the future inflation path and monetary tightening risks.

02 What Impacts Will Rising U.S. Treasury Yields Have on the AI Chain?

Regarding the shape of the yield curve, the recent surge in long-term U.S. Treasury yields has pushed the curve towards steepening. For short-term rates, based on Chair Wash's current hawkish policy orientation, short-term rates still face considerable upward pressure in the future. Once rate hike expectations materialize, short-term rates will rise rapidly, driving the yield curve towards flattening—shifting from a so-called "bear steepening" to "bear flattening."

During a rate hike cycle, when both long and short-term U.S. Treasury yields are high and the yield curve flattens, it leads to a systematic rise in the anchor for the global risk-free rate. The resulting high-interest-rate environment and relatively tight monetary policy will put pressure on global stock markets collectively. Tech stocks, represented by the AI chain, are particularly sensitive to changes in the financing environment due to their continuous R&D investments and capital expenditures, and thus will be more significantly affected.

Looking back at history, in the period leading up to the 2006–2007 subprime mortgage crisis, the U.S. Treasury yield curve was very flat for a considerable time. Although high interest rates and a flat yield curve exerted some valuation pressure on the stock market, the real market adjustment occurred after the crisis erupted. This shows that high interest rates are not the trigger for a bear market in stocks; their core impact lies in continuously applying valuation pressure: not only weakening the appeal of high-valuation assets but also more easily pricking crowded trades and exacerbating asset price volatility.

Examining the current AI chain bull market, the hotspots are mainly concentrated in the hardware sector. The strong performance of related companies and the overall positive expectations form the fundamental basis for this structural bull market. However, based on the above discussion, the valuation pressure on related targets caused by rising U.S. Treasury yields is unavoidable. Particularly for the memory sector, after accumulating considerable gains earlier and experiencing extreme trading crowding at one point, rising valuation pressure due to interest rate factors is one of the important triggers for the recent phase of market adjustment and profit-taking.

From the underlying logic of asset pricing, the challenges currently facing the AI chain bear a striking resemblance to the situation on the eve of the 2007 subprime mortgage crisis: the subprime crisis began when rental yields could no longer support the U.S. housing price bubble (carrying cost). Today, AI giants are investing massive capital expenditures, similarly relying on downstream commercial realization to close the loop on investment returns.

Currently, Anthropic's ARR (Annual Recurring Revenue) growth trajectory has noticeably slowed, meaning the contradiction between cash flow failing to cover high-leverage debt and high valuations has begun to surface. High interest rates will further exacerbate these two contradictions. In the future, the market may reassess the intensity of capital expenditures based on the ARR slowdown; meanwhile, stock investors, haunted by the psychological shadow of the subprime crisis, have already reflected their revaluation of AI chain-related companies in current asset pricing.
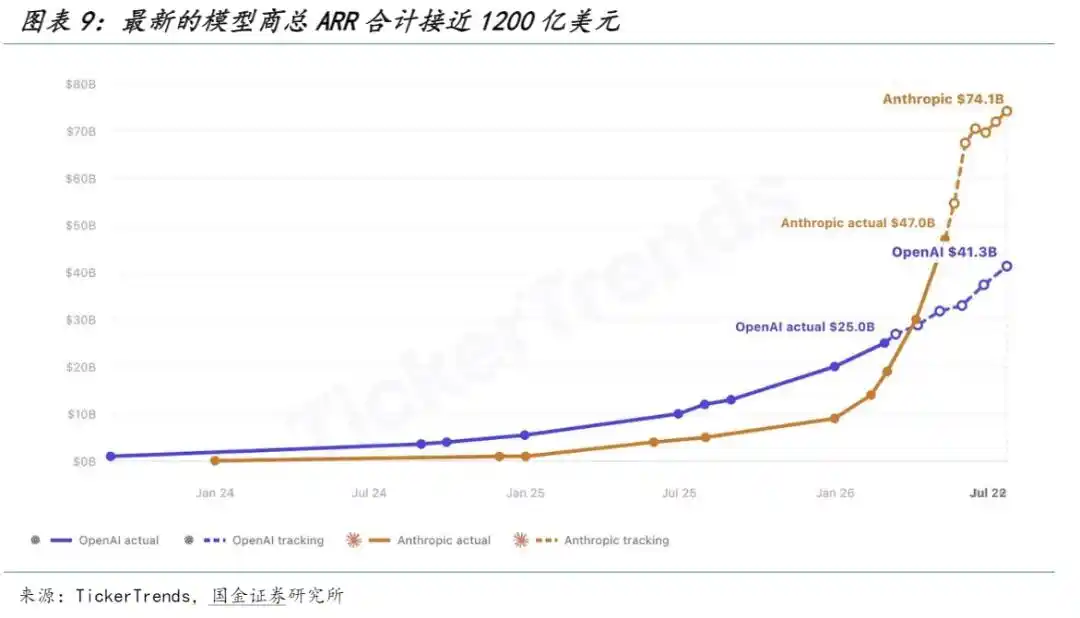
Chart: ARR of OpenAI and Anthropic; Source: Guojin Securities, 36Kr

Furthermore, rising U.S. Treasury yields will also further alter the financial behavior of major AI companies. To support massive capital expenditures, it is a prudent move for these giants to concentrate bond issuance and lock in interest rates before yields climb further. As a result, a massive volume of credit bonds flooding the bond market in a short period crowds out existing market liquidity, exacerbating the persistently high long-term yields. The consequence is ultimately an increase in the long-term financing threshold at the macro level, from which the AI chain will also struggle to escape.

*Disclaimer:

The content of this article represents only the author's views.

The market carries risks; investment requires caution. Under no circumstances shall the information or opinions expressed herein constitute investment advice to anyone. Before making investment decisions, investors should consult with professionals and make prudent decisions if necessary. We do not intend to provide underwriting services or any services requiring specific qualifications or licenses to any parties involved in transactions.


Domande pertinenti

QWhat are the core drivers behind the recent surge in U.S. long-term Treasury bond yields?

AThe core drivers are: 1) Fundamental supply-demand dynamics, primarily the U.S. government's fiscal expansion and massive bond issuance. 2) A shift in the buyer structure where commercial institutions have become major buyers, increasing market volatility. 3) The marginal impact of a bond issuance surge from tech giants funding AI capital expenditures, creating competition for funds. 4) Macro and policy factors, specifically persistent inflation and expectations for tighter monetary policy, which raise inflation risk premiums and long-term interest rate expectations.

QHow does a significant rise in U.S. Treasury yields impact AI-related stocks?

AA significant rise in U.S. Treasury yields impacts AI-related stocks primarily by increasing valuation pressure. As the global risk-free rate anchor rises, the high valuations of growth stocks like those in the AI sector become less attractive. This pressure can trigger profit-taking and exacerbate price volatility, especially in crowded trades. Furthermore, high rates increase the cost of financing for the capital-intensive AI industry, potentially forcing a reassessment of capital expenditure plans and affecting future growth expectations.

QWhy does the article draw a parallel between the current AI investment environment and the pre-2008 financial crisis period?

AThe article draws a parallel because both situations involve high leverage and valuations dependent on future cash flows that may not materialize as expected. Before the 2008 crisis, high housing prices relied on rental income that couldn't cover costs. Now, massive AI capital expenditures rely on future commercialization and revenue (like ARR) to justify the investment and debt. High interest rates expose this vulnerability by increasing financing costs, just as high rates contributed to the subprime mortgage crisis by increasing homeowners' costs. The psychological impact of the 2008 crisis also makes investors sensitive to similar leverage/valuation mismatches.

QWhat is the significance of the shift in the U.S. Treasury buyer structure mentioned in the article?

AThe shift is significant because traditional major buyers like foreign official institutions and the Federal Reserve have reduced their holdings. Their place has been taken by commercial financial institutions (banks, pensions, hedge funds, insurers). Unlike traditional buyers focused on stability and reserve management, these commercial entities have diverse investment strategies focused on returns, speculation, and specific risk metrics. This change makes the Treasury market more sensitive to changes in risk appetite and liquidity, leading to increased interest rate volatility.

QAccording to the article, what is the relationship between AI companies' bond issuance and long-term Treasury yields?

AThe relationship is one of marginal competition and mutual reinforcement. AI giants have issued massive amounts of high-quality, high-yield corporate bonds to fund capital expenditures. This large supply of attractive bonds competes for the same pool of investor capital as U.S. Treasuries, creating a marginal 'crowding out' effect that puts upward pressure on Treasury yields. Conversely, the expectation of rising yields prompts these companies to issue debt quickly to lock in lower rates, further increasing bond supply. This cycle can contribute to a self-reinforcing trend of higher long-term financing costs across the economy.

Letture associate

Founders Fund Leads $5 Million Token Purchase of ANVL: What Exactly is This "Non-Lending" DeFi Protocol Doing?

On October 6th, Founders Fund, led by Peter Thiel, invested $5 million to purchase ANVL tokens from the DeFi protocol Anvil's treasury. The round included participation from Pantera Capital and others, alongside angel investors like Compound founder Robert Leshner. Anvil is not a lending protocol. Instead, users lock assets like ETH or USDC into its vault to generate a verifiable on-chain "Letter of Credit" (LOC). This LOC acts as an economic guarantee, proving the user has sufficient locked collateral to back financial commitments, without borrowing funds. The protocol applies this mechanism to use cases like payment guarantees for merchants (via integration with Flexa) and enabling instant deposits for traders on exchanges like Bullish. Anvil's economic model is unique: it charges zero protocol fees. Its native token, ANVL, derives value solely from governance rights over parameters like supported collateral types. The total supply is 100 billion tokens. Despite an 83% price surge on the investment news, ANVL remains down approximately 89% from its all-time high. The protocol's Total Value Locked (TVL) has also fallen about 87% from its peak of ~$109 million in July 2025 to around $14 million currently. The investment represents a strategic bet that on-chain credit guarantees could become a significant category. Key factors to watch include the rate of real enterprise adoption through Anvil's SDK, the long-term sustainability of its zero-fee model, and the broader migration of traditional trade finance needs to blockchain infrastructure.

marsbit27 min fa

Founders Fund Leads $5 Million Token Purchase of ANVL: What Exactly is This "Non-Lending" DeFi Protocol Doing?

marsbit27 min fa

Mathematical Explosion: OpenAI Overnight Solves 722 Math Problems, Quasi-Riemann Hypothesis Proven

OpenAI has stunned the global mathematics and AI communities by releasing a GitHub repository containing 722 manuscripts addressing 372 previously unresolved major mathematical problem families, all reportedly generated by an unreleased internal AI model. The announcement, made without prior peer review, has provoked both excitement and alarm among mathematicians. The most notable breakthrough claims to be a proof of a "quasi-Riemann Hypothesis," establishing a zero-free region for Dirichlet L-functions with real part greater than 7/8 and eliminating the Landau-Siegel zeros—a significant leap in analytic number theory. The work has reportedly undergone formal verification using Lean. Other highlighted results include: unconditionally proving the NP-hardness of the basic semidefinite programming (SDP) threshold for approximation algorithms, based solely on P ≠ NP and circumventing the Unique Games Conjecture; proving the rational Hodge conjecture for abelian varieties with complex multiplication (CM); and resolving both the symmetric and asymmetric Mahler conjectures in convex geometry. According to OpenAI, most proofs were generated automatically by the model, with an average "thinking" time of just three hours per problem. This unprecedented scale and speed have sparked intense debate about the future of human mathematicians. While some express fear about the concentration of intellectual power, others see it as the dawn of a new era of discovery driven by AI. The mathematical world is now tasked with scrutinizing these claims, which, if verified, would represent historic milestones.

marsbit1 h fa

Mathematical Explosion: OpenAI Overnight Solves 722 Math Problems, Quasi-Riemann Hypothesis Proven

marsbit1 h fa

As Midterm Elections Approach, the Real Trade in U.S. Stocks Isn't About Who Wins

With the US midterm elections approaching in early November, political uncertainty has re-emenrged as a market variable. While market participants are weighing potential shifts in congressional control and policy direction, historical data suggests midterm elections themselves are not a definitive negative catalyst for US equities. Since 1937, the S&P 500 has averaged a positive gain of 9.2% in midterm election years, though this lags behind the 13.3% average for non-election years. A more consistent historical pattern is increased market volatility and a tendency for stronger performance concentrated in the fourth quarter, as political uncertainty is resolved. The article, citing analysis from J.P. Morgan and Capital Group, argues that the market's primary concern is policy path uncertainty rather than which party wins. This uncertainty tends to depress markets in the run-up to the vote, with a potential rebound afterward as the political risk premium dissipates. However, the article cautions against attributing market performance solely to the election. Recent midterm years like 2018 and 2022 saw significant market declines primarily driven by factors like Federal Reserve tightening and inflation, not the election outcome itself. The core argument is that the midterm election's impact on markets is often secondary to more fundamental drivers. Regardless of whether the result is a unified or divided government, the market's longer-term trajectory has historically been determined by underlying economic conditions. For the current environment, the key variables to watch post-election are not political labels but the path of interest rates, corporate earnings trends, and whether any actual policy changes materially alter cash flow expectations for businesses. The election may influence sentiment and policy expectations, but the sustainability of any year-end rally will ultimately depend on these core fundamentals of profitability, rates, and economic data.

marsbit1 h fa

As Midterm Elections Approach, the Real Trade in U.S. Stocks Isn't About Who Wins

marsbit1 h fa

AI Can't Change 'DNA': How Long Can SanDisk Stay Strong?

**AI Cannot Alter the "DNA": How Much Longer Can Western Digital's Run Last?** This analysis examines the sustainability of the current "super cycle" for NAND flash memory, driven by AI, with a focus on Western Digital (WD). The core argument is that while AI demand has fundamentally shifted NAND's role from a data warehouse to an essential component on the compute path, especially for AI inference, this does not eliminate the industry's cyclical nature. The piece first assesses the supply-demand dynamics. On the supply side, major producers are showing capital expenditure restraint for NAND, prioritizing DRAM/HBM. Capacity growth through 2028 relies heavily on technological upgrades (increasing 3D layers to 300+) and expansion primarily from China's YMTC, rather than new fabs. Global new fab capacity from players like Samsung and WD/Kioxia is concentrated post-2029. This results in estimated bit supply growth (CAGR ~24% for 2026-2028) largely driven by higher per-wafer output. Demand is undergoing a structural shift. AI-related NAND demand (for data lakes, KV cache, and staging) is forecast to grow at a 75% CAGR from 2025-2028, becoming the dominant driver. Data center demand will surpass 50% of total NAND demand in 2026. Consumer demand (PC, smartphone) is being squeezed and is expected to decline or stagnate. A key 2027 demand catalyst is NVIDIA's Rubin platform with its dedicated contextual memory storage (ICMS). The analysis concludes that a supply-demand deficit will persist into 2027. However, 2028 is identified as a potential inflection point where supply (led by YMTC's new fab) could outpace demand, ending the price rally. For Western Digital, the analysis models a more conservative path than management's guidance. It forecasts Average Selling Price (ASP) peaking in FY28 (ending June 2028) before declining in FY29-30 as the market loosens, though supported by long-term agreements (LTAs) and a higher mix of data center products. Consequently, margins and profits are expected to peak in FY28 and then contract. The valuation suggests WD's current price largely reflects a neutral scenario, with limited short-term upside unless the market becomes convinced that prices will remain stable post-2028. The fundamental takeaway is that despite AI's transformative impact, NAND's cyclical "DNA" remains intact.

marsbit1 h fa

AI Can't Change 'DNA': How Long Can SanDisk Stay Strong?

marsbit1 h fa

Trading

Spot
活动图片




