Michael Saylor: Four Centuries of Digital Credit Evolution
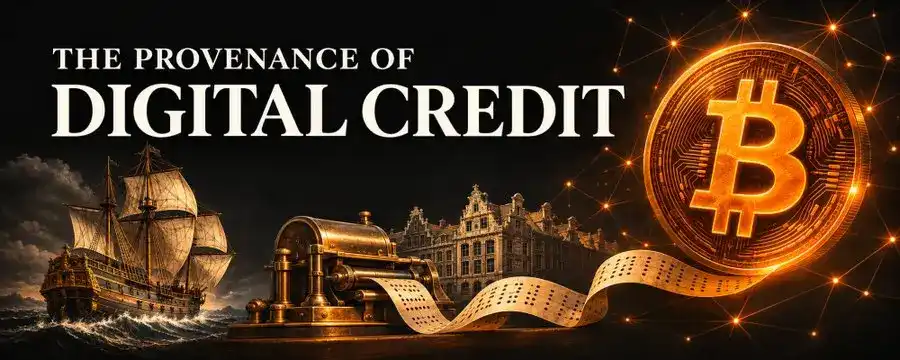
Michael Saylor traces the four-century evolution of digital credit, showing how centuries of financial infrastructure paved the way for Bitcoin-based corporate treasuries. The story begins in 1602 with the Dutch East India Company, which separated a company's capital duration from investors' holding periods through transferable shares. Preferred stock followed, exemplified by the Baltimore and Ohio Railroad's 6% perpetual preferred dividend in 1836 and Delaware's 1899 recognition of distinct share classes. Exchanges and tickers—from the 1792 Buttonwood Agreement to the 1867 stock ticker and 1971 Nasdaq—gave ownership a public market. U.S. securities and commodities law (1922–1974) established the distinction between assets a company holds and securities it issues. The 1940 Investment Company Act's "40% test" still shapes how bitcoin treasury companies use common stock, preferred stock, and debt. Tax law dating to 1921–1954 distinguishes return of capital from income, allowing preferred dividends to reduce cost basis before gains are realized. Shelf registration (Rule 415, 1982–1983) and at-the-market programs (1982, 2005) let companies prepare financing in advance and raise capital at market prices. Buybacks, recognized since 1828 with the 1982 Rule 10b-18 safe harbor, let firms manage capital in both directions. Bitcoin, launched in 2008–2009 and classified as a commodity by the CFTC in 2015, provides a new reserve asset, while companies supply capital structure, dollar liquidity, and distribution policy. Digital credit thus combines over 400 years of corporate ownership transfer, roughly 190 years of U.S. preferred stock, more than a century of tax cost-recovery rules, and four decades of modern shelf and ATM regulation into a familiar framework for investors.
marsbit3h ago