Author: Will Owens, Galaxy Research Analyst
Compiled by: Jiahuan, ChainCatcher
Introduction
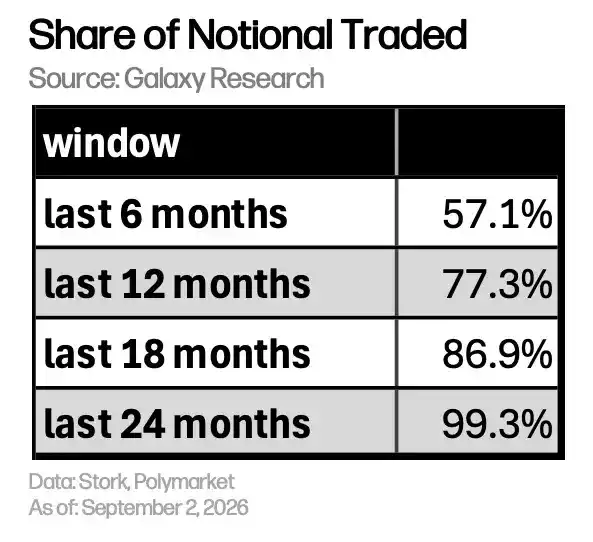
Since its launch in 2020, the Polymarket International platform has matched 1.27 billion orders for 3.07 million wallets, with a notional trading volume of $82.8 billion. Since all transactions are settled on-chain, we can review the complete record, including every position, entry price, holding period, and settlement payout, to understand the actual behavior of users on the prediction market. This report narrows its scope to 2.9 million accounts whose trading patterns are consistent with manual operation.
This report asks five questions about these accounts: After making a profit, do traders cash out and leave, or do they continue trading? Does winning make them bolder, and does losing make them more cautious? How are profits and losses distributed? Do traders typically specialize in specific areas, and does this focus lead to better returns? What are the actual differences between profitable and unprofitable traders?
Studying retail trading behavior typically relies on information disclosed by brokers or survey data. However, since Polymarket settles on-chain, there is no longer a debate about the representativeness of the sample.
The core conclusion is: 69% of retail accounts ended up with a net loss, with this group collectively losing $339 million.
In 2024, Polymarket gained prominence primarily due to the US election night. Since then, the company has re-entered the US market through a subsidiary licensed by the US Commodity Futures Trading Commission (CFTC) and introduced taker fees for the first time in early 2026. The discussion below pertains to the International platform, which is a completely separate trading platform from the US app, with its own order book.
Polymarket adjusted its fee structure earlier this year. As this report's data covers the platform's entire history, some accounts conducted all their trades before the platform began charging fees.
This is also the first full NFL season since both Polymarket and its competitor Kalshi entered the US market. Both platforms have consequently increased their investments. At the start of the season, Polymarket had already enlisted sports stars like LeBron James, Eli Manning, and Derek Jeter as "Promotional Partners," a move that also drew some criticism.
Launched alongside this promotional push is the social feature "Squads" within the US app. Squads are private groups where users can discuss prediction markets and trade based on other members' picks without leaving Polymarket. This feature aims to bring group chat discussions onto the platform. Another platform is adding social trading features, a trend also seen in recent announcements from pump.fun.
Facing such vast potential trading volume, both platforms are spending to grow their user base, and they are attracting precisely the type of traders who performed worst in this report. It will be interesting to observe whether the composition of traders changes significantly or simply increases substantially in the coming year.
Key Summary
Among 2.9 million "retail" accounts, 69.2% ended with a net loss.
This group collectively lost $338.9 million.
Losses appear to increase user churn.
After a loss, 15.2% of accounts did not trade again within 30 days.
After a profit, this figure was 6.1%.
If traders potentially have an edge in a certain area, focusing on that area can yield better returns.
44.1% of traders concentrated over 60% of their trading activity in one area.
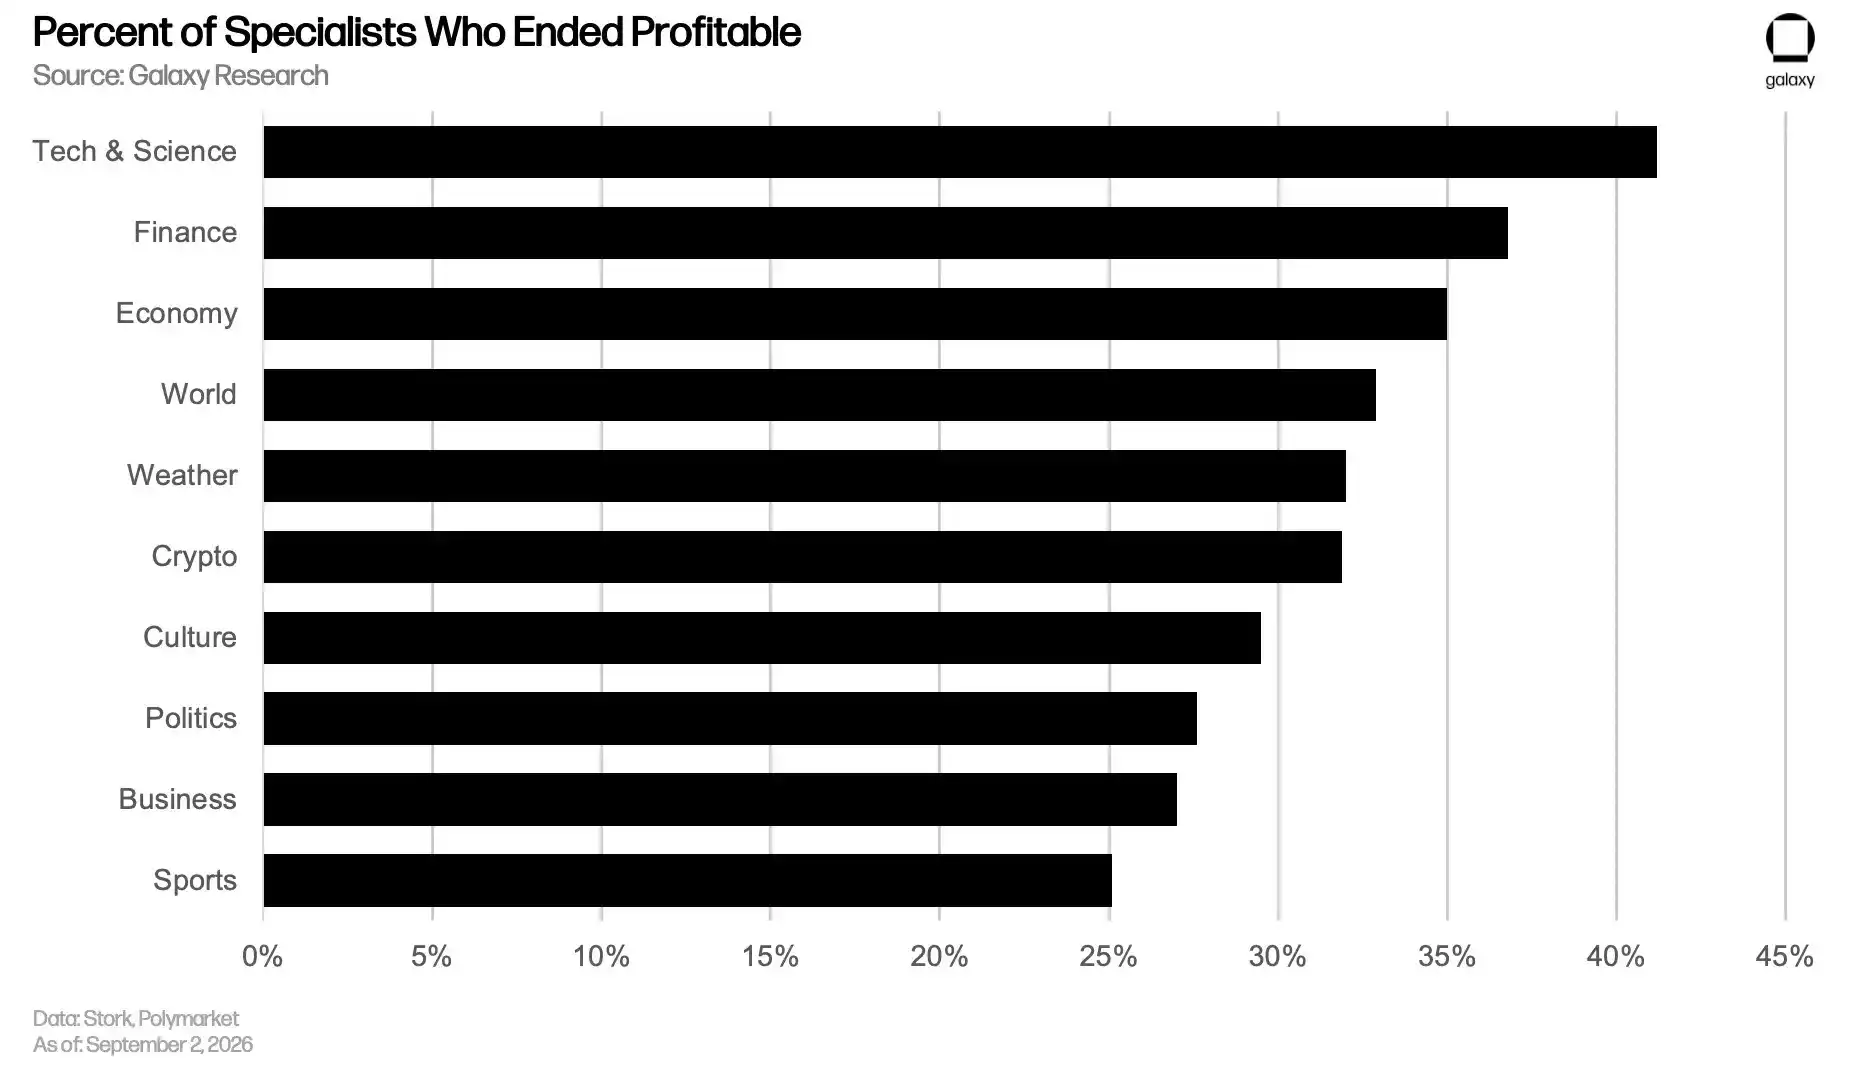
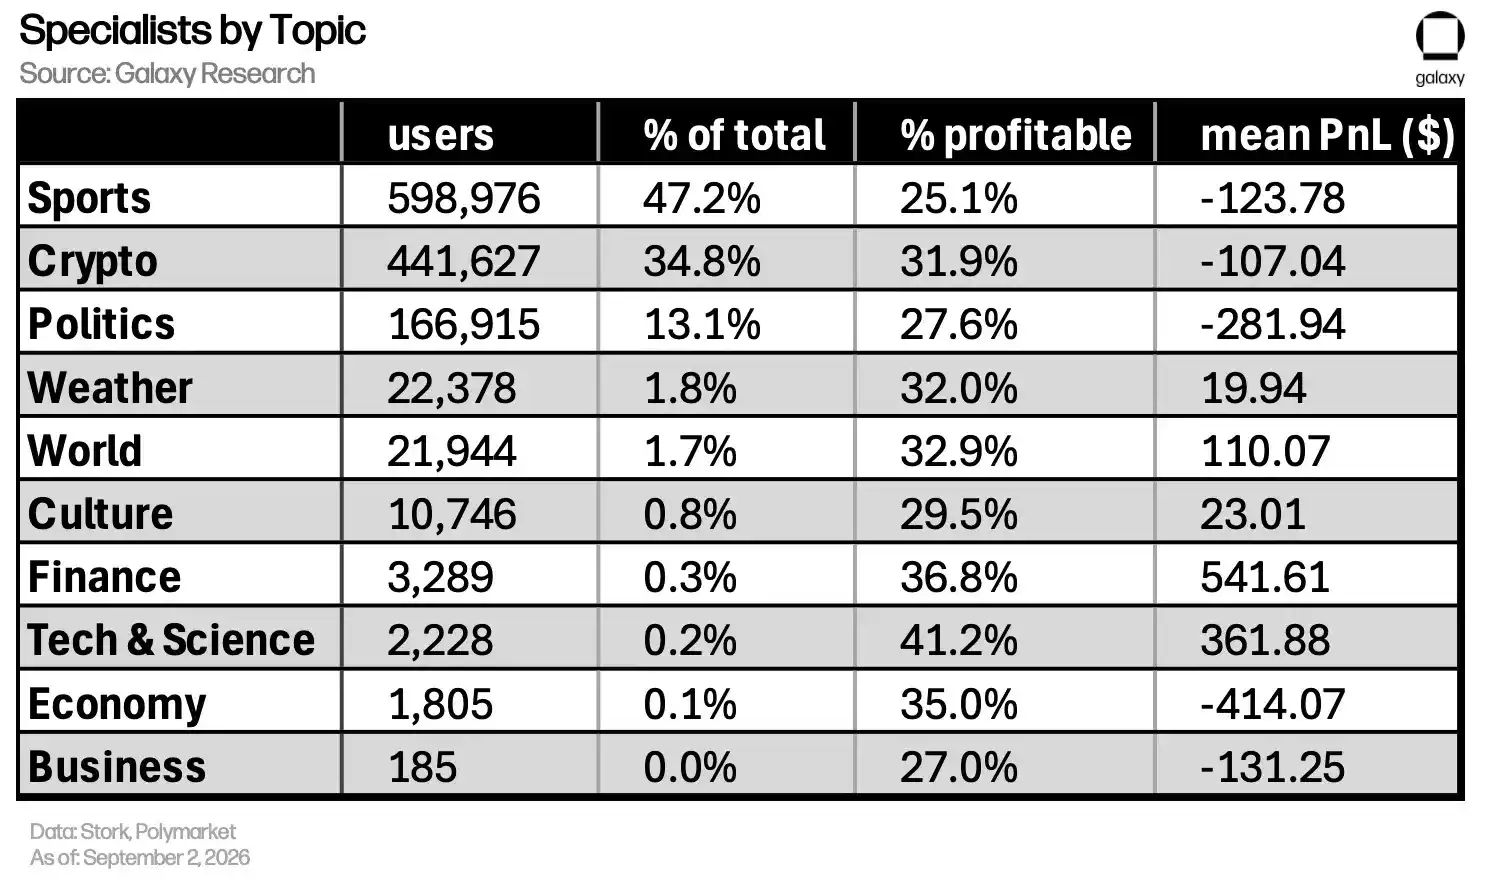
Traders focused on sports performed the worst, likely because many are amateurs or casual participants, not market makers or arbitrageurs.
Traders focused on technology and science performed the best; some may have insider information, while others may be experts in related fields.
Profitable traders tend to make larger bets per trade.
Their median bet size per position was $13.96, compared to $10 for unprofitable traders.
Research Methodology
Dataset: Polymarket settles on-chain, meaning the complete record of every order, position, entry price, and settlement payout is public. All analysis in this report is based on this record.
Study Subjects: We aim to study human behavior, so we need to exclude automated accounts trading via scripts. While we cannot precisely identify which accounts use automation, we can estimate using "orders per active day." This metric equals an account's total orders divided by the number of days on which it actually traded.
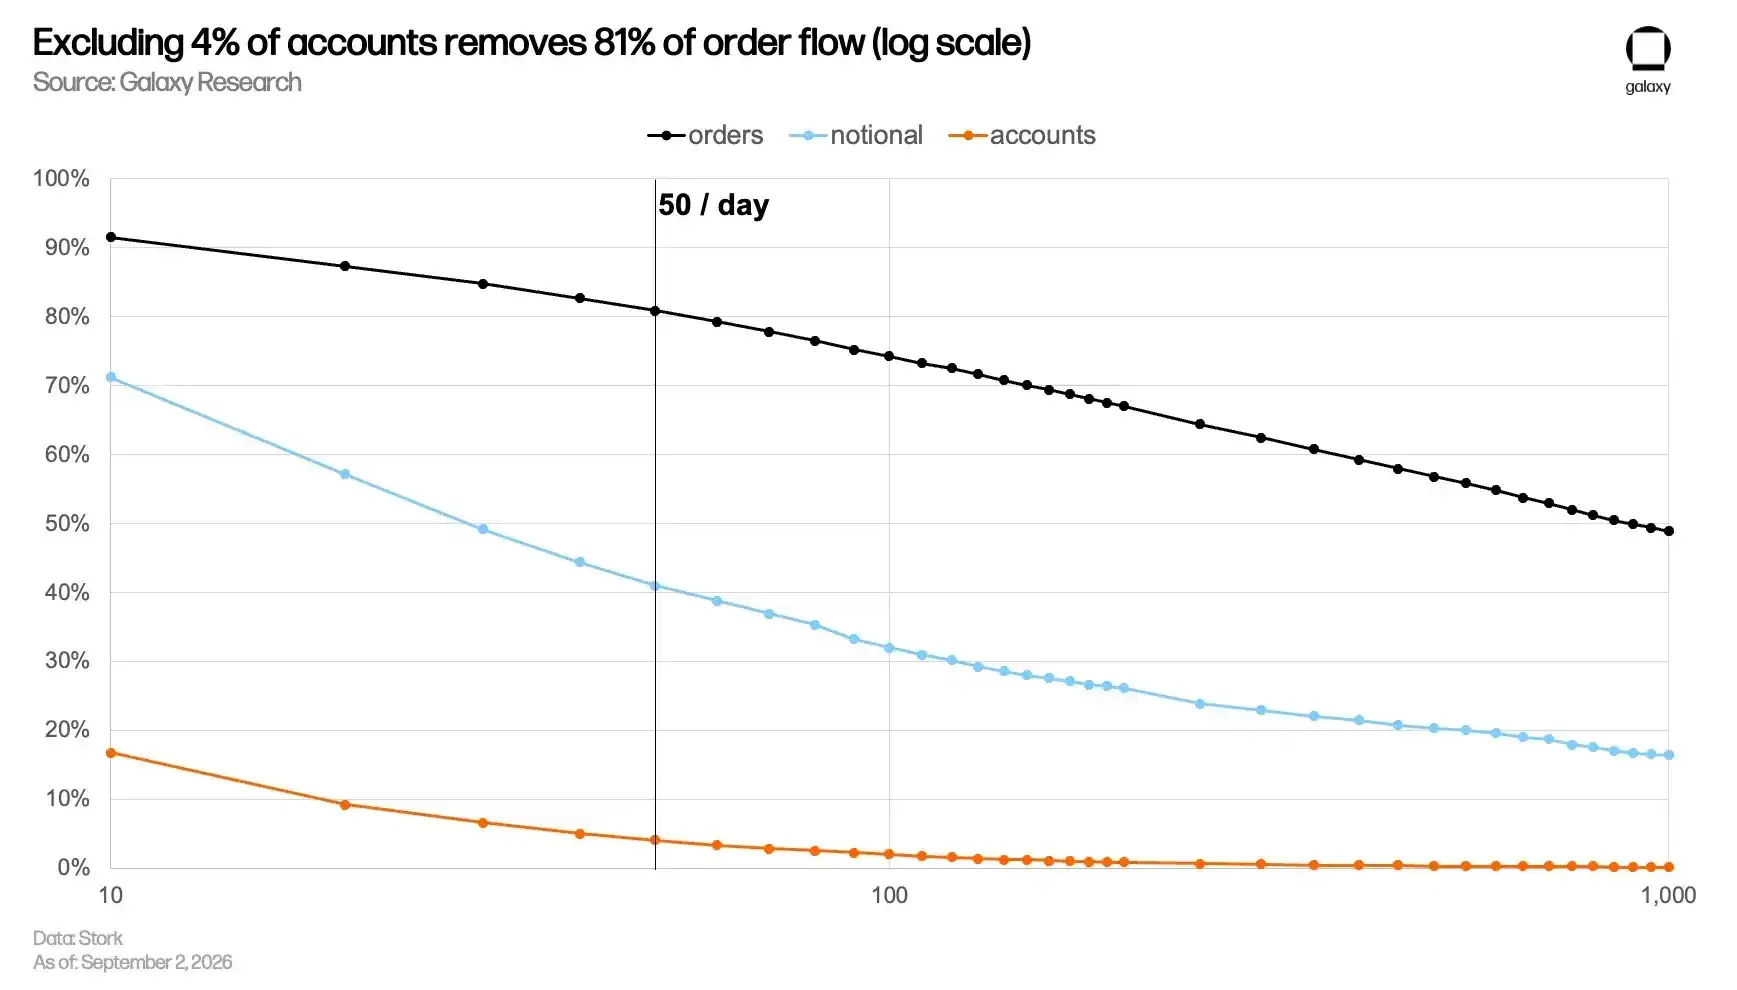
The distribution of orders per active day is continuous, with no natural cutoff. Therefore, the threshold requires researcher judgment. We used a cutoff of 50 orders per active day, excluding 125,429 accounts, or 4.1% of the total. Although these accounts represent "only" 4.1%, they accounted for 80.8% of all orders and 41% of the notional trading volume. This filtering aims to identify situations where a small number of accounts handle a disproportionately large share of trading activity.
Retail: Our screening is based on trading frequency. Even if a trader has ample capital, as long as they make independent judgments and click to place orders manually, they are categorized as retail here. Thus, the conclusions pertain to accounts trading at a manual pace, not strictly economically defined "retail" investors.
Profit Measurement: An account is considered profitable if the settlement value of its positions is higher than their purchase cost, regardless of whether the holder actually redeems them. Positions that expire worthless are typically not redeemed. If we only counted redemption records, most losses would be excluded, making this group appear more profitable than they actually are.
An important limitation of this report: We identify traders by wallet addresses but cannot reliably determine if two addresses belong to the same person. Therefore, a single person trading with multiple wallets would be counted as "multiple accounts" in this analysis.
This is particularly relevant when interpreting the conclusion that "losing traders are more likely to stop trading." An account that appears to have exited may simply be using a new wallet.
How are Profits and Losses Distributed?
Among retail accounts, 69.2% ended with a net loss. This group collectively lost $338.9 million.
The median net profit/loss for retail accounts was approximately a $3 loss. Half of all accounts had a net result between a $36.64 loss and a $0.40 profit. These amounts are not life-changing. As expected, larger gains and losses are concentrated at the extremes: accounts at the 1st percentile lost $4,804, while those at the 99th percentile gained $3,381.
Measured against the amount invested, the median account lost about 0.5% of its invested funds, while the 10th percentile lost 90%. Overall, the vast majority of accounts lost very little money, with only a few losing thousands of dollars.
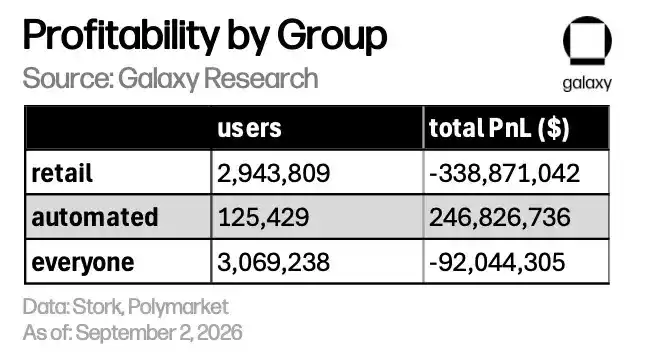
We classified 125,429 accounts as "automated accounts," which collectively ended with a net profit of $246.8 million. Their profit/loss distribution also aligns with expectations: many accounts repeatedly traded to capture trading rewards, while far fewer were engaged in actual market making and arbitrage.
The profits and losses of these two groups do not completely offset. A discrepancy of approximately $92 million comes from factors outside the trader groups, primarily unsettled positions.
After Making a Profit, Do Traders Cash Out or Keep Trading?
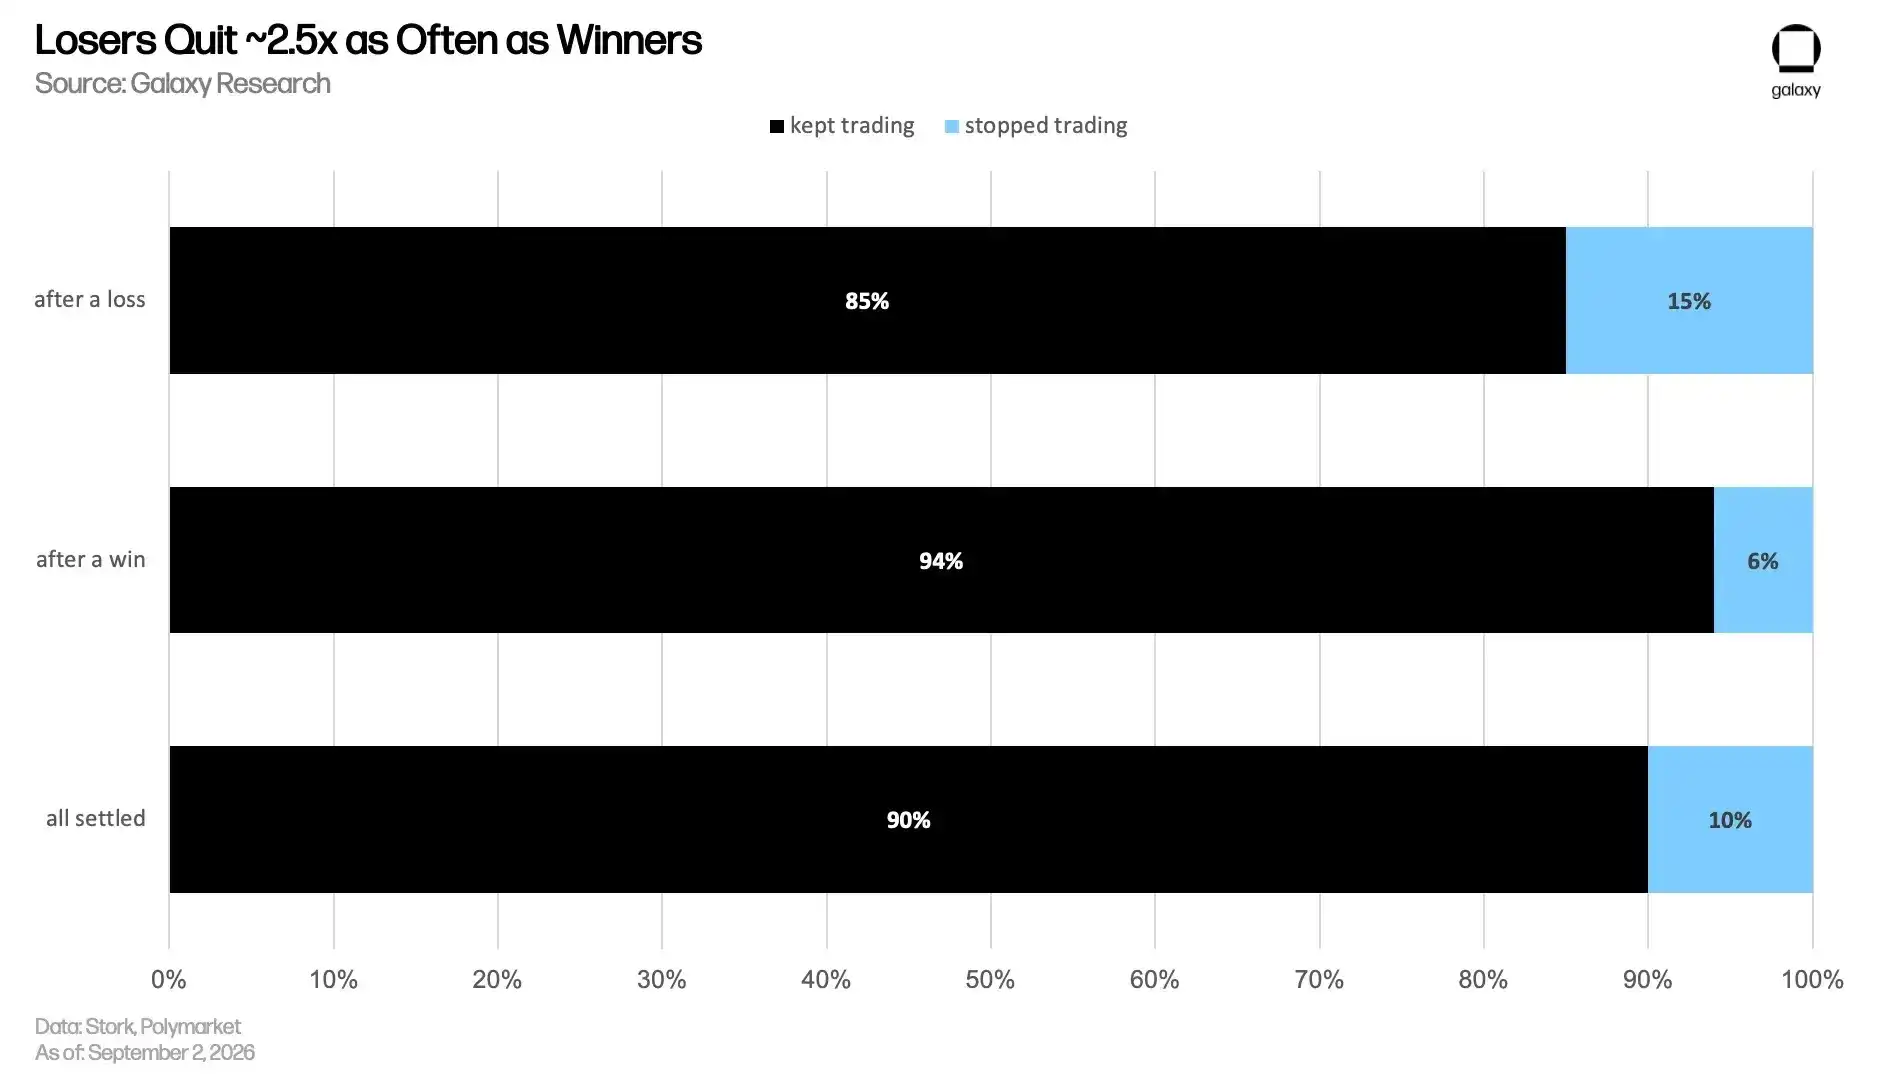
Most keep trading. Profits tend to keep users on the platform: after a profit, only 6.1% of accounts did not open a new position within 30 days; after a loss, this figure was 15.2%. Losing accounts were about 2.5 times more likely to leave.
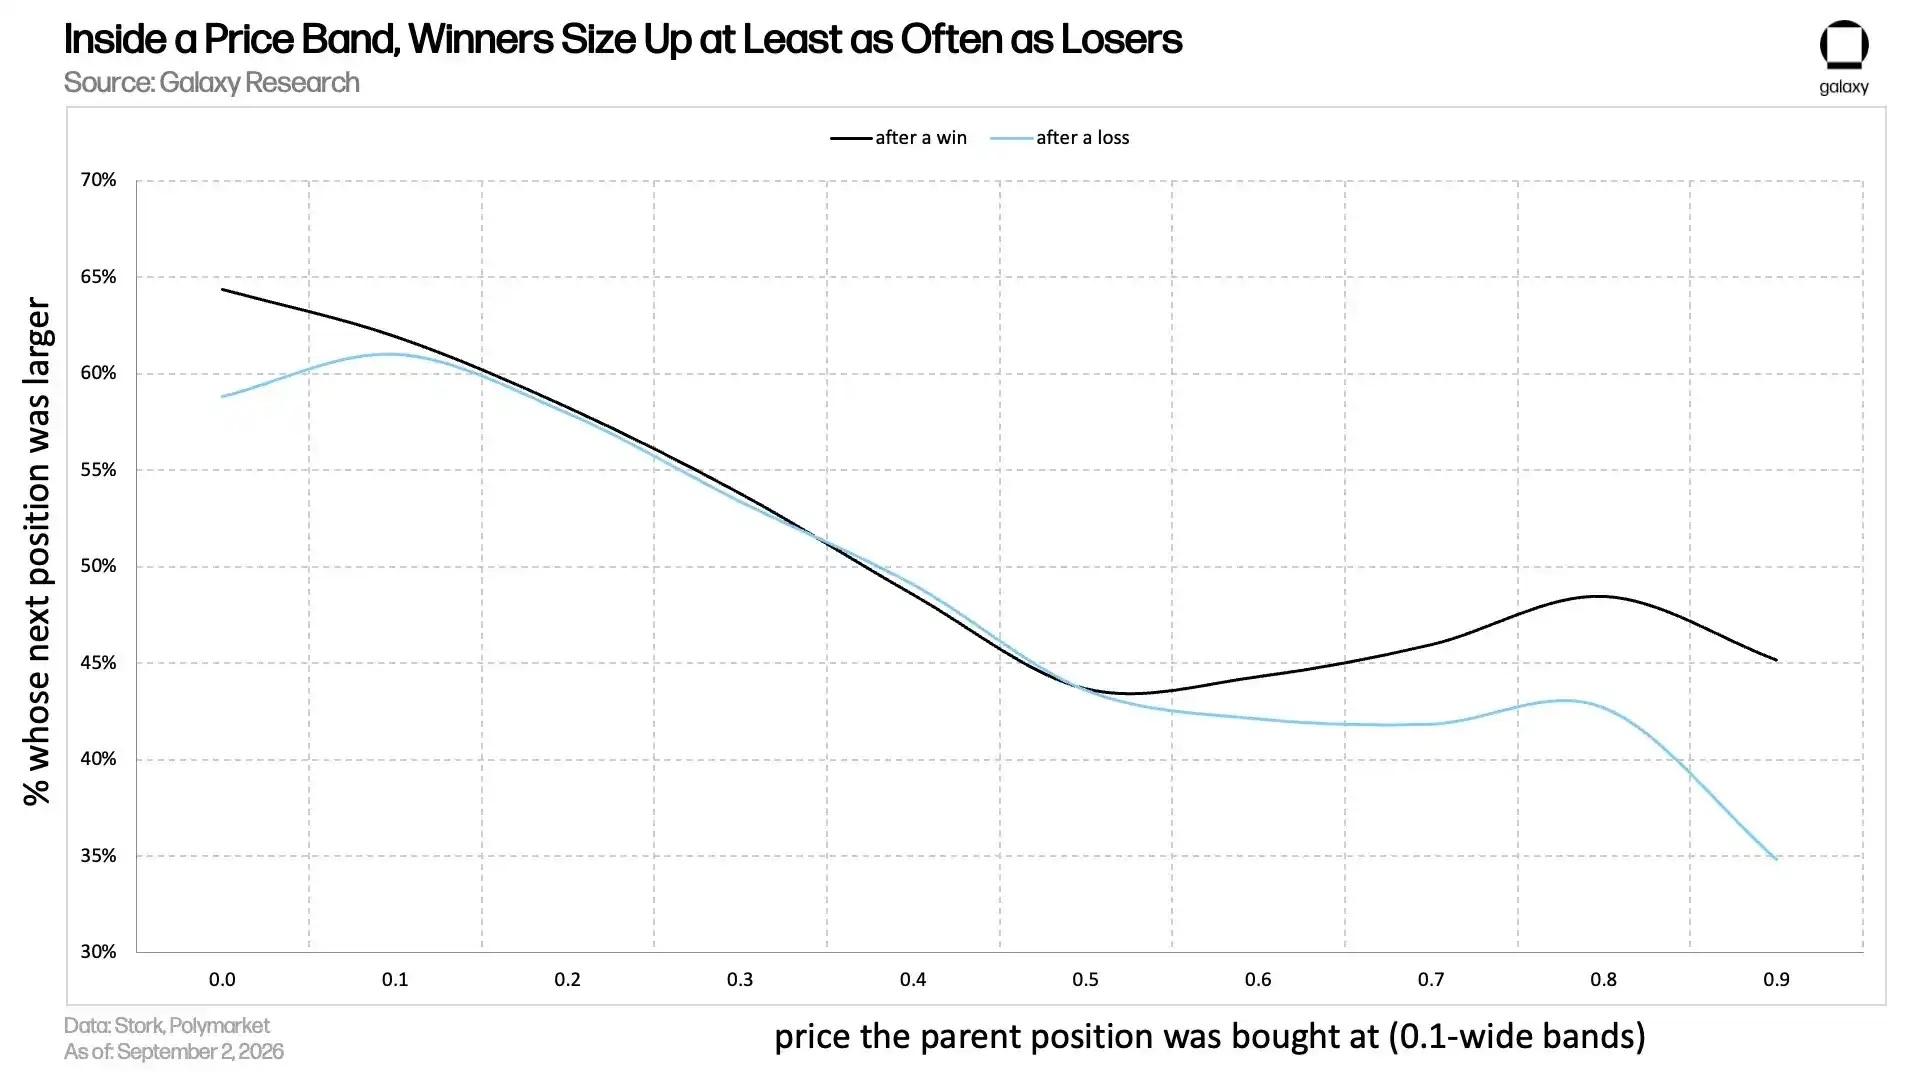
Intuitively, winning might lead traders to bet more on their next trade. However, unadjusted data shows the opposite: after a profit, 46.6% of the next positions were larger; after a loss, this figure was 50.2%. However, this comparison is influenced by other factors.
The entry price for losing positions was much lower than for winning ones, with medians of $0.43 and $0.86, respectively. Therefore, when the entry price is lower, it's easier for the next trade's bet size to increase. (If the prediction comes true, each contract settles for $1; otherwise, it settles for $0. Therefore, a price of $0.43 implies the market assigns a 43% probability to the event; the buyer at this price believes the true probability is higher.)
After controlling for entry price, the conclusion reverses. Within the same price range, traders increased their bets more often after a profit than after a loss. This phenomenon is concentrated in entry prices above $0.50. Below this price, reactions to profits and losses were almost identical, likely because traders view these trades as long-shot attempts and don't over-interpret any single outcome.
Does Winning Make Traders More Willing to Take Risks? Do Losers Double Down?
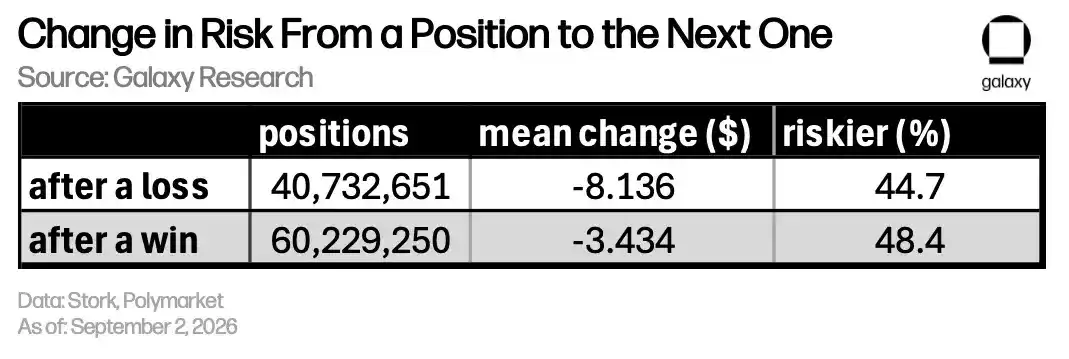
Losers typically contract. Here, "risk" refers to expected loss, not the total principal that could be lost. Assuming buying t tokens at an average price p, the buyer's expected loss is t × p × (1 − p). This means a position predicting a 99% probability event with $100,000, while large in size, would not be considered high-risk by this metric.
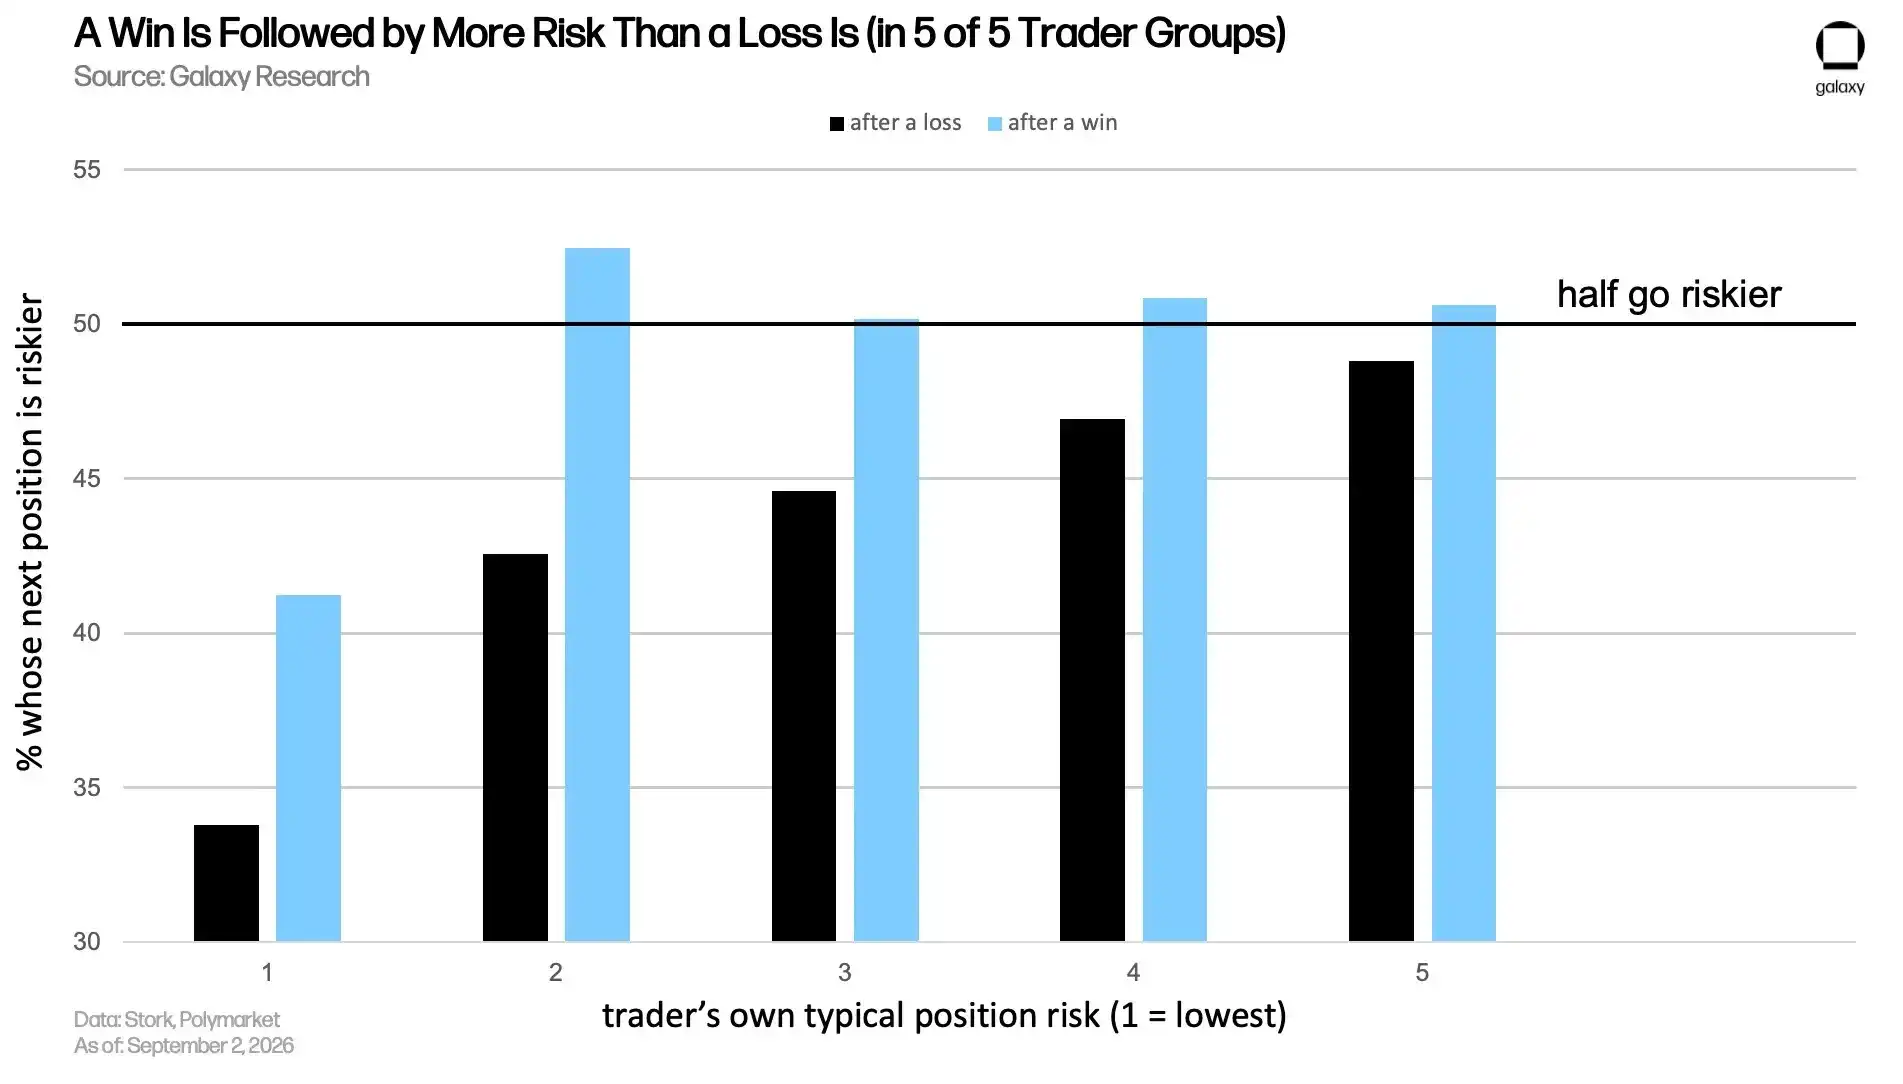
Regardless of whether the previous trade was profitable or not, traders' risk typically decreases. Their next position often carries slightly less risk than the one just settled. However, the contraction after a profit is noticeably smaller: after a profit, 48.4% of next positions had higher risk than the previous one; after a loss, this figure was 44.7%. The median risk change for both groups was zero, so most traders simply returned to their prior risk level.
We divided traders into five equal groups (quintiles) based on their typical position risk. Q1 typically takes the least risk, Q5 the most. The comparison of behavior after profits and losses is conducted within each group, thus comparing a trader's own performance under different outcomes.
Do Traders Focus on One Area or Diversify? How Does Performance Differ?
We define "single-area traders" as users who have participated in at least five categorized prediction markets, with over 60% of their activity in one area. By this definition, 44.1% of traders are single-area traders, and 55.9% are "cross-area traders."
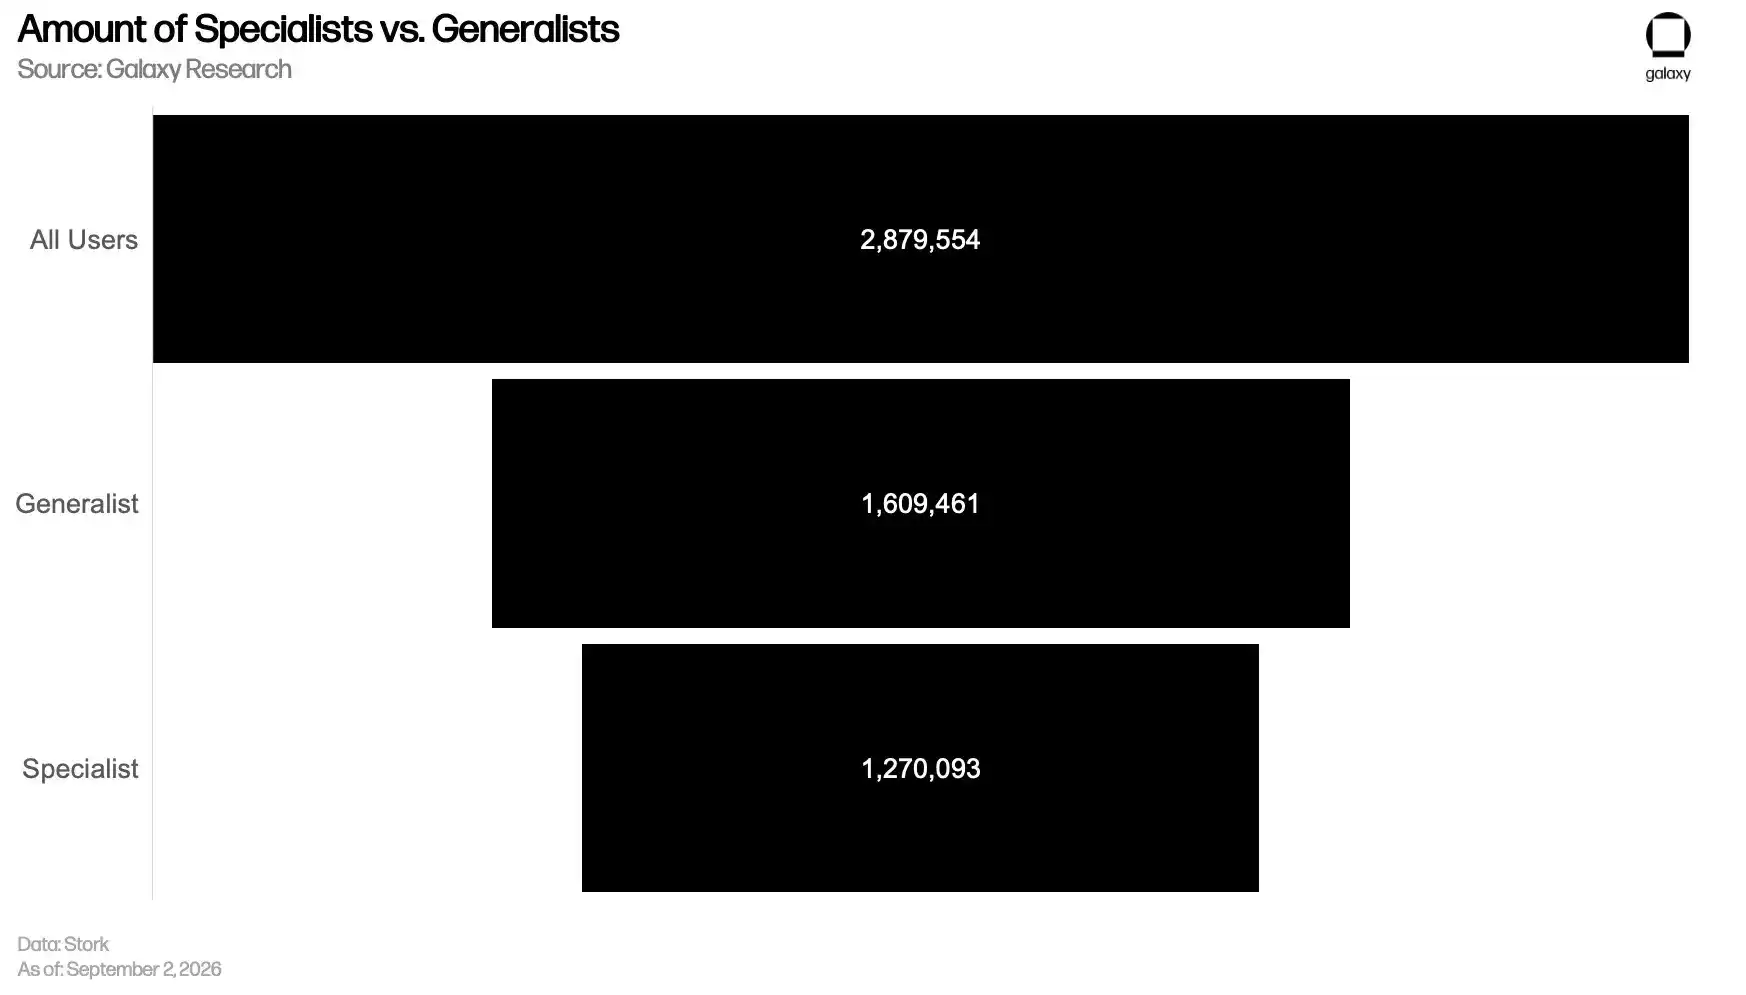
We can answer these questions because Polymarket tags each prediction market. To avoid classifying all traders as "single-area," we consolidated these tags into ten areas: Cryptocurrency, Sports, Politics, Finance, Economics, Weather, Culture, International Affairs, Technology & Science, and Business. Subcategories typically also carry the parent tag; for example, a football prediction market is also tagged as Sports.
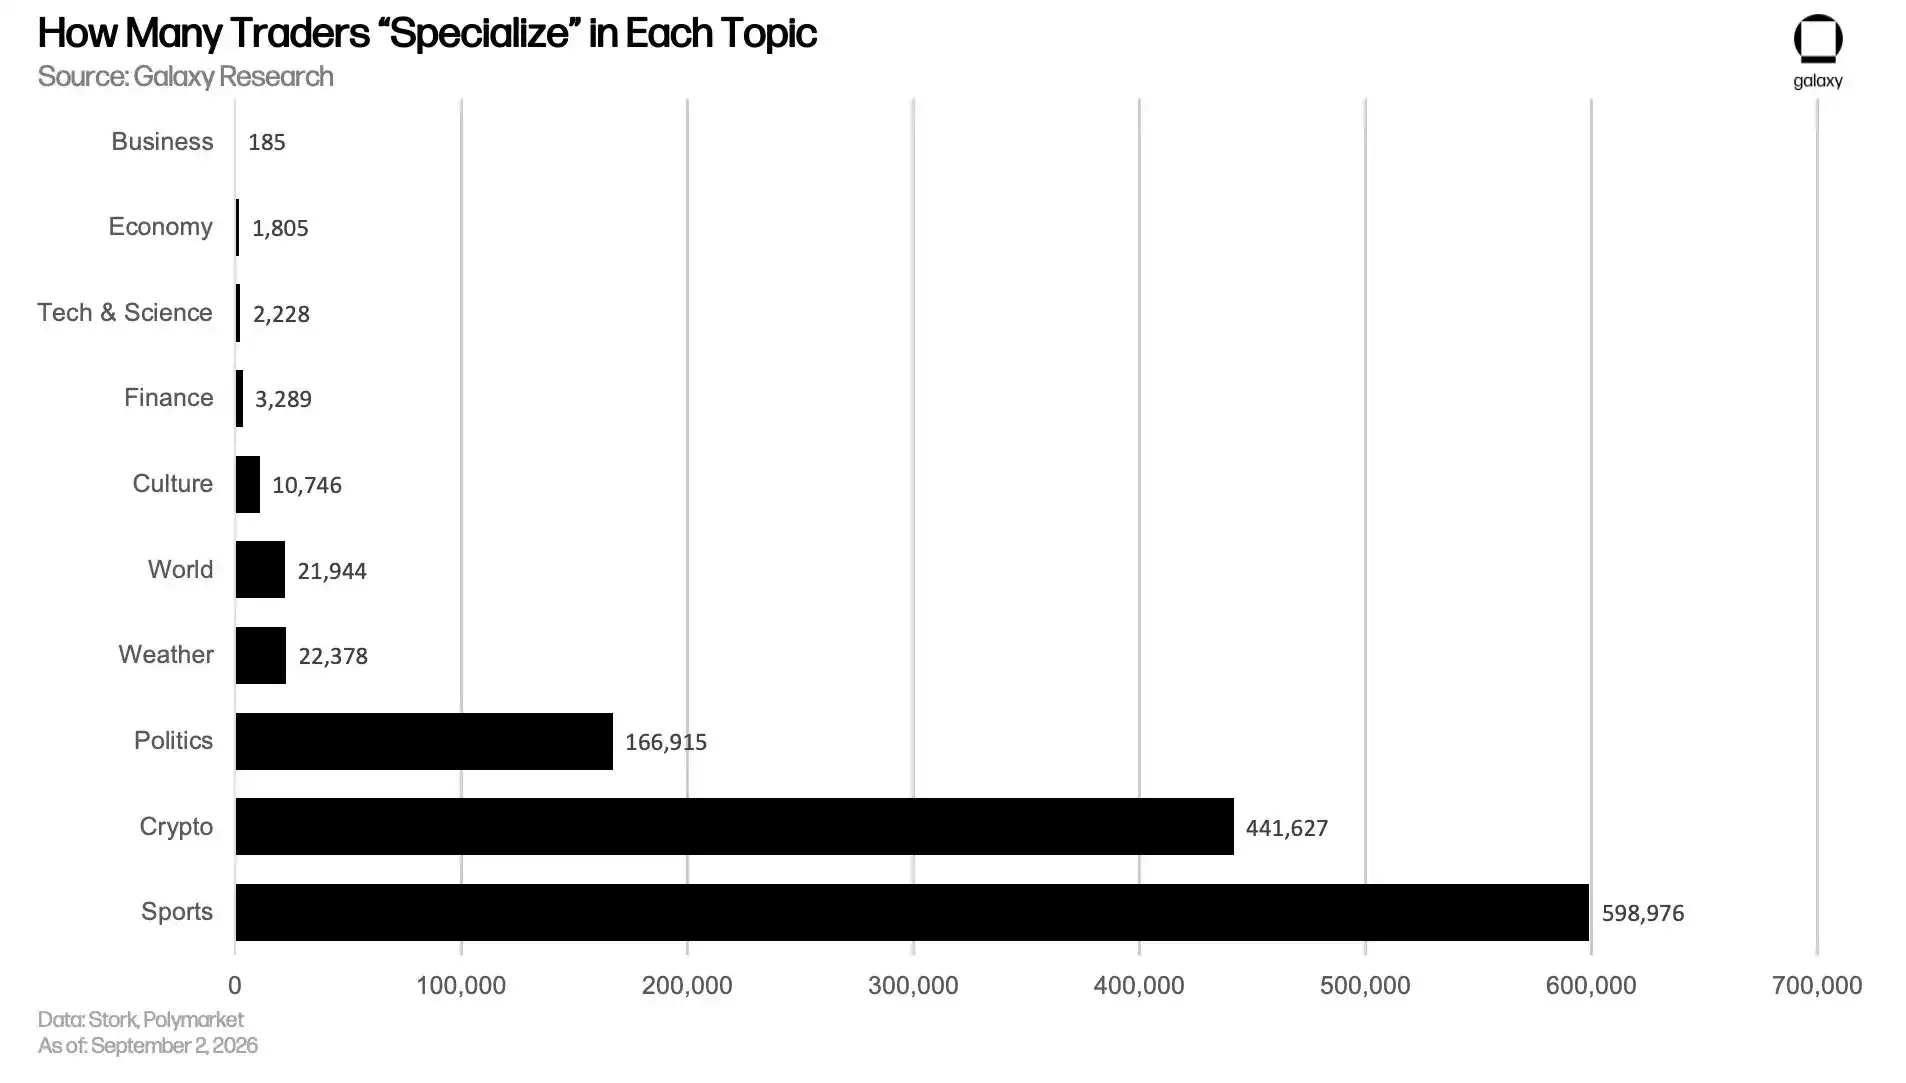
Single-area traders performed slightly worse, with 28.1% ending profitable, compared to 30.4% for cross-area traders. The reason is that 61% of single-area traders are concentrated in the three worst-performing areas: Sports, Politics, and Culture.
A person who only trades NFL game predictions on Sundays is probably not doing actuarial analysis.
Clearly, if a trader potentially has an edge in a specific area, focusing on it can yield better returns. Someone who only trades prediction markets related to OpenAI model releases likely has some advantage, which isn't necessarily insider information but could simply be skill in analyzing public information. A person who only trades NFL game predictions on Sundays is probably not doing actuarial analysis.
Sports alone accounts for 47% of all single-area traders, with only 25.1% of these accounts profitable, the lowest among all areas. Excluding Sports, Politics, and Culture, single-area traders in every other area had a higher profitability rate than the cross-area traders' 30.4%. Finance was 36.8%, and Technology & Science was 41.2%. Note that Technology & Science is a smaller category with a smaller sample.
The median number of prediction markets participated in was 18 for single-area traders and 4 for cross-area traders. Since the definition of focusing requires participation in at least five categorized markets, low-activity accounts are by default classified as cross-area traders.
What are the Differences Between Profitable and Unprofitable Traders?
Comparing the median holding period and median bet size per position between profitable and unprofitable traders yields several conclusions.
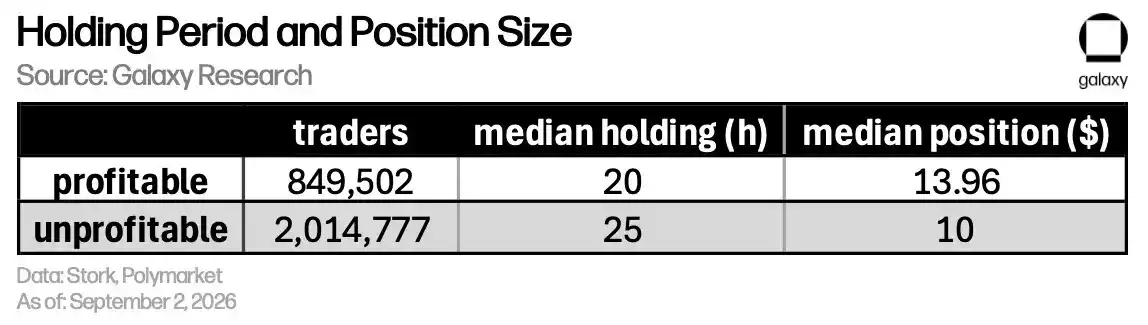
Regarding bet size, profitable traders had a median bet size per position of $13.96, while unprofitable traders had $10.00. However, profitable traders also traded more frequently, so this difference might simply reflect different activity levels rather than a difference in bet size itself. After grouping traders by their total number of positions taken, within each group, profitable traders' single bet sizes were no lower than those of unprofitable traders, and in most groups, they were significantly higher.
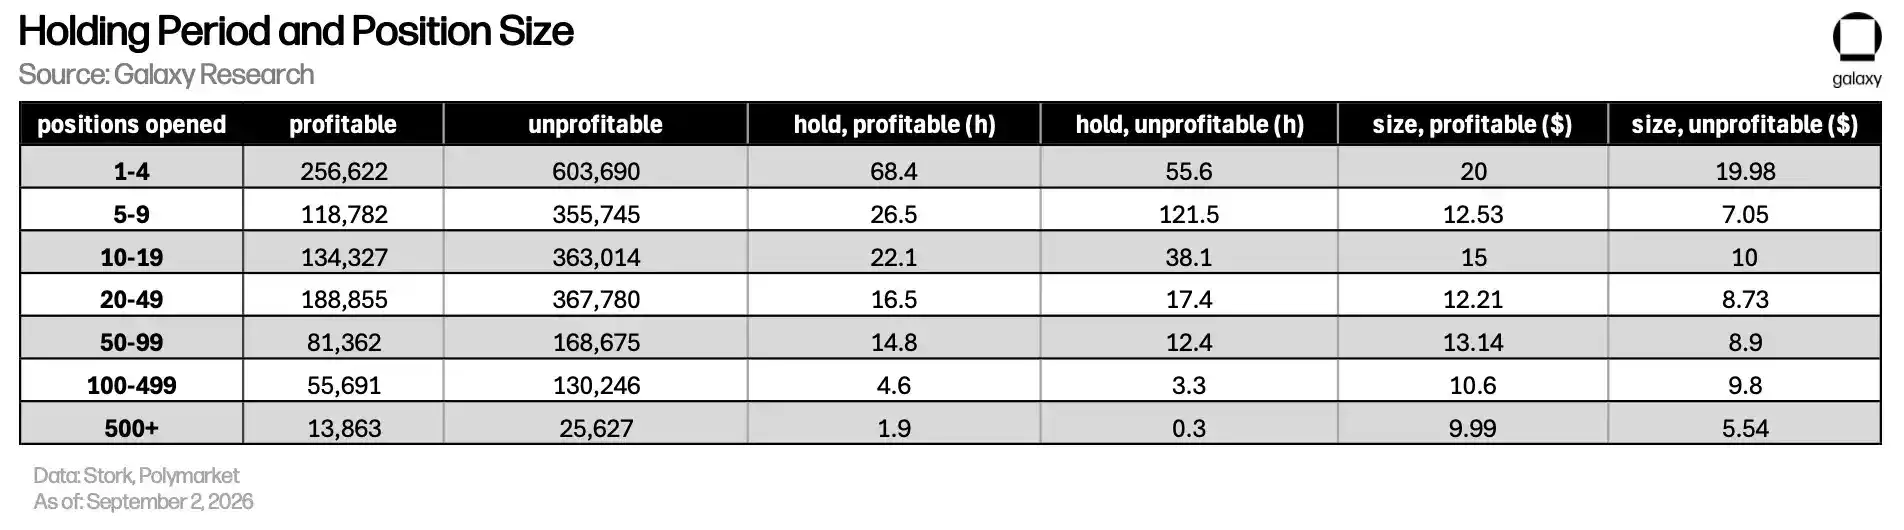
Among traders who had taken 5 to 9 total positions, the median bet size for profitable vs. unprofitable traders was $12.53 vs. $7.05; for those with 50 to 99 total positions, it was $13.14 vs. $8.90.
Holding period is less conclusive. Looking at all traders together, profitable traders held for shorter periods, with a median of about 20 hours, compared to about 25 hours for unprofitable traders.
But after grouping by activity level, the relationship of holding periods changes. In some groups, profitable traders held longer; in others, unprofitable traders held longer. Therefore, we cannot draw a clear conclusion from this data about a definite relationship between "more patience" and "higher profitability."
This differs from meme coin trading. In meme coin markets, those engaging in "scalping" ultra-short-term trades or quickly trading new pairs perform better. They are typically snipers or experienced traders who hold for just seconds to quickly take profits.
For more on such traders, refer to our Meme Coin Report; for the nature of KOLs and the resulting trading behavior, see our Social Trading Report. It should be noted that this "trading" style is quite different from trading perpetual contracts or prediction markets.
Outlook
The original goal of prediction markets was to aggregate information and harness the wisdom of the crowd. But in recent years, they have increasingly been criticized as pure guessing platforms. This report presents the profit/loss distribution of Polymarket's user base: 69% ended with a net loss, and the largest group of single-area focused users primarily trades sports-related prediction markets.
Polymarket began charging taker fees for cryptocurrency price movement prediction markets in January 2026, and by the end of March, fees covered almost all categories. Taking an example price of $0.50 per contract, buying 100 contracts in a crypto market for $50 would incur a $1.75 taker fee, equivalent to 3.5% of the single bet amount.
Politics, Finance, and Technology have the lowest fee rates at 2.0%; Sports is 2.5%. The median retail account in our entire history lost about 0.5% of total funds invested. Today, for an event with a 50% probability, the fee for a single taker trade alone is several times this percentage.
This report does not negate the value of prediction markets as tools for discovering truth.
Arguably, the fact that most participants lose, absent other forms of subsidy, is a prerequisite for information aggregation to occur. Capital with an informational edge needs to trade against traders without that edge. If all Polymarket participants were equally savvy, no one would trade. This report does not negate the value of prediction markets as tools for discovering truth. Polymarket can perfectly well have most participants lose while still providing predictive references for non-participants. It is precisely this noise trading that bears the cost of prediction.
This report is strictly limited to the International platform. Polymarket's US exchange is separate and is the company's recent primary focus for investment. For example, the funds invested to secure LeBron James's partnership illustrate this. According to Front Office Sports, Polymarket pays James $15 million annually, roughly 4 times his NBA playing salary this year. To comply with NBA rules, his promotional content is limited to American football-related prediction markets. Jeter and Manning also have partnership agreements with the platform.
The marketing investments aim to attract precisely the group that performed worst in this dataset. From a business perspective, this is understandable. Polymarket likely doesn't care if users are profitable. At least in the short term, the platform has more incentive to attract uncritical taker users than more professional market maker traders.
On Polymarket, the counterparty for every trade is a public address. Anyone who disagrees with this report's analysis can verify it themselves.
A recent controversy at Kalshi is also noteworthy. On September 20th, a quantitative trader known as beniduboss on X accused the exchange of inflating cryptocurrency perpetual contract trading volume. This is a serious allegation.
Beni cited data showing a 24-hour trading volume for ETH-PERP of approximately $538.6 million, yet open interest was only about $3.1 million, which is highly unusual in perpetual markets. For comparison, Hyperliquid's ETH-PERP typically has around $1.3 billion in 24-hour volume and about $3.1 billion in open interest.
Kalshi officially denied the accusation, stating the confusion arose between the number of contracts in a prediction market and the notional volume of a perpetual contract. As of writing, regulators have not taken action.
It's worth noting that people outside the exchange cannot actually verify this matter. Kalshi's public data feed does not identify both parties in each trade, so one cannot determine from this data alone if both sides are controlled by the same entity. On Polymarket, the counterparty for every trade is a public address. This means anyone who disagrees with this report's analysis can verify it themselves.
As prediction markets evolve and enter regulated platforms using proprietary order books, the ability for outsiders to audit trading volume data is no longer a given.