Artículos Relacionados con mNAV

El Centro de Noticias de HTX ofrece los artículos más recientes y un análisis profundo sobre "mNAV", cubriendo tendencias del mercado, actualizaciones de proyectos, desarrollos tecnológicos y políticas regulatorias en la industria de cripto.

After YZi Labs Reclaims Control, BNB Treasury CEA Industries is Undervalued

CEA Industries (BNC), the BNB Treasury company, has regained investor attention amid the rise of BSC's tokenized stock meme trend. Its tokenized stock counterpart, BNC4, launched on Four.meme, has driven BNC's pre-market price up over 60%. This resurgence follows the resolution of a months-long governance battle. In June 2026, YZi Labs successfully regained control of the company's board through a cooperation agreement, appointing key figures like Alex Odagiu as interim President. Despite the leadership transition, CEA Industries' operations have appeared stagnant; its BNB holdings have remained unchanged at 515,544 tokens for over four months. However, the company's fundamentals remain strong, with a substantial BNB reserve valued at approximately $380 million at an average cost of $855 per token. With a current market cap around $140 million and a market NAV (mNAV) ratio below 0.5, analysts suggest BNC is significantly undervalued. A price target of $9.39 is cited for mNAV to reach 1. A major potential catalyst is the significant buy-side pressure from Four.meme's BNC4 minting process. Reports indicate over $8.9 million is queued to purchase BNC stock to back the minted tokens. Positioned at the intersection of the meme stock narrative and the BNB ecosystem, BNC could benefit from a potential valuation re-rating if operational momentum resumes under its new leadership.

marsbit09/08 14:36

After YZi Labs Reclaims Control, BNB Treasury CEA Industries is Undervalued

marsbit09/08 14:36

Is the MicroStrategy Model Failing? Imitator Holding 30,000 Bitcoins Sees Pre-IPO Investors Backing Out

"The 'Bitcoin Treasury' model is facing a critical test. BSTR Holdings, a company founded by Adam Back and holding 30,021 Bitcoin, has called off its planned merger with SPAC Cantor Equity Partners I. The deal, which would have taken it public, fell apart as the attached private investment (PIPE) financing collapsed. This failure highlights a core vulnerability of the 'Bitcoin accumulation company' strategy popularized by MicroStrategy. The model relies on a key metric: mNAV, or the premium of a company's stock market value over the value of its Bitcoin holdings. This premium fuels a cycle where companies issue shares at a premium, use the cash to buy more Bitcoin, and theoretically increase the Bitcoin per share for investors. However, with Bitcoin's price down roughly 49% from its late-2024 peak, this premium has evaporated across the sector. Companies like American Bitcoin and Metaplanet are also under severe pressure. For BSTR, the lack of premium meant investors were unwilling to fund the original deal structure at the proposed terms. The companies are now renegotiating. The next SEC filing detailing any new agreement will be a crucial indicator. It will show if the model can be repriced for a low-premium environment by preserving Bitcoin holdings and investor commitments, or if it requires significantly diluting shareholders and scaling back ambitions. The outcome is a public stress test for the entire 'Bitcoin treasury' investment thesis."

marsbit07/13 06:09

Is the MicroStrategy Model Failing? Imitator Holding 30,000 Bitcoins Sees Pre-IPO Investors Backing Out

marsbit07/13 06:09

STRC Trading at Significant Discount, mNAV Falls Below Break-Even, Strategy's Valuation Logic Has Been Rewritten

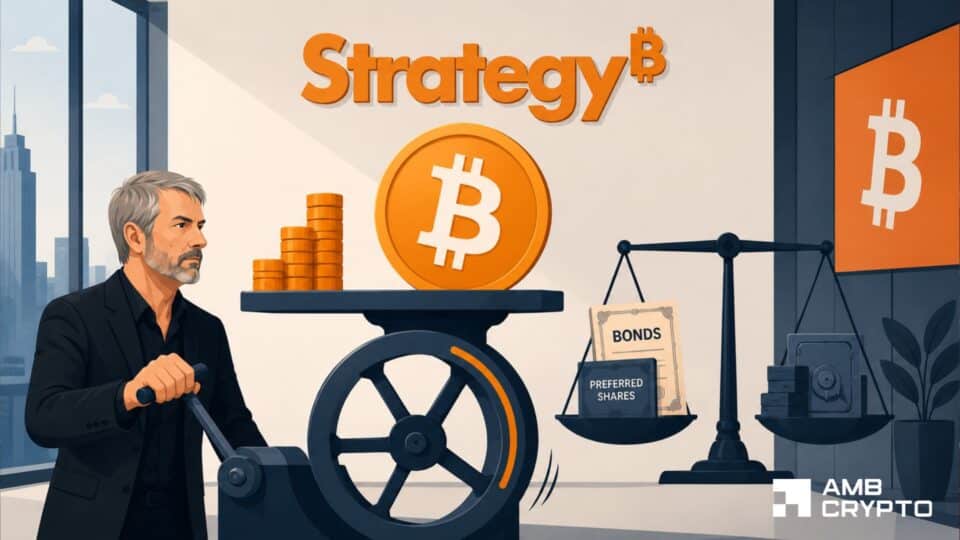
Title: STRC Deeply Discounted, mNAV Falls Below Break-even, Strategy's Valuation Logic Redefined The recent volatility in MSTR and STRC highlights the need to reassess the core business model of Bitcoin reserve companies. These entities function more like leveraged, single-asset banks rather than software/tech firms. Consequently, they should be valued using banking metrics, not based on their total Bitcoin holdings. The key valuation metric is mNAV (market net asset value), akin to a price-to-book ratio. It compares the company's market capitalization to the equity value of its Bitcoin holdings after deducting all senior debt and preferred equity (like STRC). As of June 24, Strategy's mNAV was 1.10x. The focus should be on "net Bitcoin per share" (the Bitcoin claim per share after senior claims) and its growth rate, equivalent to a bank's book value and return on assets. Given STRC's 19% discount to its $100 par value (yielding 14.2%), issuing new MSTR equity at the current price to buy more Bitcoin is inefficient. It slightly dilutes the widely watched "total Bitcoin per share" metric while providing minimal improvement to the more critical "net Bitcoin per share." The article analyzes four potential uses for $1 billion in new equity: 1. **Buy Bitcoin:** Least effective. Improves net Bitcoin per share only marginally while diluting total Bitcoin per share. 2. **Repurchase STRC:** Most effective for balance sheet repair. The discount creates immediate value, increasing net Bitcoin per share by 1.0%, reducing debt burden, and lowering future dividend obligations. 3. **Boost Cash Reserves:** Dramatically improves the "cash coverage ratio" for STRC dividends from 9.8 months to 16.8 months, a crucial liquidity metric in a tightening funding environment. 4. **50/50 Split (STRC buyback & cash):** A balanced approach improving all key metrics. Strategy's own Q1 report indicates its internal break-even mNAV for profitable equity issuance to buy Bitcoin is 1.22x. With the current mNAV at 1.10x, such a move would be value-destructive. The core assumptions of its previous expansion model—issuing STRC at par and maintaining ample dividend coverage—have broken down. The recommended path is to use new capital to optimize core financial health: repurchasing discounted STRC and/or bolstering cash reserves. This would repair the balance sheet, signal liquidity strength, support STRC's price, lower its yield, and potentially reopen the par-value issuance channel. The current STRC discount represents a low-cost capital opportunity to restart this positive cycle. Bitcoin reserve companies must be evaluated as banks, focusing on book value, leverage, and liquidity resilience.

Foresight News06/26 09:05
STRC Trading at Significant Discount, mNAV Falls Below Break-Even, Strategy's Valuation Logic Has Been Rewritten

Foresight News06/26 09:05

MicroStrategy Will Not Die in This Downturn: Reflexivity, STRC Anchoring Back to Par, and the Self-Rescue Logic of "Sell Stock, Not Bitcoin"

This article analyzes the recent sharp decline in Bitcoin and MicroStrategy (MSTR), framing it as a targeted "reflexivity" attack. The trigger was MSTR using its cash reserves to buy back convertible notes, raising market concerns about a liquidity crisis. The playbook follows George Soros's principle: market expectations can shape reality. Fears that MSTR might be forced to sell BTC caused panic selling, lowering BTC's price and worsening MSTR's financial ratios, thus reinforcing the negative narrative. The author argues that MSTR's Structured Convertible (STRC), while falling in price, is a floating-rate security that will eventually return to par value (100). The price drop reflects the market demanding a higher yield due to perceived risk, but as a floating-rate instrument, its coupon can adjust, naturally pulling the price back to par over time. This is crucial for MSTR's continued ability to raise funds. The core thesis is that MSTR's best move to counter the attack is to **issue new equity (sell shares)**, not sell its Bitcoin holdings. While selling BTC would solve the immediate cash crunch, it would destroy the company's core investment thesis and premium. It would dilute the BTC per share, likely erase the market premium over its net asset value (mNAV > 1), and worsen its debt-to-asset ratio. Issuing shares while mNAV is high (e.g., 1.25x) allows MSTR to raise cash for reserves without harming shareholder value or the "perpetual accumulation" narrative. It improves the debt ratio and reassures STRC holders, breaking the negative reflexivity cycle. In conclusion, while MSTR could survive this episode even by selling BTC, doing so would fundamentally alter its investment proposition and weaken it for future cycles. The optimal, value-preserving strategy is to sell equity to rebuild reserves and maintain the long-term growth flywheel.

marsbit06/09 03:39

MicroStrategy Will Not Die in This Downturn: Reflexivity, STRC Anchoring Back to Par, and the Self-Rescue Logic of "Sell Stock, Not Bitcoin"

marsbit06/09 03:39

活动图片