If you're active on-chain, you've probably encountered these awkward situations:
You receive some stablecoin in a new address, but can't send it out because a pop-up says you have no ETH to pay for gas; you want to swap tokens on a DEX, and it gets stuck; you withdraw USDC from an exchange only to realize you didn't prepare any gas.....
All these scenarios force you to first find a fiat on-ramp elsewhere or beg someone for some "water". This is arguably one of the classic newbie deterrents in the Crypto world.
Recently, Vitalik Buterin mentioned the progress of EIP-8141 (Frame Transactions), which once again brought a new vision into the spotlight: in the future, you could transfer assets directly even without ETH in your wallet. Gas could be deducted directly from USDC, or even some applications could cover the gas for you to attract users.
Once this news spread, it quickly evolved into a startling overstatement: "If ETH isn't even needed to use Ethereum in the future, what value does ETH have?"
The answer isn't that simple.
The asset users use to pay fees and the asset the Ethereum protocol ultimately uses to settle fees are actually two completely different things.
I. What Does Paying Gas Without ETH Actually Mean?
Let's start with a typical Ethereum transaction today.
For example, Frank has 1000 USDC in his wallet and wants to send 100 USDC to a friend. But if his wallet has no ETH, this transaction cannot be initiated.
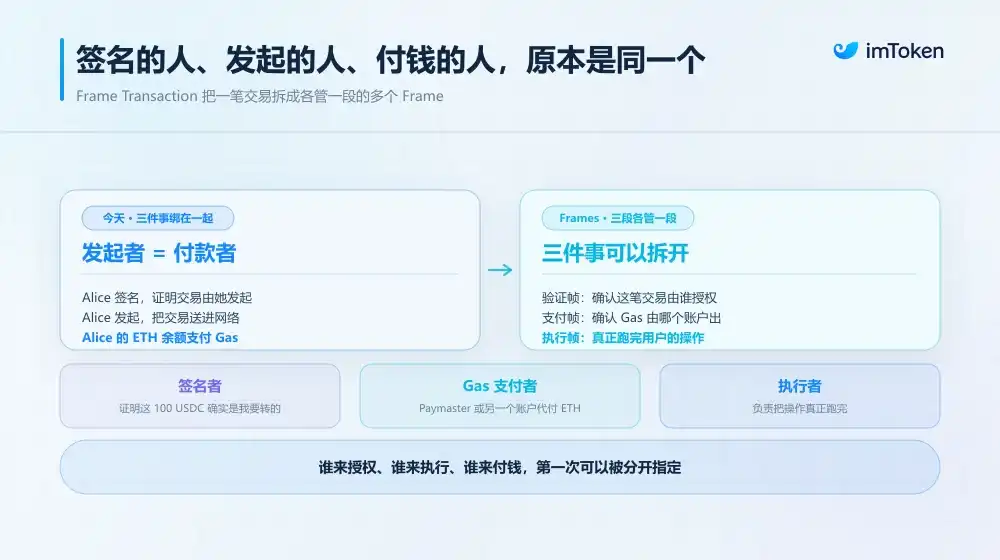
The reason is simple: the logic of current standard Ethereum accounts is very rigid. The person initiating the transaction is also the one responsible for paying the network gas—Frank signs, Frank initiates the transaction, Frank's ETH balance pays the gas. These three things are essentially tied together.
What EIP-8141 aims to do is separate them.
According to the current design, a Frame Transaction can be split into multiple different "Frames", responsible for verifying the transaction, confirming who pays the gas, and actually executing the user's operation, respectively.
Thus, in the future, when Frank makes a transfer, it could become: Frank still signs to prove "I indeed want to send this 100 USDC," but another Paymaster or account is responsible for providing ETH to pay the gas to the Ethereum network on Frank's behalf. Frank then pays a small amount of USDC to this Paymaster as a fee.
From Frank's perspective, all he might see is sending 100 USDC with a network fee of 0.1 USDC. Throughout the entire process, he might not even need to know what the ETH gas price is or prepare ETH in advance.
But from the perspective of the Ethereum protocol, things haven't become "Ethereum now accepts USDC as gas." It's just that someone in the background paid the gas with ETH for Frank and then settled with Frank using USDC.
The ERC-20 payment example given in the official EIP-8141 documentation has a similar structure, where a Sponsor is responsible for approving and covering the gas, and the user can transfer an ERC-20 Token to the Sponsor as a fee.
An analogy to real-world consumption makes it easier to understand.
When we use a Chinese Renminbi credit card in Japan, what the user perceives is "Renminbi deduction," while the merchant receives Japanese Yen. But this doesn't mean Japan's underlying settlement currency has therefore become Renminbi. The payment asset on the front end and the settlement asset on the back end can inherently be different things.
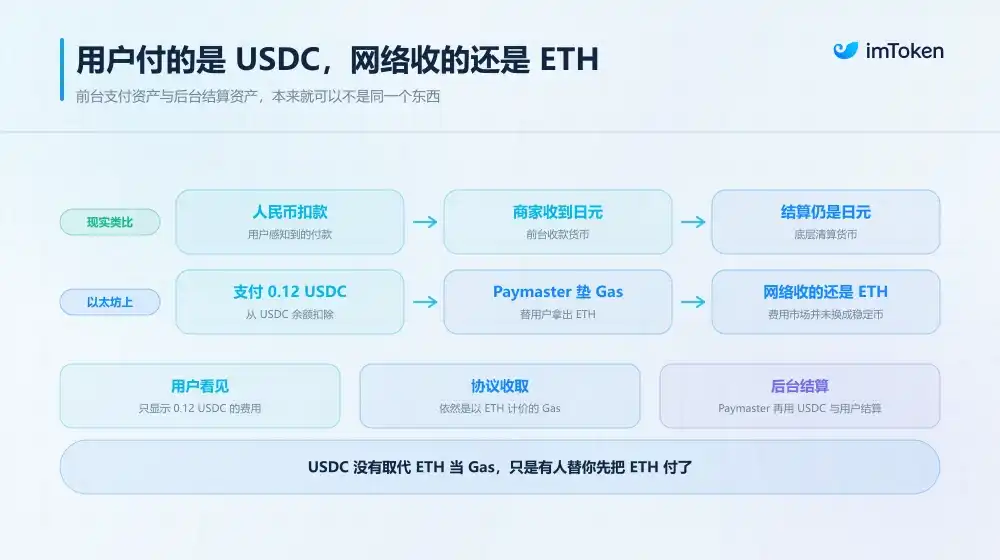
EIP-8141 is essentially doing a similar abstraction. Ultimately, users no longer need to personally hold ETH. Another account can pay the ETH gas on their behalf, and users can then complete fee settlement using assets like USDC.
The difference might seem like just a few words, but the implications for ETH are completely different.
II. Why Does Ethereum Insist on "Hiding" Gas?
In fact, the idea of "not needing to prepare ETH oneself" isn't entirely new.
Account Abstraction and Paymasters introduced by ERC-4337 already allow smart accounts to implement Gas Sponsorship. Applications can pay fees for users, or allow users to bear fees using stablecoins.
It's just that while ERC-4337 made it possible, it primarily added a set of infrastructure like UserOperation, Bundler, EntryPoint, and Paymaster outside the core protocol. EIP-8141, however, attempts to embed such capabilities more natively into the Ethereum transaction structure itself.
Ultimately, the core goal is to solve a problem that should have been addressed long ago: why should ordinary users have to understand what Gas is?
In real life, when you transfer 200 RMB to a friend on WeChat, WeChat would never pop up asking you to "first go to another platform to buy 2 RMB worth of settlement tokens."
But Crypto has precisely been tormenting people like this.
On Ethereum, you need to prepare ETH; on Solana, you have to exchange for SOL; go to BNB Chain, and you need to stock up on BNB. Even switching to a new L2, the first reaction is to check if you have starting funds in your wallet. Veterans might spend two minutes bridging assets and get it done, but for outsiders, this is a chasm that can make them close the webpage and leave.
Beyond hiding Gas, Frame Transactions can also conveniently solve several persistent headaches.
For instance, when trading a new token on a DEX today, you first need to click Approve for authorization, then click Swap, with the wallet popping up for confirmation twice. If the subsequent Swap fails, the earlier authorization remains active on-chain long-term, posing a theft risk.
But with Frames, these two actions could be bundled into one atomic batch: if the Swap fails, the previous authorization automatically rolls back as well, leaving everything clean.
This opens up a larger vision: in the future, who authorizes, who executes, who pays, and how verification is done can all be separated and recombined.
III. Is This Bullish or Bearish for ETH?
This is also where the current discussion most easily polarizes.
One argument is, "If ETH isn't needed to pay gas in the future, ETH has no value." The other is, "Lower barriers for users will lead to explosive transaction growth, making it super bullish for ETH."
For major architectural reforms involving the user experience of the underlying protocol, it's still difficult to draw definitive conclusions. However, one thing is certain: EIP-8141 does not remove ETH's role as the underlying Gas and fee settlement asset for Ethereum.
Users may be unaware of ETH, but the Paymasters, applications, or other accounts responsible for paying on their behalf still need the ability to handle network fees priced in ETH. The existing EIP-1559 fee market hasn't been replaced by stablecoins because of Frames.
What changes is the location of ETH demand.
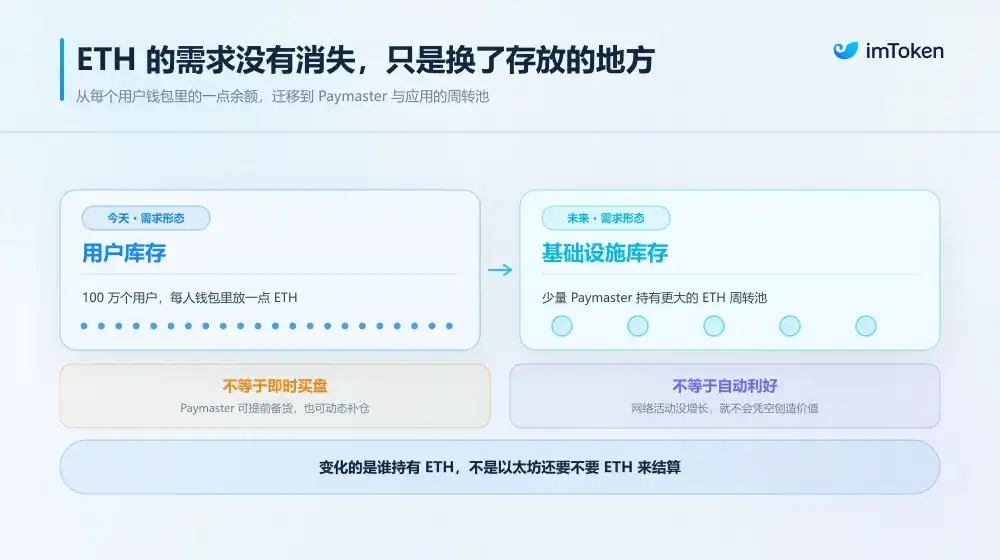
Today, it might be 1 million users, each keeping a little ETH in their wallet for gas. In the future, it could become a smaller number of Paymasters, wallet service providers, and applications holding larger ETH working balances, then handling gas collectively for a large number of ordinary users.
Of course, don't naively think that "for every stablecoin a user pays, someone will immediately go to the secondary market to buy an equivalent amount of ETH at the market price." Agents have their own inventory management and hedging strategies. This hardly translates directly into the instant buy-side pressure that retail investors might fantasize about.
Paymasters can prepare inventory in advance, dynamically replenish stock, or adopt other capital management methods. Therefore, based solely on "gas can be paid with stablecoins in the future," it's difficult to directly deduce how much new buy-side demand this will create for ETH.
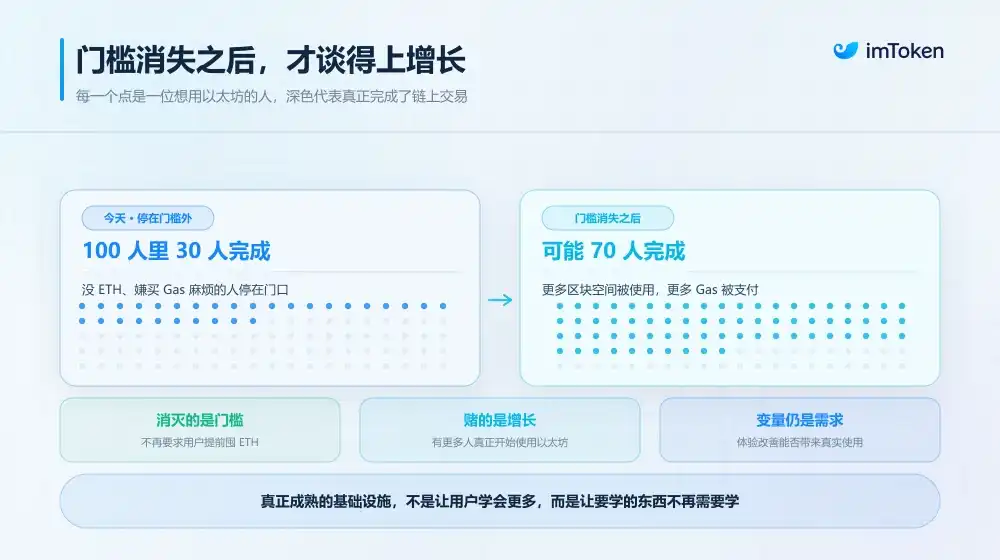
The real determinant hinges on one logic: After the user experience is optimized, does it ultimately bring more genuine demand for using Ethereum? Can it truly make the ecosystem bigger?
Doing some simple math makes it intuitive:
- If in the past, 100 people intended to enter, but 70 gave up halfway due to the hassle of buying gas, calculating Gwei, and bridging, with only 30 completing transactions;
- If in the future, wallets swallow all these complexities into the background, allowing 80 people to smoothly complete their transactions—even if they don't hold a single bit of ETH—the network's actual ETH consumption and burn would be far greater than before.
Conversely, if the entire ecosystem doesn't bring incremental activity, merely shifting from "paying yourself" to "having someone else pay," then indeed no new incremental value would be generated.
In Conclusion
From the author's perspective, it weakens the notion that "every user must stockpile a little ETH in advance to use Ethereum," but it bets that once this barrier disappears, more people will genuinely start using Ethereum.
For ordinary users, there's certainly no need to change their habits based on this EIP yet. However, from the perspective of wallet development, the direction it points towards is already clear.
A good wallet in the future may increasingly avoid requiring users to first understand Gas. Users should be responsible for deciding where assets should go and what operations to perform; wallets should be responsible for informing them of the risks and the final cost. As for which account to use for payment, whether to bill in ETH or stablecoins, or whether available Gas Sponsors exist—these complex protocol details should gradually be hidden in the background.
Truly mature infrastructure often evolves this way.