Author: Glassnode
Compiled by: Jiahuan, ChainCatcher
Core Summary
Bitcoin has rebounded to the edge of the resistance zone. Data on cost basis, liquidation maps, and ETF breakeven lines all point to the same resistance level. However, as the price approaches this zone, selling pressure is at its lowest level this year. Current actual inflation data is at a two-year low, while yields are at a cycle high. From a macro perspective, there are clearly more reasons not to raise interest rates than to raise them.
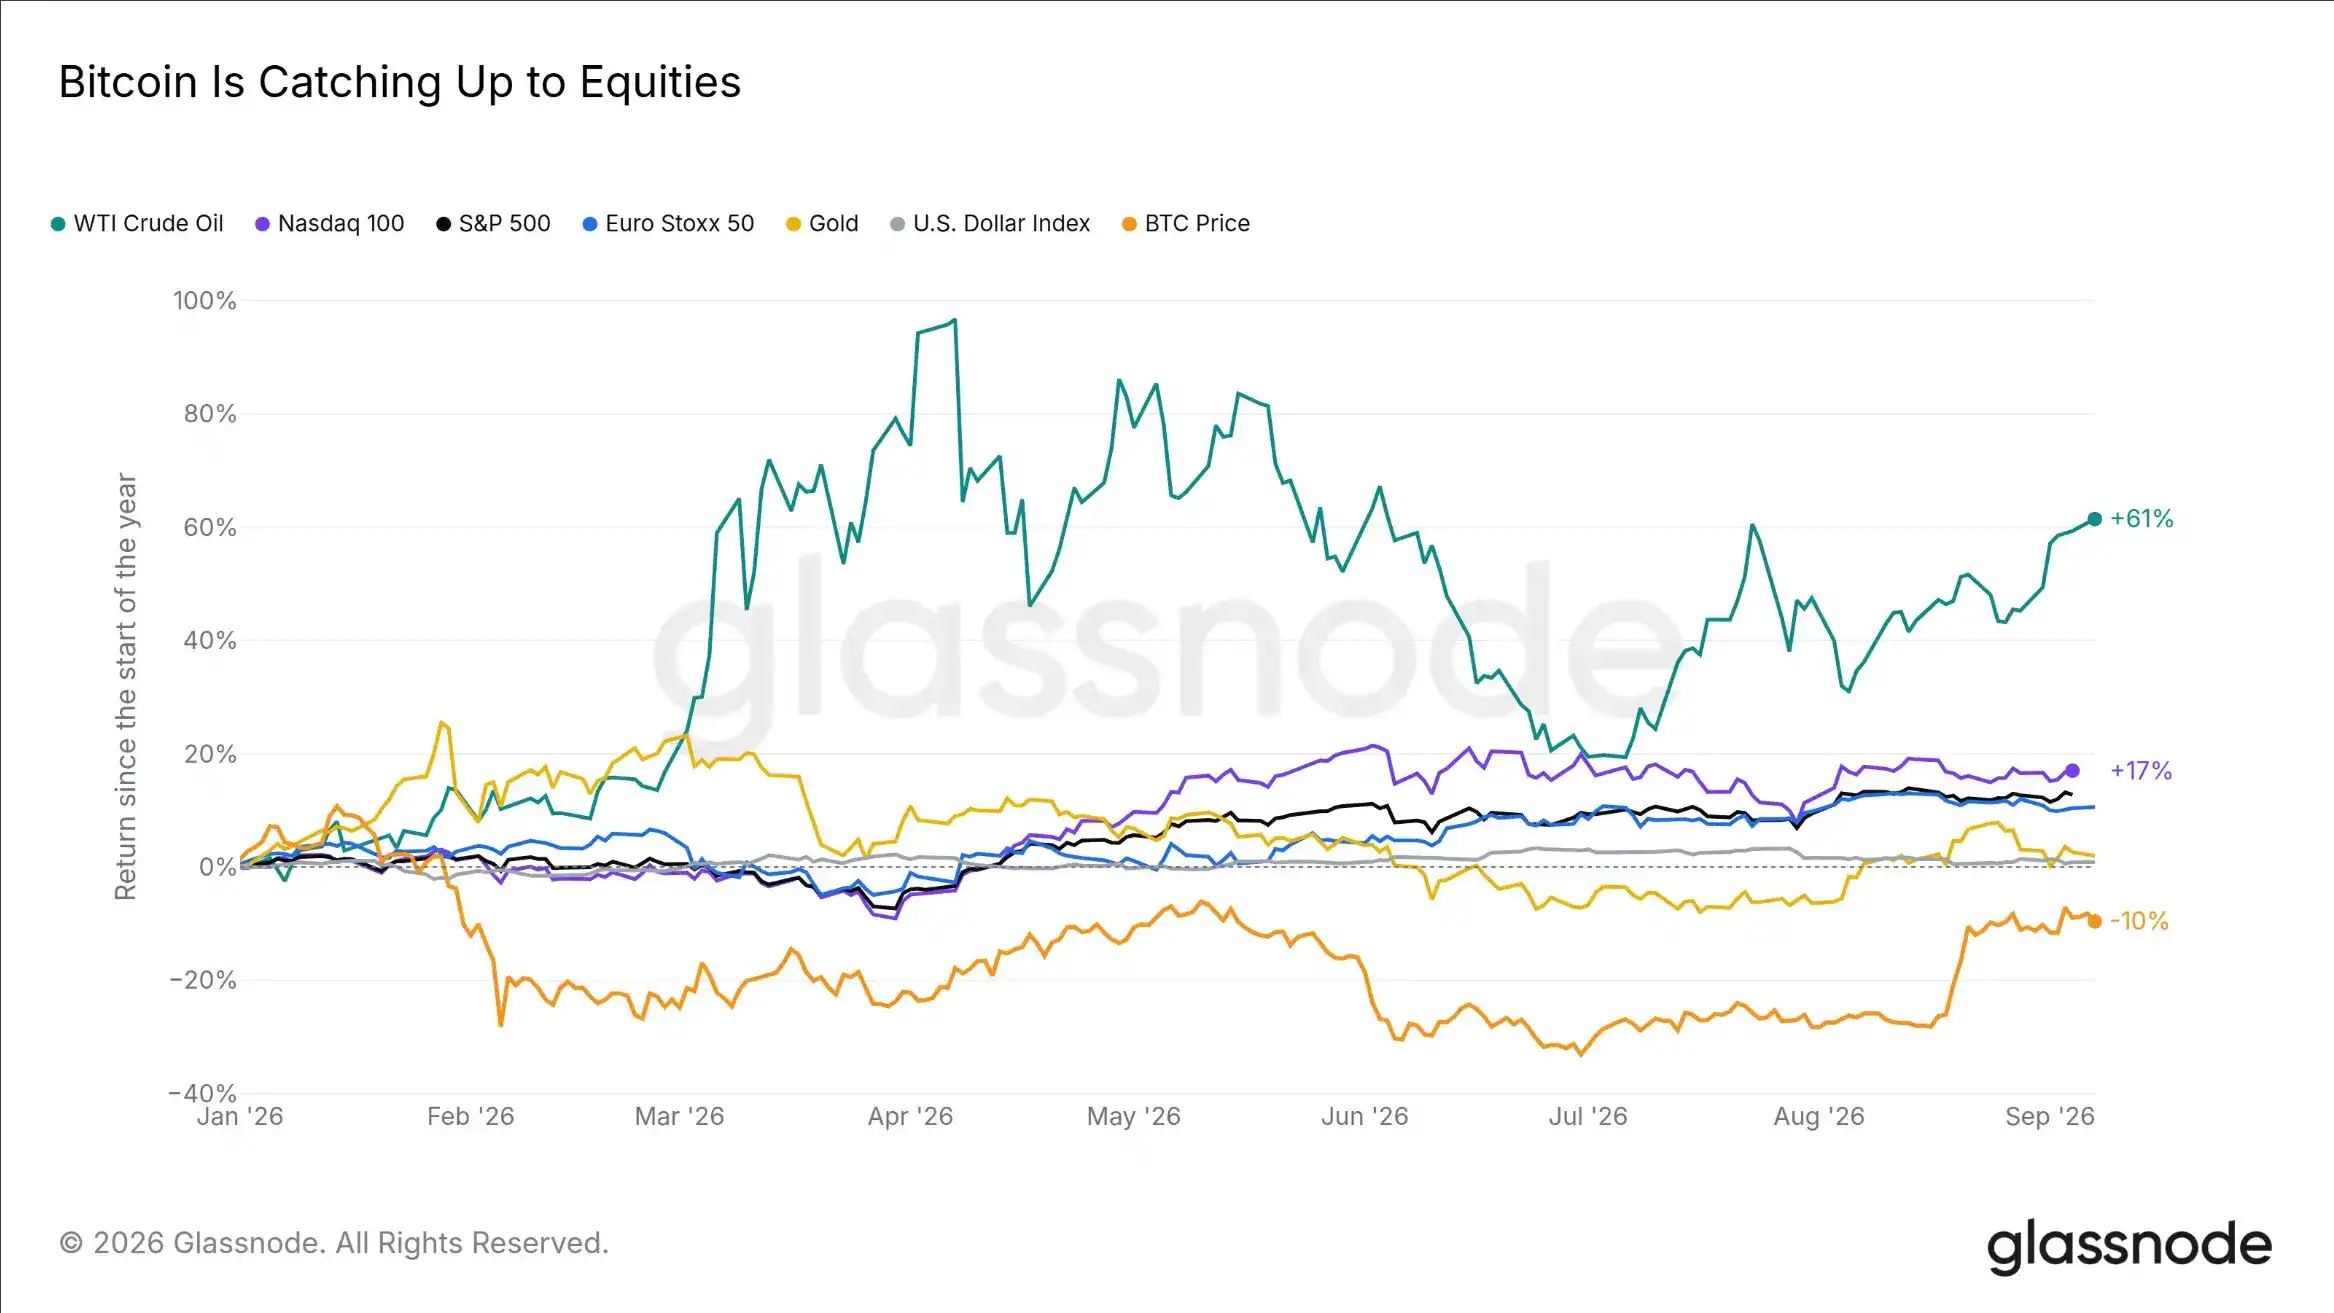
- Bitcoin has risen 23% over the past 21 trading days, while the stock market has essentially been flat over the same period, but is still down 10% year-to-date.
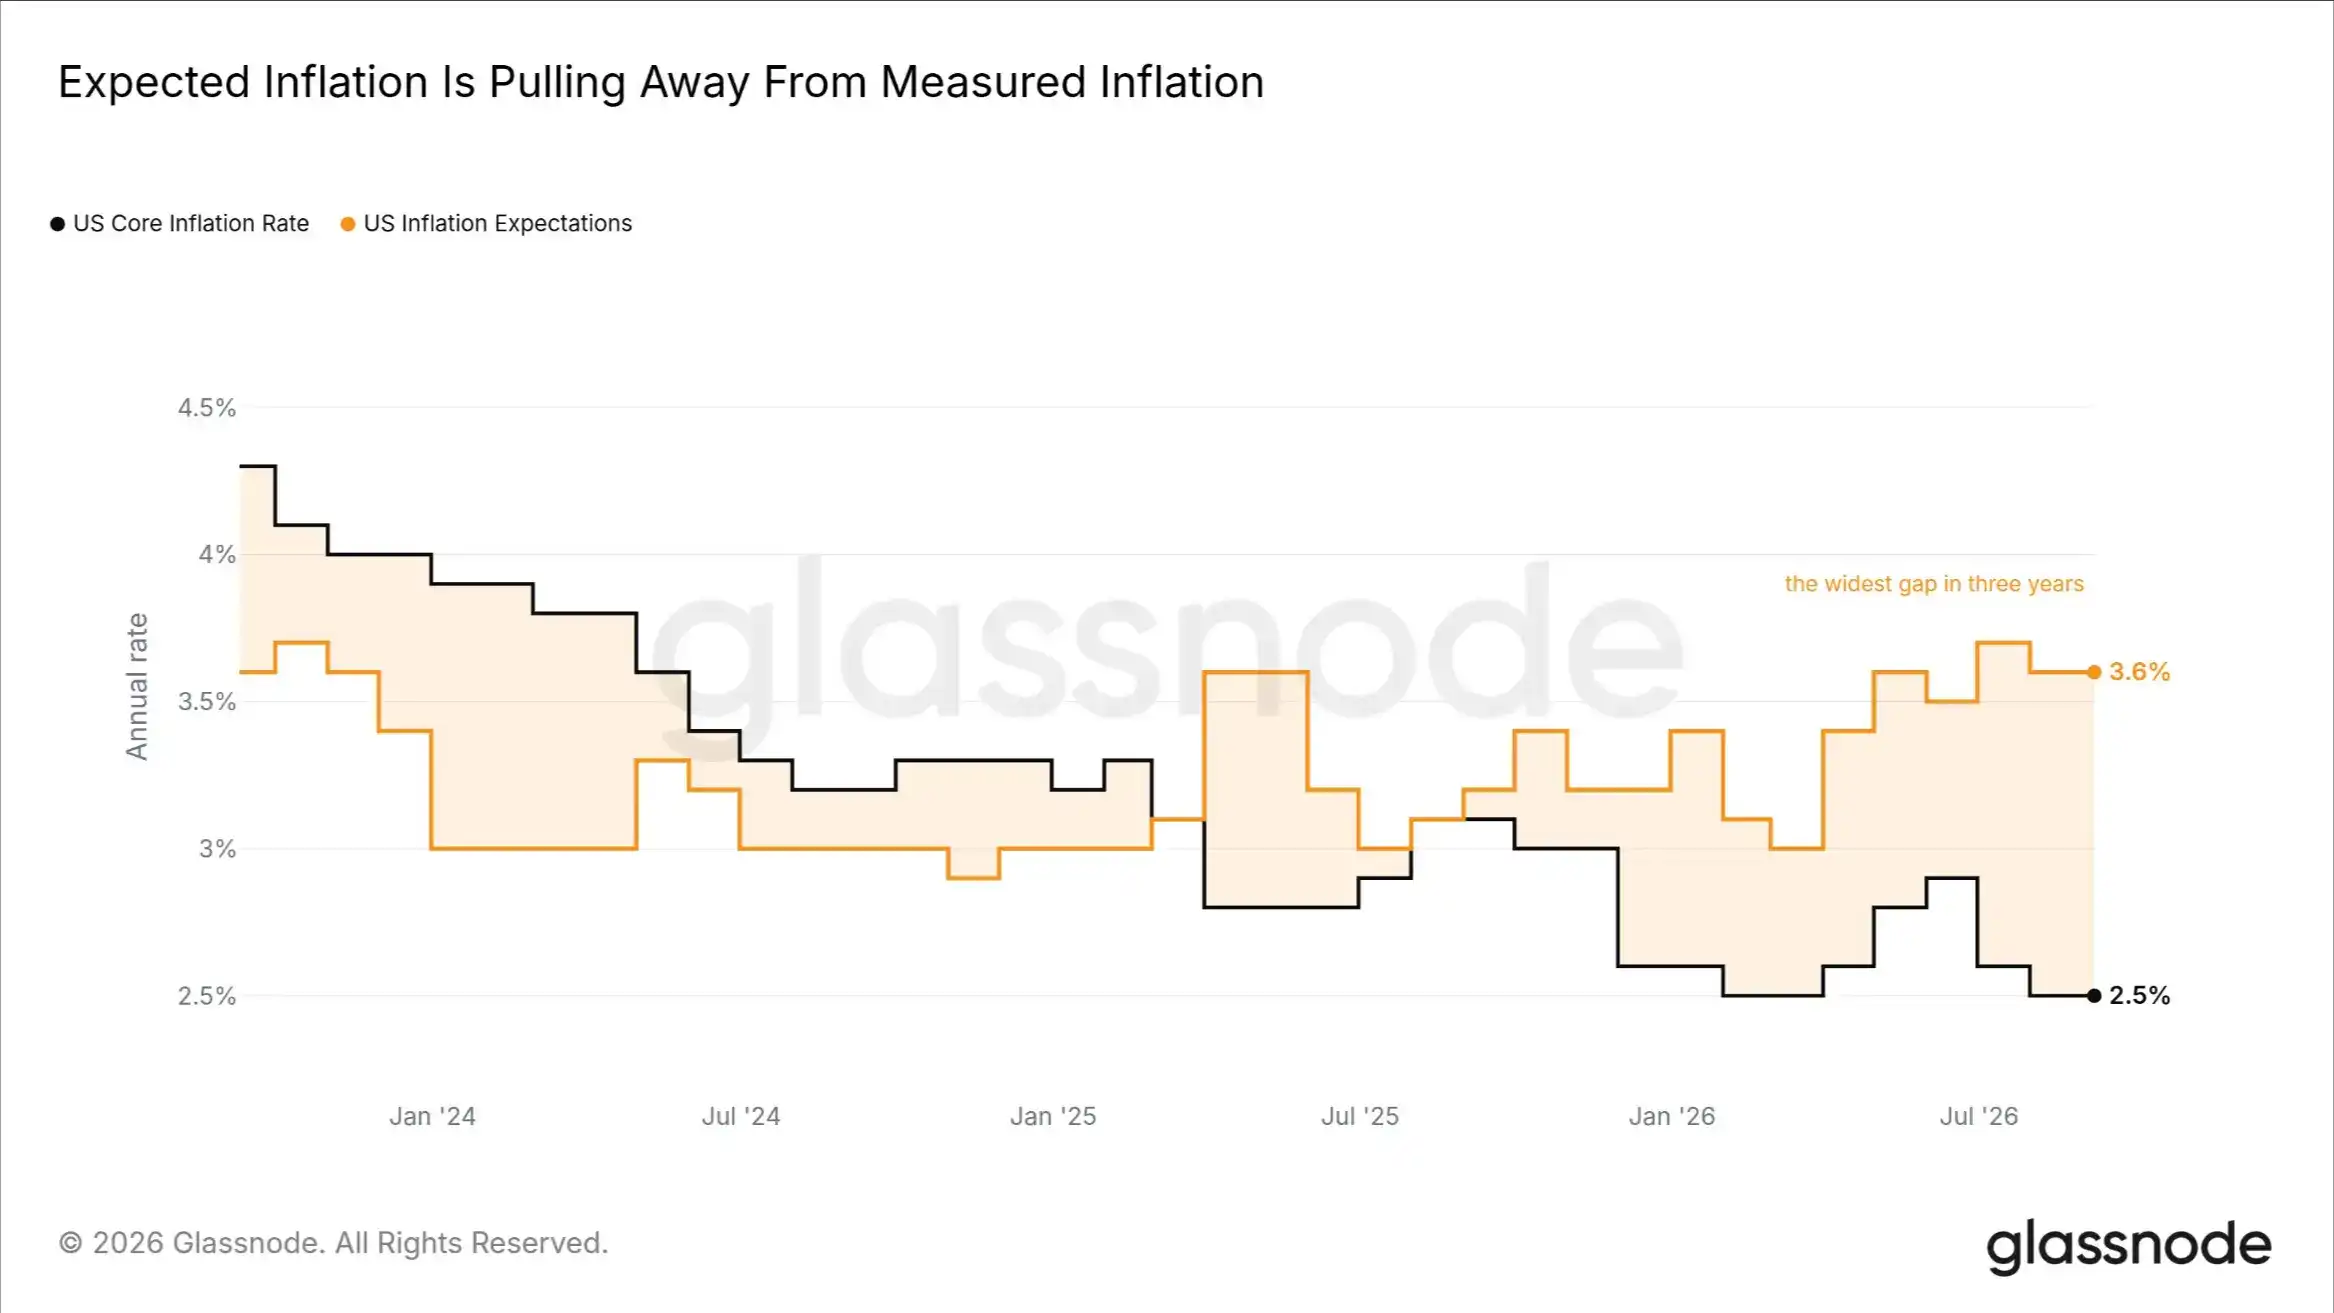
- Core inflation has fallen to a two-year low of 2.5%, while inflation expectations remain at 3.6%, the widest gap between the two in three years.
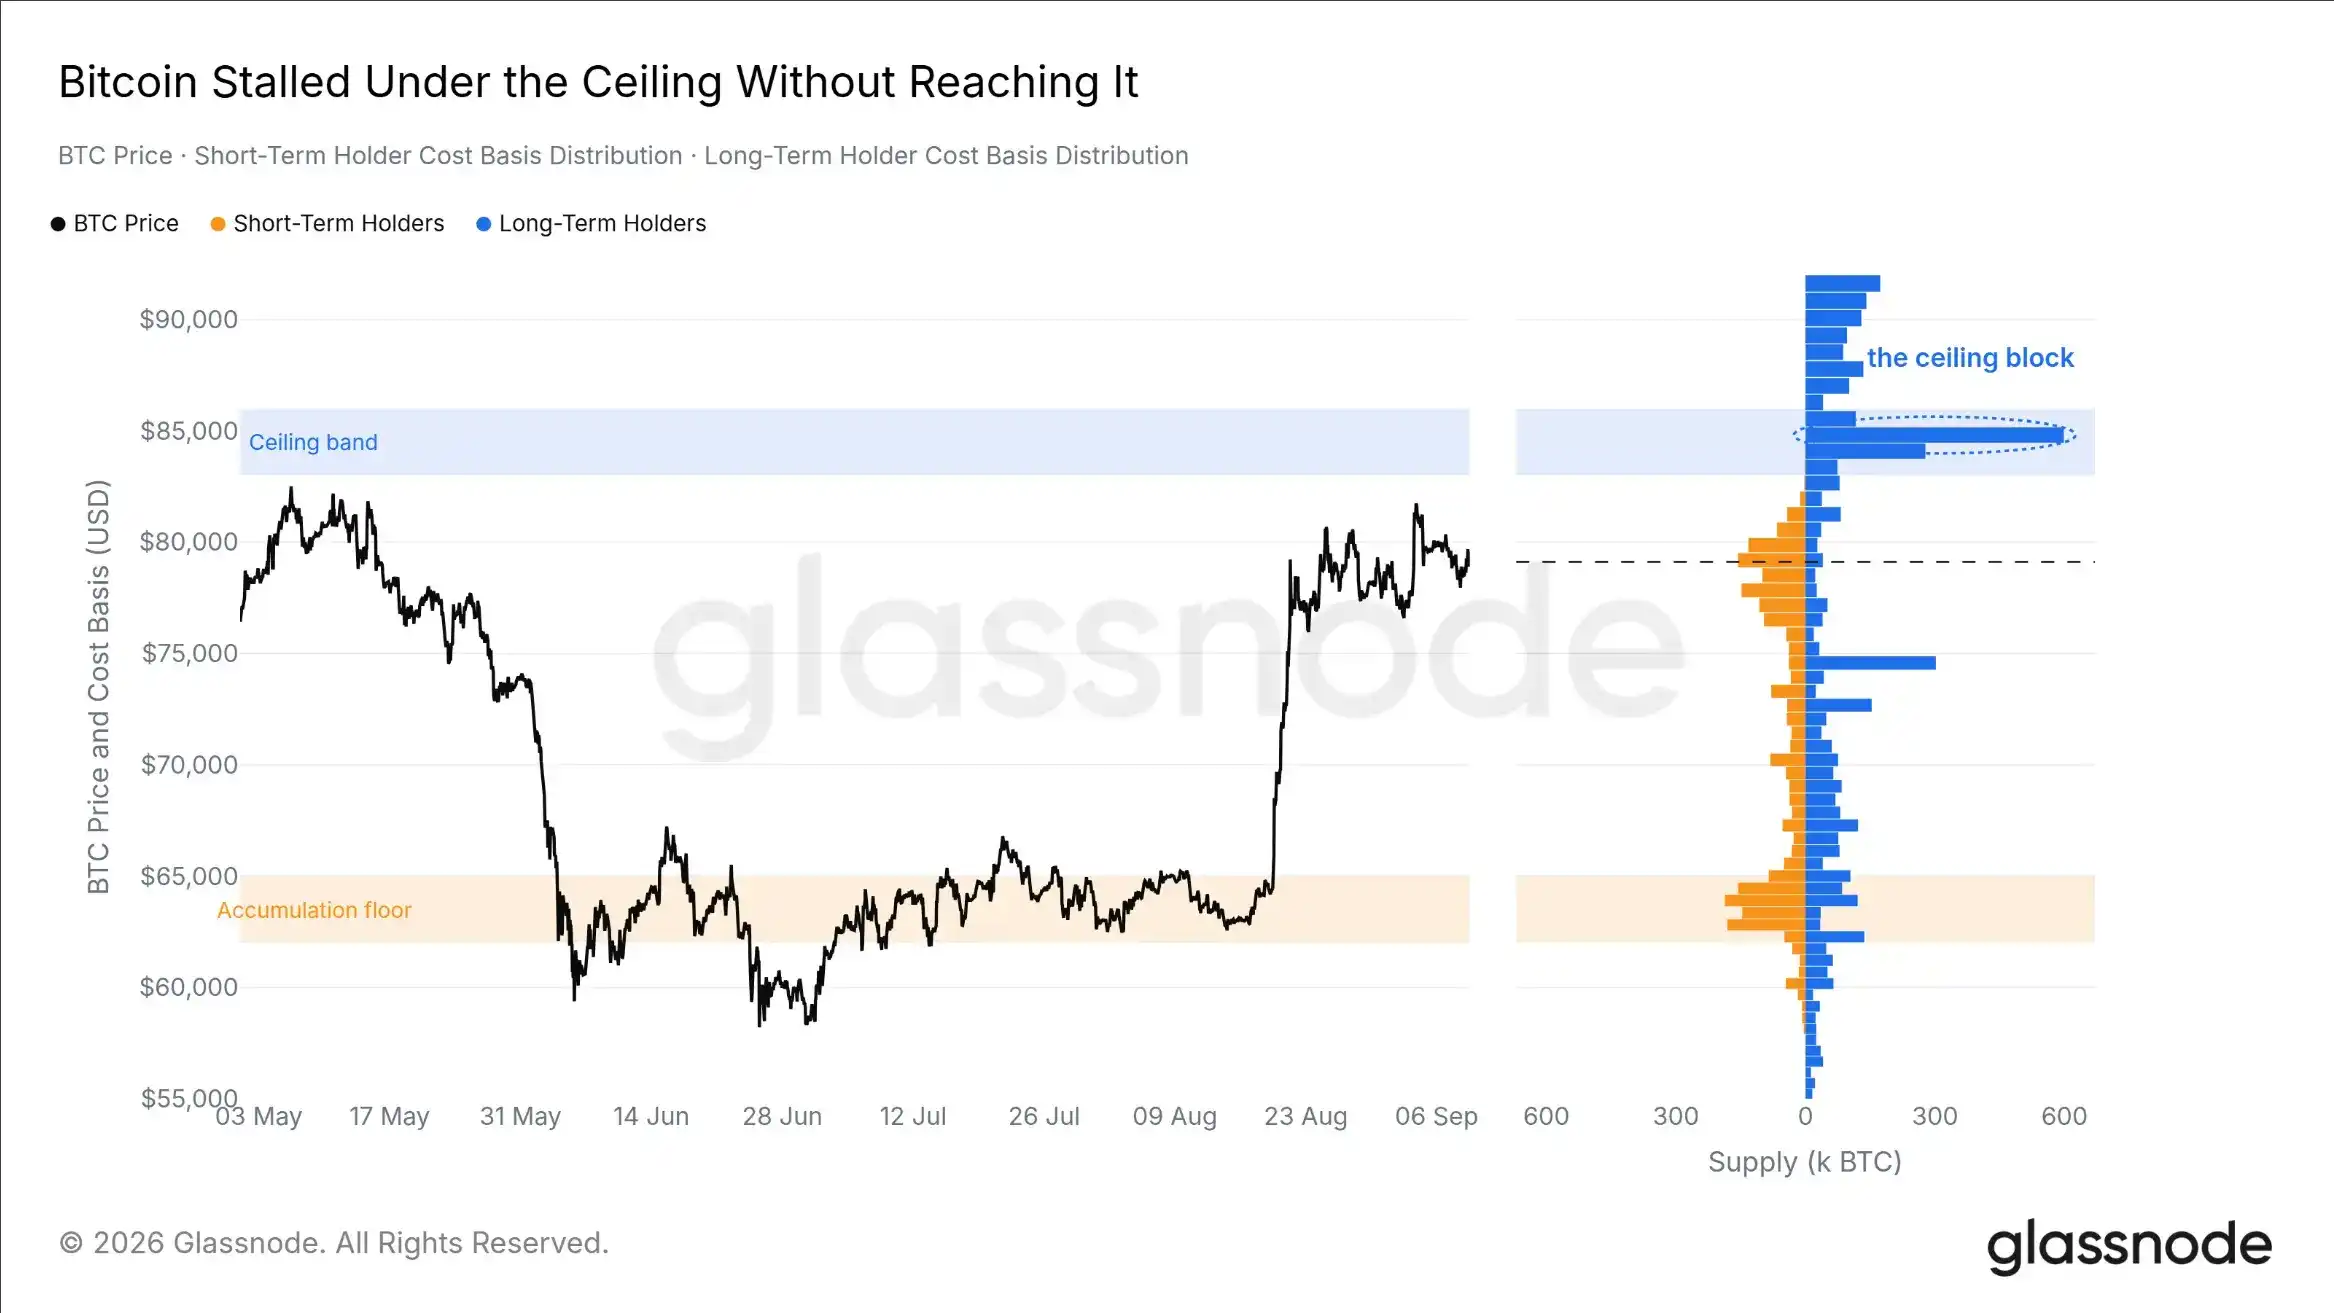
- The cost basis of long-term holders, liquidation distribution, and ETF breakeven lines all point to resistance in the $83,000 to $86,000 range. The spot price once came within 1.5% of the lower bound of this range.
- As Bitcoin approached the range high, the selling rate was less than half of the August high, and long-term holders did not participate in selling during this round of price increase.
- Bottom indicators have formed a significant resonance for several months and have largely exited the extreme weakness zone. Altcoins have not taken market share from Bitcoin as they did before previous cycle tops.
Bitcoin, Lagging Since the Start of the Year, Is Catching Up
Recovering from the Bottom
Over the past 21 trading days, Bitcoin has risen 23%, while the S&P 500 and Nasdaq 100 indices have remained largely flat, and the Euro Stoxx 50 index has seen a slight decline. Among the seven asset classes we track, Bitcoin has been the best performer in this period.
However, looking at the year-to-date performance, the situation is reversed. Bitcoin is still down 10% from the start of the year, while the S&P 500 is up 13%. Crude oil, the best performer this year, is far ahead of both.
Bitcoin was at the bottom of this performance chart for the entire summer and has only recently begun to narrow the gap with other assets. The strong performance over the past month has only recovered part of the decline from the first half of the year.
Market Expectations Running Ahead of Data
Bitcoin's rebound has occurred in an overall still tight bond market environment. The US 10-year Treasury yield closed at 4.8%, in line with its two-year high; the 2-year Treasury yield is around 4.38%, about 63 basis points above the federal funds target rate of 3.75%. The bond market is betting that monetary policy may tighten further.
However, actual inflation data does not support this judgment.
The US core inflation rate has fallen to 2.5%, hitting a new two-year low, while US inflation expectations remain at 3.6%. The gap between the two has reached a new three-year high.
With core inflation cooling and Treasury yields at cycle highs, it becomes increasingly difficult for the Federal Reserve to justify rate hikes. The CPI data for August released on September 11, 2026, and the FOMC interest rate decision on September 16 will directly test this contradiction.
If the core inflation rate moves back toward the 3.6% inflation expectation, the argument for further tightening will strengthen. If core inflation continues to remain at its current low level, it will suggest that the rise in bond yields may have already outpaced the economic data.
Resistance Points to the Same Zone from Multiple Angles
Price Stalls Below Resistance Zone
Last week's report positioned Bitcoin's upper resistance zone between $83,000 and $86,000. This rebound has tested this judgment but has not yet truly touched the zone.
On September 3, 2026, Bitcoin's spot price hit a new high above August's level but ultimately stopped 1.5% below the lower bound of the resistance zone, subsequently trading in a narrow range below $80,000.
The long-term holder cost basis distribution explains why this resistance zone is important.
Approximately 1.07 million BTC have a cost basis between $83,000 and $86,000, the vast majority of which belong to long-term holders, with the densest cost zone concentrated around $85,000. These coins have barely moved in the past 30 days.
What has really changed is the supply structure below. The coins in the $76,000 to $82,000 range are mainly held by recent buyers, and their number has been increasing; the accumulated coins in the $62,000 to $65,000 range have decreased, indicating that some BTC bought at this level earlier have changed hands.
The market has rebuilt support below the spot price, but the upper resistance zone remains undigested.
Liquidation Distribution Also Points to the Same Resistance Zone
The derivatives market gives the same answer.
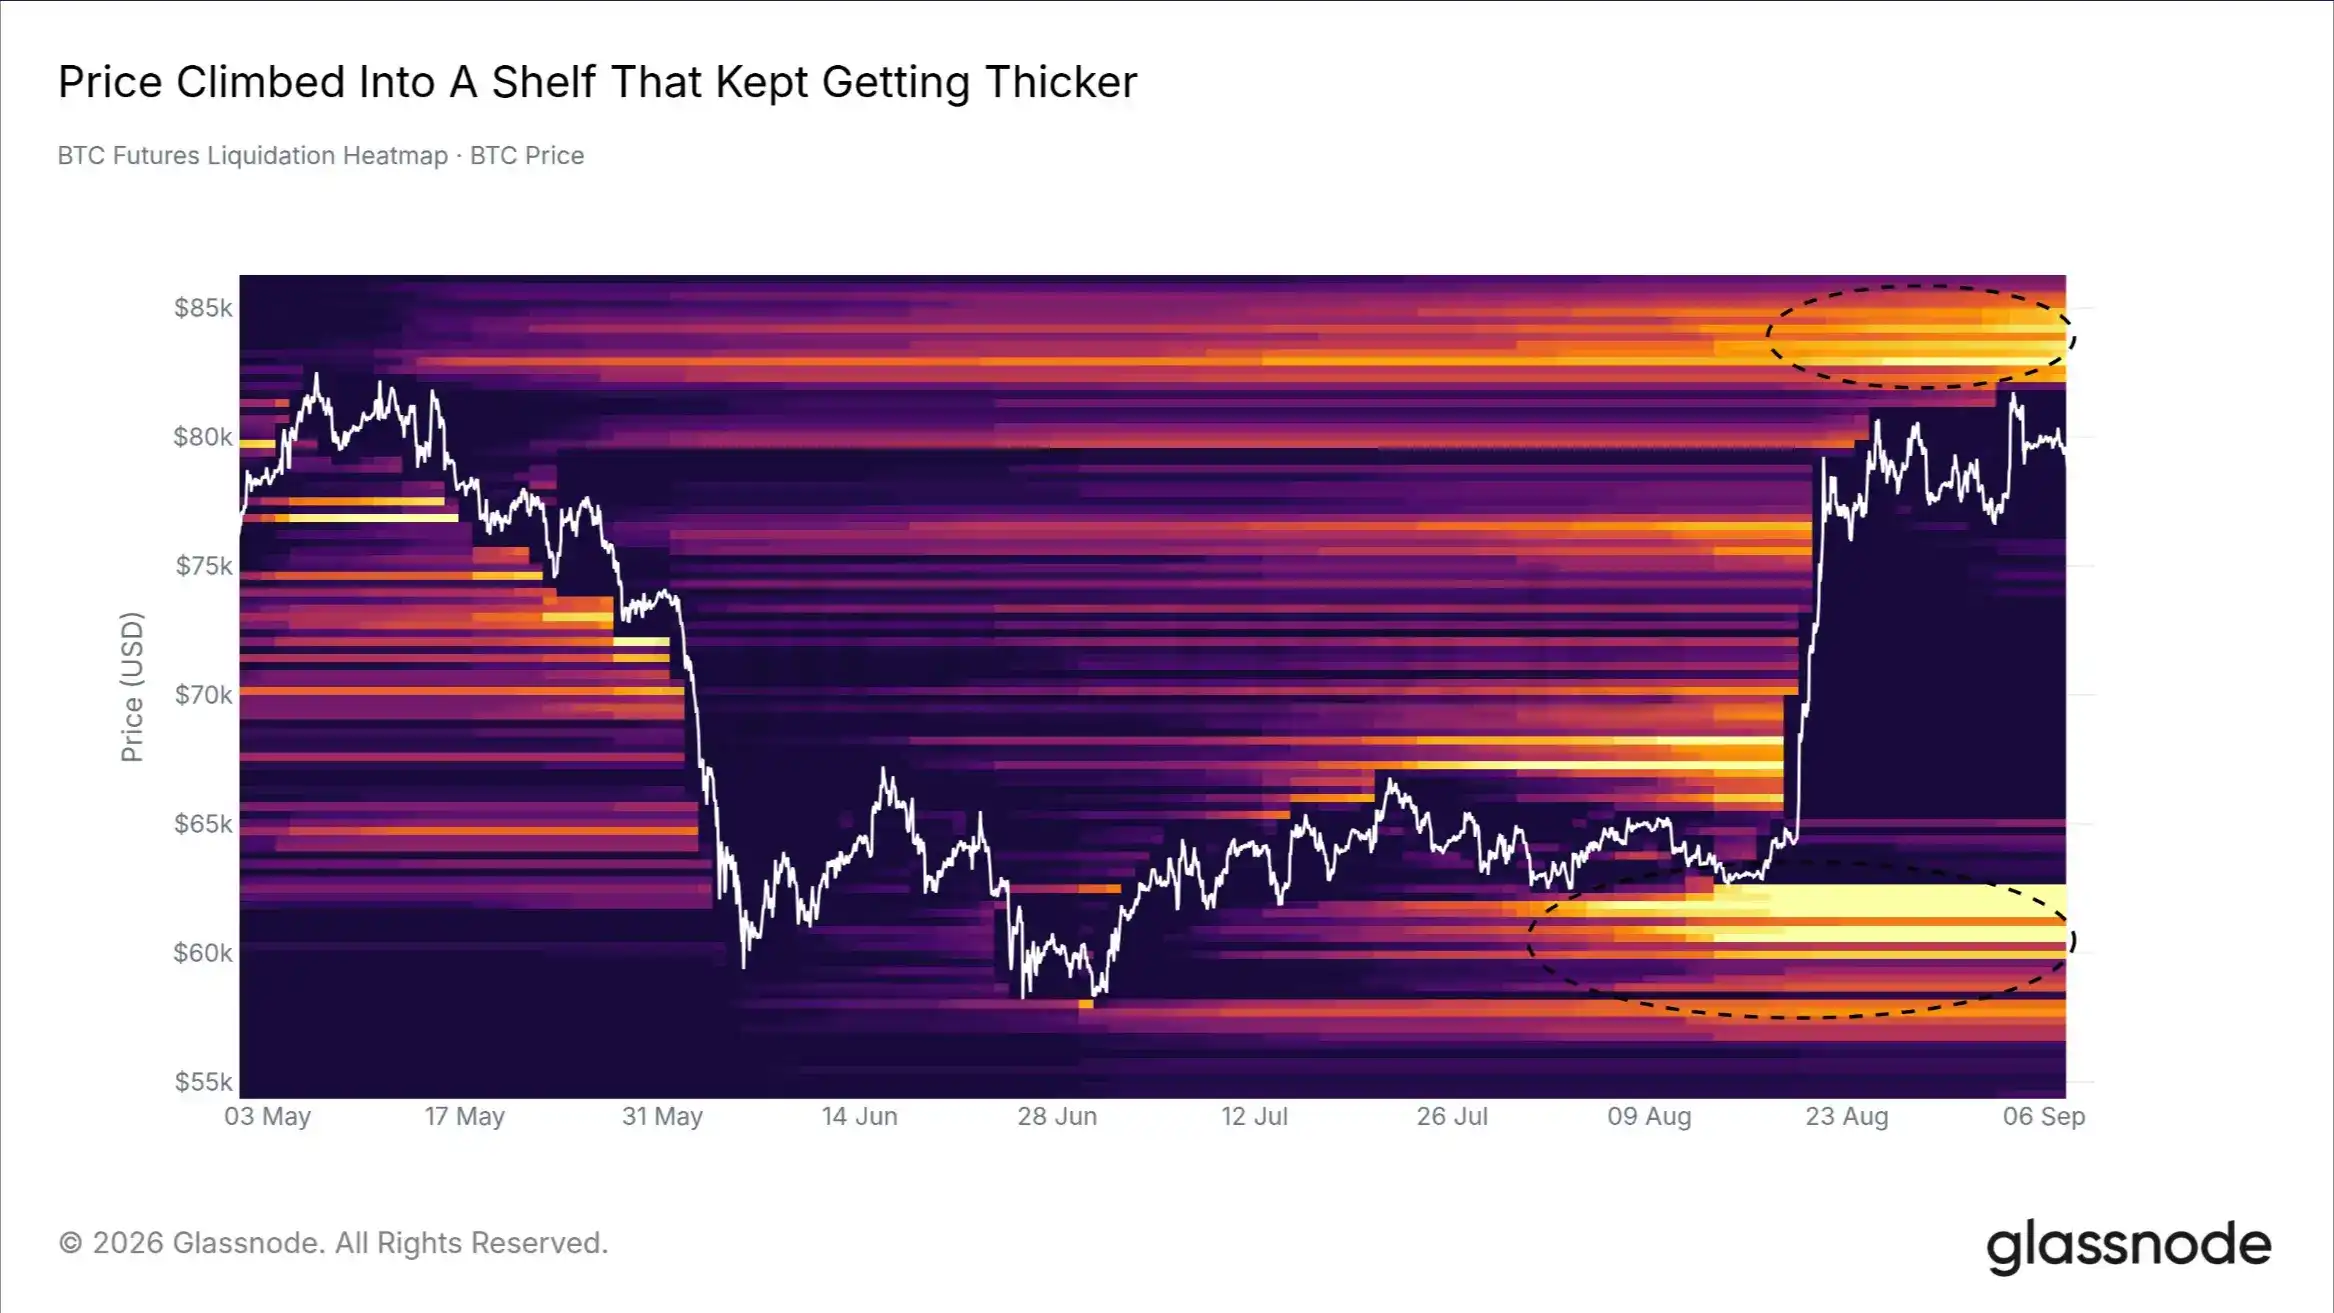
Looking at the Bitcoin futures liquidation heatmap, the short liquidation zone between $82,000 and $86,000 has expanded by 21% since the short squeeze on August 19; meanwhile, the overall size of the liquidation map has shrunk by about one-third.
Currently, the $82,000 to $86,000 range contains one of the largest concentration of liquidations since the model began recording.
The price rose exactly into a growing short liquidation zone and ultimately stalled below it. Below the current price, the long liquidation zone between $60,000 and $63,000 still exists, continuing to define the market range from below.
If the price sustainably breaks above $86,000, it will trigger the most concentrated short liquidation liquidity in the market; if it falls below $63,000, it may begin to impact long positions below.
Institutional Breakeven Lines Are Also Near $86,000
A third independent indicator also points to the same level.
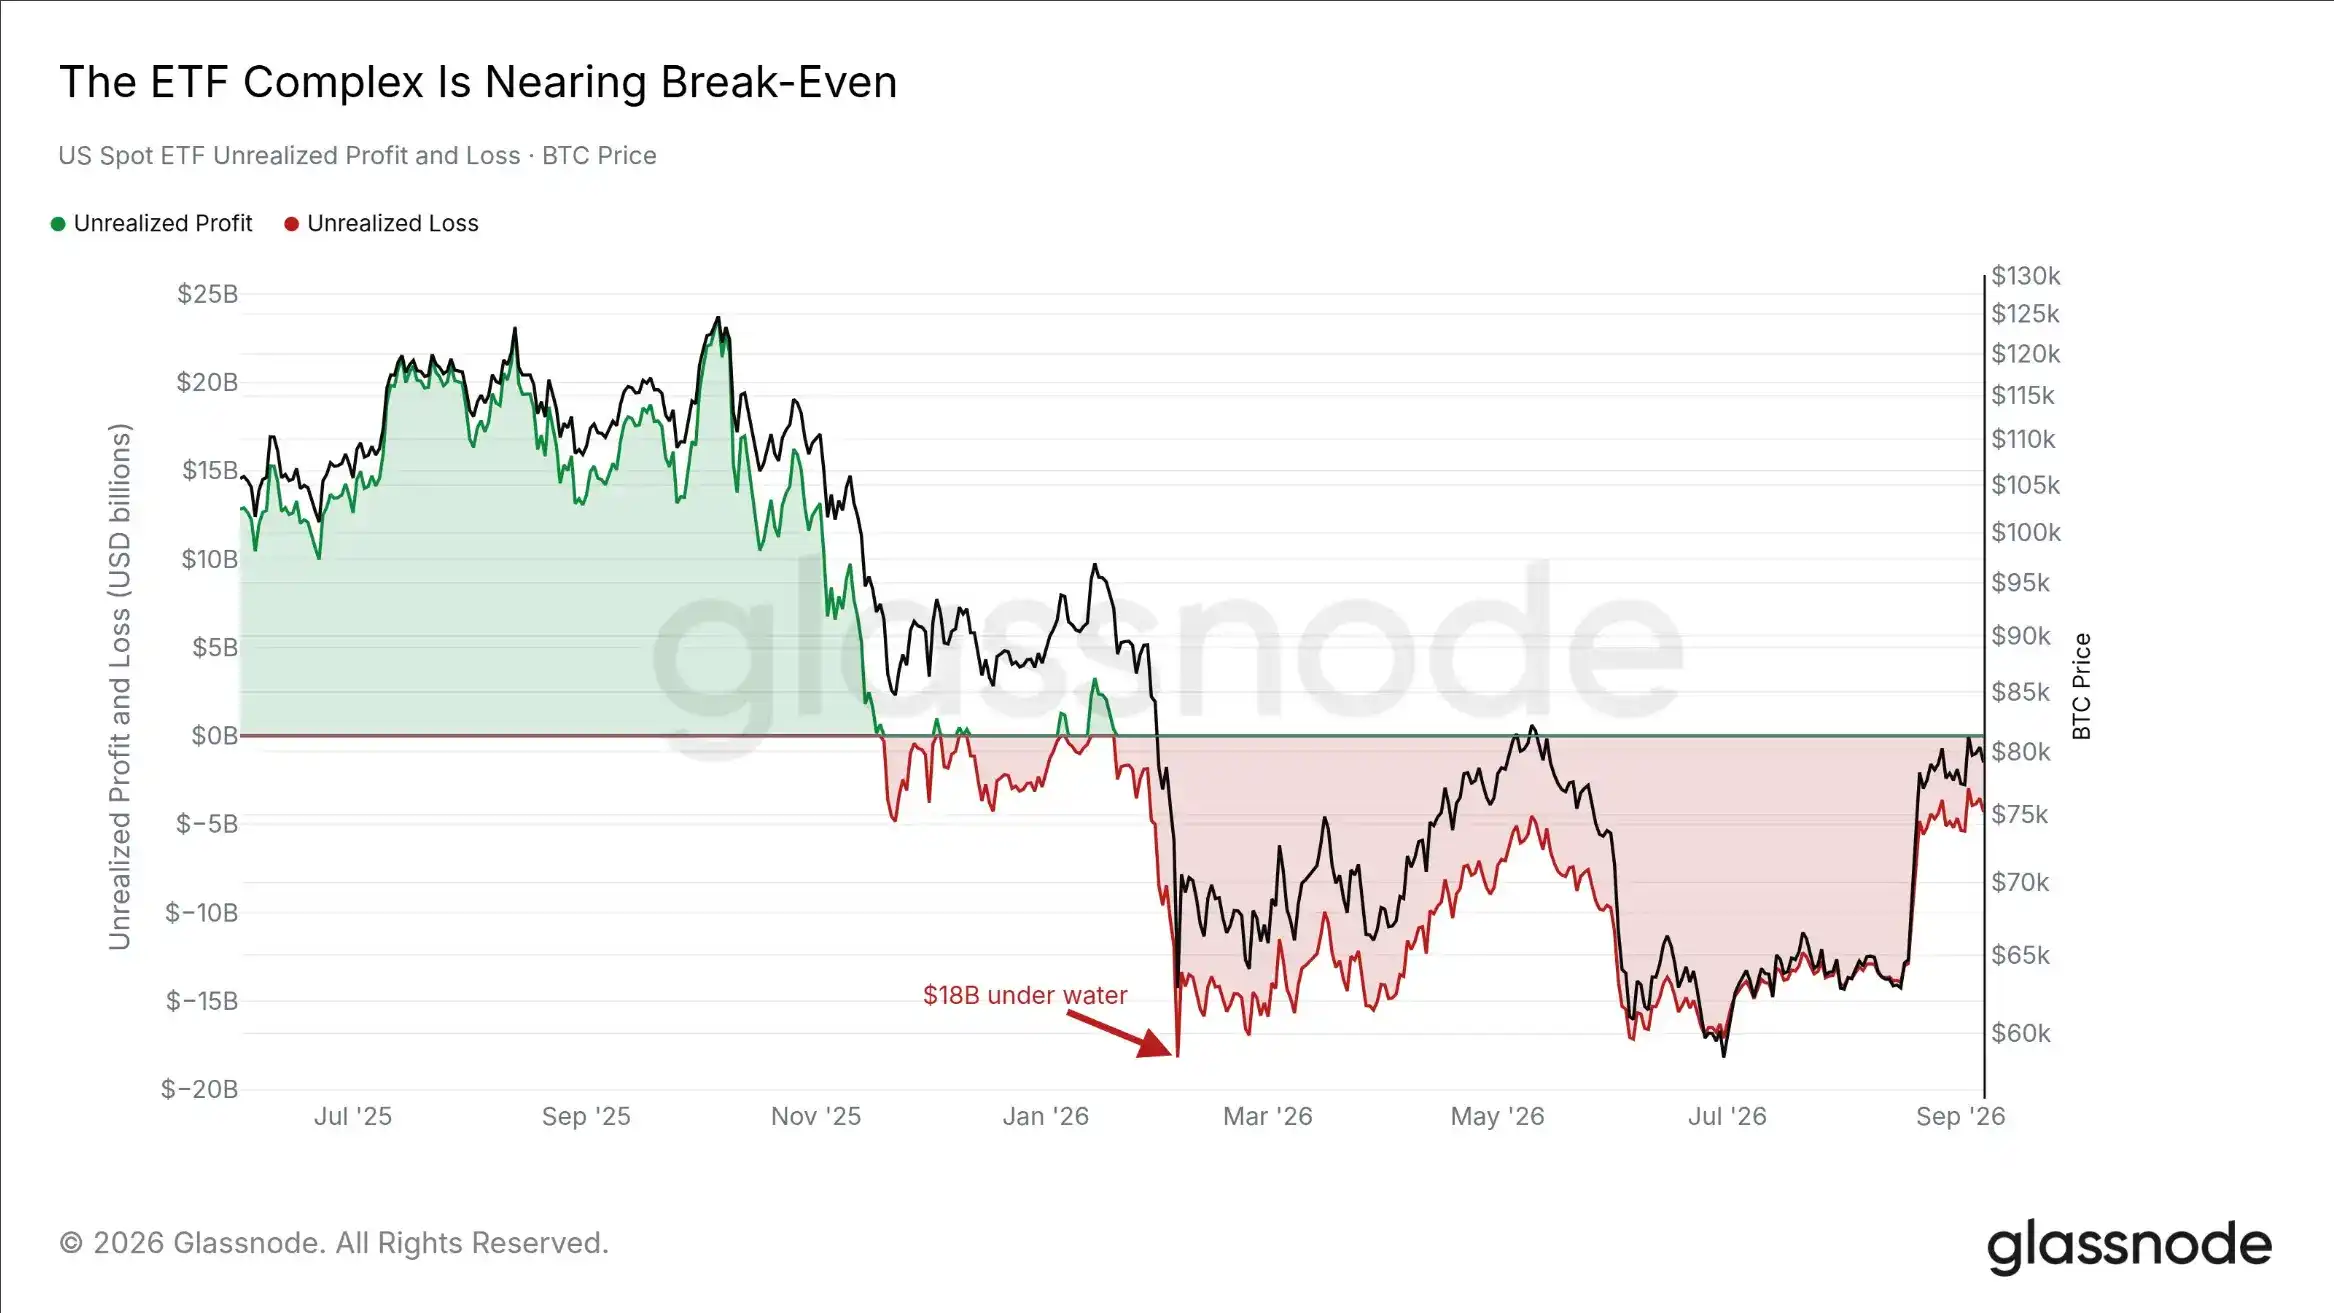
According to US spot ETF holdings data, calculated based on the BTC holding cost corresponding to the shares issued since the ETF's inception, its breakeven point is approximately $86,000.
Over the past 228 trading days, the BTC holdings corresponding to this ETF have remained below the breakeven line. The book loss reached a low of about $18 billion on February 5, 2026; as Bitcoin rebounded, the loss has narrowed to about $3.9 billion. This is the closest the ETF portfolio has been to breakeven since January.
The corporate treasury breakeven point is approximately $80,500, slightly below the current price.
All five cost basis models we track are currently above the Bitcoin spot price, ranging from the True Market Mean of $76,600 to the ETF breakeven point of $86,000.
The upper resistance is not a single technical line but a set of real cost basis intervals. If Bitcoin reclaims $86,000, the largest institutional holders will, for the first time this year, return to an overall profitable state.
Selling Power Is Weakening
The Closer to Resistance, the More Limited the Selling Pressure
As Bitcoin moves closer to the resistance zone, the market has not seen a significant increase in new supply.
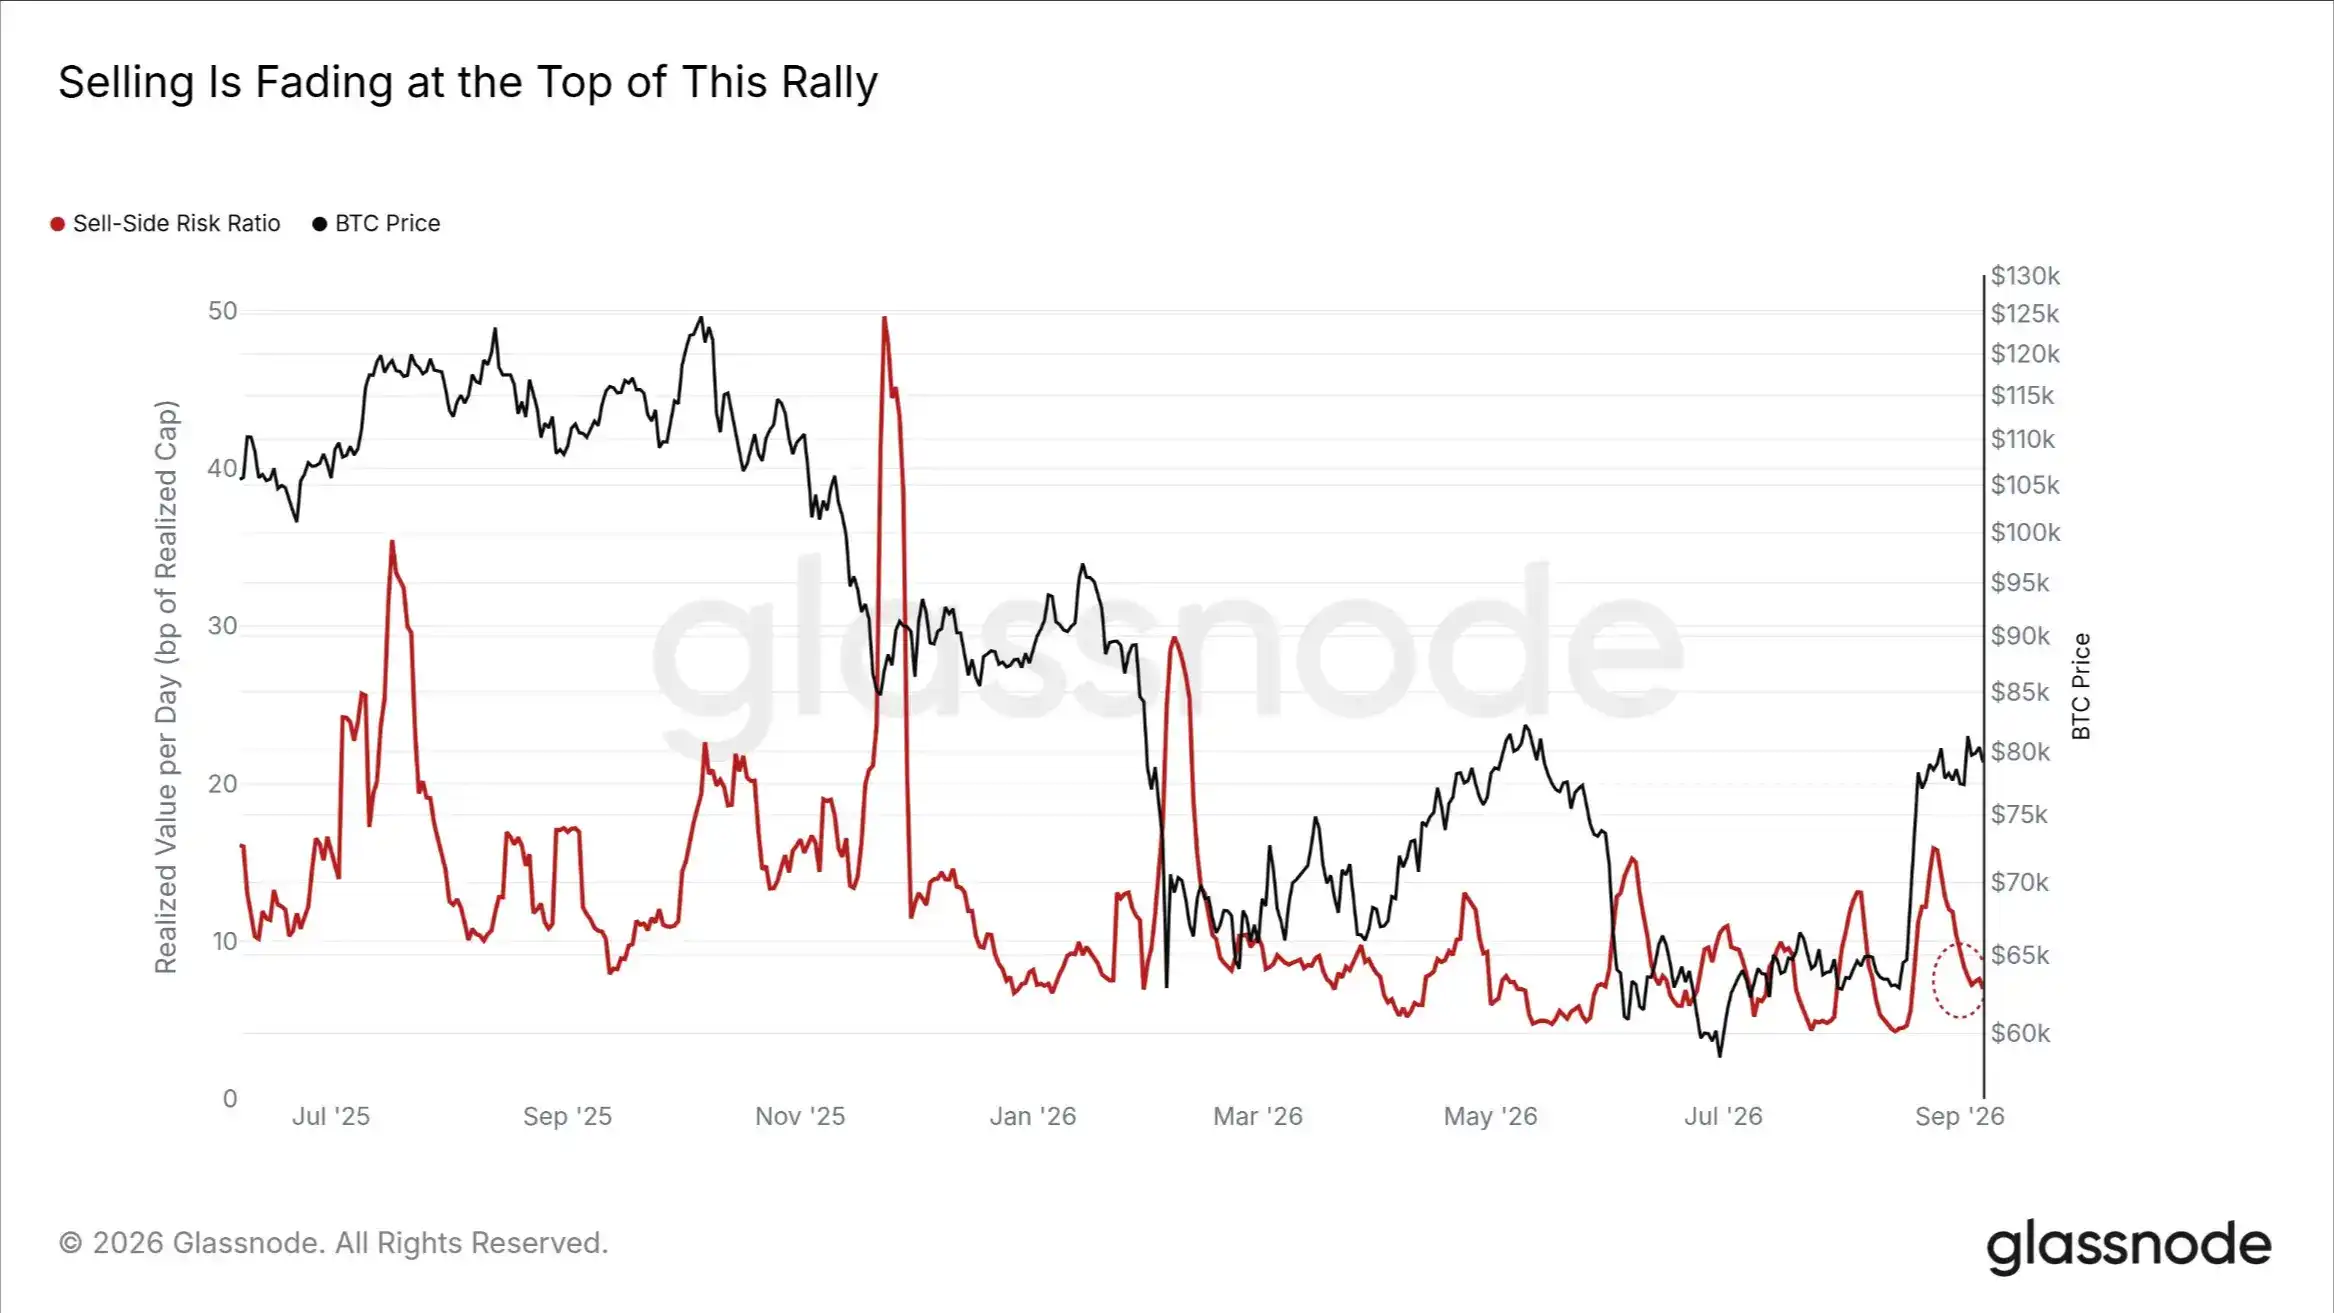
The Seller Risk Ratio measures the sum of realized profit and loss relative to realized market cap. The 7-day moving average of this indicator has now fallen to 7 basis points per day, less than half of the August high of 16 basis points.
At the market highs in July and October 2025, this indicator rose to 35 basis points and 23 basis points, respectively. In the past year, there have been only a few trading days with readings lower than the current level.
The proportion of realized profit contributed by long-term holders has also fallen from 88% at the August high to 47%. The realized profit peak seen on September 3 was less than half of the August peak.
The main sellers this month are recent buyers. Long-term holders have not been realizing profits on a large scale, and short-term holder selling intensity is also weakening.
If this indicator sustainably rebounds and breaks above 16 basis points again, it would indicate that selling pressure has returned to near the August highs. Until then, selling power in the spot market remains limited.
The Market is Between Bottom Repair and Top Confirmation
Bottom Indicators Have Exited the Extreme Weakness Zone
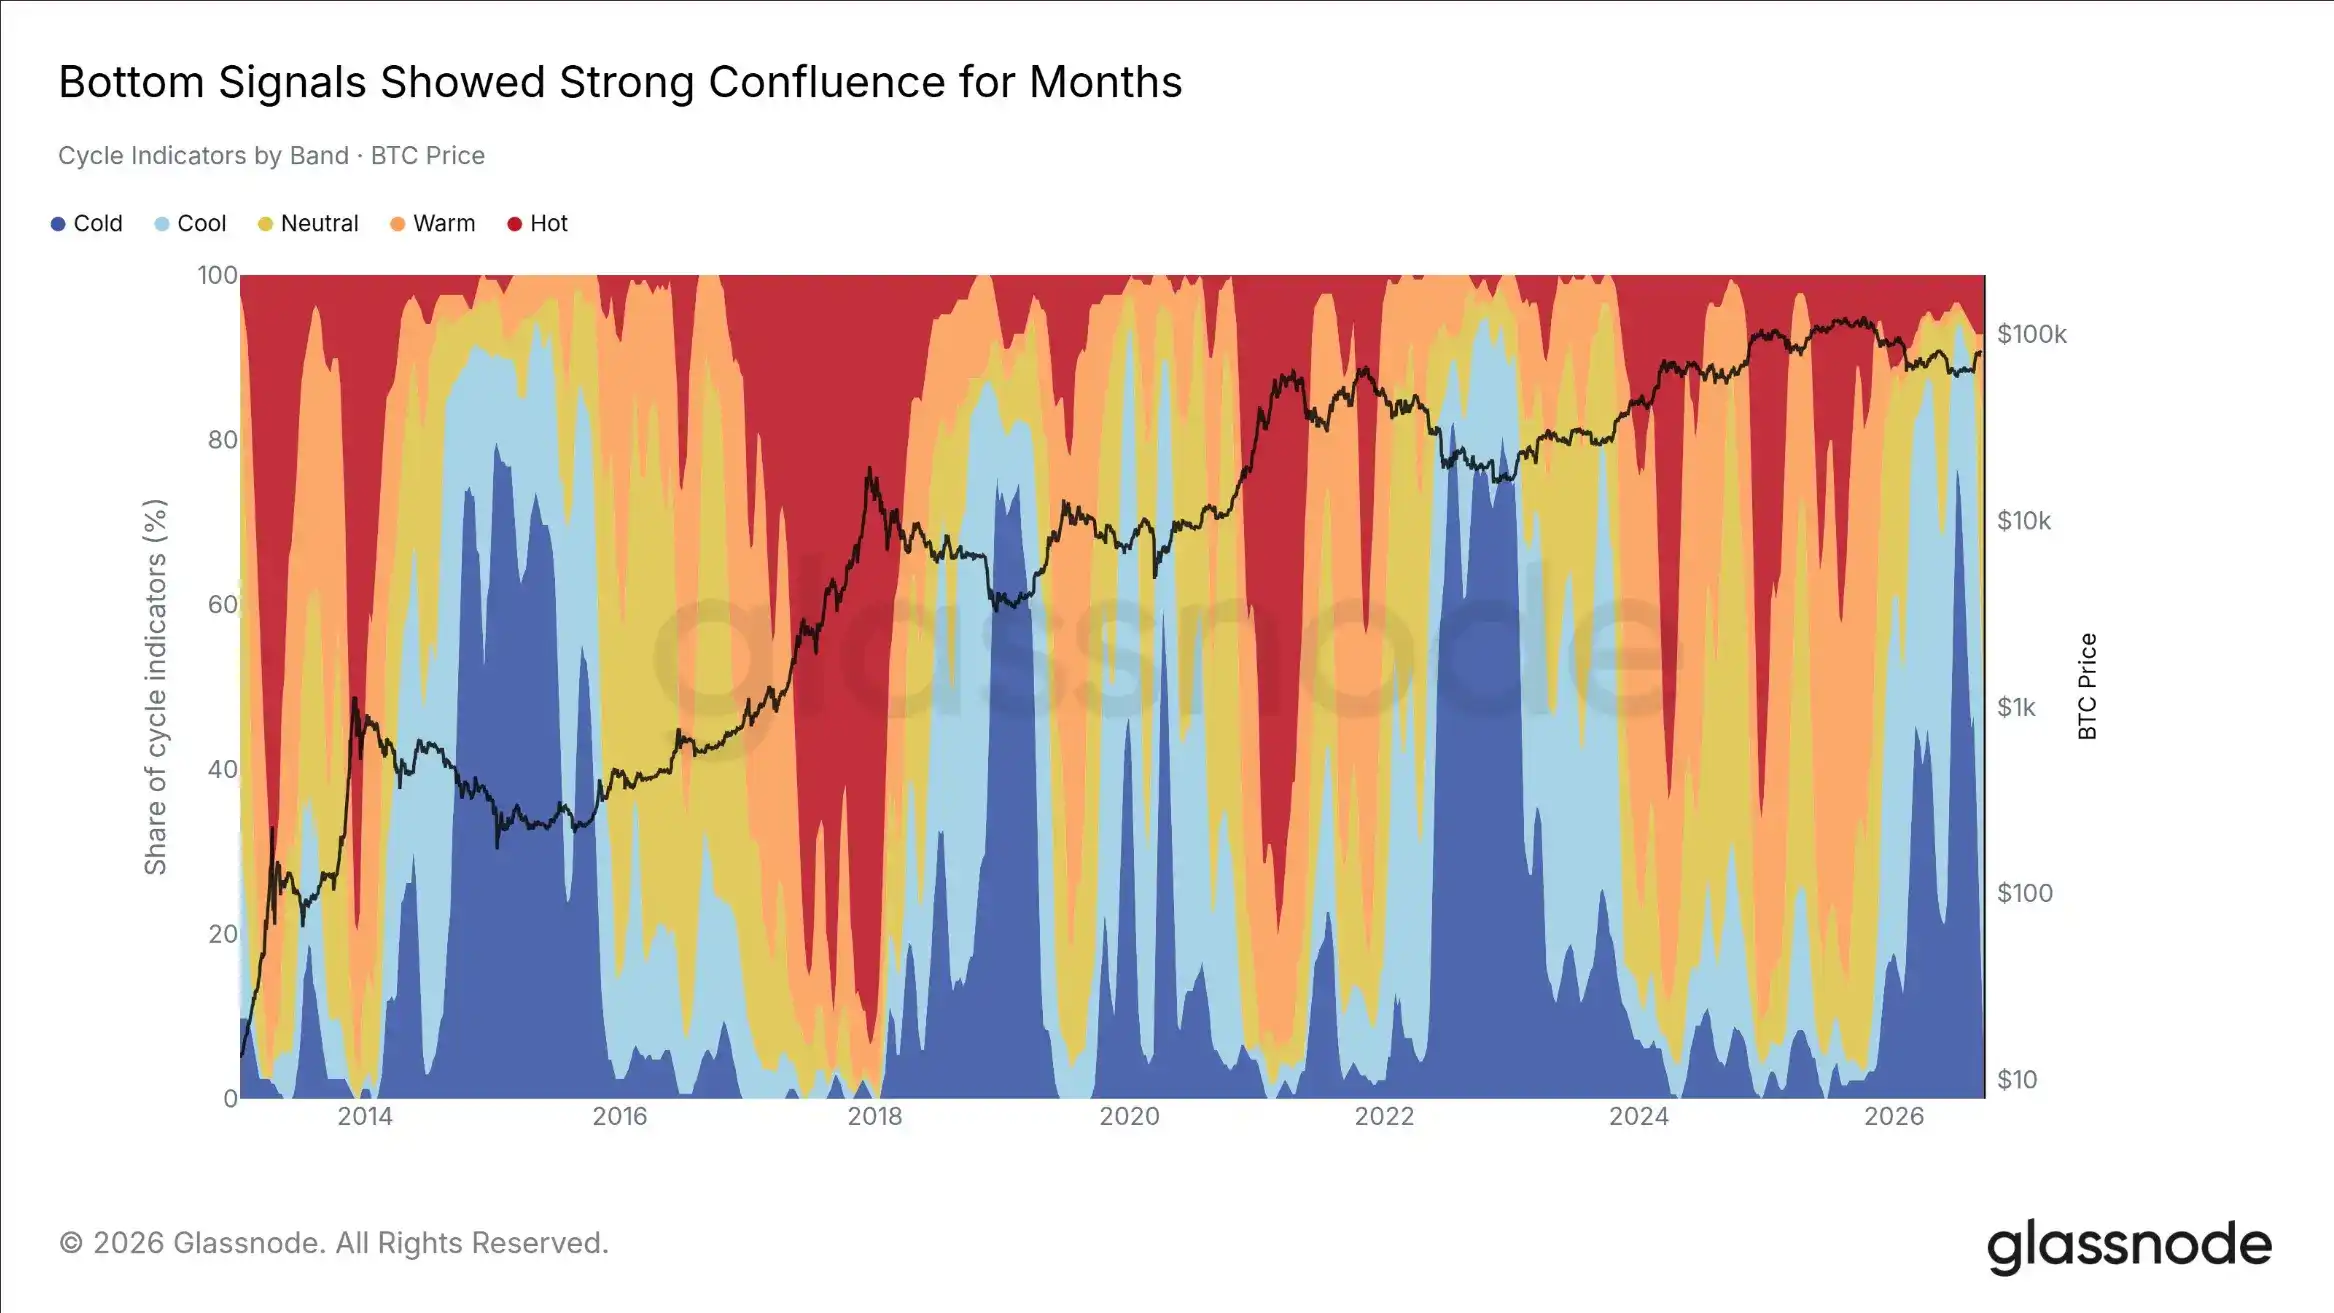
Among the 45 cycle indicators tracked by the Market Compass dashboard, the proportion of indicators in the extreme weakness zone reached a peak of 82% for the week ending June 29, 2026, and remained above the long-term median for 41 consecutive weeks.
This was the strongest bottom signal resonance seen in this cycle.
As Bitcoin has risen and market valuations have gradually recovered, the proportion of indicators in the extreme weakness zone has dropped to 2%, and bottom signals have been largely removed.
However, the market has not moved to the other extreme either. Currently, three-quarters of the indicators are still below the midpoint of their respective historical data, and there have been 43 consecutive weeks without more than half of the indicators being above 50.
Bitcoin has moved out of the value zone but has not yet entered a clearly overvalued area. If more than half of the indicators break above 50, it would be a clearer confirmation signal of a shift in the market cycle.
No Abnormal Altcoin Rotation Yet
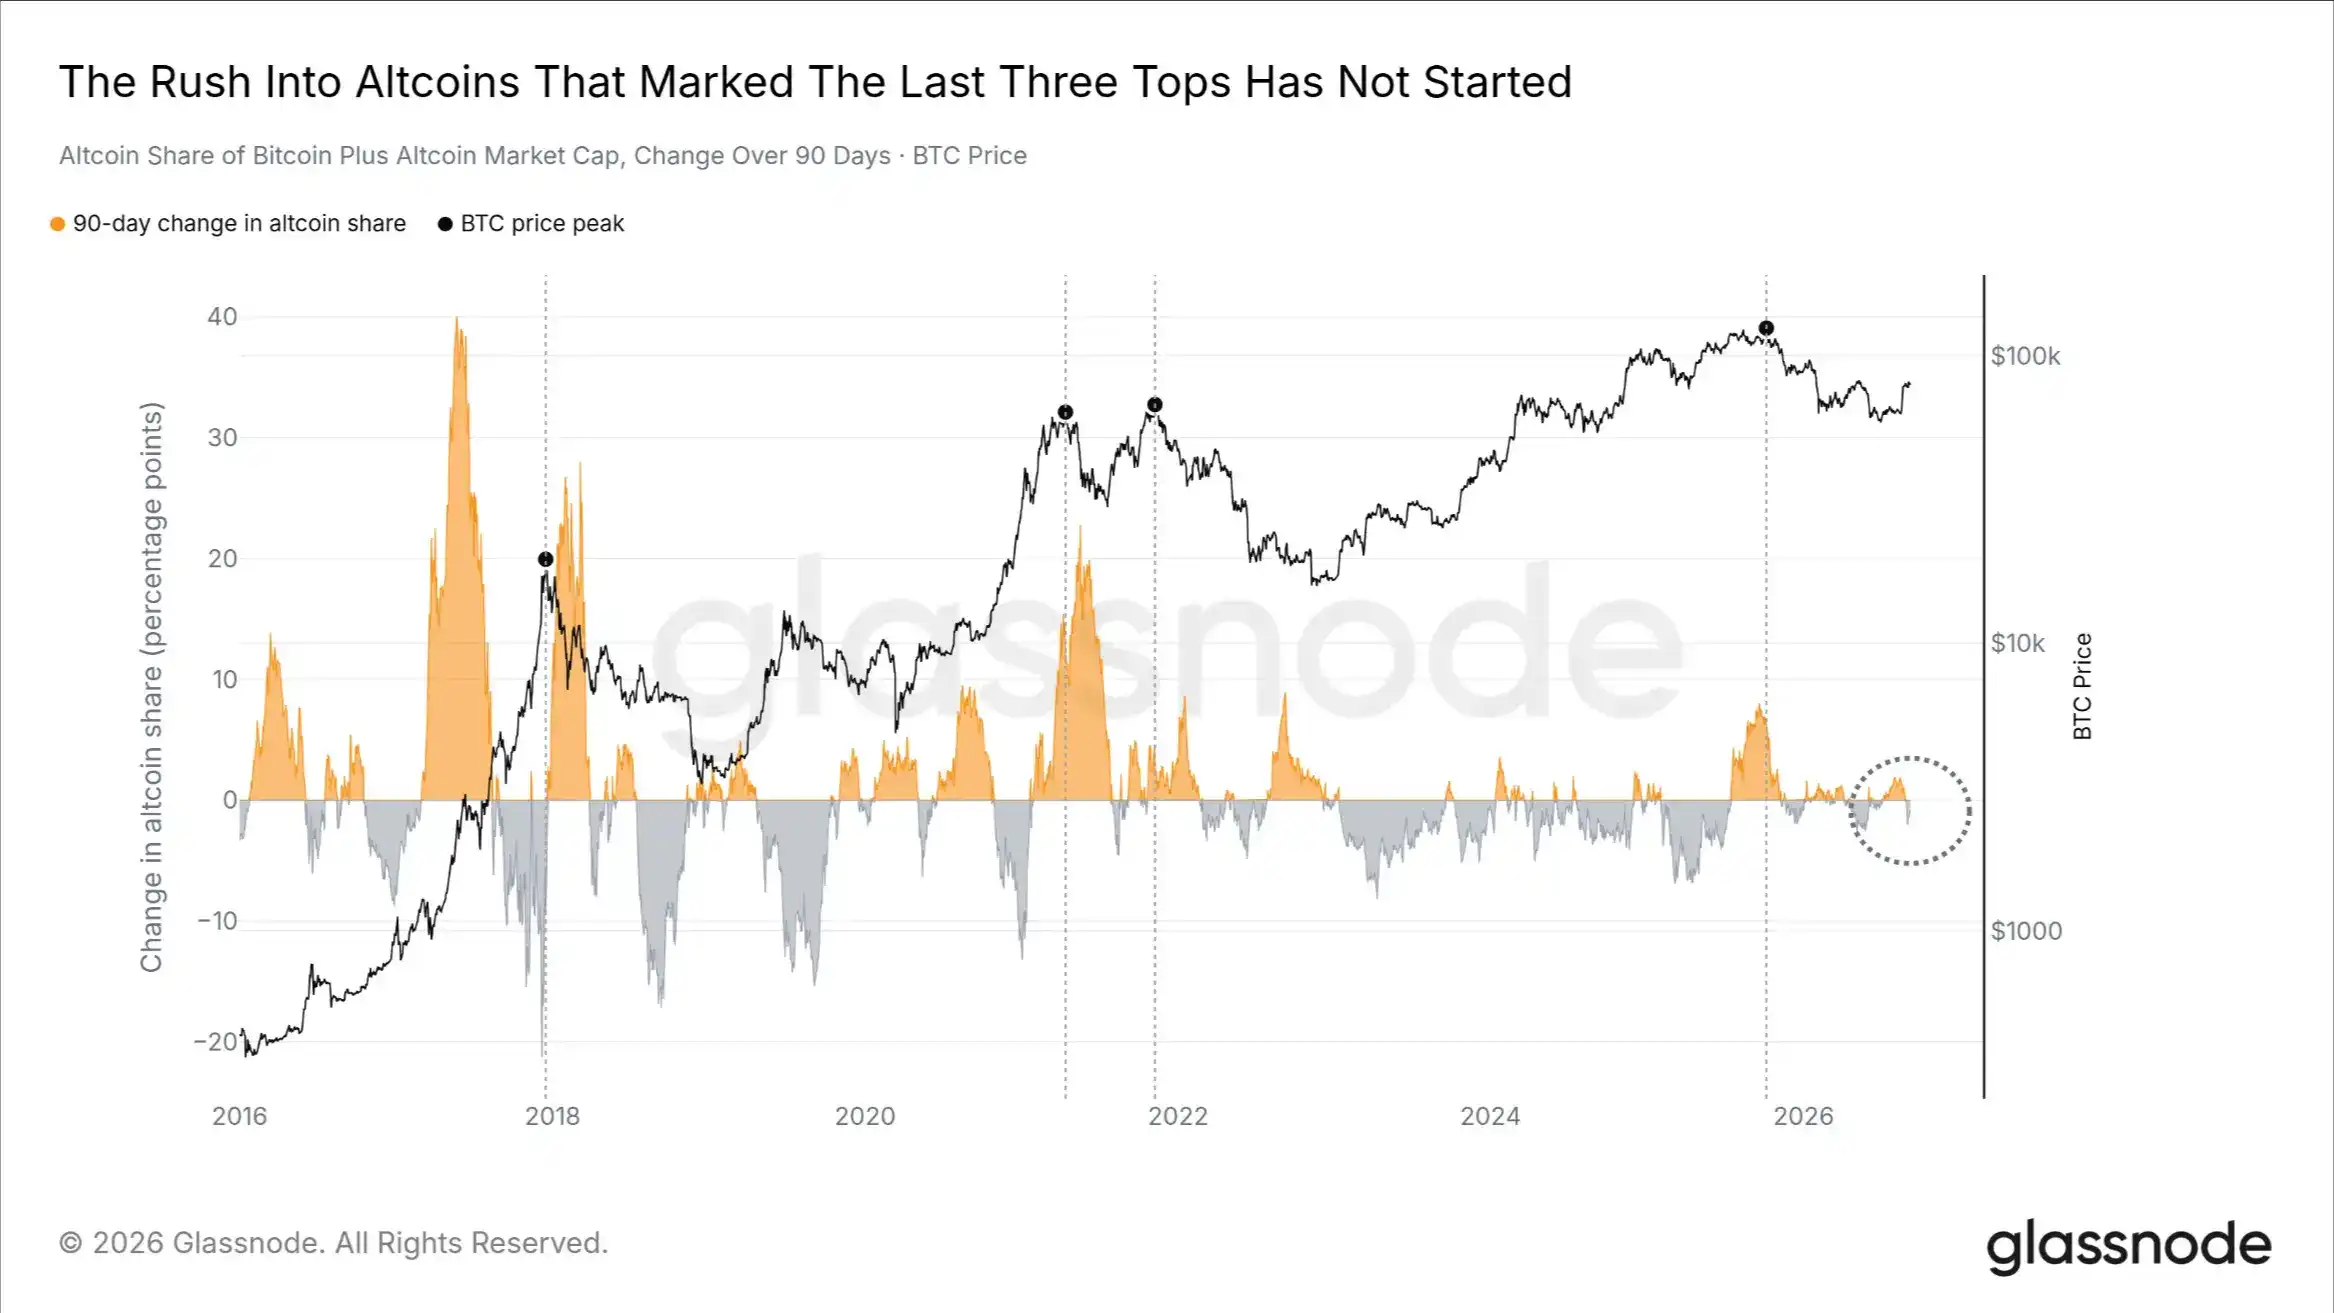
Over the past month, the total market capitalization of altcoins has risen 21%. But what needs to be observed is not whether altcoins are rising, but whether their rise relative to the entire crypto market is strong enough to start taking market share from Bitcoin.
Among the four Bitcoin price tops marked on the chart, before three of them, altcoins' market share over the past 90 days had increased significantly, gaining at least 2.8 percentage points. The top in December 2017 was the only exception.
Currently, the proportion of altcoins in the combined market cap of BTC and altcoins has instead decreased by 0.9 percentage points over the past 90 days.
Altcoins have risen in USD terms but have not outperformed Bitcoin. Various crypto assets have moved almost synchronously upward, with the largest-cap coin still leading.
Before a cycle top truly forms, there is typically a round of obvious capital rotation: funds quickly flow from Bitcoin to riskier altcoins, with the altcoin market cap growing faster than Bitcoin itself.
This stage has not yet appeared. If the altcoin market share increases by 2.8 percentage points or more in the next 90 days while Bitcoin approaches its historical high, it would constitute a similar warning to previous cycle tops. Currently, neither of these conditions is met.
Conclusion
Bitcoin is consolidating below the $83,000 to $86,000 resistance zone, and three independent indicators—long-term holder cost basis, liquidation distribution, and ETF breakeven lines—all point resistance to this same interval.
The current market is still in a state of oscillation where support has been repaired but the top has not been broken.
Compared to August, the most obvious change in this round of price action is the significant weakening of selling pressure: the Seller Risk Ratio is less than half of the August high, long-term holders have not realized profits on a large scale, yet short liquidation liquidity above is increasing.
If Bitcoin can sustainably close above $86,000 while the Seller Risk Ratio remains low, it would mean the market has digested the selling pressure above.
Conversely, if the Seller Risk Ratio breaks above 16 basis points again, or if the price falls below the support zone of $62,000 to $65,000, the current assessment would become invalid.