Europe to Introduce New Prohibitions for Russians in Cryptobusiness. What Will It Be

cryptonews.ruPublicado a 2026-08-18Actualizado a 2026-08-18

Resumen

The European Union is imposing new restrictions prohibiting Russian citizens and residents from owning, controlling, or holding management positions in European crypto-asset service provider companies, effective from August 25, 2024. These measures, part of the EU's 21st sanctions package, extend existing bans to cover all services under the MiCA regulation, including exchanges, trading platforms, custody, and advisory services. The rules forbid direct or indirect ownership or control, and any role granting decision-making authority in such EU-based companies. They also prohibit EU crypto firms from transacting with platforms in third countries deemed by the EU to systematically facilitate sanctions circumvention; a specific list of these jurisdictions is pending. Exemptions apply to citizens and permanent residents of the EU, EEA, and Switzerland. Russians must divest holdings or relinquish management roles by the deadline. Non-compliance carries risks of criminal sanctions for individuals and licensing threats for the companies involved. The move aims to close loopholes used by Russian entities to evade financial restrictions through the crypto sector.

From 2024, Russian citizens and individuals residing in Russia are prohibited from owning, controlling, and holding positions in the management bodies of European companies providing crypto wallet, account, and digital asset custody services. The 21st package of EU sanctions, adopted at the end of July, expands these restrictions. Lawyers explained what else will be prohibited regarding Russians and European crypto companies.

What Will Change in EU Rules

From August 25, the existing ban will extend to companies providing any crypto services under the MiCA regulation, including exchanges and trading platforms, said Yuri Brisov, partner at Digital & Analogue Partners. This covers the entire list under the European Market in Crypto Assets (MiCA) regulation: exchange of cryptocurrency for fiat and for other cryptocurrency, order execution and transmission, crypto-asset transfers, token placement, consulting, portfolio management, custody. If previously a Russian could not own a European crypto custodian, by the end of August they will not be able to own any licensed crypto company in the EU or be part of its management.

Owning or controlling, directly or indirectly, companies providing at least one of the above-mentioned services is prohibited for Russian citizens and residents—any individuals actually permanently residing in Russian territory, regardless of their passport, explained Maria Nefedova, consultant at IPN Partners. She clarified that the prohibition also covers holding any positions in the management bodies of such companies, if the company is established under the law of an EU member state, and the term "management body" typically includes the board of directors, supervisory board, executive board, and any other statutory body of the company vested with powers of management and supervision.

"This concerns not only the position of director, but in general any position granting the right to make decisions or control the company's activities. The wording 'own or control' can also be interpreted broadly—it formally covers not only cases of direct shareholding, but also indirect ownership through a chain of companies or exercising de facto control of a company without share ownership," says Nefedova.

Also, according to her, a ban is introduced for EU companies to enter into transactions, directly or indirectly, with companies and platforms providing crypto-asset services, if they are established in "certain" third countries. This refers to countries that the EU Council recognizes as systematically not preventing the use of platforms to circumvent sanctions. A specific list of such countries has not yet been approved and will be formed by a separate Council decision as relevant jurisdictions are identified, the lawyer clarified.

Who the New EU Restrictions Apply To

The EU states that the new measures primarily aim to combat sanctions circumvention through third countries, where, according to the EU Council, the activity of Russian banks and other players in the cryptocurrency market is gradually shifting, Nefedova said. Therefore, the new prohibitions are divided into several blocks.

The first concerns personal participation: Russian citizens and individuals actually residing in Russia are prohibited from owning shares, controlling, or holding posts in the management bodies of European crypto companies. The second block concerns business itself: European operators will be prohibited from entering into transactions with crypto companies and platforms registered in those third countries that will eventually be included in the sanctions list of "problematic" jurisdictions, the expert explained.

Brisov emphasized that, since not only direct but also indirect ownership and control are prohibited, hiding a share behind a holding company or nominee will not work. He also added that parallel norms have been introduced for citizens and residents of Belarus.

"The practical burden also falls on the European crypto companies themselves. Transaction screening does not detect such violations, so companies will have to check corporate registers, beneficial owner data, and the composition of boards of directors," said Brisov.

What Exceptions Are Provided Under the New Prohibitions

The prohibition does not apply to citizens of EU, EEA countries and Switzerland, nor to individuals with temporary or permanent residence permits in these countries: a Russian with a Cyprus passport or a Portuguese residence permit is not subject to the restriction, says Brisov. He also noted that the European Commission recognizes long-term national visas, such as study, work, or humanitarian visas, as legal residence, but this depends on the specific country's law. No special industry-specific exceptions or transitional permissions for owners without European status are provided, the expert added.

There is another exception concerning EU citizens, said Nefedova. If a citizen of an EU member state permanently resided in a country that later ends up on the EU's list of "problematic" jurisdictions, and had resided there before the date of that country's inclusion in the list, the ban on transactions with local crypto platforms does not apply to them. Most likely, the date of inclusion of a specific country in the list will be explicitly stated in the annex itself, and the EU citizen will have to document the fact of residence there before that date, for example, with a residence permit, registration, or a document on tax residency in that country, the expert explained.

How the New Rules Will Affect Russian Owners and Top Managers of European Crypto Companies

From August 25, individuals not covered by exceptions who own shares in European crypto companies of any profile must cease ownership or control in such a company, says Nefedova. In turn, top managers and board members who are Russian citizens or residents also cannot hold positions in the management bodies of such companies.

A direct mechanism for a gradual exit for this category of persons is not provided. According to the expert, it is assumed that the prohibition is unconditional and requires complete cessation of participation and holding of positions by the specified date. Thus, companies will have to conduct a pre-emptive check of the ownership structure and composition of management bodies to identify all beneficial owners and officials falling under "Russian citizen" or "resident in Russia," including cases of indirect ownership through a chain of companies, explained Nefedova.

"Formally, the ban targets the Russian individual, not the company as an EU legal entity, so direct responsibility lies with them. But in practice, banks, payment systems, and company partners usually also check the composition of shareholders and the board of directors, so the fact of having a Russian beneficial owner or top manager can lead to refusal of service or contracts with the company itself," warned the lawyer.

Brisov reminded that Russians have one week left and three options for action: sell the share, exit management bodies, or confirm European status. The expert explained that those who did not manage to do so within a month of the sanctions package adoption will exit the capital on worse terms: buyers are few, and time works against the seller.

For an individual, a violation means sanctions liability, which in most EU countries is criminal, said Brisov. According to him, for a company, a Russian shareholder or director without European status becomes a direct threat to the MiCA license: regulators assess the suitability of owners and management body members, and a sanctioned status of a participant will not pass this assessment.

"The EU's logic is consistent: first, Russians were denied access to European crypto infrastructure as clients, then as counterparties, now as owners and managers," said the expert.

end-content
Preguntas relacionadas

QWhat is the main change introduced by the EU's 21st sanctions package regarding Russian citizens and crypto assets?

AThe EU's 21st sanctions package, effective from 25 August, extends the existing ban. It prohibits Russian citizens and residents from owning, controlling, or holding management positions in any licensed EU crypto-asset service provider (CASPs). This includes services like exchanges, trading platforms, custody, and portfolio management covered under the MiCA regulation, not just crypto-custodians.

QWho is specifically targeted by the new EU ownership and management bans in the crypto sector?

AThe bans specifically target Russian citizens and any individuals who are residents of Russia (i.e., persons physically residing in Russia, regardless of their passport). This applies to direct or indirect ownership or control, and any position in a management body (e.g., board of directors, supervisory board) of a licensed EU crypto company.

QWhat are the two main blocks of the new EU crypto restrictions?

AThe new restrictions are divided into two main blocks. First, a ban on personal participation: prohibiting Russian citizens/residents from owning, controlling, or holding management posts in EU crypto companies. Second, a business-level ban: prohibiting EU operators from transacting with crypto companies/platforms registered in third countries that the EU Council later lists as systematically failing to prevent sanctions circumvention.

QWhat key exceptions allow individuals to avoid these new EU crypto restrictions?

AThe key exceptions are for citizens of the EU, EEA, and Switzerland, as well as individuals holding a temporary or permanent residence permit in these countries. A Russian citizen with, for example, a Cypriot passport or Portuguese residence permit would not fall under the restrictions. Long-term national visas (e.g., for work, study) may also be recognized as lawful residence depending on national law.

QWhat must Russian owners or managers of EU crypto companies do before the 25 August deadline, and what are the risks of non-compliance?

ABefore 25 August, Russian owners/managers who do not qualify for an exception must either sell their shares/stakes or resign from management positions. Failure to comply leads to sanctions liability, which is criminal in most EU countries for individuals. For the company, a sanctioned shareholder or director poses a direct threat to obtaining or maintaining a MiCA license, as regulators assess the suitability of owners and managers, and such individuals would fail that assessment.

Lecturas Relacionadas

Opinion: Military Conflicts Accelerate Cryptocurrency Adoption in the Middle East

Military conflicts and national currency instability have accelerated cryptocurrency adoption in the Middle East, according to an analysis for the Bitcoin Policy Institute. On-chain transaction volume in the region is estimated to have grown from around $100 billion in 2022 to $350 billion in 2025-2026, driven by macroeconomic pressure and government digitization programs, unlike global trends fueled by institutional investment. The market's initial reaction to the Israel-Iran escalation in June 2025 saw Bitcoin drop 2.3% and Ethereum 7.5%, with total crypto market cap falling 3.7%. However, Bitcoin later stabilized, with its market share rising to 64.8%, interpreted as a flight to safety from altcoins. Notably, crypto exchanges continued operating during regional conflicts while traditional stock exchanges halted. Adoption drivers vary across the region. In Egypt, Turkey, Lebanon, and Iran, demand for Bitcoin and dollar stablecoins stems from currency devaluation and traditional financial restrictions. In contrast, the UAE and Bahrain see growth supported by clear regulation, institutional players, and economic diversification programs. Data shows a surge in small everyday crypto payments in the UAE, while Turkey leads in transaction volume but with increased speculative trading. Iran's crypto market is becoming more isolated, requiring more intermediate transfers for international access. Analysts suggest these conflicts are pushing Bitcoin closer to becoming a genuine settlement medium.

cryptonews.ruHace 4 min(s)

Opinion: Military Conflicts Accelerate Cryptocurrency Adoption in the Middle East

cryptonews.ruHace 4 min(s)

Partner at Blockchain Capital: Tokenization is the Shipping Container of Capital Markets

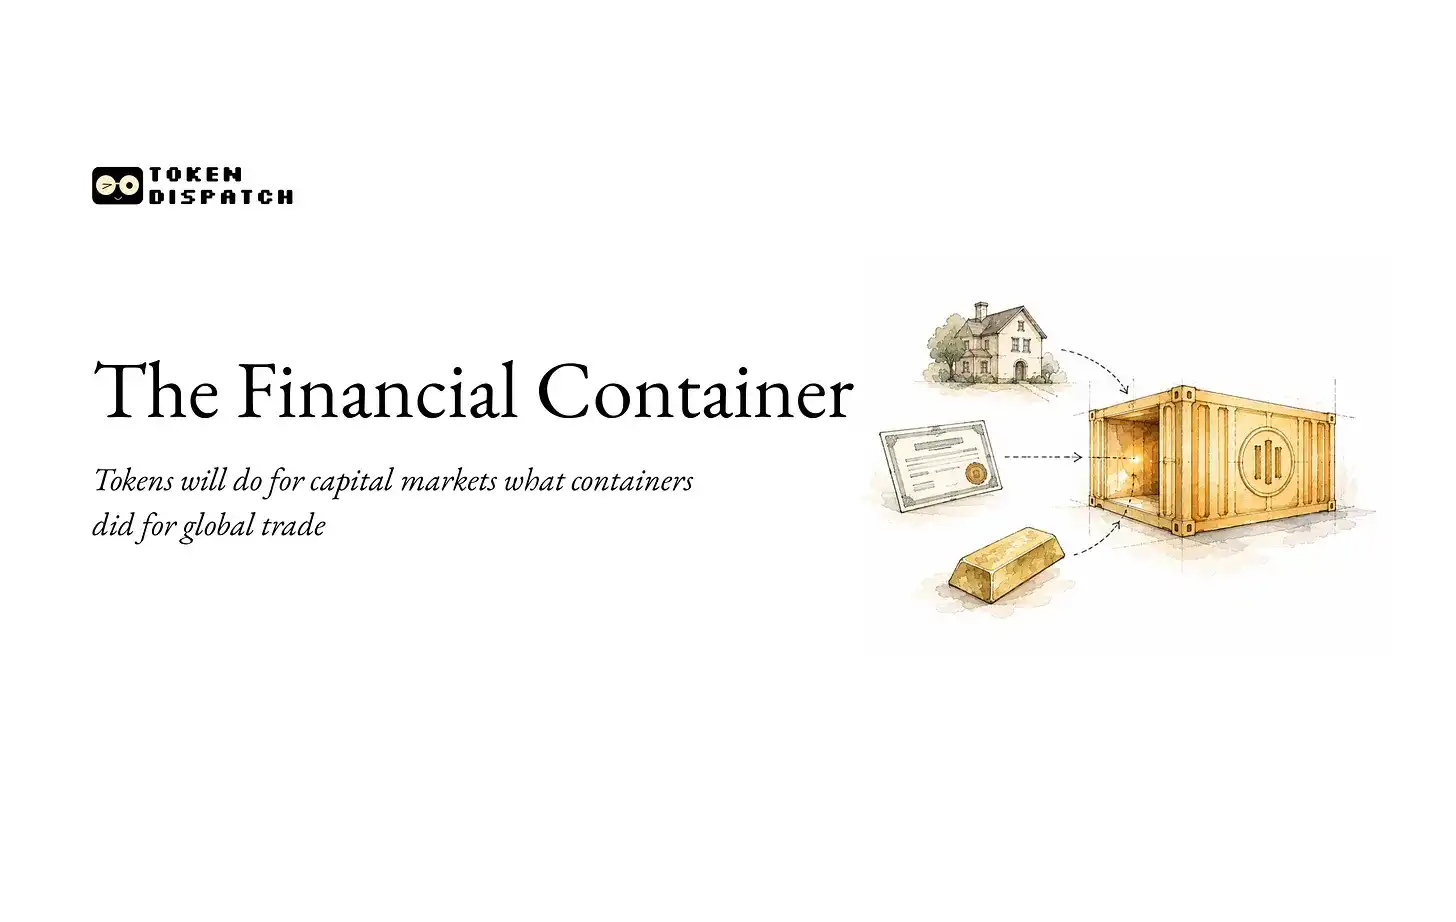
Tokenization: The Container for Capital Markets Financial markets suffer from high costs due to fragmented systems where assets like mortgages or private equity shares exist as isolated bundles of documents and data. This fragmentation creates friction, hindering the free flow of capital to productive uses. Tokenization solves this by providing a standardized, machine-readable interface for financial assets—like a container in global trade. Just as the standardized shipping container revolutionized logistics by enabling seamless, efficient transfer between ships, trucks, and trains, a token acts as a universal vessel for economic rights and rules. Once an asset is tokenized on a shared network, exchanges, lenders, and applications can all interact with it using this common interface, drastically reducing the costs of moving, settling, and utilizing capital. Stablecoins are a prime example, demonstrating how a tokenized dollar can move globally in seconds at near-zero cost by leveraging existing crypto infrastructure. This established network is now attracting a rapidly growing range of tokenized real-world assets (RWAs), from treasuries to private credit. The future capital market will be rebuilt around tokens. In decentralized finance (DeFi), protocols like Aave allow assets to directly access financial services based on transparent, code-enforced rules, reversing the traditional model where access depends on institutional relationships. Finance becomes a programmable capability attached to the asset itself. This shift promotes specialization and open networks over integrated, closed institutions. Competition will center on service quality, not control over proprietary systems or access channels. Ultimately, tokenization can create a seamless, global capital market, unlocking value from currently inaccessible, fragmented, or "stranded" assets—from small receivables to local infrastructure—by making them discoverable and financeable at dramatically lower cost. Combined with AI for automated operations, this promises to expand the reach and efficiency of capital allocation on a global scale, much as the container did for trade.

marsbitHace 9 min(s)

Partner at Blockchain Capital: Tokenization is the Shipping Container of Capital Markets

marsbitHace 9 min(s)

Wealthy Tax Evasion, Silently Shifting the Burden onto DeFi Lending Pools

A study examines how U.S. crypto investors use DeFi lending platforms like Venus to avoid capital gains taxes, and how this tax-motivated behavior increases credit risk for lending pools. Investors can borrow stablecoins against their appreciated crypto holdings instead of selling, deferring taxable events. However, this leads them to delay risk-mitigating actions like selling collateral or repaying loans when prices fall, as they seek to preserve unrealized gains and qualify for lower long-term tax rates. Researchers analyzed Venus protocol data (Nov 2020–Jul 2022). The 2021 U.S. Infrastructure Bill, which expanded tax reporting for digital assets, served as a natural experiment. Inferred U.S. users showed a 24.5% decrease in trading activity post-bill, with an extra 23% drop for those using stablecoin loans, indicating tax-driven "lock-in" of assets. This reduced liquidity correlates with higher default risk. A 1% increase in this tax-induced illiquidity was associated with an 11.2% rise in defaulting accounts and a 39.6% increase in defaulted loan value. While over-collateralization protects against normal market swings, it cannot account for borrowers' hidden tax motives. Defaults from these "invisible" risks can ultimately impact the entire lending pool through failed liquidations and loss-sharing mechanisms. The study highlights a key blind spot in automated DeFi lending: smart contracts assess collateral value but not user intent, allowing personal tax strategies to silently transfer risk to decentralized lenders.

marsbitHace 13 min(s)

Wealthy Tax Evasion, Silently Shifting the Burden onto DeFi Lending Pools

marsbitHace 13 min(s)

Moore Threads Plunges 20% to Limit Down in Early Trading, Company Responds

On September 7th, China's domestic GPU maker Moore Threads' stock price hit the 20% daily limit-down during morning trading on the Sci-Tech Innovation Board (STAR Market). This marked the first such steep decline since its listing in December 2025. The immediate trigger was a large-scale unlocking of restricted shares. A total of 25.77 million IPO-related shares became tradable, representing 5.48% of the total shares and an estimated market value of approximately 13.39 billion yuan. This nearly doubled the company's tradable share count, placing significant short-term selling pressure on the market. In response, the company's securities affairs representative stated that the unlocking was a normal post-IPO event, with the shares primarily held by institutional investors from the initial offering. The company emphasized its operations remain normal with no major changes to its fundamentals, urging investors to view the price volatility rationally. Financially, Moore Threads' latest half-year report showed strong growth. Revenue for the first half of 2026 reached 1.74 billion yuan, a 147.42% year-on-year increase, surpassing its full-year 2025 revenue. While still reporting a net loss, the loss narrowed significantly compared to the same period last year. As a key player in China's domestic GPU sector, the company continues to advance its product lines for desktops and data centers. Market analysts note that while share unlockings cause short-term volatility, long-term stock performance will ultimately depend on the company's fundamental business progress and the broader industry logic of domestic substitution. A larger unlocking event is scheduled for December 2026.

marsbitHace 14 min(s)

Moore Threads Plunges 20% to Limit Down in Early Trading, Company Responds

marsbitHace 14 min(s)

Trading

Spot
活动图片