Author: Li Dan
As CoreWeave's default risk soars to a record high, with a market-implied five-year cumulative default probability exceeding 60%, NVIDIA CEO Huang Renxun stepped out to "put out the fire," stating that CoreWeave's financial strength continues to improve, its financing costs are declining, and there is no need for NVIDIA to provide a backstop.
On Thursday, October 15th, U.S. Eastern Time, CoreWeave's five-year credit default swap (CDS) spread, an indicator reflecting the cost of insuring against a company's debt default, surged by 74.5 basis points at one point, reaching 1194.5 basis points, a record intraday high. Concurrently, yields on some of the company's bonds climbed above 15% to 16%, reflecting a sharp increase in investor concerns about its debt repayment ability.
At an event in Sweden the same day, Huang Renxun told media in an interview: "CoreWeave's strength is growing day by day." He expressed optimism about the company, noting that its "cost of capital is actually coming down." Addressing market concerns about whether NVIDIA needed to provide financial backing for CoreWeave, Huang Renxun explicitly stated he did not believe it was necessary.
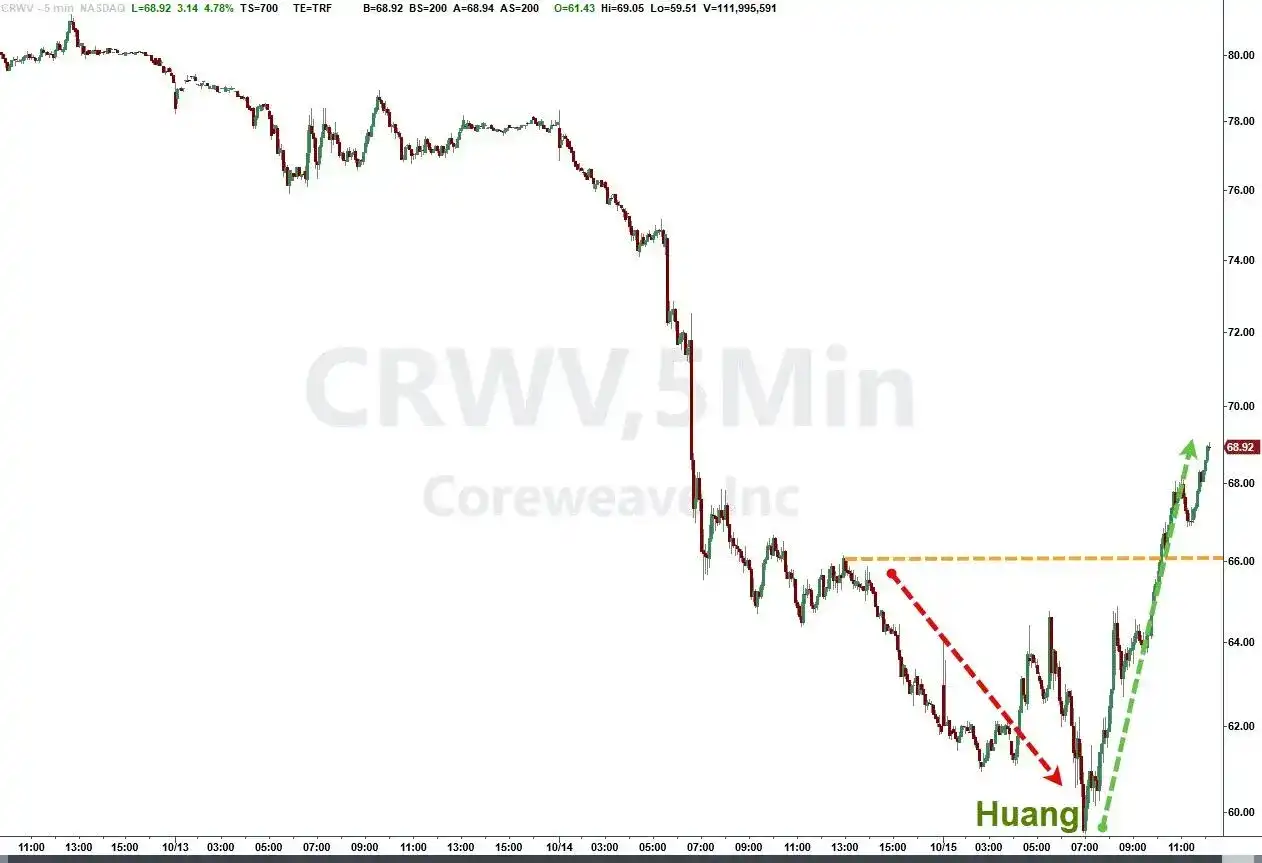
On Thursday, CoreWeave (CRWV) stock opened sharply lower by 6.6%, with losses widening to 9.5% in the morning session. After Huang Renxun's remarks, it accelerated its recovery, turning positive in the afternoon session and continuing to rise. By late afternoon, gains had reached just over 6%, rebounding roughly 17% from its intraday low hit earlier in the day. The stock closed up more than 5.9%, snapping a three-day losing streak and paring its weekly loss to around 15%.
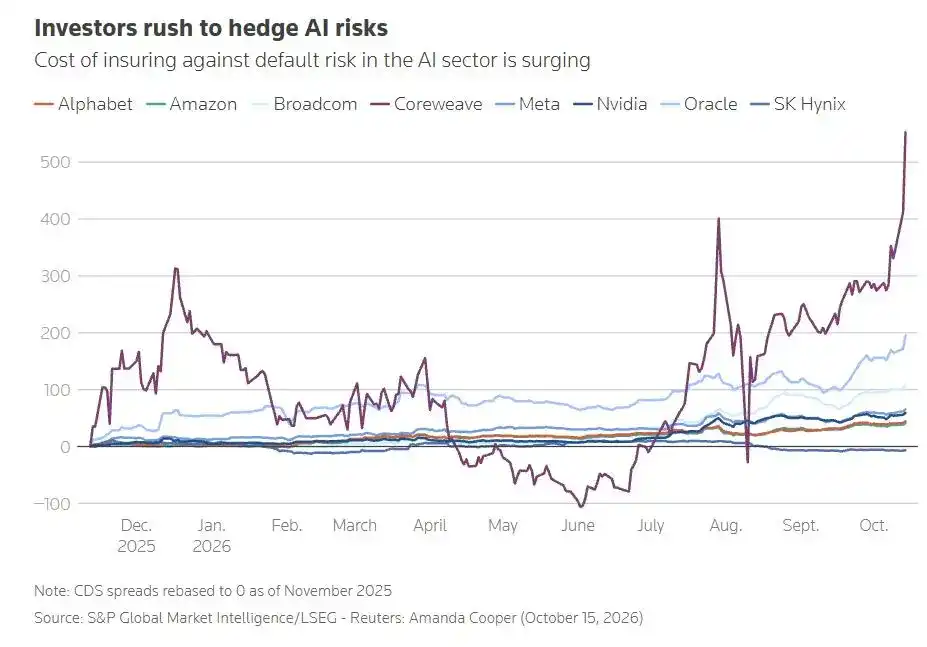
More alarmingly, the nervousness in the credit markets is spreading, indicating investors are reassessing the debt risks behind AI infrastructure investments. Media reports note that Oracle's five-year CDS spread was nearing 300 basis points on Thursday, widening about 31 basis points over four days this week. CDS spreads for Amazon, Google's parent Alphabet, and Meta are also at record highs; SoftBank's five-year CDS spread widened by 24 basis points in a single day; while CDS spreads for NVIDIA, STMicroelectronics, and SpaceX have also risen notably.
Five-Year CDS Breaks 1190 bps, CoreWeave Bonds Sold Off
CoreWeave is facing selling pressure in both stocks and bonds.
ICE Data Services data shows CoreWeave's five-year CDS spread intraday surged to 1194.5 basis points on Thursday, a record high since records began, with associated pricing implying a cumulative five-year default probability exceeding 60%. LSEG and S&P Global Market Intelligence data indicate CoreWeave's CDS spread intraday broke through 1100 basis points on Thursday, implying a five-year default risk of about 64%, higher than the roughly 30% level a year ago.
CDS are credit derivatives used to hedge against debt default risk; their spreads typically rise as market worries about an issuer's repayment ability intensify. However, the implied default probability from CDS depends on the pricing model and related assumptions, and does not mean the company's actual probability of default over the next five years has been precisely determined.
The bond market performance is equally severe. Citing trading data, Bloomberg reported that intraday on Thursday, the price of CoreWeave's 9% coupon bonds maturing in 2031 fell about 3.3 cents to 79.9 cents per dollar of face value, with the yield rising to 15.6%; another bond with a 9.75% coupon, also maturing in 2031, fell about 2.6 cents to 78.65 cents, with the yield climbing to 16.2%.
Reuters reported that CoreWeave bonds maturing in 2032 were trading at about 78 cents per dollar of face value on the Tradeweb platform, with yields exceeding 16%. Different bonds have varying maturities, coupon rates, and trading prices, but all show investors are demanding higher risk compensation.
Bond prices significantly below face value and soaring yields mean CoreWeave may face higher costs for future bond market financing or refinancing.
CoreWeave co-founder Brannin McBee recently told the Financial Times that the company hopes to achieve an investment-grade credit rating, thereby opening access to a broader pool of funding, potentially even being able to borrow from an "infinite" pool of capital. This goal contrasts starkly with the current high bond yields: amid investor concerns about repayment ability that have yet to ease, whether the company can consistently secure financing at lower costs remains to be tested by the market.
Oracle, SoftBank, and Other AI-Related Firms See CDS Widen as Credit Risk Diffuses Across Sector
CoreWeave is not the only AI-related company experiencing pressure in credit markets.
Intraday Thursday, Oracle's five-year CDS spread was quoted at 288 basis points, flat with the previous session but 28 basis points wider than the 260 basis points a week earlier; SoftBank's five-year CDS spread widened by 24 basis points in a single day to 424 basis points. Meanwhile, CDS spreads for NVIDIA, STMicroelectronics, and SpaceX also widened notably.
According to LSEG and S&P Global Market Intelligence data, CDS spreads for Amazon, Alphabet, and Meta have also climbed to record highs, though their overall ascent has been slower than that of Oracle and CoreWeave. The cost of credit insurance for these tech giants is similarly affected by the reassessment of AI investment financing risks.
CDS spreads measure the cost investors pay to insure against debt default risk. A widening spread means the market demands higher risk compensation, but it is not equivalent to an imminent corporate default, nor should different companies' CDS spreads be directly compared as comparable default probabilities.
Rising credit insurance costs for multiple AI-related companies reflect that investors are re-evaluating the financing methods for AI infrastructure investments. The large-scale borrowing needs of companies like Oracle are drawing attention, while CoreWeave, due to its heavy debt load, unprofitability, and high reliance on external financing, has become the most concentrated case of market pressure.
Reuters pointed out that U.S. inflation data exceeding expectations and renewed market concerns about the future path of interest rates have exacerbated investor doubts about the return cycle for massive AI capital expenditures. As the industry increasingly relies on debt rather than free cash flow to finance AI construction, the market's focus is shifting from the growth in computing power demand itself towards whether related companies can generate sufficient profits and cash flow in time to cover rising interest expenses.
Burdened by Approximately $50 Billion Debt, CoreWeave's Expansion Model Questioned
The core issue facing CoreWeave is the balance between capital expenditure growth and cash flow and financing capacity.
Media reports point out that this AI cloud computing company carries nearly $50 billion in debt and remains in a loss-making state. The company relies on large-scale purchases of NVIDIA GPUs, building data centers, and expanding computing capacity to meet customer demand. Such investments typically require significant capital outlays before revenue gradually materializes.
CoreWeave has aggressively increased capital expenditures to capture a share of the fast-growing AI computing power market. During periods of strong demand, debt-fueled expansion can enable companies to build infrastructure ahead of time and use long-term customer contracts to support investment plans. However, data center construction cycles are long and equipment investments are substantial. If financing costs rise, projects are delayed, or customer demand growth falls short of expectations, companies may face funding gaps and debt repayment pressure.
Therefore, CoreWeave's problem is not just its high debt level; the market is questioning whether its future cash flow can cover capital expenditures, interest expenses, and other operating costs. Rising bond yields further raise the threshold for new financing, making this issue more prominent.
CoreWeave's management emphasizes strong order backlogs and believes the market has misjudged its financial situation. However, order backlogs are not equivalent to cash received: long-term contracts can provide some revenue visibility but do not automatically eliminate risks like construction cost overruns, delivery delays, changing financing conditions, and customer concentration. Investors need to judge whether these contracts can ultimately translate into sufficient cash flow and sustainable profits.
Why NVIDIA Stepped Up to 'Put Out the Fire': Intertwined Supplier Financing and Customer Demand
Huang Renxun publicly expressed confidence in CoreWeave, reflecting the close commercial and capital ties between NVIDIA and this AI cloud service provider.
NVIDIA holds approximately a 10% stake in CoreWeave, making it the second-largest shareholder. At the same time, CoreWeave is a significant purchaser of NVIDIA GPUs. Its business model relies on purchasing NVIDIA chips, building data centers, and then leasing computing power to AI developers and large tech companies.
If CoreWeave faces financing difficulties, subsequent data center construction, GPU procurement, and computing power delivery could all be affected. Even if existing orders are not immediately canceled, rising financing costs could alter project construction schedules and capital return expectations, thereby impacting market judgments about the growth of NVIDIA's AI demand.
A more sensitive issue is that arrangements where suppliers invest in customers and customers purchase suppliers' products can easily raise market concerns about "circular financing."
Such transactions themselves do not imply misconduct, but when a company relies on borrowing to buy a supplier's products, and the supplier holds an equity stake in the company, investors will ask: How much of the industry chain's growth comes from genuine end-customer demand, and how much depends on financing-driven continuous expansion?
Huang Renxun's emphasis that CoreWeave's financing costs are declining and his explicit statement that NVIDIA need not provide a backstop serves both to maintain market confidence in a key partner and to prevent the market from directly interpreting their commercial ties as implying NVIDIA must bear CoreWeave's debt risk.
However, these remarks are not a substitute for scrutiny of CoreWeave's balance sheet. NVIDIA holding equity does not equate to providing a guarantee for its debt, and Huang Renxun's optimistic assessment cannot directly solve the company's financing needs, interest burden, and cash flow issues.
Can AI Investment Returns Cover Massive Capital Expenditures? This Becomes the Core Market Question
CoreWeave's credit turmoil is becoming a stress test for AI infrastructure investment.
Amid rapid generative AI demand growth, tech companies and computing power operators are aggressively building data centers, trying to capture the future market. However, infrastructure investment often precedes revenue realization, especially for new cloud service providers relying on external financing, who need to continuously borrow to purchase GPUs, build facilities, and pay for energy and operational costs.
When interest rate expectations rise and bond investors demand higher risk compensation, this model faces stricter scrutiny. Increased financing costs not only compress profits but may also force companies to slow expansion; if expansion slows, it could impact future revenue growth and the return on existing investments.
Deutsche Bank strategist Jim Reid noted that this is not the first time significant market volatility has been experienced due to AI concerns, but as the AI capital expenditure cycle is increasingly financed by debt rather than free cash flow, investors must pay more attention to price signals from credit markets. "Overall, financing costs related to AI are not yet high, but there are worrying signs at the fringes."
This judgment highlights a key contradiction the industry faces: growth in computing power demand does not automatically mean computing power operators can secure sufficient profits; order growth does not necessarily mean debt can be easily repaid.
For CoreWeave, the real test is whether it can control debt growth, continuously secure financing, and translate its massive order backlog into sustainable operating cash flow. For NVIDIA and the broader AI industry chain, the market's focus is shifting from "how much more computing power is needed" to "who will pay for computing power construction, and whether these investments can ultimately generate sufficient returns."
Huang Renxun attempted to soothe the market, but CoreWeave's high bond yields, record credit insurance premiums, and widening CDS spreads for companies like Oracle and SoftBank indicate that investors' examination of the AI financing model is deepening. In the future, valuations in the AI industry chain will depend not only on whether computing power demand continues to grow but increasingly on whether companies can transform this capital expenditure race into real, sustainable cash flow at affordable financing costs.