Author: Rita
Marvell Technology provided a target of over $30 in non-GAAP earnings per share for FY31 at its Investor Day, corresponding to a revenue framework of $70 to $90 billion. Morgan Stanley noted in a report dated October 7, 2026, that this guidance is at least 20% higher than its previous forecast.
Morgan Stanley raised its price target from $268 to $300, maintaining an Equal-weight rating. The firm acknowledged the growth drivers while cautioning that this guidance hinges on data center capital expenditures reaching $3 trillion by 2030. The FY31 revenue framework is based on existing customers, products, and design wins and does not rely on any single socket.
FY31 Revenue Target 20% Higher
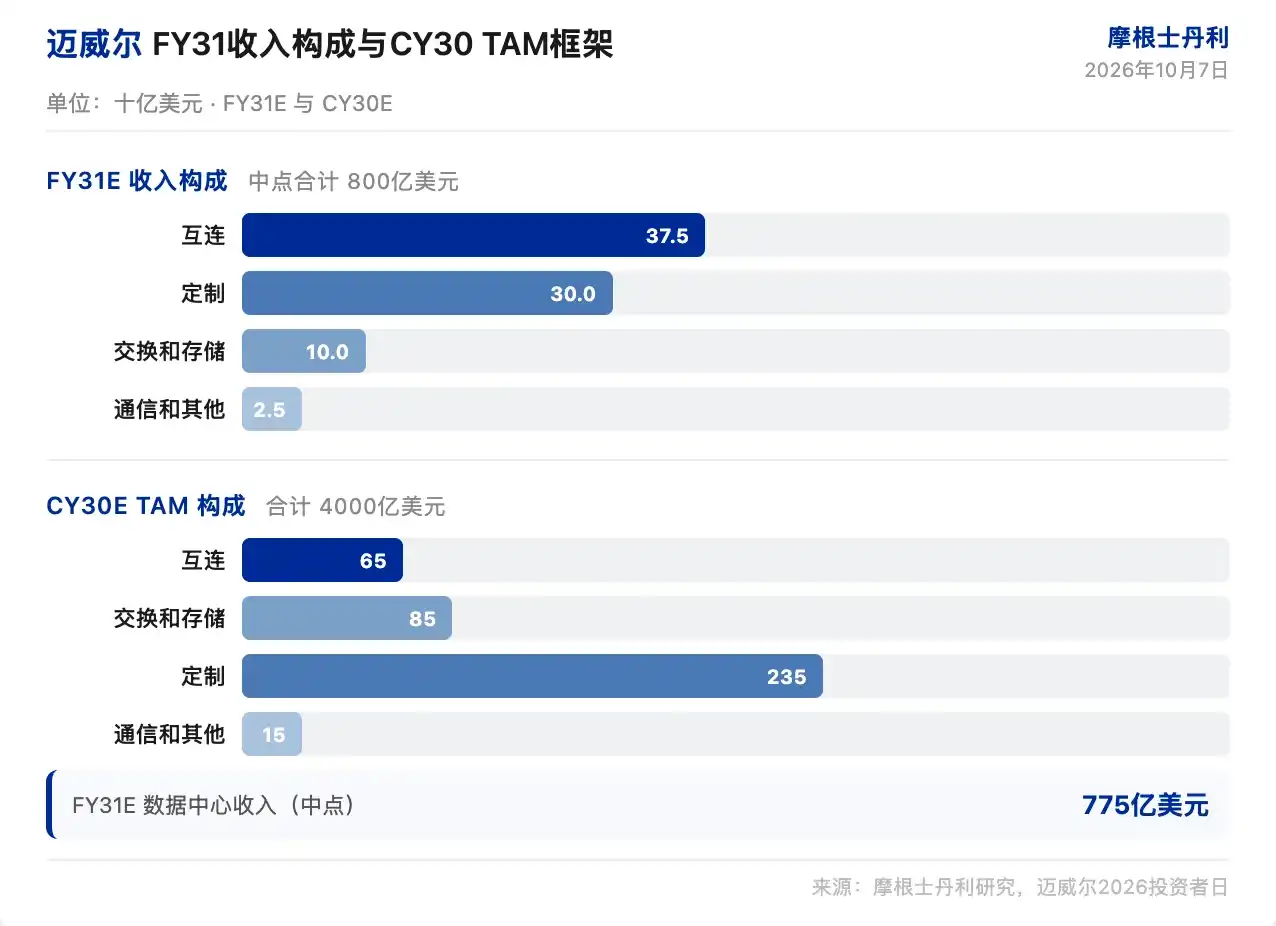
The midpoint of data center revenue is $77.5 billion, encompassing interconnect, custom, switching, and storage. Morgan Stanley previously anticipated in a preview that Marvell might provide FY30 revenue of over $40 billion, and the new framework is above that trajectory. The increment primarily comes from interconnect and custom.
FY28 revenue guidance was raised from $18 billion to $20 billion, while FY27 remains unchanged at approximately $12 billion. Morgan Stanley pointed out that the revenue growth assumptions underlying the FY31 framework imply a compound annual growth rate of 55% to 70%.
The guidance corresponds to a total addressable market (TAM) of approximately $400 billion for CY30. This includes $65 billion for interconnect, $85 billion for switching and storage, $235 billion for custom, and $15 billion for communications and other. Morgan Stanley noted that the midpoint implies Marvell capturing about 20% of its addressable data center TAM.
Connectivity Theme Contributes Largest Increment
Connectivity was the clearest theme at the Investor Day and the primary driver for the FY28 revenue increase. Management indicated the incremental $2 billion comes from continued strength in scale-out optics, an expanding opportunity in scale-up optics, and switching business.
Scale-up optics is essentially a greenfield business with virtually no revenue currently. It is expected to contribute several hundred million dollars starting next year, with a steeper ramp thereafter. Scale-out switching is projected to exceed $1 billion next year. Marvell disclosed it is developing an accelerator interconnect standard (UALink) switch, being deployed at leading hyperscalers, marking the company's first public discussion of this socket.
Morgan Stanley believes the Trainium 4 opportunity still favors Astera Labs. The market is large enough for both companies to secure meaningful sockets. The firm is closely monitoring Marvell's progress with UALink.
Scale-up accounts for approximately 85% of current data center traffic. The transition from copper to integrated optics is key to the scale-up opportunity.
Marvell covers the digital signal processor (DSP), transimpedance amplifier (TIA) and driver, near-package optics (NPO), and co-packaged optics (CPO). Optical content reaches thousands of dollars per XPU on both the custom accelerator chip (XPU) and switching sides. Morgan Stanley views Marvell's breadth across the optical stack as a key differentiator.
Custom Revenue Revision Relies on Google
Marvell raised its FY29 custom revenue target from over $10 billion to over $12 billion. It expects growth of over threefold from FY28 to FY31, reaching approximately $30 billion in FY31. Existing XPU projects are progressing as planned, with growth increasingly coming from XPU adjacencies, including NICs, memory, storage, infrastructure management, and inference acceleration.
Management listed inference acceleration as a new opportunity. Dedicated accelerators attach to XPUs to offload specific workloads. Morgan Stanley believes this may relate to the Google opportunity, though management did not comment on specific customers. The firm assumes existing XPU projects include Maia and other current collaborations.
Regarding the Google agreement, management stated the FY31 forecast assumes a reasonable portion of the opportunity and does not employ the full warrant framework. Morgan Stanley noted that upside potential is significant if utilization ultimately approaches maximum potential. The firm views the Google opportunity as one of the main sources for the custom business revision.
Morgan Stanley Maintains Equal-weight Rating
Morgan Stanley adjusted its FY28 revenue, gross margin, and EPS forecasts to $20.3 billion, 57.7%, and $7.76. Previously, they were $18.0 billion, 57.9%, and $6.68. FY29 was adjusted to $35.9 billion, 57.5%, and $14.32. Previously, they were $24.1 billion, 57.9%, and $9.58.
FY30 is $53.6 billion, 57.5%, and $21.55. The price target corresponds to 46 times the CY27e ModelWare valuation framework EPS of $6.54. The valuation multiple was lowered from 49x to 46x, from a previous EPS of $5.47.
Morgan Stanley's preference was to buy Marvell before Analyst Day and continue holding post-event. This growth rate implies a high bar each quarter.
When every company has a strong four-year growth outlook, those providing long-term guidance face a higher bar than those who do not. Marvell and AMD have provided long-term guidance; Nvidia and Broadcom have not.
Bull case is $480, 60 times CY27e ModelWare EPS of $7.46. Base case is $300, 46 times CY27e ModelWare EPS of $6.54. Bear case is $172, 30 times CY27e ModelWare EPS of $5.73. The current stock price is $287.01, close to the base case target price.
Marvell's bet hinges on data center capital expenditures reaching $3 trillion by 2030. The FY31 revenue framework is based on existing customers, products, and design wins and does not rely on any single socket. If this growth path materializes, $80 billion in revenue is achievable. This path must be validated each quarter; the bar has been raised.
Disclaimer
This article is a compilation and interpretation by Chaoxiang Research of a third-party brokerage research report (Morgan Stanley, October 7, 2026), combined with public market information. The ratings, price targets, earnings forecasts, and related judgments cited are the views of that brokerage's analysts, representing only their institution's stance and not the views of Chaoxiang Research. They do not constitute any investment advice.
The market carries risks; decisions should be made independently. This article should not serve as the basis for buying or selling any securities.
This answer is AI-generated, content is for reference only, please carefully discern