U.S. stock markets partied last night. Following the positive market signals from the previous day's "ADP" data, remarks from the Federal Reserve's Waller last night again conveyed a dovish tilt, suggesting the conditions for triggering further rate hikes have become less immediate. The three major indices collectively advanced, with safe-haven and alternative assets like gold, silver, and Bitcoin rising in tandem. Technology growth stocks saw particularly notable gains, while the AI hardware supply chain clearly underperformed the broader market. On the surface, this appears to be a synchronized rally across asset classes. However, dissecting the underlying drivers reveals its essence: a valuation-driven, macro-sentiment repair fueled by the dovish shift in Fed official rhetoric and the resulting decline in U.S. Treasury yields, rather than a substantive improvement in fundamentals or industry trends. With the FOMC meeting drawing nearer, trade data and geopolitical tensions indicate that inflationary pressures have not truly subsided. Next week's release of the August CPI data may become the key variable testing whether this round of repair can be sustained.
I. Market Review: Structural Divergence Beneath the Broad Rally Surface
As of the close on September 3, the Dow Jones Industrial Average rose approximately 580 points, or about 1.08%, to 53,656 points; the Nasdaq Composite Index gained about 1.2%, settling near 26,572 points; the S&P 500 Index increased about 1.04% to 7,743 points; the Nasdaq 100 Index also closed up over 1%. At the individual stock level, clear structural differentiation was evident: First, traditional tech giants and related growth stocks led the gains, with Tesla and SpaceX-related concept stocks closing up about 6%, Oracle, Dell Technologies, and Meta closing up over 4%, and Microsoft closing up over 3%. Second, the AI hardware supply chain collectively weakened, with the Philadelphia Semiconductor Index performing flat, Broadcom closing down a sharp 6%, and memory and optical communication sectors also underperforming the broader market. Third, divergence appeared within the software sector, with Snowflake closing up over 20% thanks to better-than-expected earnings (management attributed growth to increased penetration of AI products), standing as a rare example of a fundamentally-driven rally.
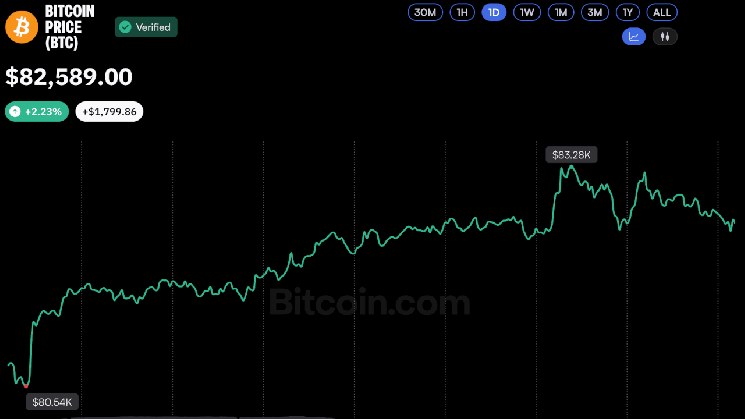
In terms of asset linkages, gold and silver rose roughly 3% in sync, Bitcoin broke through the $80,000 mark, the 10-year U.S. Treasury yield fell about 5 basis points to near 4.75%, and the U.S. Dollar Index weakened. The improvement in risk appetite also transmitted to leading indicators for Asian markets — Hong Kong futures night session rose nearly 1%, and the FTSE China A50 Futures Index gained about 0.3%.
II. Understanding Waller's Remarks: Slower Hikes but Inflation Concerns Unresolved
The direct trigger for this round of market movement was the latest public remarks from Federal Reserve Governor Waller last night: barring surprises in upcoming inflation data, he is inclined to support holding rates steady. This stance was quickly reflected in interest rate futures pricing. According to CME Group's FedWatch Tool, after Waller's speech, traders' probability of a Fed rate hike in the coming weeks was sharply revised down from 63.2% the previous day to 50.4%, a drop of over 12 percentage points.
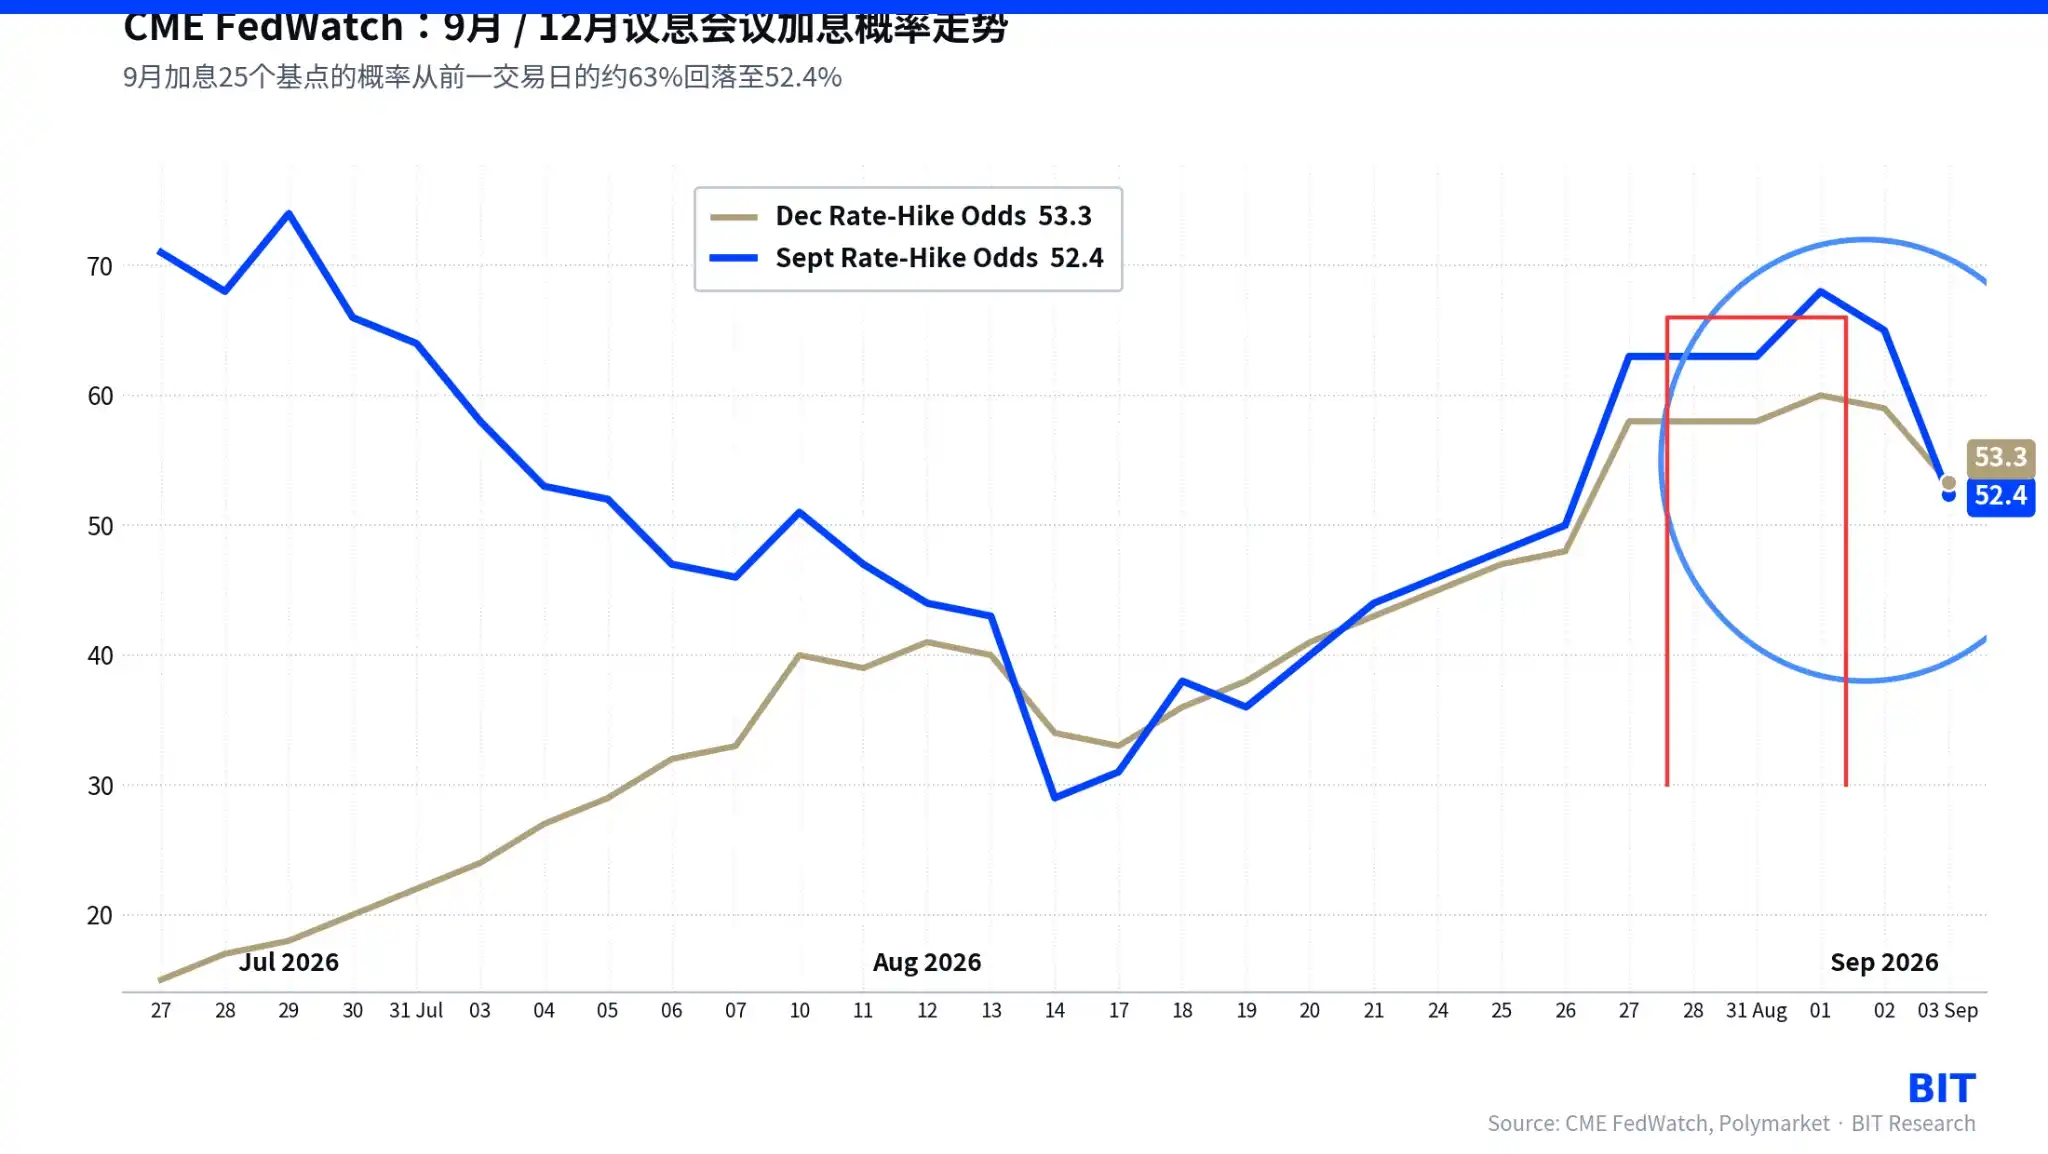
It should be noted that this is not an unconditional dovish signal but rather an intermediate state closer to "slower rate hikes, unresolved concerns." In the period leading up to this, market concerns about a September rate hike had been intensifying, with the core logic being that the pace of disinflation might be interrupted — any marginal rebound in the August CPI reading, even if not significantly exceeding expectations, could be enough to tip the policy scale back towards tightening. Waller's remarks represent a marginal easing of these concerns. He explicitly tied the next interest rate decision to next week's August CPI data release while also expressing cautious optimism about recent signs of inflation improvement and upcoming employment data. In other words, the Fed's current policy reaction function remains unchanged, with inflation still the top priority; only the tolerance for "data surprises" has slightly increased in the short term. This implies that whether this sentiment-driven repair can continue depends heavily on whether next week's data validates this optimism. The core variable of inflation itself has not been truly resolved.
III. The Essence of Structural Divergence: Valuation Repair in Response to Macro Sentiment, Not Industry Logic
From an asset pricing perspective, last night's leading gainers — Tesla, SpaceX-related concepts, Oracle, Dell, Meta, Microsoft, etc. — typically share the characteristics of long-duration, high-valuation growth stocks. Their pricing is significantly more sensitive to the risk-free rate (i.e., U.S. Treasury yields) than value or cyclical assets. The yield decline prompted by Waller's remarks led to an improvement in the discount rate assumption for these assets, providing direct support to their valuations — this is essentially a liquidity and rate expectation-driven valuation repair, not a fundamental change in industry fundamentals.
In contrast, the pricing logic for the AI hardware supply chain is more anchored to capital expenditure cycles and industry competitive dynamics, showing a relatively weaker correlation with short-term interest rate changes. Broadcom closed down 6% at $346.49 — the company's Q3 revenue was $29.6 billion (up 86% year-over-year), with AI revenue reaching $16.7 billion (a massive 221% increase), accounting for 56% of total revenue. The performance itself was quite impressive. However, its Q4 revenue guidance of $34.8 billion was slightly below market expectations of $35.05 billion. The market used this to reassess its potential for replacing Nvidia in the custom AI chip (ASIC) space and the progress thereof. Improvements in the liquidity environment could not offset this specific negative news. The market's vote with its feet reflects lingering fundamental concerns about "increasing revenue without increasing profits."
Snowflake's counter-trend surge provides a meaningful contrast: in the same macro environment, its gains primarily stemmed from its earnings report verifying the monetization capability of its AI products, a typical "fundamentals-driven" rally. This indicates that the market's logic for AI-related industries has entered a phase requiring performance delivery; the phase dominated by narratives and sensitivity to interest rates has passed. Hard data is now required.
IV. Inflationary Pressures Persist: Dual Signals from Trade Data and Geopolitical Oil Prices
Waller's remarks temporarily alleviated market anxiety about rate hikes. However, zooming out to examine the fundamental picture, the concerns underpinning inflation and the threat of exogenous war-related factors have not been dispelled:
From the perspective of trade data, U.S. July import-export figures serve as an important reference for judging the August CPI trend. The goods trade deficit widened further that month, primarily driven by strong domestic import demand: capital goods imports maintained a high growth rate, reflecting that corporate capital expenditure intentions have not been significantly suppressed by high interest rates. Household import demand also showed no apparent weakness. Overall, domestic demand resilience is stronger than market expectations. Meanwhile, export performance remained relatively weak, and the pace of decline in import prices has slowed compared to earlier periods. In summary, the current U.S. economy exhibits a pattern of "supported domestic demand, weak external demand" and has not entered a recessionary cooling phase. This forms the realistic basis for the risk of a marginal rebound in August CPI.
Another clue is the geopolitical transmission chain for oil prices. The previously brokered U.S.-Iran temporary ceasefire, which broke down in mid-August, saw renewed escalation this week, with military confrontations between the U.S. and Iran re-intensifying in the Strait of Hormuz: On August 31, the U.S. launched a new round of strikes against Iran, pushing oil prices higher for the day. From September 1 to 2, U.S. forces further expanded the scope of strikes, destroying approximately 100 military targets within Iran and, for the first time using a "tanker-for-tanker" reciprocal retaliation method, struck two Iranian government oil tankers anchored near the Iranian coast. Iran retaliated by firing about 25 ballistic missiles and dozens of drones towards a U.S. military base near Jordan, most of which were intercepted or missed. As a result, Brent crude briefly spiked to around $97 per barrel, with WTI holding above $90 per barrel. Only because the market interpreted the U.S. military actions as "restrained," coupled with the implementation of the OPEC+ September production increase plan, did the upward momentum fail to expand further. Oil prices overall are consolidating at high levels rather than trending downward.
Looking ahead to next week's CPI release, the marginal risk of energy prices pulling up the August CPI has not been eliminated. Should the situation in the Strait of Hormuz see further deterioration or even impact shipping traffic, imported inflationary pressures could become more explicit.
Notably, the reason safe-haven assets like gold could rise in sync last night despite elevated oil prices is essentially due to the improvement in liquidity expectations brought by Waller's remarks, which temporarily outweighed the potential negative of rising energy costs in the short term. However, this combination of "rate-friendly expectations hedging energy risks" is not stable. If next week's CPI confirms that the energy component is exerting a substantive pull on overall inflation, the market's optimistic pricing based on Waller's dovish signals will face correction pressure. In other words, the easing of macro sentiment is real, but the deeper issue of inflation remains unresolved for now.
V. Outlook for Next Week's CPI: Three Scenarios and Asset Pricing Paths
Next week's release of the August CPI data will be the most significant piece of information before the Fed's September FOMC meeting. Reviewing the previously released July data, CPI was 3.4% year-over-year, core CPI was 2.5% year-over-year. While there was marginal easing compared to before, a significant gap remains from the 2% policy target, indicating the inflation foundation is still not solid. Considering factors like domestic demand resilience and geopolitical oil price risks, after next week's CPI release, the market is likely to evolve along the following three general paths:
1. **CPI Higher Than Expected:** The disinflation rhythm is substantively interrupted. The market will increase the probability of a September and subsequent rate hikes. The gains from this round of expectation-driven repair face a significant risk of retracement. Long-duration growth stocks, precious metals, crypto assets, and other interest-rate-sensitive assets will be the first to bear the brunt of the pressure.
2. **CPI Largely In Line With Expectations:** The Fed is highly likely to continue its "on hold" policy path, but officials' rhetoric is expected to maintain a cautious tone. The November FOMC meeting will likely continue to be viewed by the market as a potential policy observation window. Risk assets are likely to maintain a range-bound, volatile pattern.
3. **CPI Significantly Lower Than Expected:** The disinflation trend is reconfirmed. The consensus expectation for a relaxation of the conditions triggering rate hikes will be further solidified, potentially even opening space for market discussion about a more accommodative policy path within the year. The current repair rally could gain further support from the fundamentals side, with the potential to extend in both duration and magnitude beyond current expectations.
It is important to emphasize that the nature of this rebound is closer to a phase of repair in expectations. The Fed has not signaled the start of a rate-cutting cycle; the overall monetary policy stance remains relatively tight. Before the August CPI data lands, directional certainty in overseas markets remains relatively low, with implied volatility at elevated levels. Short-term volatility and pullback risks should not be underestimated.
**Disclaimer:** This article is for reference only and does not constitute any investment advice or product offer. Data is as of the U.S. stock market close on September 3, 2026 (Eastern Time), sourced from public information. The company does not guarantee its accuracy or completeness. The article contains forward-looking judgments; actual results may differ materially. Investment involves risks; prices may rise or fall, past performance is not indicative of future results, and investors may lose their entire principal. Product availability is subject to local laws and regulatory restrictions. Please conduct your own assessment and consult independent professional advice.