85% of concentrated liquidity is underutilized — Meaning for DeFi?

ambcryptoPublicado a 2026-07-18Actualizado a 2026-07-18

Resumen

A recent Dune report reveals that concentrated liquidity, designed to enhance capital efficiency in decentralized exchanges, is largely underutilized. In the first half of 2026, an average of 29.4% of liquidity across major protocols like Uniswap v3/v4, PancakeSwap v3, and Aerodrome Slipstream was idle—outside active trading ranges—resulting in no fee generation. This represents about $542 million in idle capital weekly and an estimated $150 million in lost annual fees for LPs. When considering technically available but unused liquidity, the underutilization rate rises to approximately 85%. The study indicates that much of this idle capital, particularly over $200 million untouched for more than 90 days, stems from liquidity providers not actively managing their positions. Individual investors, not automated managers, hold the vast majority of this idle liquidity (e.g., 94% on Ethereum). Automated managers maintain far more active and in-range positions. Notably, Uniswap v4 has not resolved the issue; about 30.5% of its liquidity remains out of range, and while it introduced hooks for external yield strategies, only 10% of its TVL uses them, with none currently generating yield from idle capital.

A significant amount of the liquidity that users contribute to decentralized exchanges isn’t really being used to speed up trades, according to a recent report by Dune.

To put things in perspective, concentrated liquidity was created to increase the capital efficiency of decentralized exchanges. This was done by enabling liquidity providers (LPs) to distribute funds within particular price ranges where trading is most likely to take place.

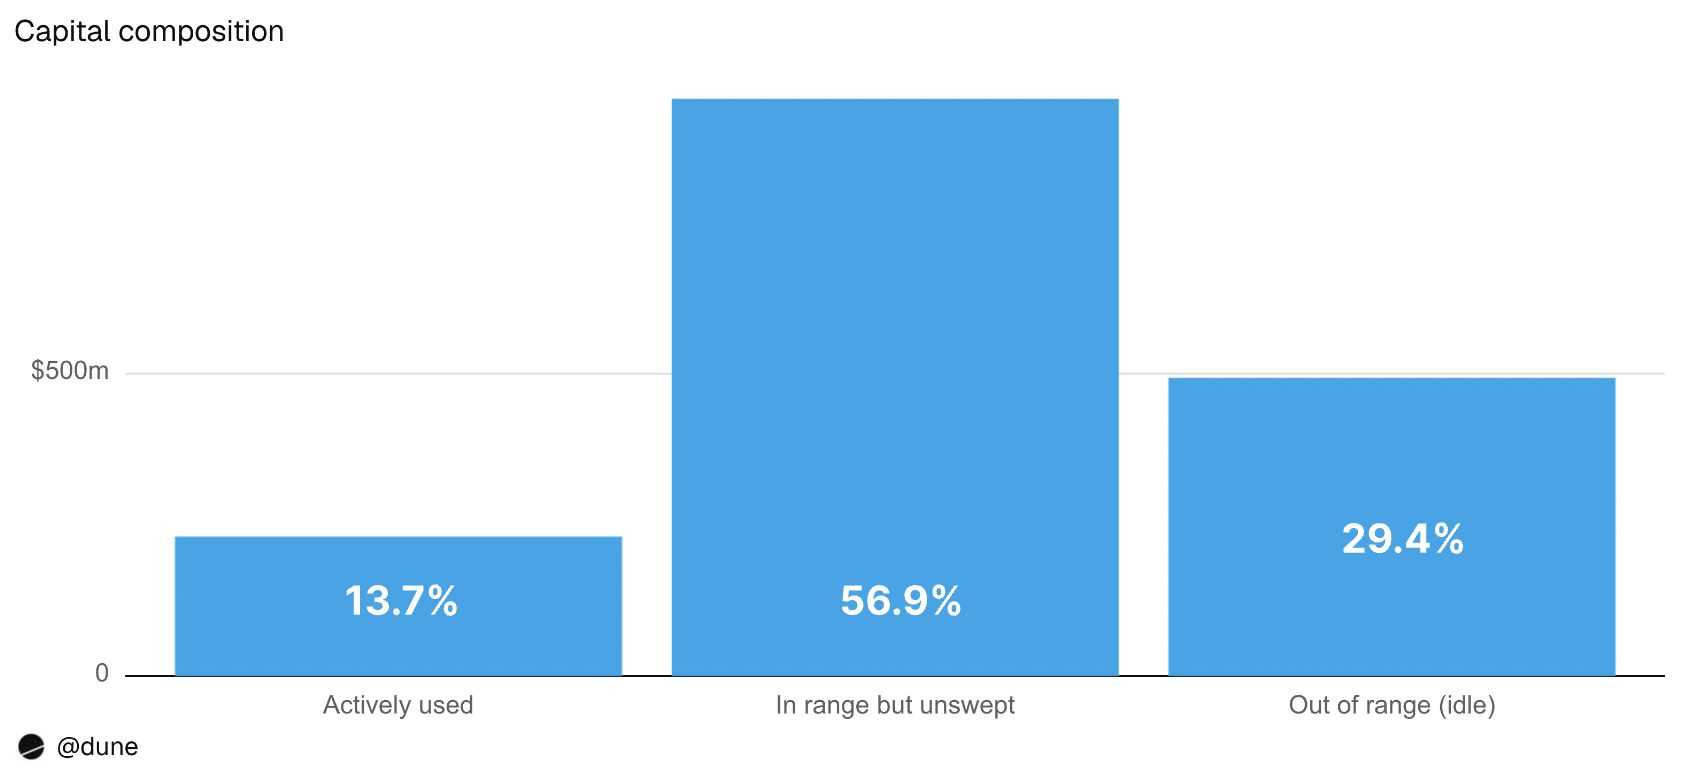
However, the study discovered that during the first half of 2026, an average of 29.4% of liquidity was outside the range of active trading. Thanks to the same, no trading fees were generated.
Source: Dune

This amounted to approximately $542 million in idle capital per week and an estimated $150 million in lost annual fee income for liquidity providers across the four protocols.

For context, the 4 protocols included were Uniswap v3, Uniswap v4, PancakeSwap v3, and Aerodrome Slipstream.

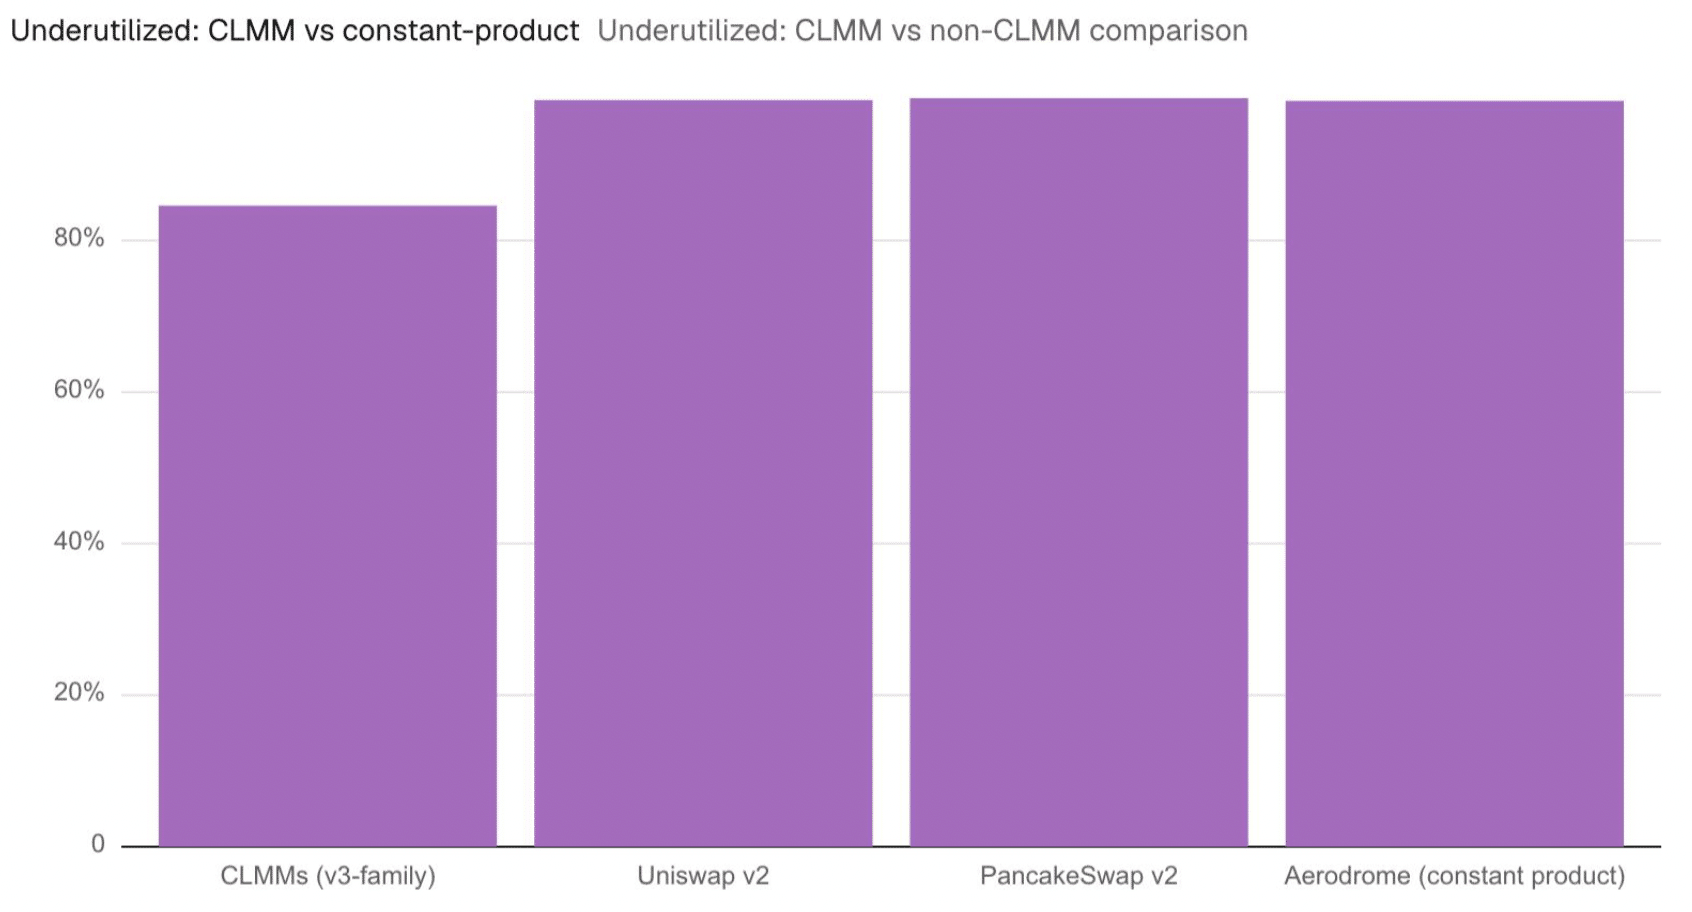
Underutilized concentrated liquidity

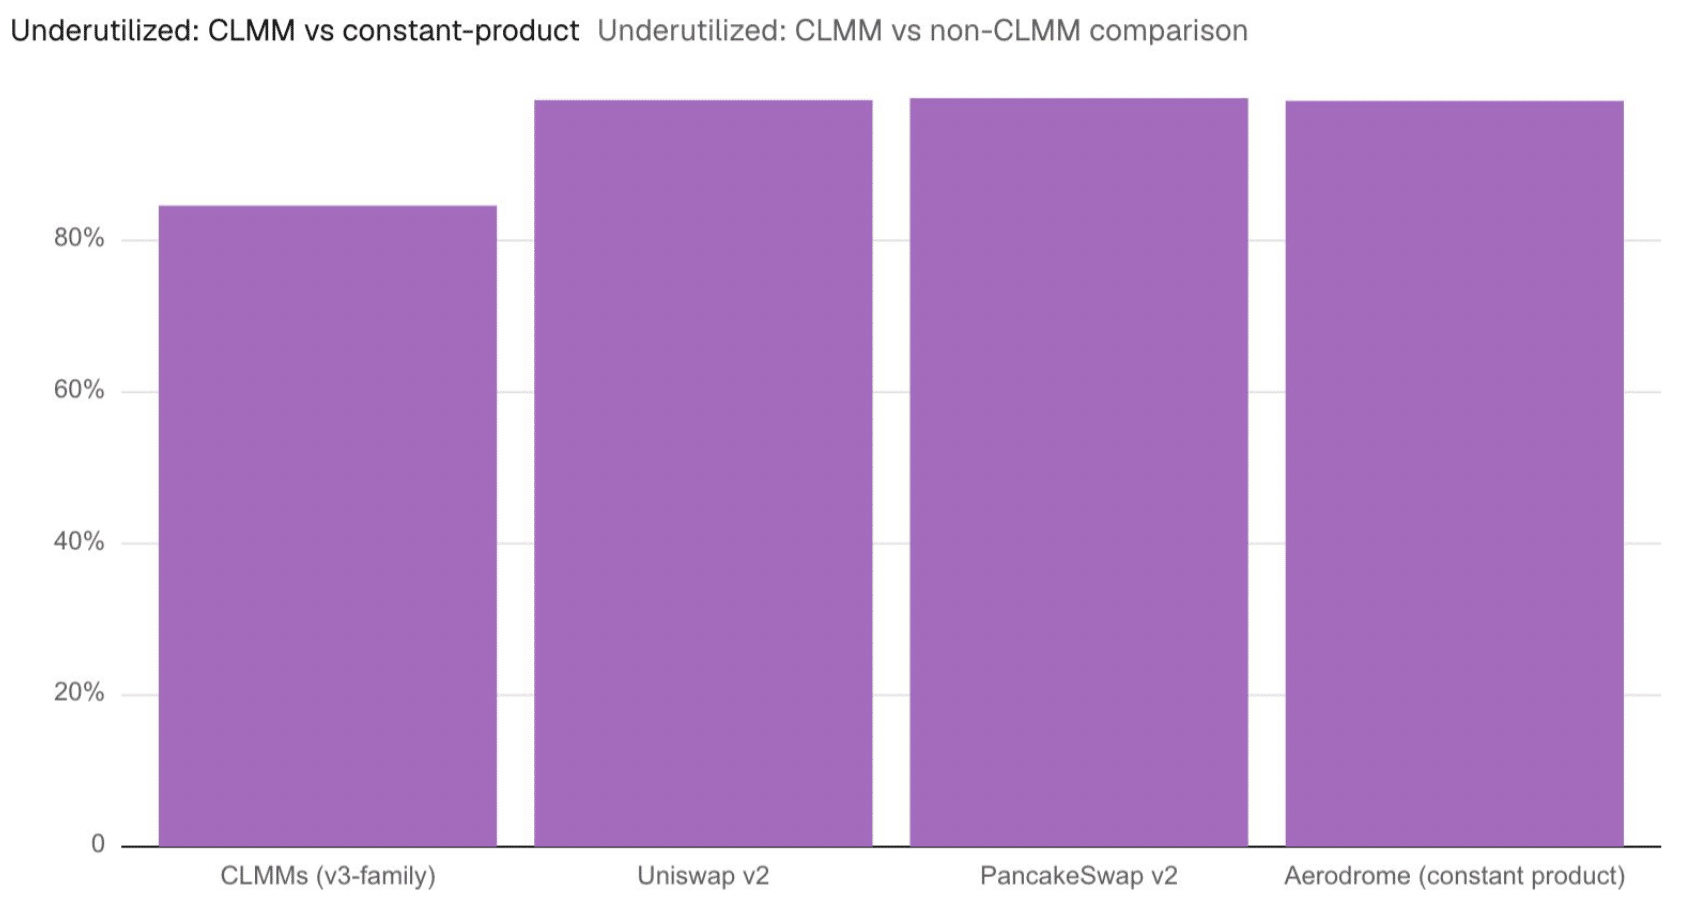
Considering technically available but never used liquidity, about 85% of capital was underutilized.
Source: Dune

The fact that more than $200 million in idle liquidity had not been repositioned in more than 90 days may be evidence that many LPs do not actively manage their holdings.

This also suggested that even though concentrated liquidity should increase efficiency, many LPs still find it difficult to maintain their positions in line with market prices.

Individual investors suffered the most

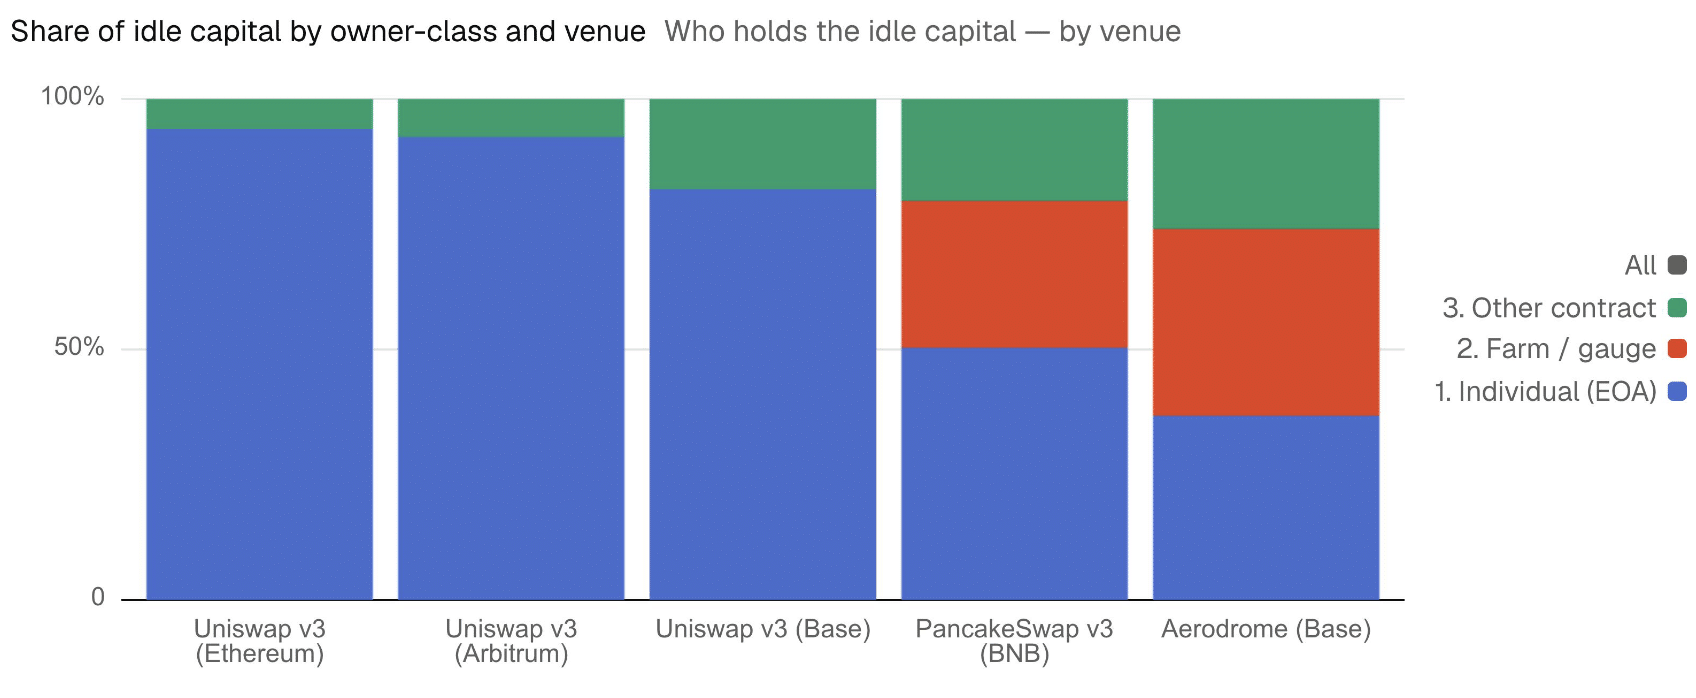
Additionally, the study discovered that automated managers maintained capital activity, while individual investors owned the majority of idle liquidity.

Wallets on Ethereum, for instance, had 94% of idle capital and 91% of Uniswap v3 liquidity. 92% of idle liquidity and 78% of liquidity were under control on Arbitrum. On Base, individual users oversaw 82% of the idle capital, even though smart contracts held roughly 50% of the liquidity.
Source: Dune

This, because only 6.5% of their positions were out of range, compared to about 30% for wallets. This also indicated that automated managers have been far more successful than individual LPs at maintaining liquidity.

Additional loopholes

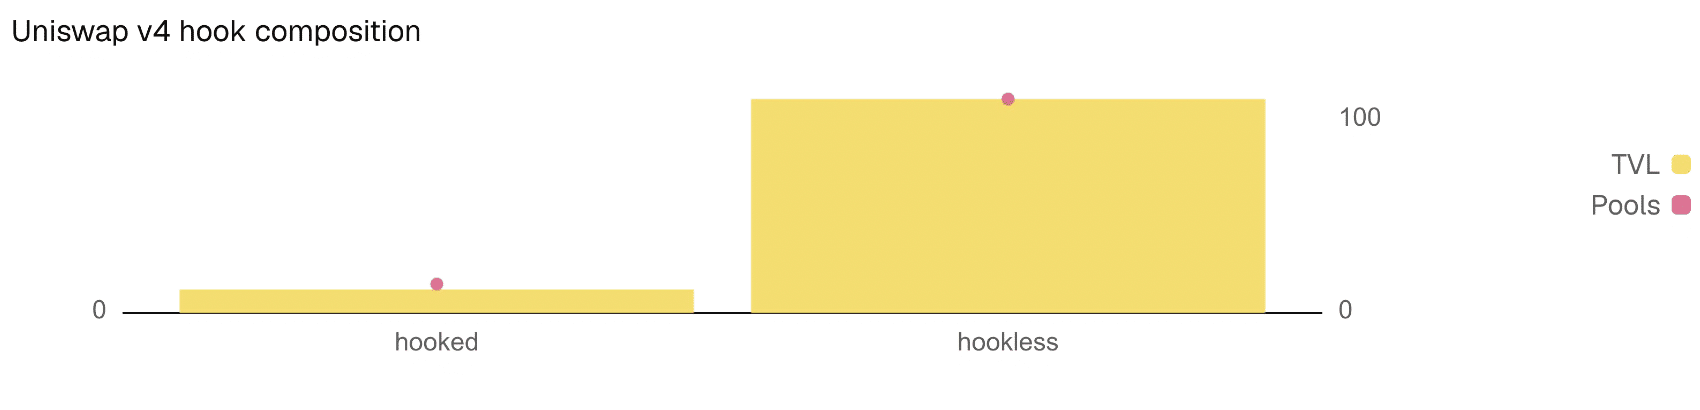
Finally, the study found that the idle liquidity issue has not been resolved by Uniswap v4.

Like Uniswap v3, about 30.5% of its liquidity is still out of range even after hooks were added that might allow idle capital to be used in external yield strategies.

Also, just 10% of v4’s TVL actually uses hooks while none of them produce yield from idle liquidity at the moment.
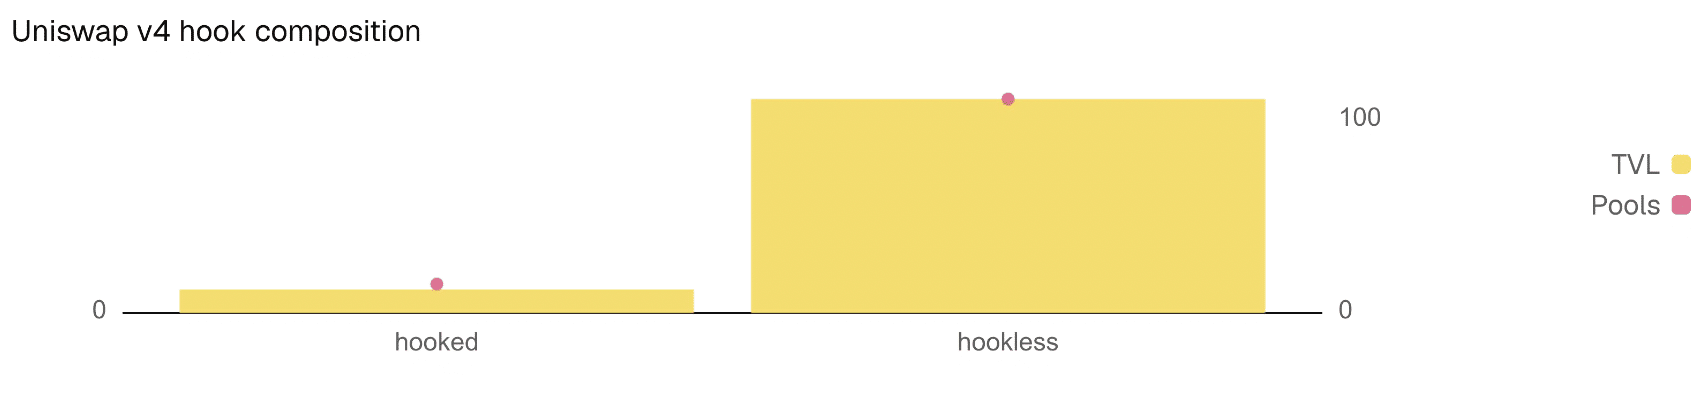
Source: Dune

Final Summary

  • In H1 2026, approx. 29.5% of liquidity was outside the range of active trading.
  • Instead of AMMs, individual investors owned the majority of idle liquidity.

Preguntas relacionadas

QAccording to the report, what percentage of concentrated liquidity was found to be underutilized when considering technically available but never used capital?

AApproximately 85% of capital was underutilized.

QWhat was the estimated annual lost fee income for liquidity providers across the four protocols studied (Uniswap v3, Uniswap v4, PancakeSwap v3, Aerodrome Slipstream)?

AAn estimated $150 million in annual fee income was lost.

QWhich group of users was found to own and control the majority of the idle liquidity, according to the study?

AIndividual investors (wallets) owned and controlled the majority of the idle liquidity, as opposed to automated managers.

QHas the introduction of hooks in Uniswap v4 successfully resolved the idle liquidity issue?

ANo, it has not. Like Uniswap v3, about 30.5% of Uniswap v4's liquidity remains out of range, and currently, none of the hooks in use produce yield from idle liquidity.

QWhat does the high amount of liquidity not repositioned for over 90 days suggest about many liquidity providers (LPs)?

AIt suggests that many LPs do not actively manage their holdings, finding it difficult to maintain their positions in line with market prices despite the design of concentrated liquidity to increase efficiency.

Lecturas Relacionadas

G7 Warning on Quantum Attacks Accelerates Transition to New Cryptographic Security System

The G7 cybersecurity working group urges countries and businesses to immediately begin transitioning to post-quantum cryptography, a warning directly relevant to crypto networks, exchanges, and custodians who must undertake costly system upgrades before quantum computers threaten modern encryption. Their report, while not mentioning cryptocurrencies specifically, highlights the risk quantum computing poses to public-key cryptography, which underpins crypto transactions. A key concern is the "harvest now, decrypt later" strategy, where encrypted data is collected for future decryption, a threat also applicable to blockchain's publicly visible keys. Europe has set concrete deadlines, mandating that all EU member states begin their transition by the end of 2026, with high-risk systems completing it by 2030. This shifts quantum readiness from a technical issue to a regulatory and competitive necessity. Bitcoin and Ethereum are pursuing different upgrade paths. Bitcoin's BIP-360 proposal aims to mitigate long-term quantum vulnerabilities, while Ethereum's broader roadmap targets upgrades to validator signatures, commitments, and zero-knowledge proofs by 2029. A major challenge is the increased data size of post-quantum signatures, which could raise storage, bandwidth, and transaction costs. The immediate market risk is not a quantum attack itself, but the complex preparation for it: governance debates, protocol development, infrastructure changes, and the vulnerability of old wallets with exposed keys. With entities like Google accelerating their migration timelines and NIST proposing phase-out dates for current standards, having a migration plan is becoming a competitive advantage.

cryptonews.ruHace 7 hora(s)

G7 Warning on Quantum Attacks Accelerates Transition to New Cryptographic Security System

cryptonews.ruHace 7 hora(s)

Trading

Spot
活动图片