Citi's Interpretation: Why Does Citi Still Give SanDisk a Target Price of $2500 After Earnings Report Despite a Significant Stock Price Drop?

marsbitPublicado a 2026-08-07Actualizado a 2026-08-07

Resumen

Citi maintains a "Buy" rating on SanDisk with a $2500 price target despite a post-earnings stock drop. This target, implying an 85.1% upside from the August 5th close of $1350.50, hinges on the firm's view that SanDisk merits a higher valuation than traditional NAND cyclical stocks. Although SanDisk reported strong Q4 FY26 results with revenue up 51% sequentially and robust full-year data center growth (+437%), its stock fell sharply on August 6th. Investors are concerned about potential NAND price growth moderation and guidance that failed to meet elevated market expectations. Citi's bullish thesis centers on SanDisk's new long-term "New Business Model" (NBM) agreements. These contracts, covering a significant portion of its NAND bit output for FY27 and FY28, represent minimum revenue commitments of approximately $94 billion backed by financial guarantees. This structure aims to increase revenue and cash flow predictability. The report links this visibility to AI data center demand, driven by the expansion of inference workloads requiring more storage. Citi estimates data center storage capacity demand will grow about 35% in CY27. However, the analysis notes long-term contracts cannot eliminate the NAND cycle. Risks include potential oversupply from industry capacity expansion, competition, and macroeconomic headwinds. The $2500 target essentially bets that AI demand and these contracts can reduce earnings volatility enough to support a premium valuation (~11x CY27E EPS)...

On August 5th, Citi published a management call-back report, giving SanDisk a 'Buy' rating with a target price of $2500. Based on the closing price of $1350.50 on August 5th used in the report, this corresponds to an expected stock return of 85.1%.
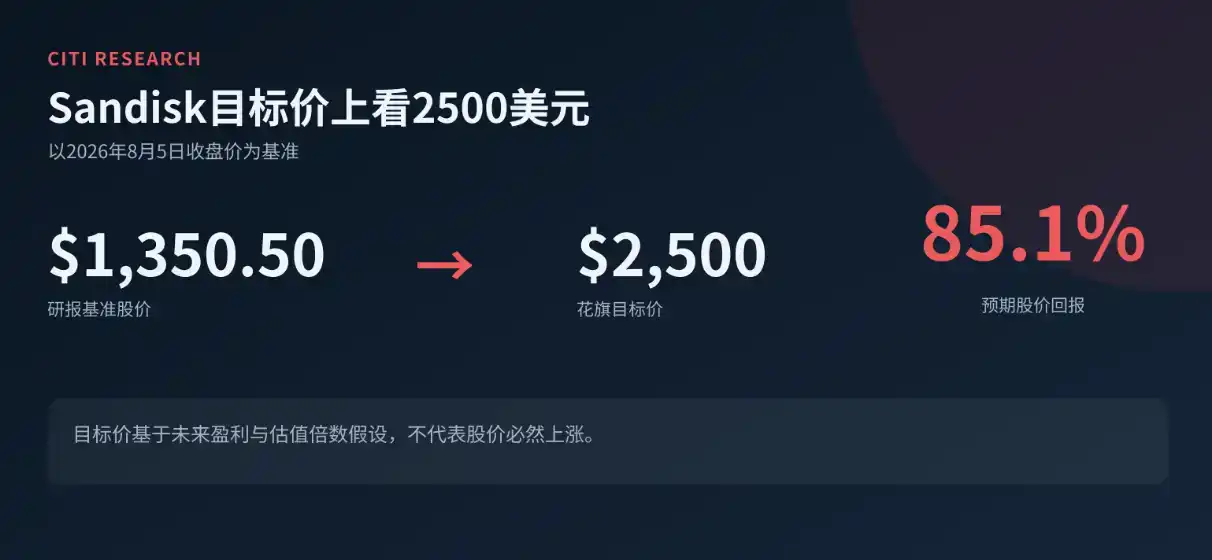
This target price does not guarantee that SanDisk's stock will necessarily rise another 85%. It is based on Citi's assumptions about future earnings and valuation multiples, and the so-called 'upside potential' changes with market prices.

In fact, following the release of strong earnings, SanDisk's stock price did not continue to rise. According to Reuters, the company's stock price fell as much as 13.3% intraday on August 6th to $1178. Market concerns primarily focus on the potential slowdown in NAND price increases and the company's guidance not meeting investors' previously formed higher expectations.

The truly noteworthy aspect of this report is not just the $2500 target price, but Citi's attempt to redefine SanDisk: Can AI data center demand and long-term contracts allow it to command a valuation higher than that of traditional NAND cyclical stocks?
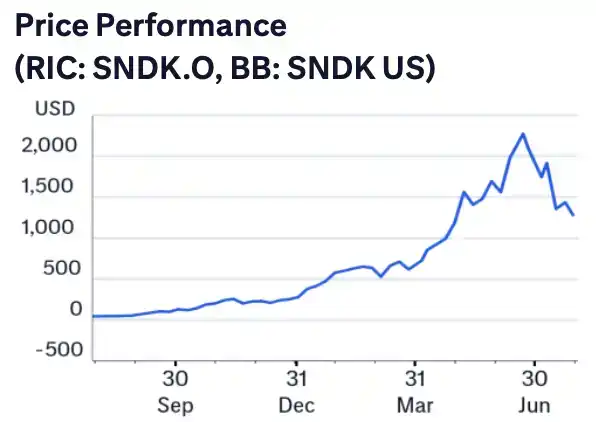
SanDisk's stock performance versus Citi's $2500 target price. Citi set the $2500 target based on SanDisk's August 5th closing price of $1350.50, corresponding to an expected 85.1% stock return. Source: Citi Research

Why Did the Stock Price Drop Sharply Despite Strong Earnings?

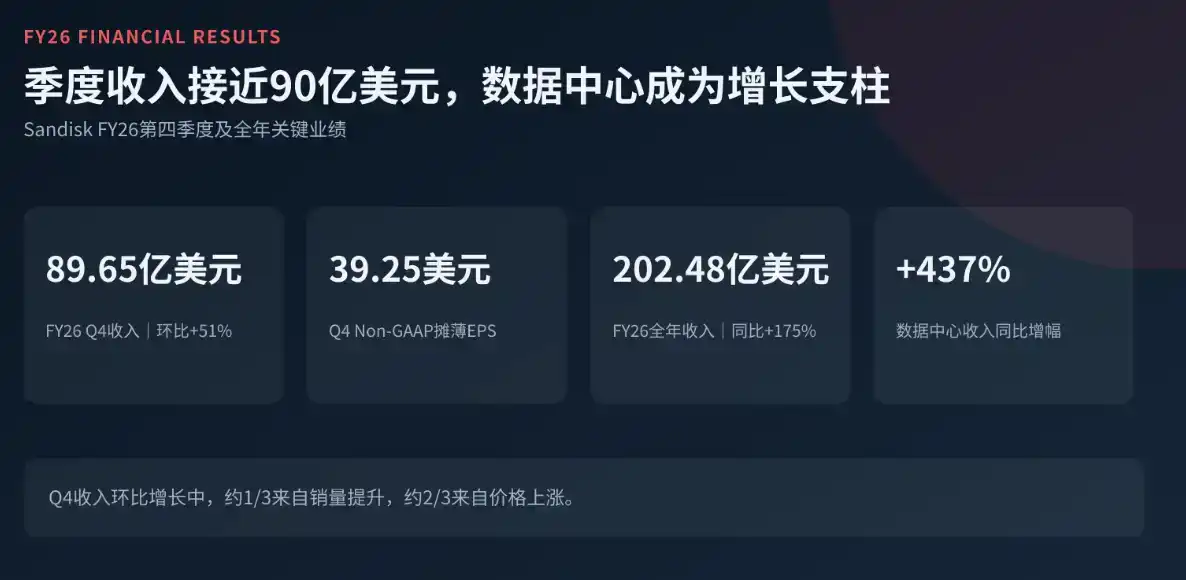
SanDisk reported FY26 Q4 revenue of $8.965 billion, a 51% sequential increase; Non-GAAP diluted EPS was $39.25.

FY26 full-year revenue was $20.248 billion, a 175% year-over-year increase; Data Center business revenue grew 437% year-over-year. The company expects FY27 Q1 revenue to be between $10.3 and $10.8 billion, with Non-GAAP diluted EPS between $44 and $46.

These figures confirm that the Data Center has become a key growth pillar for SanDisk. The company stated that approximately one-third of the sequential revenue growth in Q4 came from volume increases, and about two-thirds from price increases. This indicates that the current performance growth relies on data center demand, product mix improvement, and strong NAND prices.

However, the stock price decline after the earnings report also reflects that the market's expectations have been significantly raised. With SanDisk's stock price having risen substantially beforehand, investors are no longer just concerned about whether AI storage demand is growing, but how long NAND prices can continue to rise and whether profit forecasts can be revised upward again.

The company's guidance for FY27 Q1 revenue, while still strong, failed to meet the higher unofficial expectations of some investors. The potential slowdown in price increase rates has also led the market to reevaluate the sustainability of the current high profit margins.
Why is Citi Willing to Give a Higher Valuation Based on the $94 Billion Long-term Contracts?

Citi's core rationale for its bullish view on SanDisk is the company's so-called 'New Business Model' (NBM) long-term agreements.

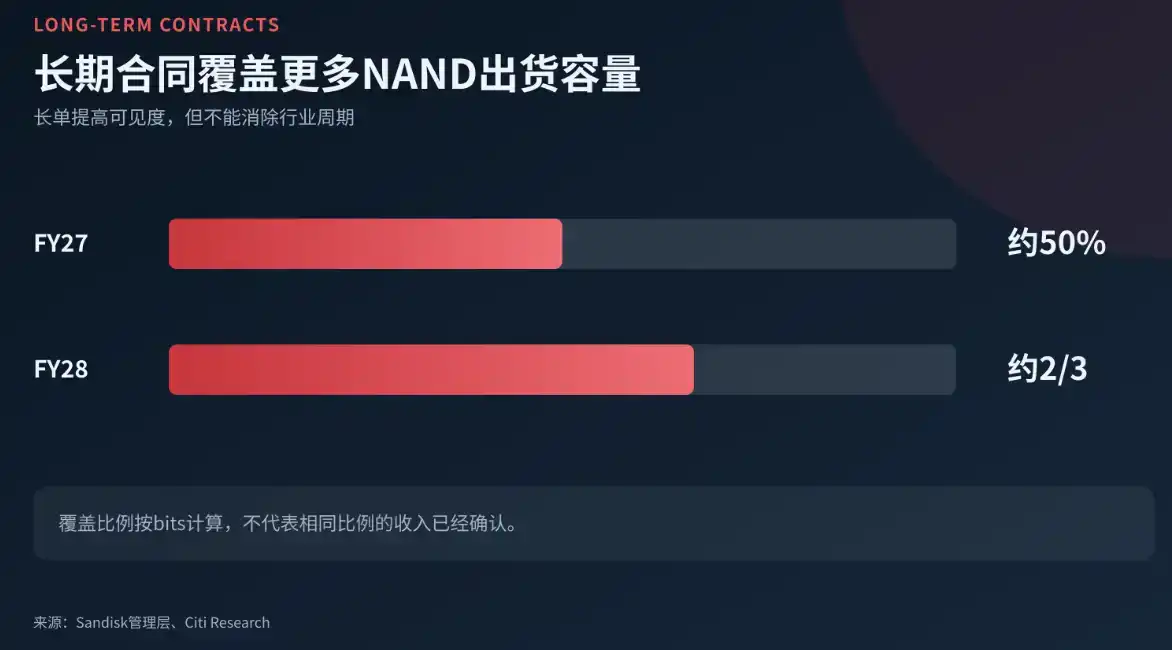
According to management's communication to Citi during the post-earnings call-back, long-term contracts already cover approximately 50% of SanDisk's FY27 bits, and about two-thirds of FY28 bits. 'Bits' here refers to NAND shipment capacity, not revenue share.

The average term of these contracts exceeds four years, corresponding to approximately $94 billion in minimum revenue commitments, with about $16.5 billion in financial guarantees attached.

The report does not disclose specific purchase volumes for different customers, price adjustment mechanisms, or guarantee trigger conditions. Therefore, the $94 billion cannot be directly understood as confirmed accounting revenue. More accurately, subject to normal contract fulfillment, the company has secured significant minimum revenue commitments.

SanDisk's official earnings announcement shows that since announcing five NBM agreements in the April earnings call, the company has signed five more agreements, including three with new customers and two expansions of existing agreements.

Long-term contracts are changing how investors view SanDisk. NAND has historically been a typical cyclical industry: prices rise and profits expand when demand is strong, but subsequent capacity releases can lead to oversupply. The company's revenue and profits are easily impacted by quarterly prices, inventory, and customer purchasing patterns.

Long-term contracts cannot eliminate this cycle but can lock in part of the shipment volume and minimum prices in advance, improving the predictability of future revenue and cash flow.
Citi believes this revenue visibility is sufficient to support SanDisk achieving a higher valuation multiple than traditional NAND companies. The report values SanDisk at approximately 11 times CY27E EPS, higher than the median of about 8x for Kioxia and the broader peer range of 6 to 8 times.

Citi's forecast table separately lists SanDisk's FY27 EPS as $222.15 and FY28 EPS as $225.88. Note that FY27 and CY27 are different time frames; the FY27 EPS of $222.15 should not be directly taken as the CY27 EPS used in the target price calculation.
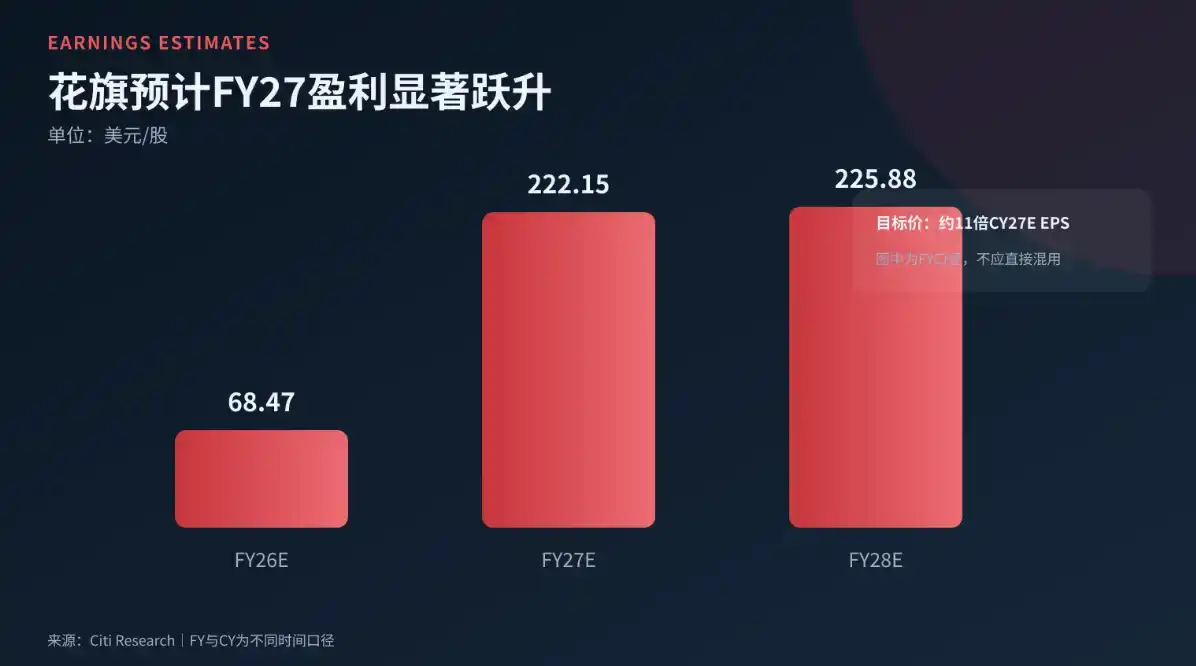
Citi's EPS forecasts for SanDisk. Citi expects SanDisk's FY27 EPS to be $222.15 and FY28 EPS to be $225.88; its $2500 target price uses a valuation of approximately 11 times CY27E EPS. CY and FY timeframes should not be directly mixed. Source: Citi Research

AI Inference Expansion: Data Centers Need More Storage

SanDisk's NAND flash solutions cover SSDs, memory cards, USB drives, portable storage devices, and automotive storage products. However, the market's current focus is on enterprise SSDs, particularly products for cloud providers and data center customers.

Management told Citi that hyperscale cloud providers are expanding their NAND procurement commitments after signing initial agreements, driven primarily by the evolution of AI inference demand and rising cloud capital expenditures.

AI infrastructure isn't just about GPUs and HBM. As inference workloads expand, data centers also need more storage devices to hold models and business data. Enterprise SSDs' advantages in access latency, power consumption, and deployment density mean NAND is also a beneficiary of AI infrastructure expansion.

The Citi report forecasts that CY27 data center storage capacity demand will grow by about 35%. This metric measures exabyte capacity demand, not sales. Actual revenue growth will also be affected by NAND prices, product mix, and customer contract terms.

Management also stated there is currently no indication that customers' difficulties in obtaining DRAM are slowing NAND deployment. If cloud providers delay deployment due to shortages of DRAM, HBM, or other server components, related NAND demand could also be postponed. However, at least during this call-back, SanDisk had not observed this happening.
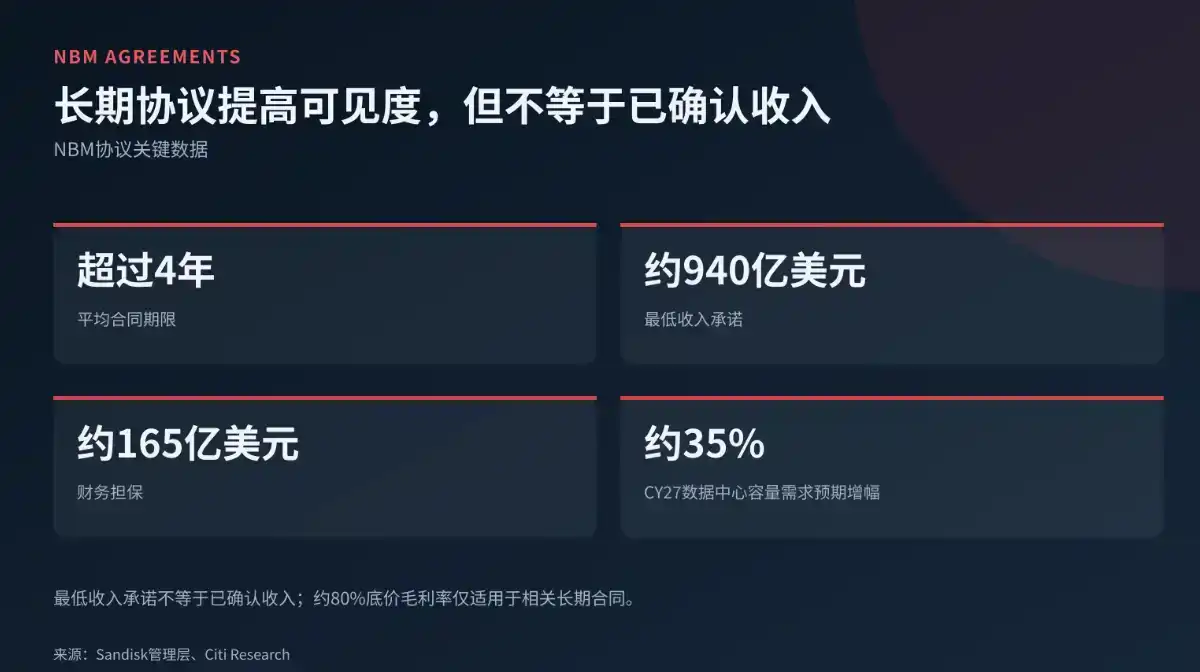
Long-term Contracts Reduce Earnings Volatility but Cannot Eliminate the NAND Cycle

Beyond shipment volume, the pricing of long-term contracts is also a key factor in Citi's bullish view.

According to management's communication to Citi, the gross margin for these long-term contracts when executed at the floor price is approximately 80%; if market prices exceed the contract floor price, profit margins may receive further support.

This figure is impactful but must be confined to the scope of the long-term contracts. It cannot be interpreted as SanDisk's overall business having a permanent 80% gross margin guarantee, nor does it mean all contracts will be executed under identical price and cost structures.

SanDisk's FY26 Q4 overall gross margin was 84.6%, and the company's guidance for FY27 Q1 gross margin is 83% to 85%. Citi states this guidance reflects business mix and rising SSD component costs, not weakening NAND prices.

The company's current inventory of about 170 days is another variable to watch. Management said the higher inventory is a proactive buffer built to meet long-term contract commitments; rising costs of SSD components like DRAM have also increased inventory value.

Therefore, high inventory cannot be simplistically equated with weak demand, but it's not without risk. If NAND price increases continue to slow, the impact of inventory costs, contract pricing, and delivery timing on profits could be amplified by the market.

The supply side also hasn't disappeared. SanDisk and Kioxia jointly develop and produce NAND wafers through Flash Ventures. Company filings with the SEC show the relevant joint venture arrangement currently extends to 2034, but SanDisk also bears approximately half the fixed costs and corresponding capital investments.

This collaboration provides a long-term supply foundation but does not mean SanDisk has unlimited, cost- and industry-cycle-agnostic capacity.

Citi notes that if underutilized industry capacity is reactivated, supply and demand could turn to surplus relatively quickly; expansion by Chinese manufacturers, price competition, and a deteriorating macroeconomic environment could also impact enterprise SSD demand and profit margins.

Therefore, the $2500 target price is not really betting that the NAND cycle has disappeared, but that AI data center demand and long-term contracts can reduce the quarterly volatility of SanDisk's earnings, allowing it to achieve a valuation higher than traditional cyclical stocks.

Going forward, the market needs to observe four variables: the execution pace of the $94 billion minimum revenue commitments, the contract price adjustment mechanisms, whether data center capacity demand materializes as expected, and whether industry capacity recovers faster than demand.


Preguntas relacionadas

QAccording to Citi's report, what is the key reason behind their 'Buy' rating and $2500 price target for SanDisk despite the post-earnings stock drop?

ACiti's bullish view is primarily based on SanDisk's new long-term agreements, or 'New Business Model' contracts, which cover a significant portion of its future NAND bit shipments and guarantee a minimum of approximately $94 billion in revenue. This is expected to reduce earnings volatility and justify a higher valuation multiple compared to traditional cyclical NAND companies.

QWhy did SanDisk's stock price fall significantly after it released strong quarterly earnings?

AThe stock price fell due to market concerns that the rate of NAND price increases might slow down. Furthermore, the company's guidance for the following quarter, while still strong, did not meet some investors' informal, higher expectations that had been built up during the prior significant stock rally.

QWhat role does AI infrastructure play in the demand for SanDisk's products, according to the article?

AAI infrastructure expansion, specifically the growth of AI inference workloads, is driving demand for more storage in data centers. As these workloads evolve, data centers require more storage devices like enterprise SSDs to hold models and business data, making NAND a beneficiary of AI infrastructure growth.

QWhat is the implied gross margin for SanDisk's long-term contracts when executed at their floor prices, and what is a key limitation of this figure?

AThe implied gross margin for these long-term contracts, when executed at their floor prices, is approximately 80%. However, this figure is limited to the scope of these specific contracts and should not be misinterpreted as a guarantee of a permanent 80% gross margin for SanDisk's overall business.

QWhat are the key risks to Citi's optimistic thesis and $2500 price target for SanDisk, as mentioned in the article?

AKey risks include: 1) The potential for underutilized industry capacity to be brought back online, quickly shifting the supply-demand balance; 2) Expansion and price competition from Chinese manufacturers; 3) A deterioration in the macroeconomic environment impacting enterprise SSD demand and margins; and 4) The need to monitor the execution of the $94 billion minimum revenue commitments and the associated price adjustment mechanisms.

Lecturas Relacionadas

Founders Fund Leads $5 Million Token Purchase of ANVL: What Exactly is This "Non-Lending" DeFi Protocol Doing?

On October 6th, Founders Fund, led by Peter Thiel, invested $5 million to purchase ANVL tokens from the DeFi protocol Anvil's treasury. The round included participation from Pantera Capital and others, alongside angel investors like Compound founder Robert Leshner. Anvil is not a lending protocol. Instead, users lock assets like ETH or USDC into its vault to generate a verifiable on-chain "Letter of Credit" (LOC). This LOC acts as an economic guarantee, proving the user has sufficient locked collateral to back financial commitments, without borrowing funds. The protocol applies this mechanism to use cases like payment guarantees for merchants (via integration with Flexa) and enabling instant deposits for traders on exchanges like Bullish. Anvil's economic model is unique: it charges zero protocol fees. Its native token, ANVL, derives value solely from governance rights over parameters like supported collateral types. The total supply is 100 billion tokens. Despite an 83% price surge on the investment news, ANVL remains down approximately 89% from its all-time high. The protocol's Total Value Locked (TVL) has also fallen about 87% from its peak of ~$109 million in July 2025 to around $14 million currently. The investment represents a strategic bet that on-chain credit guarantees could become a significant category. Key factors to watch include the rate of real enterprise adoption through Anvil's SDK, the long-term sustainability of its zero-fee model, and the broader migration of traditional trade finance needs to blockchain infrastructure.

marsbitHace 1 hora(s)

Founders Fund Leads $5 Million Token Purchase of ANVL: What Exactly is This "Non-Lending" DeFi Protocol Doing?

marsbitHace 1 hora(s)

Mathematical Explosion: OpenAI Overnight Solves 722 Math Problems, Quasi-Riemann Hypothesis Proven

OpenAI has stunned the global mathematics and AI communities by releasing a GitHub repository containing 722 manuscripts addressing 372 previously unresolved major mathematical problem families, all reportedly generated by an unreleased internal AI model. The announcement, made without prior peer review, has provoked both excitement and alarm among mathematicians. The most notable breakthrough claims to be a proof of a "quasi-Riemann Hypothesis," establishing a zero-free region for Dirichlet L-functions with real part greater than 7/8 and eliminating the Landau-Siegel zeros—a significant leap in analytic number theory. The work has reportedly undergone formal verification using Lean. Other highlighted results include: unconditionally proving the NP-hardness of the basic semidefinite programming (SDP) threshold for approximation algorithms, based solely on P ≠ NP and circumventing the Unique Games Conjecture; proving the rational Hodge conjecture for abelian varieties with complex multiplication (CM); and resolving both the symmetric and asymmetric Mahler conjectures in convex geometry. According to OpenAI, most proofs were generated automatically by the model, with an average "thinking" time of just three hours per problem. This unprecedented scale and speed have sparked intense debate about the future of human mathematicians. While some express fear about the concentration of intellectual power, others see it as the dawn of a new era of discovery driven by AI. The mathematical world is now tasked with scrutinizing these claims, which, if verified, would represent historic milestones.

marsbitHace 1 hora(s)

Mathematical Explosion: OpenAI Overnight Solves 722 Math Problems, Quasi-Riemann Hypothesis Proven

marsbitHace 1 hora(s)

As Midterm Elections Approach, the Real Trade in U.S. Stocks Isn't About Who Wins

With the US midterm elections approaching in early November, political uncertainty has re-emenrged as a market variable. While market participants are weighing potential shifts in congressional control and policy direction, historical data suggests midterm elections themselves are not a definitive negative catalyst for US equities. Since 1937, the S&P 500 has averaged a positive gain of 9.2% in midterm election years, though this lags behind the 13.3% average for non-election years. A more consistent historical pattern is increased market volatility and a tendency for stronger performance concentrated in the fourth quarter, as political uncertainty is resolved. The article, citing analysis from J.P. Morgan and Capital Group, argues that the market's primary concern is policy path uncertainty rather than which party wins. This uncertainty tends to depress markets in the run-up to the vote, with a potential rebound afterward as the political risk premium dissipates. However, the article cautions against attributing market performance solely to the election. Recent midterm years like 2018 and 2022 saw significant market declines primarily driven by factors like Federal Reserve tightening and inflation, not the election outcome itself. The core argument is that the midterm election's impact on markets is often secondary to more fundamental drivers. Regardless of whether the result is a unified or divided government, the market's longer-term trajectory has historically been determined by underlying economic conditions. For the current environment, the key variables to watch post-election are not political labels but the path of interest rates, corporate earnings trends, and whether any actual policy changes materially alter cash flow expectations for businesses. The election may influence sentiment and policy expectations, but the sustainability of any year-end rally will ultimately depend on these core fundamentals of profitability, rates, and economic data.

marsbitHace 1 hora(s)

As Midterm Elections Approach, the Real Trade in U.S. Stocks Isn't About Who Wins

marsbitHace 1 hora(s)

AI Can't Change 'DNA': How Long Can SanDisk Stay Strong?

**AI Cannot Alter the "DNA": How Much Longer Can Western Digital's Run Last?** This analysis examines the sustainability of the current "super cycle" for NAND flash memory, driven by AI, with a focus on Western Digital (WD). The core argument is that while AI demand has fundamentally shifted NAND's role from a data warehouse to an essential component on the compute path, especially for AI inference, this does not eliminate the industry's cyclical nature. The piece first assesses the supply-demand dynamics. On the supply side, major producers are showing capital expenditure restraint for NAND, prioritizing DRAM/HBM. Capacity growth through 2028 relies heavily on technological upgrades (increasing 3D layers to 300+) and expansion primarily from China's YMTC, rather than new fabs. Global new fab capacity from players like Samsung and WD/Kioxia is concentrated post-2029. This results in estimated bit supply growth (CAGR ~24% for 2026-2028) largely driven by higher per-wafer output. Demand is undergoing a structural shift. AI-related NAND demand (for data lakes, KV cache, and staging) is forecast to grow at a 75% CAGR from 2025-2028, becoming the dominant driver. Data center demand will surpass 50% of total NAND demand in 2026. Consumer demand (PC, smartphone) is being squeezed and is expected to decline or stagnate. A key 2027 demand catalyst is NVIDIA's Rubin platform with its dedicated contextual memory storage (ICMS). The analysis concludes that a supply-demand deficit will persist into 2027. However, 2028 is identified as a potential inflection point where supply (led by YMTC's new fab) could outpace demand, ending the price rally. For Western Digital, the analysis models a more conservative path than management's guidance. It forecasts Average Selling Price (ASP) peaking in FY28 (ending June 2028) before declining in FY29-30 as the market loosens, though supported by long-term agreements (LTAs) and a higher mix of data center products. Consequently, margins and profits are expected to peak in FY28 and then contract. The valuation suggests WD's current price largely reflects a neutral scenario, with limited short-term upside unless the market becomes convinced that prices will remain stable post-2028. The fundamental takeaway is that despite AI's transformative impact, NAND's cyclical "DNA" remains intact.

marsbitHace 2 hora(s)

AI Can't Change 'DNA': How Long Can SanDisk Stay Strong?

marsbitHace 2 hora(s)

Trading

Spot
活动图片




