Smarter Web to Become the First UK Bitcoin-Operating Company to Issue Preferred Shares

cryptonews.ruPublished on 2026-09-12Last updated on 2026-09-12

Abstract

Smarter Web, the UK's largest corporate holder of Bitcoin, plans to launch a new class of non-voting, preferred shares called "MORE" on the London Stock Exchange. This marks the first such offering from a UK corporate Bitcoin holder. The shares aim to raise £15-25 million, offering holders cumulative weekly variable dividends, liquidation preference, and a company call option. Unlike common stock, these shares are a fixed-income instrument providing Bitcoin exposure. The company intends to fund dividends from operational cash flow, cash reserves, its Bitcoin treasury, and future share sales. Following the announcement, Smarter Web's stock rose over 15%. Smarter Web, holding 2,747 BTC, recently redeemed a convertible note early to avoid equity dilution. It now seeks long-term capital for acquisitions, working capital, and expanding its Bitcoin holdings. The plan requires FCA prospectus approval, a minimum £10 million raise, and shareholder vote on September 28. This move comes as some UK competitors retreat from Bitcoin, with sector companies having lost significant market value since a 2025 peak. Smarter Web is attempting to expand its funding options amidst this challenging environment.

The UK's largest corporate Bitcoin holder, The Smarter Web Company (LON: SWC), announced on Friday its plans to launch a new class of preferred shares on the London Stock Exchange, the first of its kind issued by a UK corporate company owning Bitcoin.

The preferred shares, named 'MORE,' will be listed on the exchange with a nominal value of £0.001 each. The company aims to raise between £15 and £25 million in gross proceeds, offering what the Bristol-based firm described as 'accumulative weekly variable-rate dividends,' along with preferential rights upon liquidation and a company buyback option.

The plan appears to have been well-received by investors, as the company's SWC shares rose more than 15% on the day.

What do Smarter Web's MORE Preferred Shares offer?

The MORE preferred shares do not grant holders voting rights at general meetings. They are simply a fixed-income instrument allowing holders to gain exposure to Bitcoin without purchasing the coin itself or the company's ordinary shares.

In July, Swedish company Bitcoin Treasury Capital listed the first Bitcoin-backed preferred shares in Europe, offering monthly fixed annual dividend payments of 10%.

Smarter Web's version will be included in the UK FCA's listing under the non-voting shares category.
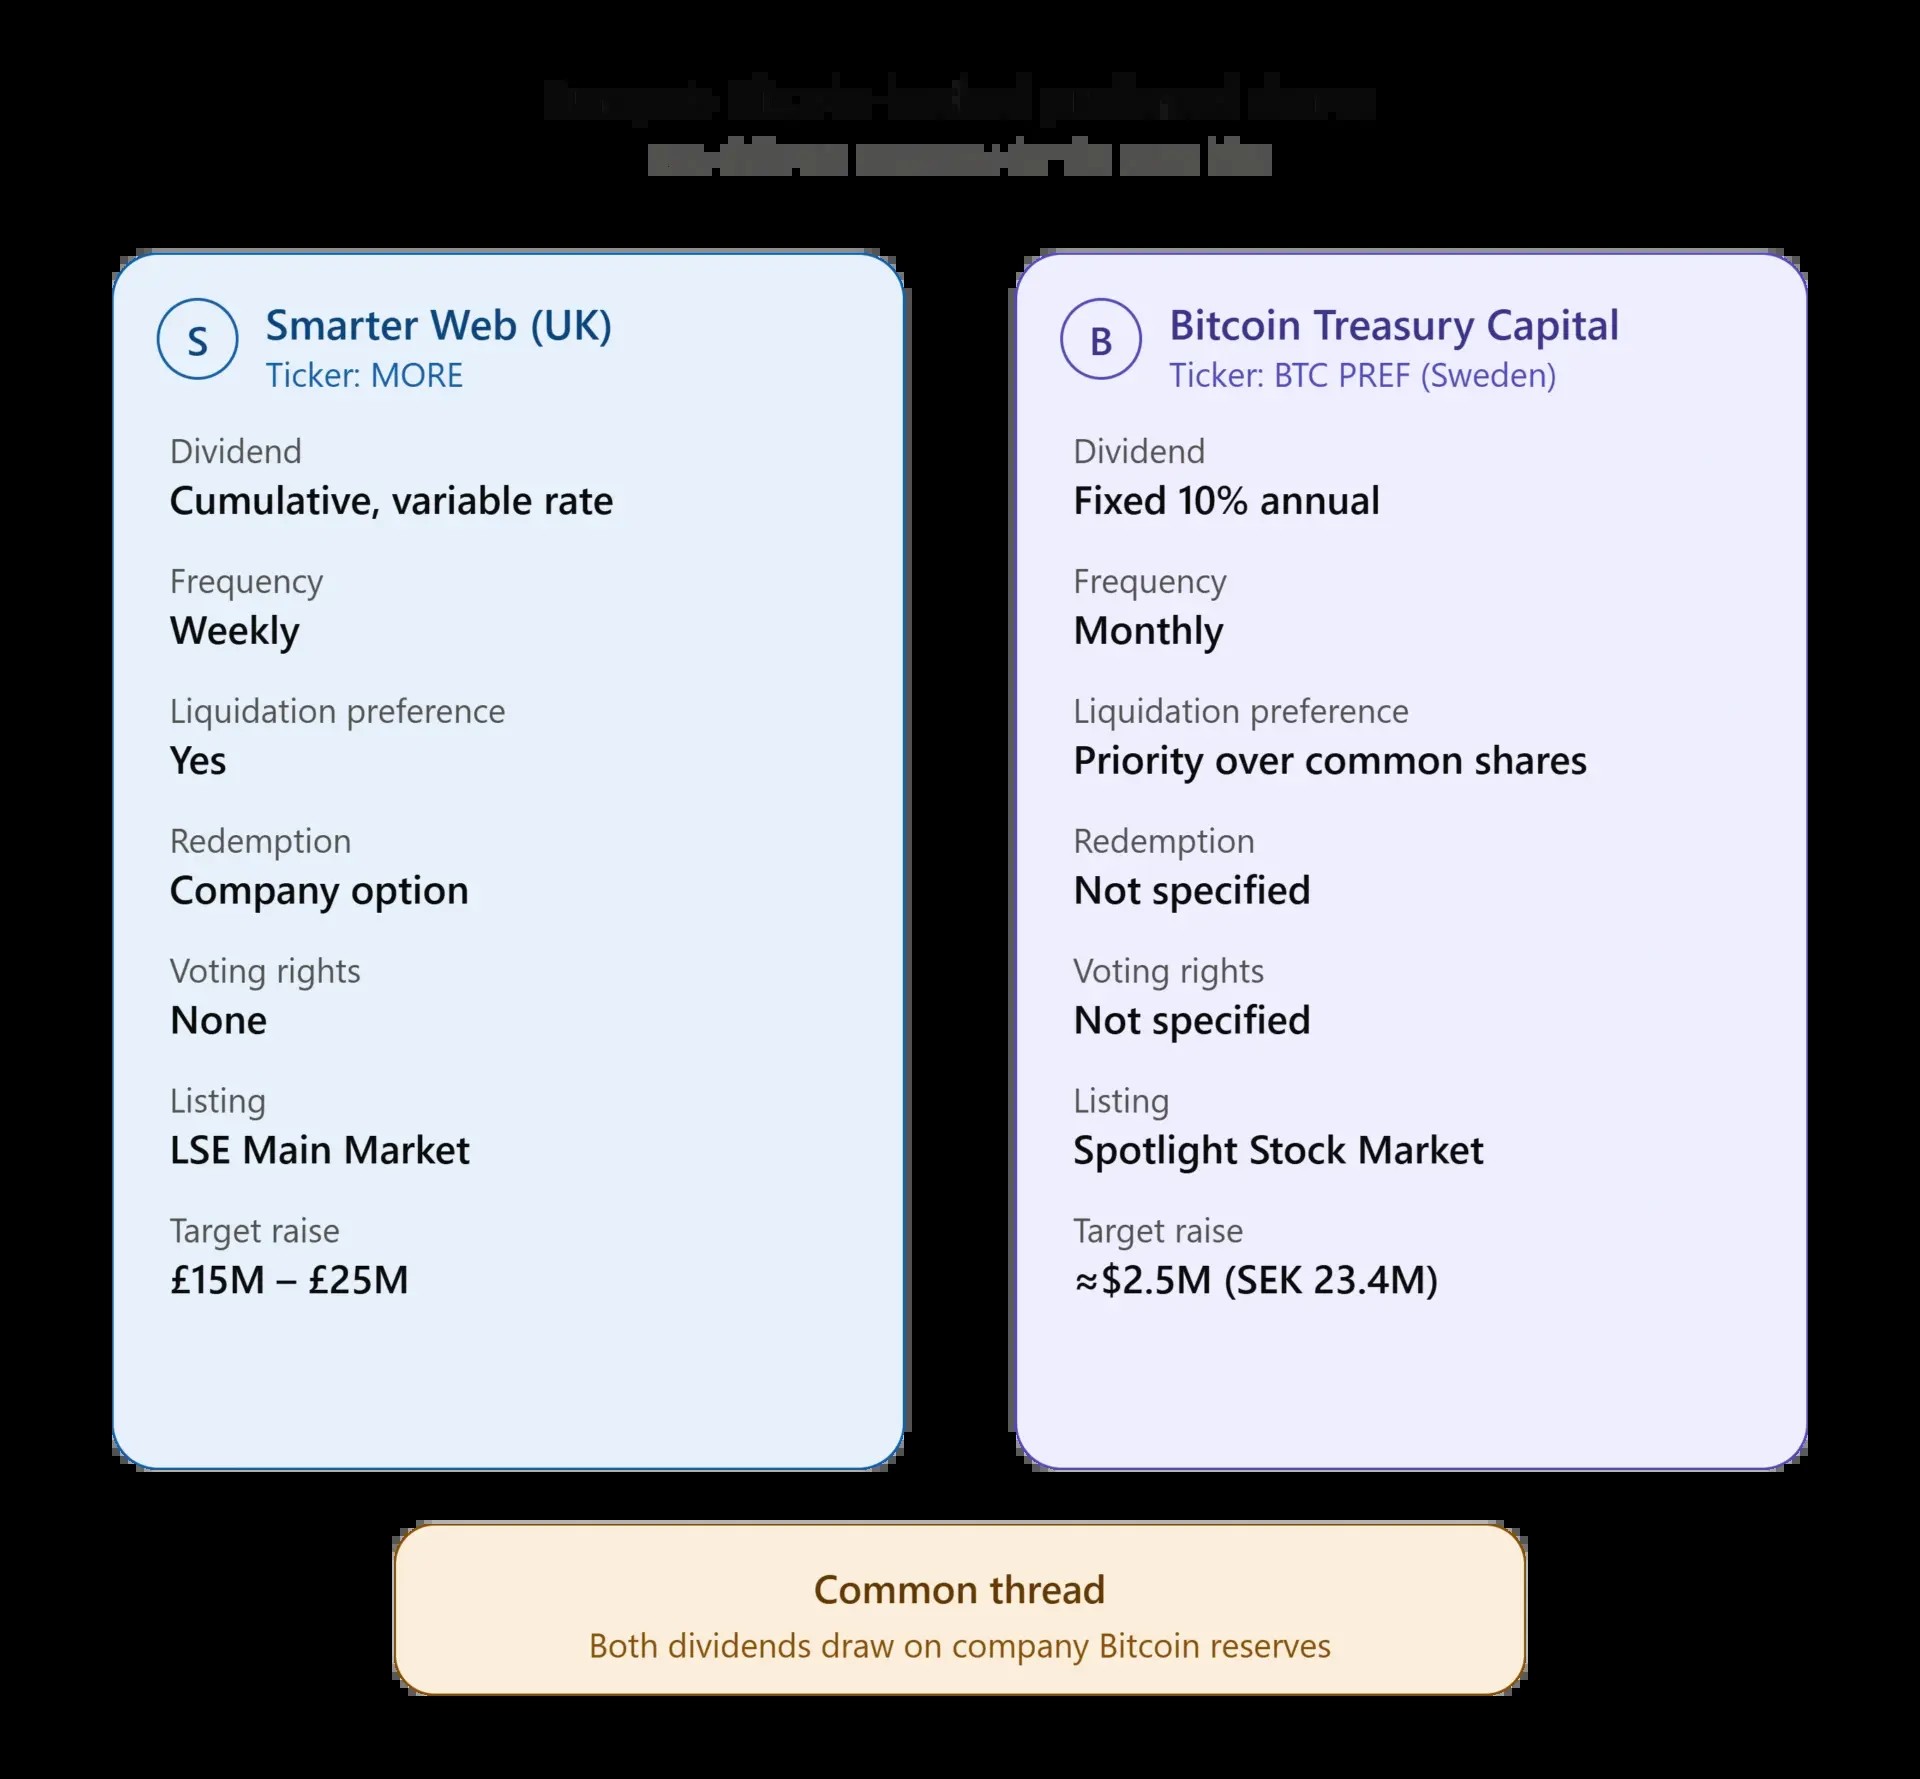
Comparison of Smarter Web's and Bitcoin Treasury Capital's preferred shares.

Smarter Web's management outlined four methods for funding the dividend payments:

  • Operating cash flow
  • Cash reserves
  • Bitcoin treasury
  • Future sales of ordinary or preferred shares

The company also expects to sell more preferred shares over time through a market placement mechanism managed by Tennyson Capital Partners.

How is Smarter Web currently managing its Bitcoin reserve?

When Smarter Web sold 177.89 $BTC to settle an $11.7 million convertible instrument provided by the TOBAM group, CEO Andrew Webley stated that the company was reconsidering its position on whether fiat and Bitcoin-denominated convertible bonds were 'the right solution for raising capital.' Notably, Webley left open the possibility of benefitting from them.

However, the early debt repayment two weeks ahead of schedule prevented the potential issuance of over 7.7 million ordinary shares.

Smarter Web is now moving forward with a long-term capital source that management plans to use for financing acquisitions of income-generating web businesses, replenishing working capital, and further growing the Bitcoin treasury.

According to Cryptopolitan, as of early September, Smarter Web owned 2,747 $BTC, ranking 29th among public corporate holders, following the addition of 35 coins in a recent update.

The FCA must still approve the prospectus before Smarter Web can list the MORE shares on the exchange. The completion of the deal also depends on the company raising at least £10 million, securing at least three registered market makers, and having at least half of the preferred shares in free float.

Shareholders will vote on this plan at a general meeting on September 28th in Bristol.

Why timing is a double-edged sword

The fundraising comes amid a reshuffle in the corporate treasury sector. Some UK competitors are retreating: according to Cryptopolitan, in July, over 90% of Satsuma Technology's shareholders voted to sell their 668 $BTC and delist, returning far less than the £163.6 million invested.

The Financial Times reported that Bitcoin-managing companies have lost over $80 billion in market value compared to their 2025 peak.

Against this backdrop, Smarter Web is attempting to expand, not contract, its financing capabilities. The MORE listing will test whether all conditions are met and how investors value weekly variable dividends backed by a volatile asset.

end-content
Related Questions

QWhat is the significance of Smarter Web's planned MORE preferred shares issuance?

ASmarter Web's planned issuance of MORE preferred shares is significant as it would be the first such issuance by a UK corporate Bitcoin holder on the London Stock Exchange. It offers a new investment vehicle providing exposure to Bitcoin without direct purchase of the cryptocurrency, featuring variable weekly dividends.

QWhat are the key differences between Smarter Web's MORE shares and the Swedish Bitcoin Treasury Capital's preferred shares?

ASmarter Web's MORE shares offer variable weekly dividends and are to be listed in the UK's non-voting FCA category, while Swedish Bitcoin Treasury Capital's shares offered fixed monthly dividends at a 10% annual rate and were the first Bitcoin-backed preferred shares in Europe.

QWhat will be the sources of funding for the dividends on the MORE preferred shares?

AThe dividends for the MORE preferred shares will be funded from four sources: operational cash flow, cash reserves, the Bitcoin treasury, and future sales of ordinary or preferred shares.

QWhat are the conditions that must be met before Smarter Web can list the MORE shares?

ABefore listing, the FCA must approve the prospectus. The deal completion also depends on the company raising a minimum of £10 million, attracting at least three registered market makers, and having at least half of the preferred shares in free float.

QWhat is the current status of Smarter Web's Bitcoin holdings?

AAs of early September, Smarter Web held 2,747 Bitcoins, ranking 29th among public corporate holders. This follows a recent addition of 35 coins. The company earlier sold 177.89 BTC to settle a convertible instrument.

Related Reads

Changing Gas Metering Could Break Smart Contracts? Ethereum Urgently Halts Hoodi Fork to Investigate Eight Major Security Risks

Ethereum core developers have paused the Hoodi testnet upgrade after security auditors found that two upcoming Gas improvement proposals could invalidate long-standing assumptions underpinning many deployed smart contracts. The proposals, EIP-8037 and EIP-8038, part of the Glamsterdam upgrade, aim to reprice state storage by decoupling state creation from state access and setting dynamic weights for certain opcodes, in order to curb unchecked growth of Ethereum's state data. However, this overhaul disrupts static Gas constants that developers have relied on as fixed system parameters. ChainSecurity identified eight invariant risks. Many contracts and off-chain infrastructure depend on hardcoded Gas limits, for example to prevent reentrancy or bound execution scope; higher costs could cause cross-contract calls to run out of Gas and revert. Other risks lie in error-handling logic that relies on precise prediction of inner execution costs, and in proxy contracts that forward Gas based on fixed ratios, potentially distorting execution paths or locking funds in incomplete state-machine branches. To avoid systemic compatibility failures and cascading disruptions across multisig wallets, bridges, and lending protocols, developers agreed at an ACD meeting not to hard-fork Hoodi until the affected contracts are fully mapped and compatibility guidance is issued. Because much logic lives off-chain in proprietary routing, settlement scripts, and liquidation bots, the Ethereum Foundation acknowledged it cannot audit the entire ecosystem alone. It has published a public repository detailing the eight affected invariants, sample problem code, and prompt templates for audit and scanning tools, so teams can check their own logic. Findings will be reviewed at next week's ACD meeting, when Hoodi activation conditions will be reassessed.

marsbit1h ago

Changing Gas Metering Could Break Smart Contracts? Ethereum Urgently Halts Hoodi Fork to Investigate Eight Major Security Risks

marsbit1h ago

What Exactly Drives the Value of Layer 1?

This analysis by Marc Arjoon, CFA, examines what actually drives Layer 1 valuation through time-series regression on major L1 assets. Short-term, all L1 price movements remain dominated by Bitcoin beta. Over longer horizons, Ethereum's market cap has fully decoupled from its own protocol revenue—a deliberate policy outcome of Dencun and higher gas limits rather than a demand collapse—with its 2025 rally driven instead by spot ETF and corporate treasury demand. Solana, by contrast, shows revenue and market cap moving in tandem, both rising ~15x since January 2023 and peaking the same week. Active addresses and DEX volumes show weak weekly correlations and large divergences despite long-cycle drift. Testing Metcalfe's Law, the fitted elasticity of market cap to active addresses is only 0.56 for Ethereum and 0.62 for Solana and BNB—closer to the square root of addresses than the square. None of six valuation multiples reliably mean-reverts; Mcap/REV is the only one that predicts positive 13-week returns from low valuation quantiles on Ethereum and TRON. No L1 has Bitcoin's deep holder base: only 4% of Solana and 10% of Ethereum supply has been dormant over three years versus 42% for Bitcoin. Ethereum's pricing anchors to peer capital share—59% of L1 market cap, 70% of DeFi TVL, 75% of tokenized RWA—rather than on-chain activity, where it holds just 5% of active addresses. Across chains, market cap rank correlates strongly with TVL (Spearman 0.87) and stablecoin supply (0.63) but weakly with transactions (0.17). The core conclusion: L1s are valued less as fee-generating businesses and more as monetary assets competing for capital settlement and liquidity share.

marsbit1h ago

What Exactly Drives the Value of Layer 1?

marsbit1h ago

From 85% to 9%: The Dramatic Shift in Korean Exchange Listing Logic—Tokens Are Safer, but Is the Business Harder?

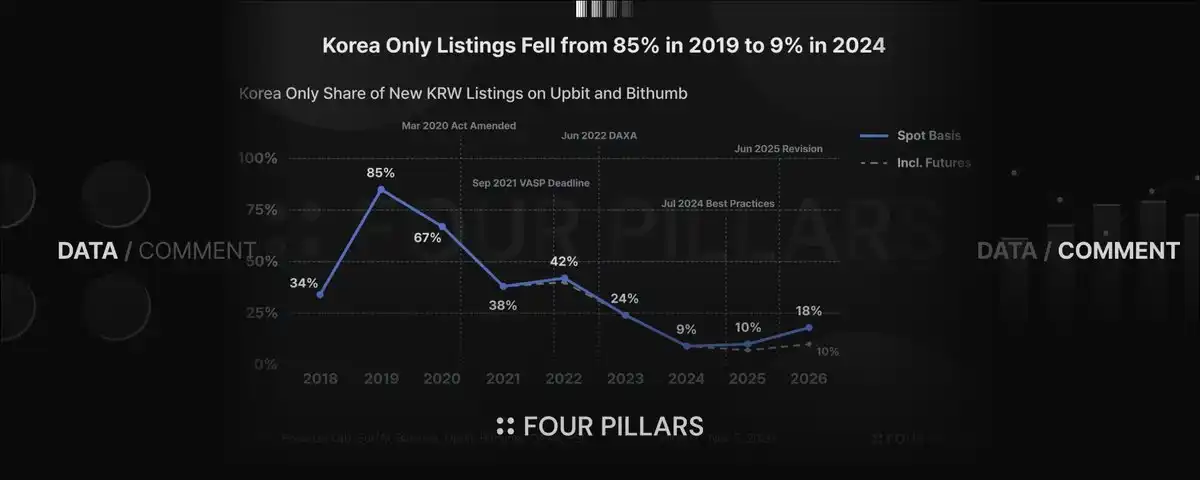
South Korea’s KRW crypto exchanges have fundamentally changed their listing logic. According to Bonanza Lab data across Upbit, Bithumb, Coinone, Korbit, and Gopax, the share of Korea-only token listings fell from 85% in 2019 to 9% in 2024, with a slight rebound to 18% in 2026 that drops back to about 10% when excluding assets first traded on overseas futures markets. The shift began with the 2021 Specific Financial Information Act, which required real-name bank accounts and traditional-finance-level AML compliance, and was reinforced by DAXA’s unified listing review guidelines effective July 2024, under which assets with two or more years of trading history on compliant overseas exchanges can automatically satisfy baseline disclosure and whitepaper requirements. Despite the collapse in local-first listings, total listings have grown: Upbit and Bithumb added 43 KRW-market tokens in 2022, 116 in 2023, 125 in 2024, and 238 in 2025. Listing timing remains cyclical—in the 2025 bitcoin high, 111 assets (47%) were brought to Korea within 30 days of overseas listing, while in 2026 mature assets with over a year of overseas trading became the mainstay (52 assets, 31%), including older tokens such as CRV and RSR. The consequences are clear. The share of assets hit by investment warnings or delisting within two years fell from 24% for the 2020 cohort to 10% for 2024. Among 2020–2024 listings, 44 of 148 Korea-only tokens (30%) faced warnings or delisting within two years, versus only 26 of 279 overseas-first tokens (9%). Overseas seasoning also reduces post-listing drawdowns: assets listed in Korea within 30 days of overseas launch saw a median 30-day price decline of 39%, compared with just 7% for assets with over a year of overseas trading history. The trade-off is revenue. Heavily traded overseas assets generate limited first-day speculative volume, and since Korean exchanges rely overwhelmingly on spot trading fees, weaker listing-day surges can hurt earnings. A renewed bull market could temporarily revive listings of newly launched overseas assets, but exchanges cannot build a durable, cycle-resistant business on listing structure alone. Their core challenge is to create new trading demand and diversify revenue beyond listing-driven fees.

marsbit1h ago

From 85% to 9%: The Dramatic Shift in Korean Exchange Listing Logic—Tokens Are Safer, but Is the Business Harder?

marsbit1h ago

Didn't We Agree on Decoupling? BTC Fell Along With US Stocks Again

Bitcoin's "decoupling" from tech stocks proved short-lived. On Nov 4, the Dow rose 3% and BTC rebounded to $81K; just 24 hours later, a massive AI-driven selloff sent Nasdaq down 5.5% and BTC back to $75.2K. The trigger had nothing to do with crypto: after Democrats won Congress, markets feared slower data-center buildout, and chip stocks cratered (Nvidia -9.26%, AMD -17.26%, semiconductor ETF -12%, worst since March 2020). All 11 S&P sectors fell. BTC followed: it dropped about 5.5% to $76K, with over $1B liquidated in 24 hours—nearly 90% longs, about 210,000 traders forced out. The transmission path was simple: tech panic → institutions sell BTC ETFs → ETF outflows trigger on-chain leverage liquidations → accelerated decline. From Oct 30 to Nov 5, BTC ETFs saw roughly $1.5B in net outflows. The decoupling narrative keeps flipping. In February, Grayscale's Zach Pandl said BTC was highly correlated with high-growth tech software stocks. By August, the same analyst said BTC's correlation with gold had risen above 50% while its correlation with Nasdaq 100 fell from over 60% to about 33%—prompting talk that BTC was finally shifting toward gold. Two months later, K33 Research found BTC-Nasdaq synchronicity rising again. On Nov 5, Nasdaq fell ~6.5%, BTC ~5.5%, while gold rose 0.9%—BTC tracked Nasdaq, not gold. This isn't new. In early 2022, Kaiko found BTC-Nasdaq correlation at its highest since July 2020, while BTC-gold correlation was negative—the first data-driven blow to the "digital gold" thesis. In April 2025's tariff shock, BTC briefly decoupled, rising 13% while Nasdaq was flat, but correlation soon returned. Nov 5 mirrored April 2025: two shocks of similar magnitude; BTC withstood the first but not the second. Different institutions use different windows—Grayscale looks at 90 days, K33 at two-week returns—so conclusions change with the window. Correlation isn't a fixed conclusion; it keeps flipping. Notably, BTC and gold are both among 2025's worst performers. Charlie Bilello's Oct 23 ranking of 21 assets showed BTC down 7.3% and gold down 7.5%—the two worst—while short-term Treasuries rose 2.9% and commodities 52.5%. By Nov 5, BTC's year-to-date loss widened to about 13%. Bilello noted that since 2011, no year had seen BTC and gold both at the bottom. Gold itself fell about 27% from its January high near $5,600 to about $4,095, hit by war-driven inflation, higher yields, a stronger dollar, and leveraged selling. Yet in March, during the Iran war, BTC didn't follow stocks down—Grayscale's April report was titled "Resilience in War," noting equities, bonds, and precious metals all fell while crypto rose slightly, aided by Strategy's purchase of ~44,400 BTC. Same year: BTC held up in March but fell with tech in November. "Digital gold" is less a fixed property than a switching state. Pandl framed it honestly in February: "Is BTC a store-of-value asset like gold, or a growth asset like tech stocks? Short answer: we think it's both." The risk-asset side is visible—post-ETF institutional inflows make BTC trade like a high-beta tech stock. The store-of-value side needs a longer view: since 2011, BTC's average annual return is 120.6% versus gold's 6.3%. Even JPMorgan now includes BTC in long-term capital market assumptions, projecting 10% annualized returns over the next decade (above US large caps' 7.5%), though it flags 55% volatility and unstable correlations and excludes BTC from main portfolio models. Pandl added: "If BTC succeeds as a monetary asset long term, its price behavior may eventually look more like gold." Note the "if"—BTC is only 17 years old. Three indicators to watch: whether BTC-Nasdaq 100 90-day correlation stays above 0.5; whether spot ETFs see net outflows for more than a week; and whether BTC follows or decouples from tech in the next big move. At 17, BTC hasn't yet grown into itself.

marsbit1h ago

Didn't We Agree on Decoupling? BTC Fell Along With US Stocks Again

marsbit1h ago

After the US Midterm Elections, South Koreans Are in Complete Panic

After the U.S. midterm elections, a "blue wave" swept Congress and key AI-data-center states, triggering a global selloff in AI and semiconductor stocks. While most markets absorbed the shock without emergency action, South Korea reacted with alarming urgency: the deputy prime minister and finance chief convened an emergency market meeting, the financial services commissioner and a Bank of Korea deputy governor attended, and authorities announced a three-month exemption from the 140% credit-financing collateral requirement for brokerages, while the exchange triggered a Sidecar circuit breaker to halt programmatic selling. The panic is rooted in structure. In the month before the crash, Korean retail investors—the famous "ant army"—piled into Samsung Electronics and SK Hynix, often using borrowed money and single-stock leveraged ETFs, which regulators had already been tightening since July as leverage grew dangerously large. Retail investors hold roughly 60% of these leveraged products, and earlier declines had already wiped out 41% of their assets. Beneath them, the National Pension Service, the world's third-largest sovereign wealth fund, was heavily concentrated in the same chip stocks and rode them down from June's peak, losing about $137 billion. Korea's stock market is also a amplifier of social mood and a political risk, and the won is not a safe-haven currency: risk-off outflows hit the currency, import-dependent inflation rises, and a stock-FX-inflation "triple kill" becomes lethal. Foreign investors hold nearly 38-39% of market capitalization and over 46-50% of Samsung and SK Hynix, and have been massive net sellers—about $131 billion withdrawn this year, the most in Asia. Ultimately, the U.S. election was only the match; Korea's dependence on semiconductors is the fuel. Chips are now approaching 47% of exports, and semiconductor-related production contributed about half of Q3 GDP growth. With demand tied to U.S. AI capital spending, Korea catches a heavy cold whenever America sneezes—so its response is less market rescue than firefighting.

marsbit2h ago

After the US Midterm Elections, South Koreans Are in Complete Panic

marsbit2h ago

Trading

Spot
活动图片